
 Computer Keyboard Market | 2026-2036
Computer Keyboard Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Keyboard Market Analysis
Modular keyboard kits with hot-swappable switches is recalibrating how enthusiasts and professionals configure input devices without soldering expertise. Logitech International SA leverages its wireless technology leadership to sustain premium positioning across multiple operating systems. Corsair Components Inc. anchors its reputation in mechanical switch performance for gaming segments. Razer Inc. differentiates through software-integrated ecosystems that bind hardware to cloud-based customization platforms.
A computer keyboard is an electromechanical or solid-state input device comprising key switches, a controller PCB, and a communication interface, translating physical actuation into digital signals for host processing; membrane variants use conductive pad layers while mechanical types employ individual switch housings with metal contacts, with actuation forces typically ranging from 45g to 80g depending on switch design. Wireless Bluetooth connectivity is capturing share in mobile and multi-device workflows where cable management constrains desk configurations. Gaming end users command premium pricing pools as mechanical switch quality and RGB customization drive replacement cycles faster than office or educational segments. Full-size form factors retain dominance in data-entry and accounting environments where numeric keypad integration sustains productivity metrics.
The EU RoHS directive and REACH framework restrict cadmium, lead, and specific flame retardants in keyboard plastics and solder joints, compelling manufacturers to reformulate materials or risk market exclusion across European distribution channels. The FCC in the United States mandates electromagnetic compatibility certification for wireless keyboards operating in unlicensed radio bands, adding compliance layers that favor established vendors with dedicated testing laboratories. Stakeholders must monitor evolving right-to-repair legislation in multiple jurisdictions, as regulatory pressure toward replaceable components could accelerate modular design standards and reshape supplier relationships across the switch and controller ecosystem.
Market Dynamics
Modular hot-swappable switch architectures are restructuring procurement patterns across enthusiast and professional segments, decoupling keyboard longevity from fixed soldering configurations and enabling component-level replacement cycles.
Growth Catalysts
- EU RoHS Directive:Hazardous substance restrictions in electronics are accelerating lead-free solder adoption and reformulated plastic compounds across manufacturing bases, creating compliant-first supplier advantages in European distribution channels.
- Esports Broadcasting Infrastructure:Streaming professionals and competitive gaming venues are driving premium peripheral refresh rates, with RGB-integrated mechanical keyboards becoming standard equipment for audience-visible setups.
- Shenzhen-Dongguan Component Clustering:Dense ecosystems of switch manufacturers, PCB fabricators, and controller chip suppliers in China's Pearl River Delta are compressing prototyping timelines and enabling rapid SKU expansion for both domestic brands and export channels.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in Hall-effect magnetic switch production are compressing margins for high-end gaming keyboard manufacturers dependent on precise actuation sensing.
- FCC Certification Burden:Electromagnetic compatibility testing for wireless keyboards operating in unlicensed 2.4 GHz and Bluetooth bands imposes fixed compliance costs that disproportionately burden smaller vendors without captive testing laboratories.
- Membrane Switch Substitution:Silicone dome and scissor-mechanism alternatives in enterprise bulk procurement are capping mechanical keyboard penetration in cost-sensitive office deployments where typing feel is deprioritized.
Strategic Opportunities
- Right-to-Repair Legislative Momentum:Proposed repairability mandates in multiple jurisdictions are creating regulatory tailwinds for modular designs with standardized screw patterns, replaceable cables, and documented disassembly procedures.
- India PLI Scheme for Electronics:Production-linked incentive frameworks for IT hardware manufacturing are attracting component suppliers and assembly operations to establish India-based capacity for domestic and export markets.
- Low-Profile Optical Switch Convergence:Hybrid mechanical-optical actuation mechanisms are opening white space in mobile workstation and travel-keyboard segments where traditional switch heights constrain portability.
Industry Challenges
- Firmware Security Certification:Wireless keyboard vendors face escalating complexity in obtaining Bluetooth SIG qualification and USB-IF certification while simultaneously hardening against keylogging injection attacks.
- Legacy PS/2 Interface Support:Enterprise and industrial buyers with aging embedded systems continue demanding PS/2 compatibility, forcing manufacturers to maintain obsolete controller firmware branches alongside modern USB-C and wireless stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Keyboard Market |
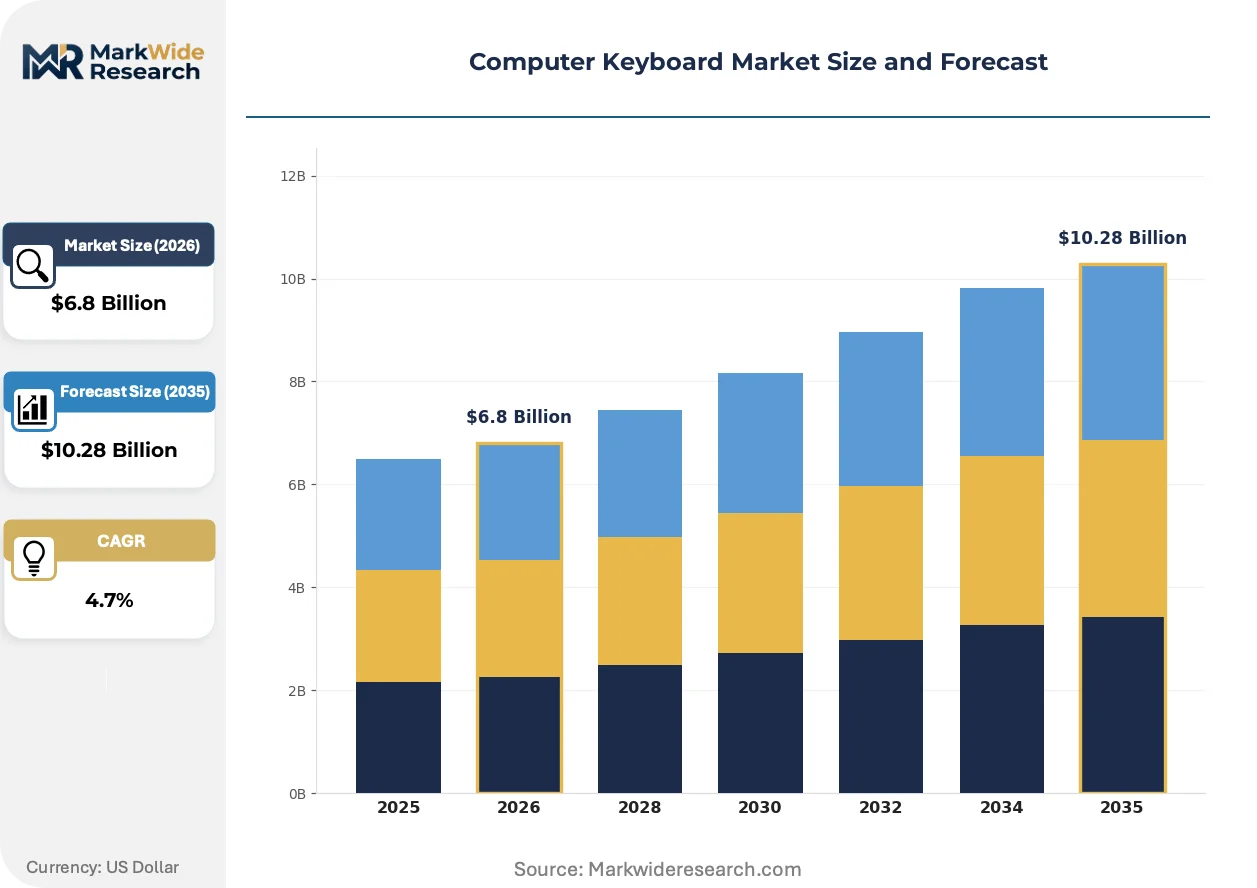
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Membrane, Wireless, Ergonomic End User: Gaming, Office, Educational, Industrial Technology: Bluetooth, USB, Optical, Scissor-switch Form Factor: Full-size, Tenkeyless, Compact, Split |
| Companies Covered | HP Inc., Lenovo Group Ltd., Logitech International SA, Corsair Components Inc., ASUSTeK Computer Inc., Apple Inc., Dell Technologies Inc., Razer Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Keyboard Market Emerging Trajectories
Input device architectures are fragmenting across specialized workflows, with switch technology, connectivity protocols, and form-factor configurations diverging rather than consolidating around universal standards.
Magnetic Hall-effect switch technology is converging with adjustable actuation point software, enabling per-key sensitivity calibration that mechanical contact switches cannot replicate. Competitive gamers and rapid-typing professionals are adopting these configurations at accelerating rates. This convergence is compressing replacement cycles in premium segments as adjustable actuation becomes a differentiable feature rather than a durability specification.
REACH framework restrictions on per- and polyfluoroalkyl substances are compelling keyboard manufacturers to reformulate PTFE-based lubricants and fluoropolymer coatings used in stabilizer wires and switch housings. Industrial consequences include accelerated qualification timelines for alternative dry-film lubricants and ceramic-based coating systems. Gaming and enthusiast segments are most affected, with vendors reformulating flagship product lines to maintain European market access ahead of substance sunset dates.
Direct-to-consumer configuration platforms are displacing traditional retail assortment models, with buyers selecting switch types, plate materials, and keycap profiles through online visualizers before manufacturing commitment. Specialty retailers and boutique mechanical keyboard distributors are being disrupted by vendor-owned configurator workflows with extended lead times and higher per-unit customization. This pattern is most visible in North American and Western European enthusiast communities where community-driven switch reviews and sound-test videos drive purchase decisions independent of physical retail inspection.
Computer Keyboard Market Segmentation
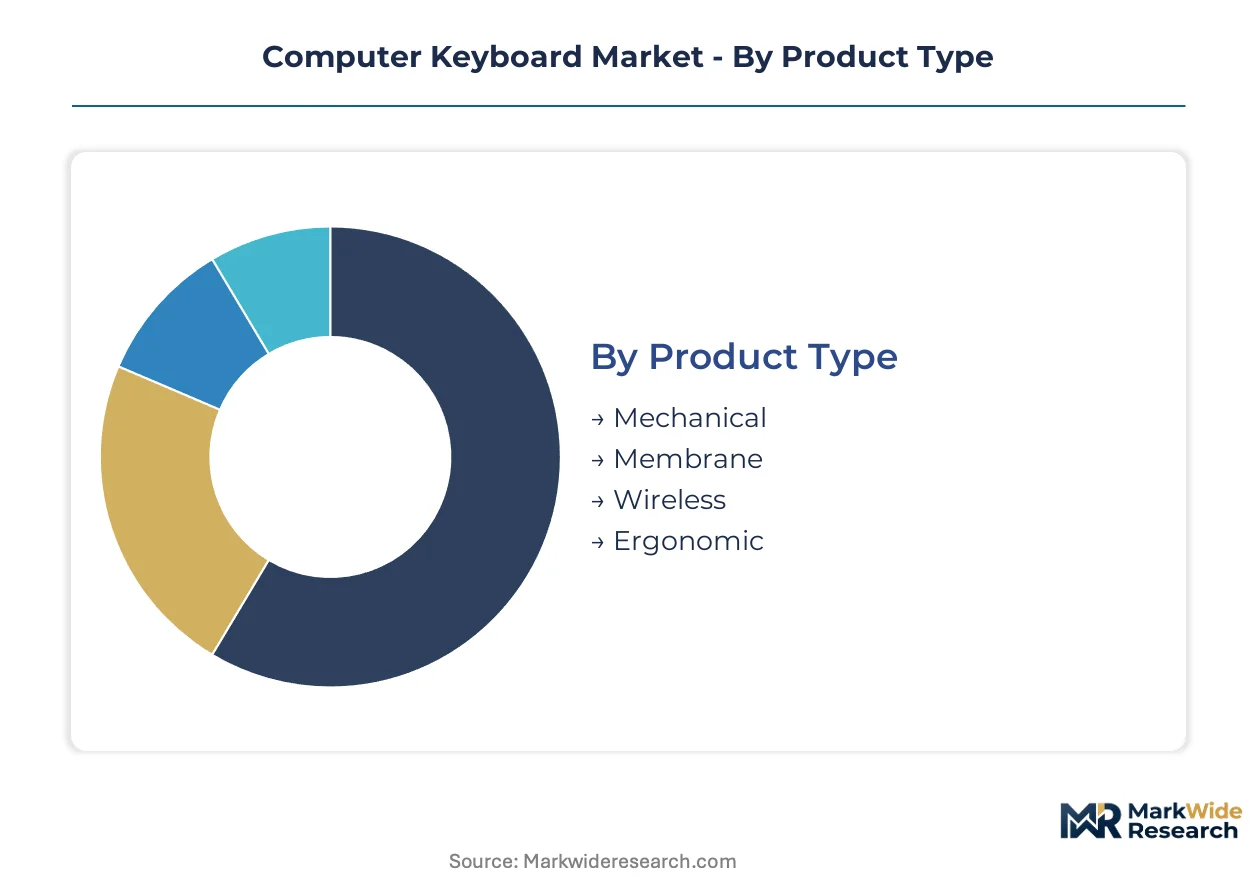
Keyboard segmentation reveals how component sourcing clusters and manufacturing capabilities align with distinct performance requirements across user workflows. Supply chain configuration varies dramatically between high-volume membrane production and precision mechanical switch assembly.
Product Type:
Switch mechanism selection concentrates manufacturing investment in distinct regional clusters, with PCB fabrication and controller programming capabilities determining competitive positioning.
- Mechanical:Individual switch housings with metal contacts deliver 45-80g actuation forces and 50-100 million keystroke durability ratings. Shenzhen and Dongguan component ecosystems serve enthusiast and gaming demand in China, Germany, and the United States where tactile feedback commands premium positioning.
- Wireless:Bluetooth and 2.4 GHz radio modules integrate rechargeable battery systems with power management controllers. Multi-device workflows in mobile professional segments across Japan, South Korea, and the United States are compressing cable-dependent form factors.
- Membrane:Conductive pad layers with silicone dome actuation enable sub-dollar manufacturing costs at massive scale.
- Ergonomic:Split-angle configurations with adjustable tenting reduce repetitive strain injury risk in enterprise procurement.
Today's leader: Mechanical. Tomorrow's challenger: Wireless.
End User:
Application-specific durability and customization requirements fragment procurement channels, with replacement cycles spanning 18 months to 7 years depending on use intensity.
- Gaming:RGB integration, N-key rollover, and sub-1ms polling rates define competitive specifications. Esports venues and streaming professionals in the United States, Germany, and South Korea refresh equipment at accelerated rates driven by audience-visible aesthetics.
- Office:Noise-dampened switches and wireless connectivity dominate enterprise bulk procurement. Cost-sensitive deployments across India and Brazil prioritize membrane alternatives where typing feel is secondary to acquisition price.
- Educational:Spill-resistant designs with reinforced keycaps withstand institutional abuse cycles.
- Industrial:IP-rated sealing and wide-temperature operation serve manufacturing floor environments.
Gaming captures margin concentration. Office retains volume dominance.
Technology:
Interface protocol selection determines certification burden and interoperability scope, with electromagnetic compliance testing favoring established vendors.
- Bluetooth:SIG qualification requirements and multi-host pairing capabilities enable seamless device switching. Mobile workstation users in the United Kingdom, France, and Australia are displacing USB-restricted configurations.
- USB:USB-IF certification and universal driver support sustain enterprise IT standardization. Wired reliability in financial trading floors and healthcare systems across Germany and Japan resists wireless migration despite cable management constraints.
- Optical:Infrared beam interruption eliminates debounce delay and extends switch longevity beyond mechanical contacts.
- Scissor-switch:Low-profile mechanisms with stabilized keycap travel dominate laptop integration and ultra-slim desktop designs.
USB anchors installed base. Bluetooth gains share fastest.
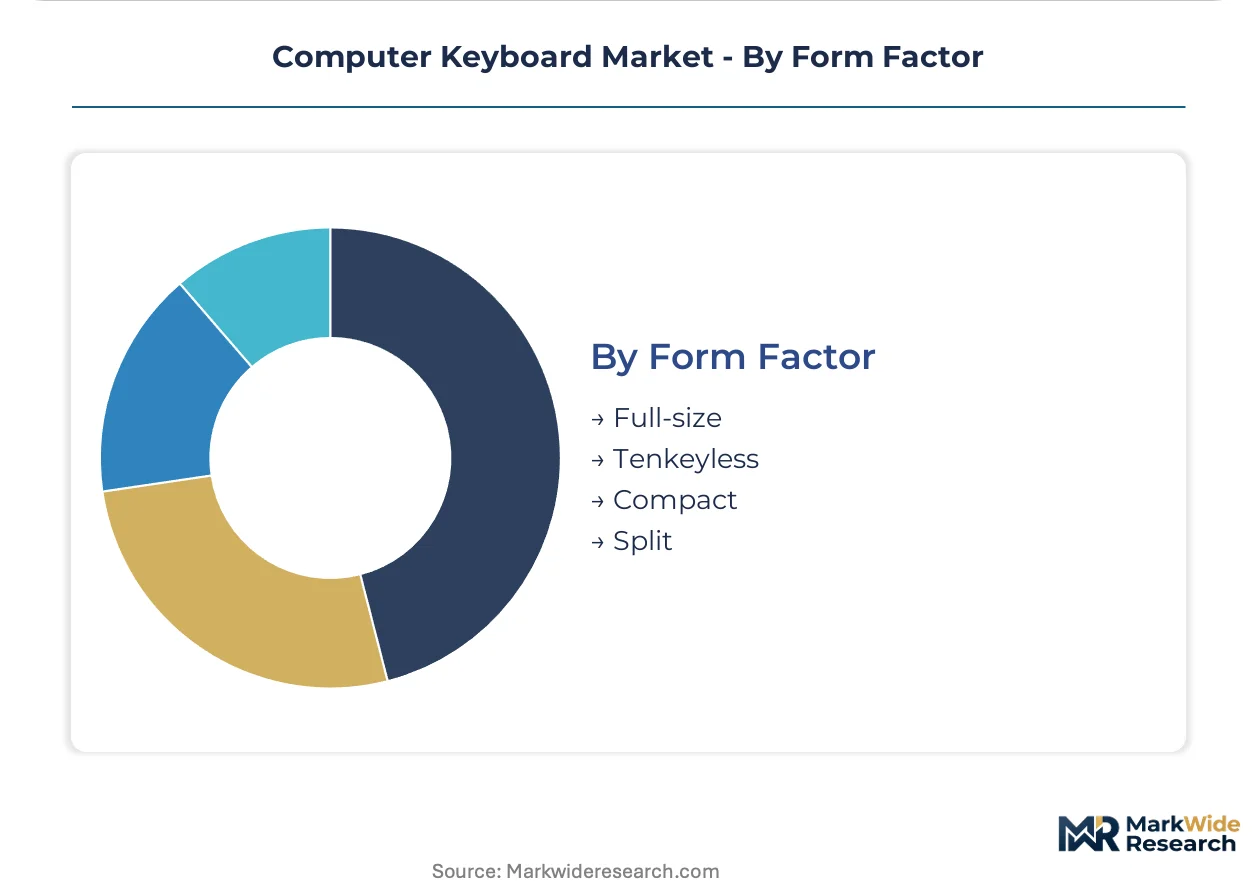
Form Factor:
Desktop footprint constraints and numeric data entry requirements create persistent segmentation between productivity-focused and space-optimized configurations.
- Full-size:104-key layouts with integrated numeric keypads sustain accounting and data entry productivity metrics. Enterprise procurement across the United States, Canada, and Germany defends this standard despite ergonomic criticism.
- Tenkeyless:87-key designs eliminate numeric clusters while preserving function rows. Gaming setups and compact workstations in the Netherlands, Sweden, and Singapore prioritize mouse movement space over spreadsheet functionality.
- Compact:60-75% layouts with layered function access minimize travel footprint.
- Split:Separated halves with adjustable splay angles address repetitive strain prevention in specialized ergonomic procurement.
Full-size defends enterprise share. Tenkeyless expands in gaming and creative segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The computer keyboard industry traces its modern scaling to IBM's 1981 Model F manufacturing in the United States, establishing the mechanical switch standards that still anchor premium segments today. Component ecosystems subsequently migrated to East Asia, creating the geographic specialization patterns that define contemporary sourcing.
United States
Enterprise IT refresh cycles and esports broadcasting infrastructure sustain robust replacement demand across corporate and gaming segments. FCC electromagnetic compatibility certification requirements for wireless keyboards operating in unlicensed 2.4 GHz bands impose compliance costs that favor established vendors with captive testing laboratories. Seattle and Austin host concentrated software-integrated peripheral development operations serving streaming professionals.
Germany
Industrial automation floors and financial trading terminals maintain demand for IP-rated sealed keyboards with PS/2 legacy compatibility. EU RoHS directive enforcement through national market surveillance authorities restricts cadmium and lead content in solder joints and plastic housings. Munich and Hamburg anchor specialized distribution channels serving Central European enterprise procurement.
China
Shenzhen and Dongguan form the densest global concentration of switch manufacturers, PCB fabricators, and controller chip suppliers, compressing prototyping timelines for both domestic brands and export channels. MIIT certification requirements for wireless devices operating in Chinese spectrum bands add regulatory layers distinct from FCC or CE frameworks. The Pearl River Delta ecosystem enables rapid SKU expansion across mechanical, membrane, and optical switch variants.
Japan
Mobile workstation users and multi-device professionals drive Bluetooth keyboard adoption in corporate environments where cable management constrains desk configurations. METI industrial standards for electromagnetic compatibility align with but remain distinct from international IEC frameworks. Tokyo and Osaka host precision component suppliers specializing in low-profile scissor-switch mechanisms for laptop integration.
South Korea
Competitive gaming venues and professional esports teams command premium peripheral refresh rates with sub-1ms polling specifications. MFDS and RRA certification requirements for wireless radio equipment create compliance pathways parallel to FCC and CE regimes. Seoul anchors domestic brand headquarters and testing facilities serving both local tournament infrastructure and export markets.
Computer Keyboard Market Vendor Landscape
Premium-margin players sit above commodity-margin players across switch quality, wireless protocol integration, and software customization depth. The vendor base organizes into three tiers: integrated technology conglomerates with captive semiconductor supply, specialized gaming peripheral houses with enthusiast community relationships, and contract manufacturers serving enterprise bulk procurement. Consolidation pressure operates through acquisition of switch technology startups and licensing agreements for proprietary wireless protocols.
Within the diversified technology tier, Logitech International SA and HP Inc. occupy positions spanning multiple operating systems and connectivity standards. Razer Inc. exemplifies the gaming-specialist archetype with software-integrated ecosystem binding. Lenovo Group Ltd. represents the enterprise-originated diversification pattern into premium consumer segments.
| Leading Market Players |
|---|
| HP Inc. |
| Lenovo Group Ltd. |
| Logitech International SA |
| Corsair Components Inc. |
| ASUSTeK Computer Inc. |
| Apple Inc. |
| Dell Technologies Inc. |
| Razer Inc. |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
Enterprise bulk procurement offices in India and Brazil anchor volume pricing for membrane keyboard tiers, compressing margins for manufacturers serving cost-sensitive office deployments where acquisition price outweighs tactile performance specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RGB-integrated mechanical gaming units from noise-dampened wireless office configurations and basic membrane alternatives. Price differentiation hinges on switch certification grade and customization depth, with Hall-effect magnetic switches commanding substantial premiums over standard mechanical contacts. Pricing pressure stems from rare earth magnet volatility in neodymium and dysprosium sourcing for high-end gaming peripherals. Enterprise procurement in India and Brazil exhibits highest price sensitivity, while esports venues in South Korea and Germany demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs are compelling keyboard manufacturers to qualify secondary PCB fabricators and switch suppliers beyond their primary Shenzhen and Dongguan partnerships. Component sourcing draws from China for switch housings and controller chips, Japan for precision scissor mechanisms, and Taiwan for semiconductor fabrication. Rare earth magnet dependency creates single-source vulnerability for Hall-effect switch production. Distribution runs through direct-to-consumer configuration platforms displacing traditional retail assortment models in North American and Western European enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as adjustable actuation point software and per-key sensitivity calibration shift enthusiast and professional demand toward premium specifications that mechanical contact switches cannot replicate.
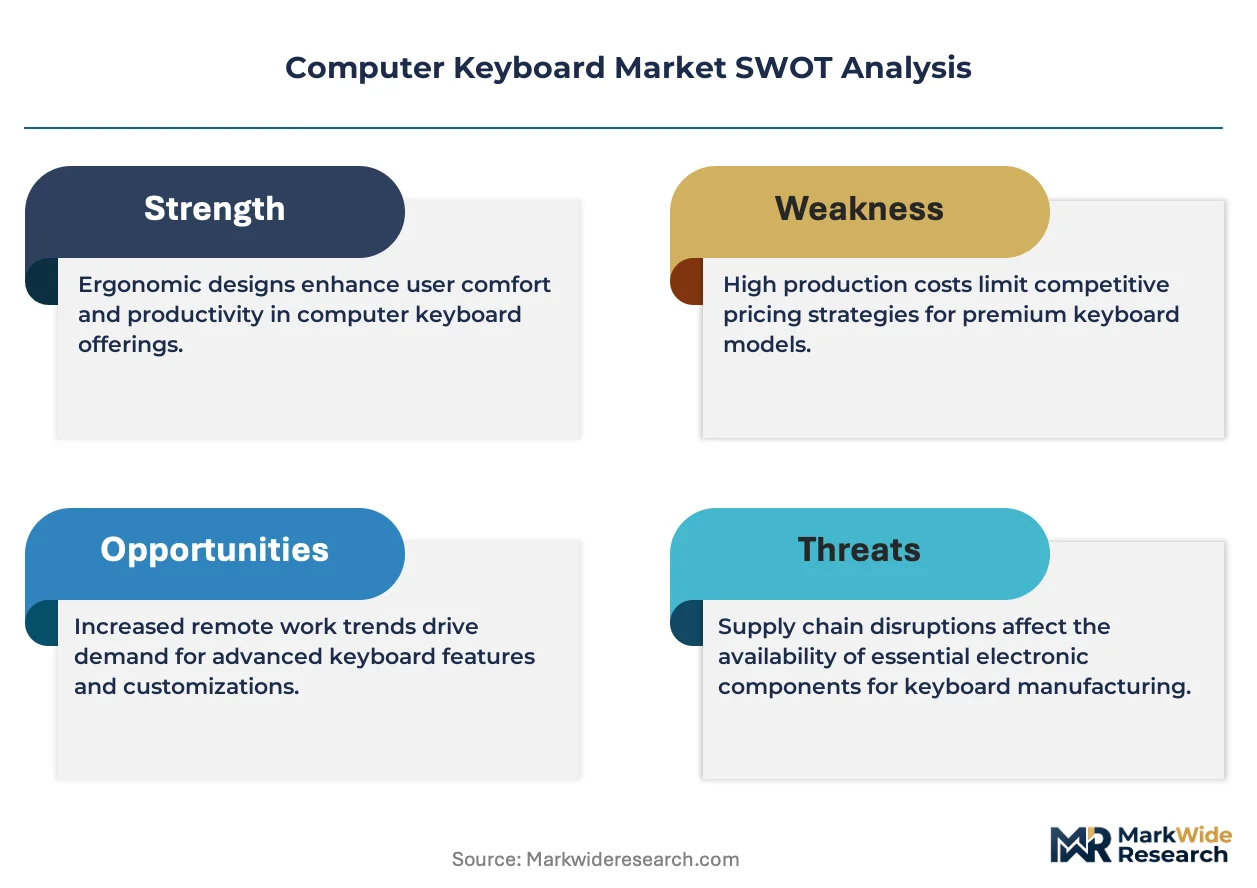
For Market Incumbents: Lock in switch technology leadership by acquiring Hall-effect magnetic sensor startups before adjustable actuation becomes table stakes, and secure captive testing laboratory capacity for FCC electromagnetic compatibility certification to exclude smaller wireless competitors. Membrane switch substitution in enterprise bulk procurement threatens volume tiers, making backward integration into controller chip supply the critical defensive lever. For New Entrants and Emerging Players: Capture white space in India's PLI scheme-attracted electronics manufacturing by establishing component assembly operations serving domestic brands and export channels, with modular hot-swappable architectures as the entry wedge. Right-to-repair legislative momentum in multiple jurisdictions creates the most penetrable regulatory tailwind for documented disassembly procedures and standardized screw patterns. For Investors and Strategic Acquirers: Gaming peripheral houses with enthusiast community relationships are the most active acquirer in this space, seeking proprietary wireless protocol licensing and software-integrated ecosystem assets. Long-term viability favors vendors with demonstrated switch durability testing infrastructure and cloud-based customization platform deployment. Watch magnetic Hall-effect switch adoption rates among competitive gamers as the inflection indicator for premium segment replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Switch Technology Startup | Secures adjustable actuation point capabilities ahead of competitive gaming standardization. |
| India Manufacturing Footprint Establishment | Captures PLI scheme incentives for IT hardware assembly serving domestic and export demand. |
| Proprietary Wireless Protocol Licensing | Creates ecosystem lock-in through software-integrated hardware customization platforms. |
| Modular Design Standard Adoption | Aligns product architectures with right-to-repair mandates across European and North American jurisdictions. |
| Direct-to-Consumer Configurator Launch | Displaces specialty retailer margins with vendor-owned customization workflows and extended lead times. |
Methodological Framework
Direct dialogue with mechanical switch manufacturers, gaming peripheral product managers, enterprise IT procurement officers, and FCC certification consultants grounded the qualitative foundation, cross-referenced with SEC filings from diversified technology conglomerates, MIIT wireless device registration databases, EU RoHS enforcement actions from national market surveillance authorities, and import-export customs records from Shenzhen and Dongguan port authorities. Bottom-up demand modeling and top-down supply capacity assessments were triangulated for convergence validation.
Bottom-up unit economics across switch mechanism types, connectivity protocols, and form-factor configurations were aggregated against top-down manufacturing capacity estimates from Pearl River Delta component clusters over the projection horizon. CAGR derivation incorporated replacement cycle compression from adjustable actuation technology adoption, enterprise procurement elasticity to membrane substitution, and regulatory timeline assumptions for REACH framework substance restrictions affecting PTFE-based lubricants.
Rare earth magnet price volatility, right-to-repair legislative passage timelines, and Bluetooth SIG qualification backlogs are the dominant revision risks to modeled outputs. Deviation in magnetic switch material costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Audio Jack Market