
 Baby Prams and Strollers Market | 2026-2036
Baby Prams and Strollers Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Prams and Strollers Market Analytics
Aluminum is pivoting toward magnesium alloys across stroller frame construction, trimming chassis weight while preserving structural integrity. Goodbaby International Holdings Ltd. leverages vertical manufacturing scale across Asian production bases. Dorel Industries Inc. anchors North American distribution through mass retail channel control. Artsana Group specializes in European premium design heritage.
Baby prams and strollers constitute wheeled infant transport devices with collapsible frames, typically spanning 50-120 cm in folded length, engineered for safe conveyance of children from birth through toddler stages. Standard prams retain dominance in newborn-focused segments where flat recline and bassinet compatibility matter most, while jogging strollers capture the fastest expansion among fitness-oriented parents seeking suspension systems and pneumatic tires. Travel system strollers concentrate margin pools through modular car seat integration that locks in repeat purchases across the infant gear ecosystem.
GB standards in China mandate frame stability testing and chemical migration limits for plastic components in direct infant contact. REACH regulation across Europe restricts phthalates and heavy metals in fabric coatings and polymer frames, compelling reformulation of legacy material recipes. The US Consumer Product Safety Commission enforces federal stroller safety standards covering restraint systems and parking brake performance. Stakeholders must monitor evolving chemical disclosure requirements and decide whether to front-load compliance investments or risk exclusion from regulated distribution channels.
Market Dynamics
Urban millennial parents are compressing purchase cycles and demanding modular platforms that adapt from newborn bassinets through toddler seating, forcing manufacturers to engineer frame architectures that accommodate multiple life stages without full product replacement.
Growth Catalysts
- REACH chemical migration limits:European phthalate restrictions in fabric coatings and polymer frames are accelerating R&D investment in bio-based alternatives, creating first-mover advantages for compliant suppliers.
- Fitness-oriented parent segments:Jogging stroller demand with suspension systems and pneumatic tires is pulling premium pricing into the mid-market through feature trickle-down.
- China's GB standards:Mandatory frame stability testing and chemical disclosure requirements are consolidating domestic manufacturing toward certified producers, improving export quality perception.
Market Restraints
- Magnesium alloy supply concentration:Primary smelting capacity clusters in Shaanxi and Shanxi provinces, exposing stroller manufacturers to regional energy policy disruptions and input price volatility.
- Technical limitation in ultralight frames:Sub-6kg chassis designs sacrifice torsional rigidity, creating liability exposure under US Consumer Product Safety Commission brake-performance standards.
- Substitution threat from baby carriers:Soft-structured carriers and wraps capture urban transit-dependent parents seeking hands-free mobility without bulk.
Strategic Opportunities
- German premium channel expansion:Specialty retailers in Munich and Hamburg command 40-60% gross margins on modular travel systems, rewarding brands with European design heritage.
- Car seat convergence:Click-in infant carrier compatibility is creating platform lock-in effects that extend customer lifetime value across the infant gear ecosystem.
- US Consumer Product Safety Commission recall transparency:Mandatory incident reporting databases are enabling proactive brands to differentiate on safety track records.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction testing for GB, REACH, and US federal standards extends product development cycles by 8-14 months.
- Supply chain reconfiguration friction:Nearshoring experiments to Mexico and Poland face skilled welding technician shortages and tooling transfer costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Prams and Strollers Market |
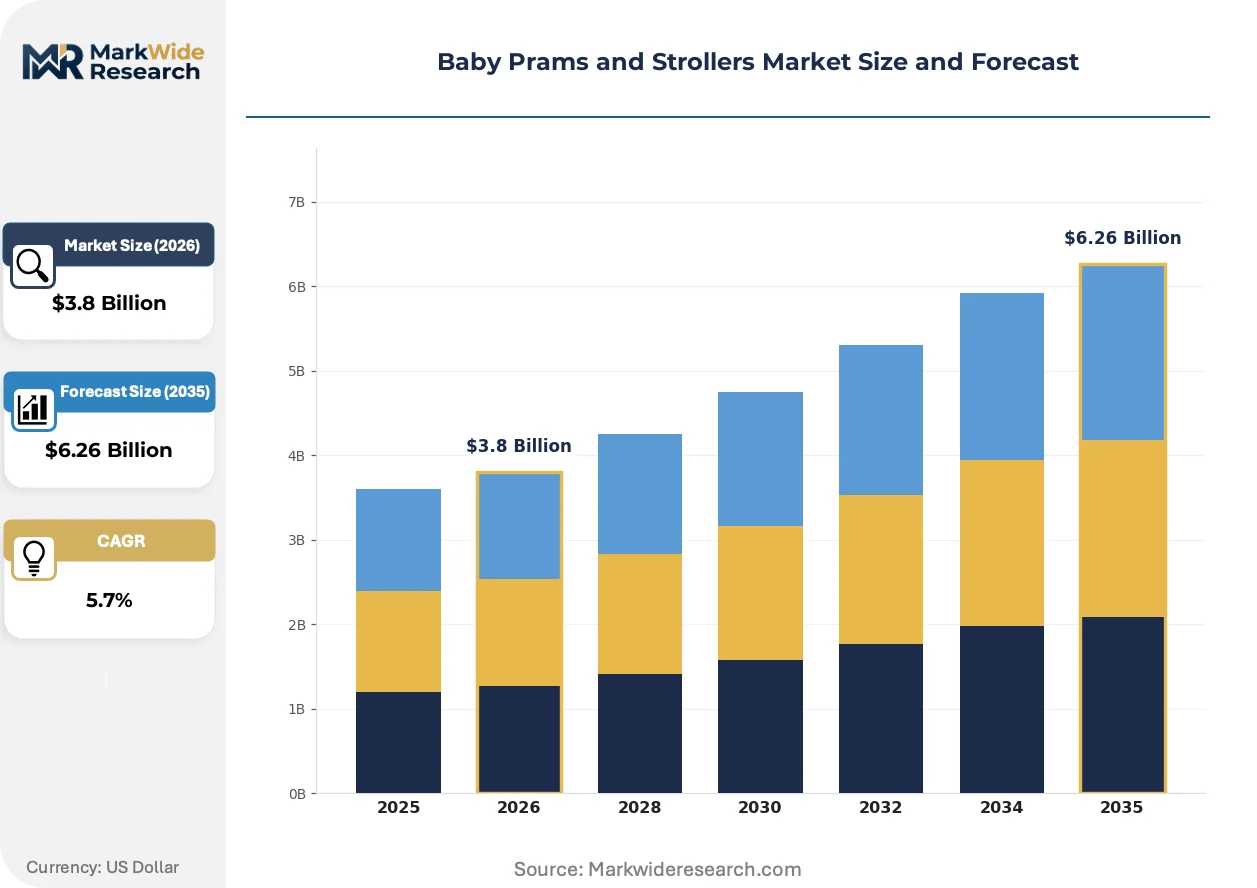
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Prams, Umbrella Strollers, Jogging Strollers, Travel System Strollers Material: Metal, Plastic, Fabric, Wood End User: Parents, Caregivers, Daycare Centers, Retailers Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Britax Child Safety, Inc., Dorel Industries Inc., Artsana Group, Newell Brands Inc., Goodbaby International Holdings Ltd., Bugaboo International, Peg Perego, Nuna International BV, UPPAbaby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Prams and Strollers Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are converging to redefine how stroller manufacturers compete on safety transparency and weight-performance ratios.
Magnesium alloy substitution for 6061-T6 aluminum is rewriting chassis engineering economics. Premium urban parents in Shanghai and San Francisco are adopting sub-5kg frames at triple the rate of conventional aluminum models. This material pivot is compressing the performance gap between luxury and mass-market tiers, forcing mid-tier brands to accelerate alloy adoption or cede urban market share.
REACH Annex XVII phthalate restrictions are tightening enforcement across EU member states. Fabric coating reformulations now require third-party migration testing before CE marking approval. Travel system manufacturers with integrated car seat platforms face the steepest compliance burdens, as multi-component products trigger cascading chemical disclosure requirements across their supplier networks.
Direct-to-consumer subscription models for stroller accessories and replacement parts are disrupting traditional retail replenishment cycles. Urban millennial parents in Brooklyn and Berlin now expect platform-extendable purchases rather than single-transaction buying. This behavioral shift is most visible in modular travel system adoption, where car seat base compatibility drives repeat purchase lock-in across the infant gear category.
Baby Prams and Strollers Market Segmentation
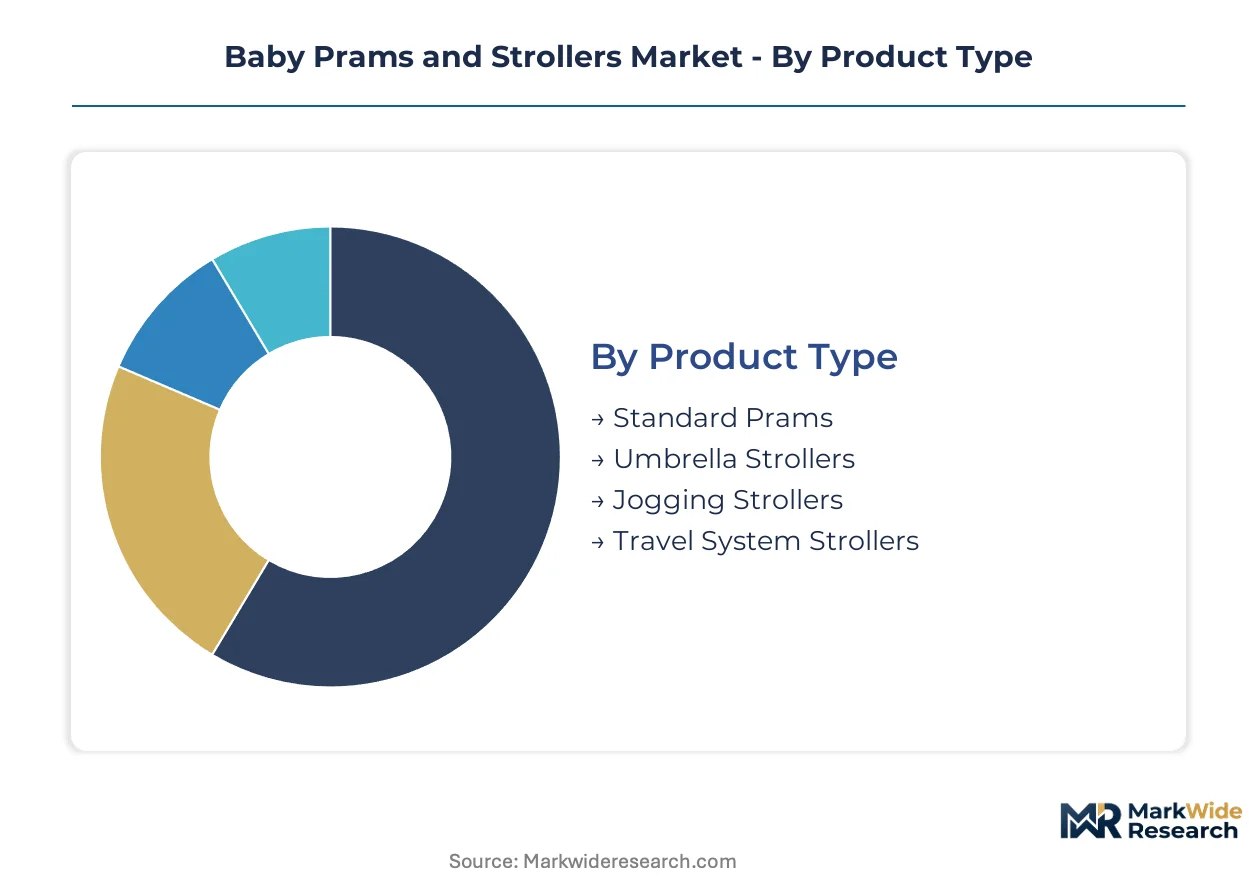
Segmentation in baby prams and strollers reveals how capital allocation, material science, and distribution channel control create divergent margin structures across product architectures. Manufacturers must align R&D spending and certification investments with the specific performance and safety demands of each segment cluster.
Product Type:
Capital intensity varies sharply across frame architectures, with suspension systems and multi-position recline mechanisms demanding specialized tooling and extended testing cycles.
- Standard Prams:Bassinet-compatible designs with flat recline surfaces and reversible seat orientations dominate newborn-focused purchases. Demand concentrates in German specialty retail channels where parents prioritize sleep-safe certifications and extended lie-flat functionality.
- Jogging Strollers:Pneumatic tire configurations and adjustable suspension systems support fitness-oriented parents. Adoption accelerates in San Francisco and Brooklyn where urban parks and running paths intersect with dense residential zones.
- Umbrella Strollers:Ultra-compact folding mechanisms under 15kg target transit-dependent urban families.
- Travel System Strollers:Modular car seat integration creates platform lock-in across the infant gear ecosystem.
Standard prams absorb the bulk of installed capacity; jogging strollers are expanding most quickly.
Material:
Raw material selection determines welding complexity, chemical compliance burden, and finished goods tariff classification across export markets.
- Metal:Magnesium alloy substitution for 6061-T6 aluminum is compressing weight-performance ratios in premium chassis. REACH phthalate restrictions on polymer coatings are accelerating metal frame preference in EU-bound production.
- Plastic:Glass-filled nylon components in wheel hubs and joint mechanisms balance cost against impact resistance. GB standards in China mandate chemical migration testing for all plastic surfaces in direct infant contact.
- Fabric:Water-resistant polyester blends with OEKO-TEX certification dominate canopy and seating applications.
- Wood:Birch and beech laminates appear in boutique bassinet inserts and handle accents.
Metal frames command the highest per-unit material cost; plastic components deliver the steepest expansion trajectory in volume terms.
End User:
Procurement authority and volume scale diverge dramatically between individual consumers and institutional purchasers with negotiated supply agreements.
- Parents:Primary decision-makers research safety ratings and compatibility with existing infant gear. Urban millennial parents in Shanghai and Hamburg compress purchase cycles through direct-to-consumer platform research.
- Daycare Centers:Multi-unit procurement with standardized fleet requirements prioritizes durability certifications and bulk pricing structures.
- Caregivers:Professional nanny services and family childcare providers seek lightweight models for vehicle transport.
- Retailers:Mass merchandisers and specialty boutiques influence manufacturer SKU allocation through shelf-space negotiations and exclusive colorway agreements.
Parents drive absolute revenue volume; daycare centers are gaining share fastest in institutional procurement channels.
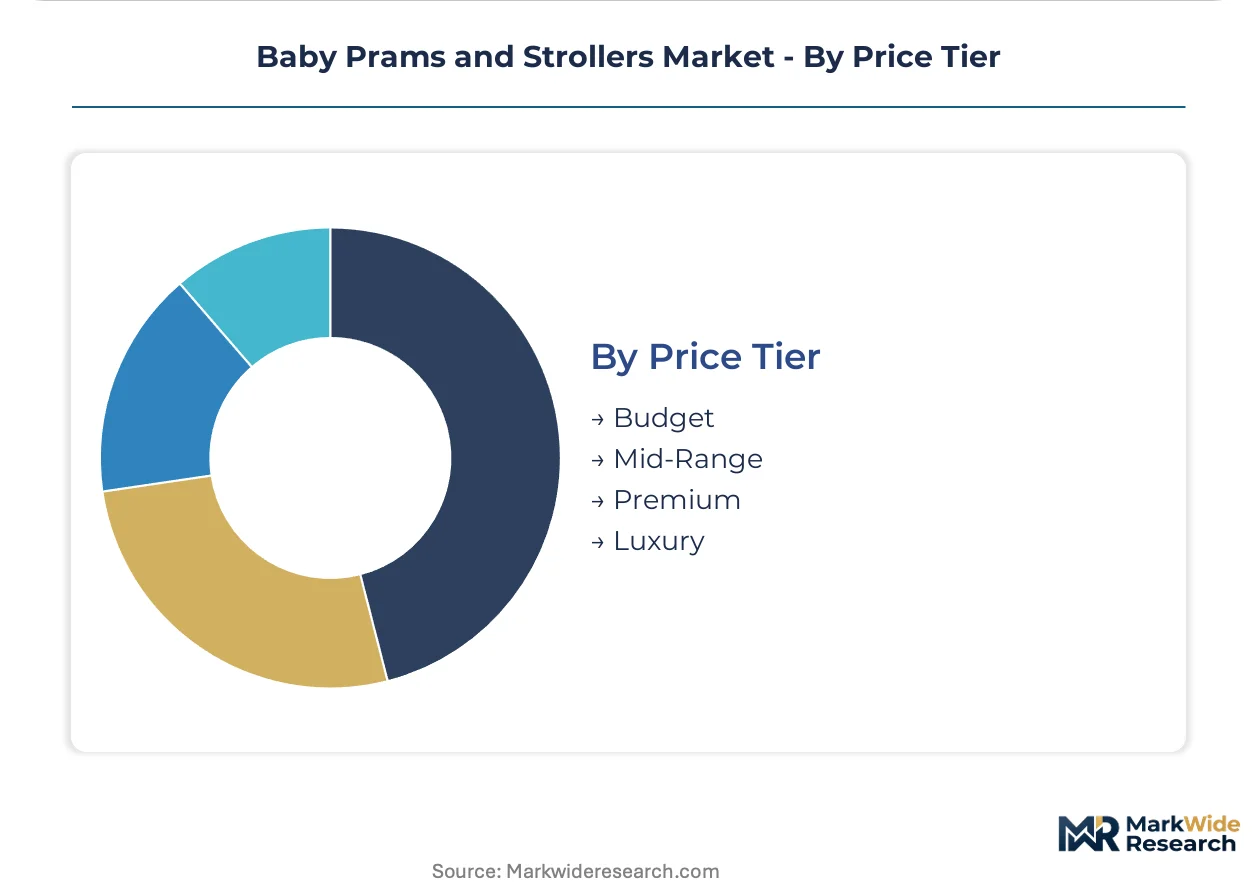
Price Tier:
Margin structure and distribution channel access stratify sharply across pricing bands, with certification grade and component origin serving as primary differentiation signals.
- Premium:Magnesium alloy chassis, leather-accented handle grips, and third-party safety certifications define this tier. Specialty retailers in Munich command 40-60% gross margins on modular travel systems with European design heritage.
- Luxury:Limited-edition collaborations and bespoke fabric selections target gift purchasers and status-conscious parents. Harrods and Bergdorf Goodman anchor distribution with personalized fitting services.
- Budget:Steel tube frames with basic recline functions serve price-sensitive first-time parents through mass retail channels.
- Mid-Range:Aluminum construction with partial feature trickle-down from premium tiers occupies the competitive center.
Premium tiers absorb the bulk of R&D investment; luxury segments are climbing the fastest in per-unit margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial parents in Shanghai, Brooklyn, and Hamburg compress purchase cycles through direct-to-consumer platform research, concentrating demand in metropolitan corridors with high transit dependency and premium retail access.
United States
Fitness-oriented parents in San Francisco and Brooklyn drive jogging stroller adoption with suspension-equipped models. The US Consumer Product Safety Commission enforces federal brake-performance and restraint-system standards. Manufacturing clusters in Michigan and Ohio supply steel tube frames to mass retail channels serving budget-conscious first-time parents.
China
Domestic millennial demand in Shanghai and Beijing favors modular travel systems with car seat integration. GB standards mandate frame stability testing and chemical migration limits for plastic components. Production concentrates in Guangdong and Zhejiang provinces where certified exporters serve both domestic premium channels and European-bound shipments.
Germany
Specialty retailers in Munich and Hamburg command elevated margins on bassinet-compatible standard prams with sleep-safe certifications. REACH Annex XVII restricts phthalates in fabric coatings and polymer frames. Baden-Württemberg hosts engineering firms supplying magnesium alloy chassis components to premium European brands.
United Kingdom
London parents prioritize ultra-compact folding mechanisms for transit-dependent urban mobility. Trading standards authorities align with REACH chemical disclosure requirements for imported infant products. Distribution clusters in the Midlands handle final assembly and compliance certification for EU-bound and domestic retail channels.
Japan
Tokyo and Osaka metropolitan parents demand sub-5kg magnesium alloy frames for crowded transit environments. METI oversees product safety standards harmonized with international stroller certification protocols. Industrial clusters in Aichi Prefecture supply precision-machined wheel hub components to domestic and Southeast Asian manufacturers.
Baby Prams and Strollers Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale magnesium alloy chassis production to meet ultralight frame demand. The vendor base stratifies across three tiers: vertically integrated Asian producers controlling raw material through finished goods, European design houses commanding premium channel margins, and mass-market fabricators competing on volume through retail shelf-space negotiations. Strategic archetypes include alloy specialists, modular platform architects, and private-label suppliers. M&A activity and geographic licensing agreements represent the dominant competitive moves as firms secure distribution access in high-margin metropolitan markets.
Among Asia-Pacific producers, Goodbaby International Holdings Ltd. exemplifies scale-driven vertical integration across manufacturing bases. Dorel Industries Inc. anchors North American mass retail distribution through channel control. Artsana Group occupies the European heritage-design tier, representing premium positioning through specialty retail relationships. These three archetypes illustrate how geographic origin and corporate structure shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Britax Child Safety, Inc. |
| Dorel Industries Inc. |
| Artsana Group |
| Newell Brands Inc. |
| Goodbaby International Holdings Ltd. |
| Bugaboo International |
| Peg Perego |
| Nuna International BV |
| UPPAbaby |
| Others |
Value Network & Pricing Analysis
Vertical integration across Asian manufacturing bases anchors supply positioning and pricing power for stroller producers serving REACH-regulated European markets and GB-standard Chinese domestic channels. Captive magnesium alloy sourcing and in-house frame welding capacity insulate integrated players from Shaanxi smelter price volatility while supporting premium-tier margin structures.
Pricing Analysis
Volume-mid split separates mass-market steel tube frames from magnesium alloy premium tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in mid-range aluminum segments is intensifying because feature trickle-down from magnesium chassis erodes differentiation. First-time parents in mass retail channels exhibit highest price sensitivity; urban millennial buyers of modular travel systems show lowest.
Supply Chain Analysis
Skilled welding technician shortages in Guangdong and Zhejiang provinces constrain capacity expansion for magnesium alloy chassis production. Raw material flows draw from Shaanxi magnesium smelters, 6061-T6 aluminum mills in Henan, and glass-filled nylon compounders in Taiwan. Single-source vulnerability clusters in Shaanxi energy policy exposure. Distribution runs through mass merchandisers in North America, specialty retailers in Germany, and direct-to-consumer platforms in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII phthalate restrictions and GB chemical migration mandates create a cost-of-compliance moat that favors certified incumbents with testing infrastructure already deployed. New entrants face 8-14 month certification timeline barriers that consolidate margin pools among compliant suppliers.
For Market Incumbents: To counter substitution threat from soft-structured baby carriers, deepen platform lock-in through car seat base compatibility investments and backward integration into magnesium alloy component supply. Prioritize certification maintenance across evolving REACH enforcement patterns to defend channel access in European specialty retail.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models for stroller accessories and replacement parts. Target urban millennial parents in Brooklyn and Berlin seeking platform-extendable purchases rather than single-transaction buying. Penetrate through modular travel system white space where car seat convergence creates repeat purchase lock-in.
For Investors and Strategic Acquirers: Exit pathways concentrate in geographic licensing agreements and design-house acquisitions by vertically integrated Asian producers. Long-term viability hinges on compliance infrastructure amortization across multi-jurisdiction sales. Watch for GB standard enforcement intensity in China as inflection indicator for domestic manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnesium Alloy Capacity Expansion | Captive smelter relationships in Shaanxi secure input cost stability for ultralight chassis production. |
| REACH Compliance Certification Investment | Third-party migration testing unlocks CE marking approval for EU specialty retail channel access. |
| Car Seat Platform Integration | Click-in infant carrier compatibility extends customer lifetime value across infant gear ecosystems. |
| Direct-to-Consumer Subscription Launch | Accessory replenishment models capture urban millennial parents compressing purchase cycles. |
| Nearshoring to Mexico and Poland | Regional assembly reduces logistics exposure but faces skilled welding technician shortages. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this stroller market analysis. Primary interviews with product development executives at frame manufacturers, regulatory affairs leads at certification laboratories, category buyers at mass retailers, and supply planners at magnesium alloy processors combined with secondary validation. Bottom-up shipment data from Guangdong and Zhejiang production clusters reconciled against top-down consumer expenditure estimates from customs records and retail audit databases.
Data-stream reconciliation across production volume, import-export flows, and channel inventory levels shaped the analytical framework. Segmentation dimensions modeled include product architecture, material composition, price tier, and end-user procurement authority across the analysis window. CAGRs derived from trend extrapolation of alloy adoption rates, fitness-oriented parent segment expansion, and modular platform penetration. Forecast inputs incorporated REACH enforcement intensity projections and GB standard revision timelines.
Regulatory revision, raw material price volatility, and substitution acceleration from baby carriers are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding certification timeline stability and urban millennial demographic retention. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
US Baby Care Products Market
Baby Products
Postpartum Products Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Slings Market
Baby Products
Baby Feeding Accessories Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Italy Baby Care Products Market
Baby Products
Baby Bassinets Market
Baby Products
Feeding Bra Market
Baby Products
Pregnancy Products Market
Baby Products
Mexico Baby Care Products Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Global Adaptive Strollers Market