
 United States Beauty and Personal Care Products Market | 2026-2036
United States Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
United States Beauty and Personal Care Products Market Analytics
Cosmetic chemist talent is rotating from legacy fragrance houses toward indie skincare labs, tightening formulation capacity at established players. Procter & Gamble leverages its massive in-house R&D campus in Cincinnati to develop proprietary active delivery systems. The Estée Lauder Companies anchors its prestige portfolio through controlled distribution at department store counters and dedicated e-commerce platforms. L'Oréal S.A. competes across mass and prestige tiers simultaneously, using scale advantages in raw material procurement.
Beauty and personal care products encompass topical formulations designed for skin conditioning, hair maintenance, color enhancement, and scent application, typically incorporating emulsifiers, preservatives, active ingredients, and fragrance compounds manufactured through batch processing or continuous mixing systems. These products serve consumer hygiene, aesthetic expression, and dermatological wellness needs across daily grooming rituals. Skincare commands the largest value pool as consumers extend regimens beyond basic cleansing into serums and treatments, while fragrance recovers from pandemic-era demand compression through premium positioning. The unisex gender segment attracts new brand entrants seeking to capture consumers outside traditional binary marketing, though female-identified products still dominate absolute volume.
FDA oversight under the Modernization of Cosmetics Regulation Act now mandates adverse event reporting and facility registration, elevating compliance costs for smaller formulators. California's Proposition 65 and the state's Safer Consumer Products program impose additional ingredient restrictions beyond federal baselines, creating a bifurcated compliance landscape. FTC guidelines on influencer marketing and substantiation claims further constrain digital promotional strategies. Stakeholders must track evolving state-level chemical disclosure laws while building flexible supply chains capable of adapting formulation bases to jurisdiction-specific prohibition lists.
Market Dynamics
The FDA's Modernization of Cosmetics Regulation Act is compressing formulation timelines as brands scramble to meet adverse event reporting and facility registration mandates before enforcement phases tighten.
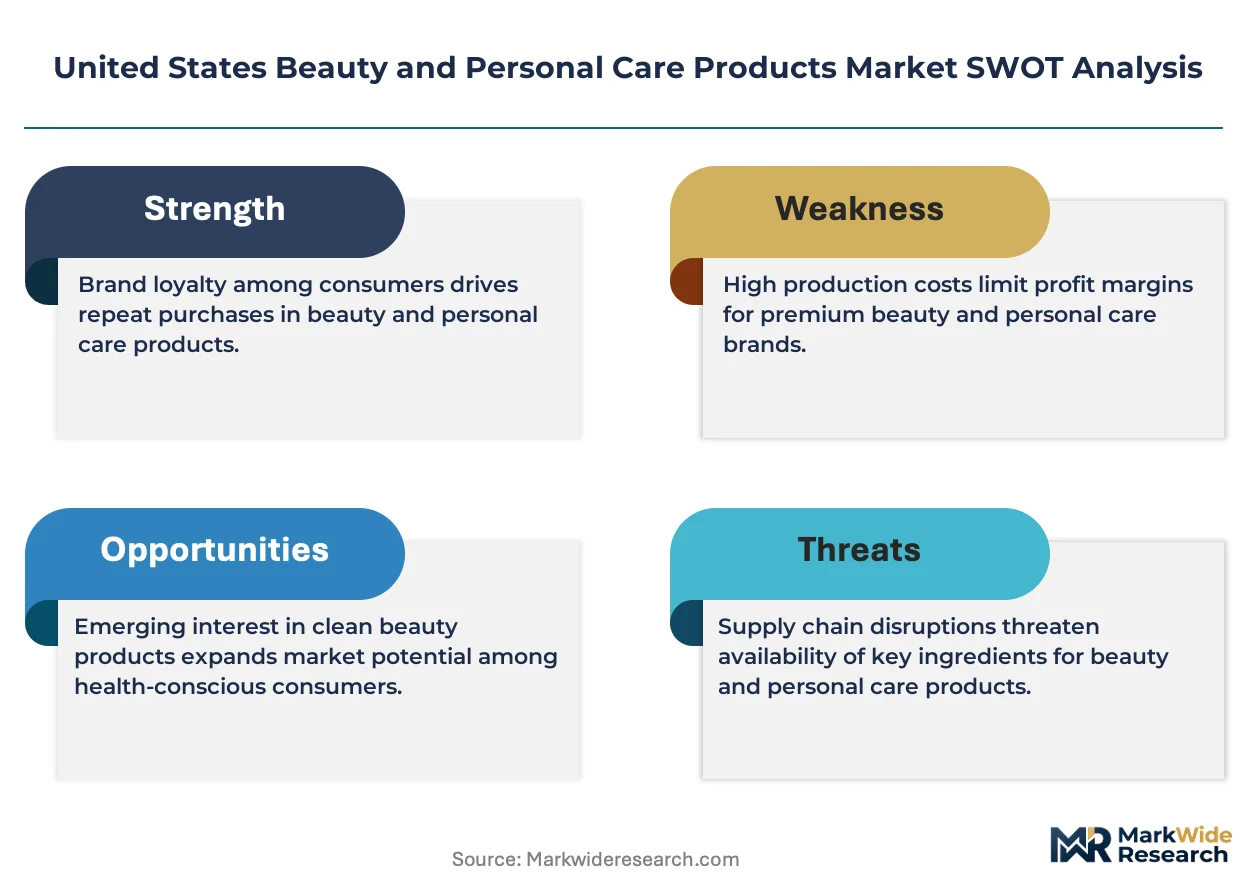
Growth Catalysts
- Clean beauty clustering:Los Angeles and San Francisco metro corridors concentrate venture funding and indie brand incubation, pulling talent from legacy fragrance houses into California-based skincare labs.
- Millennial purchasing power maturation:This demographic cohort is expanding premium skincare spending as income levels advance, shifting volume toward serums and treatment-grade formulations.
- MoCRA facility registration:The FDA's mandatory registration requirement is filtering out informal operators, creating shelf space for compliant mid-tier brands at mass retail.
Market Restraints
- Cosmetic chemist scarcity:Talent rotation toward indie labs has tightened formulation capacity at established players, extending NPD cycles by 4-6 months.
- Bifurcated compliance costs:California's Proposition 65 and Safer Consumer Products program impose ingredient restrictions beyond FDA baselines, forcing dual formulation tracks.
- Raw material concentration:Specialty active suppliers cluster in Switzerland and South Korea, exposing brands to currency and shipping volatility.
Strategic Opportunities
- Unisex segment white space:New entrants are capturing consumers outside binary marketing frameworks, though female-identified products still dominate absolute volume.
- Department store counter revival:Prestige houses can anchor controlled distribution through dedicated physical footprints and owned e-commerce platforms.
- FTC guideline adaptation:Influencer marketing substantiation rules favor brands with in-house clinical testing capabilities, creating barriers for pure digital-native competitors.
Industry Challenges
- Adverse event reporting infrastructure:Smaller formulators lack pharmacovigilance systems to capture and submit serious event data within FDA-mandated windows.
- Batch processing flexibility:Continuous mixing systems require capital retooling to accommodate jurisdiction-specific prohibition lists without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Beauty and Personal Care Products Market |
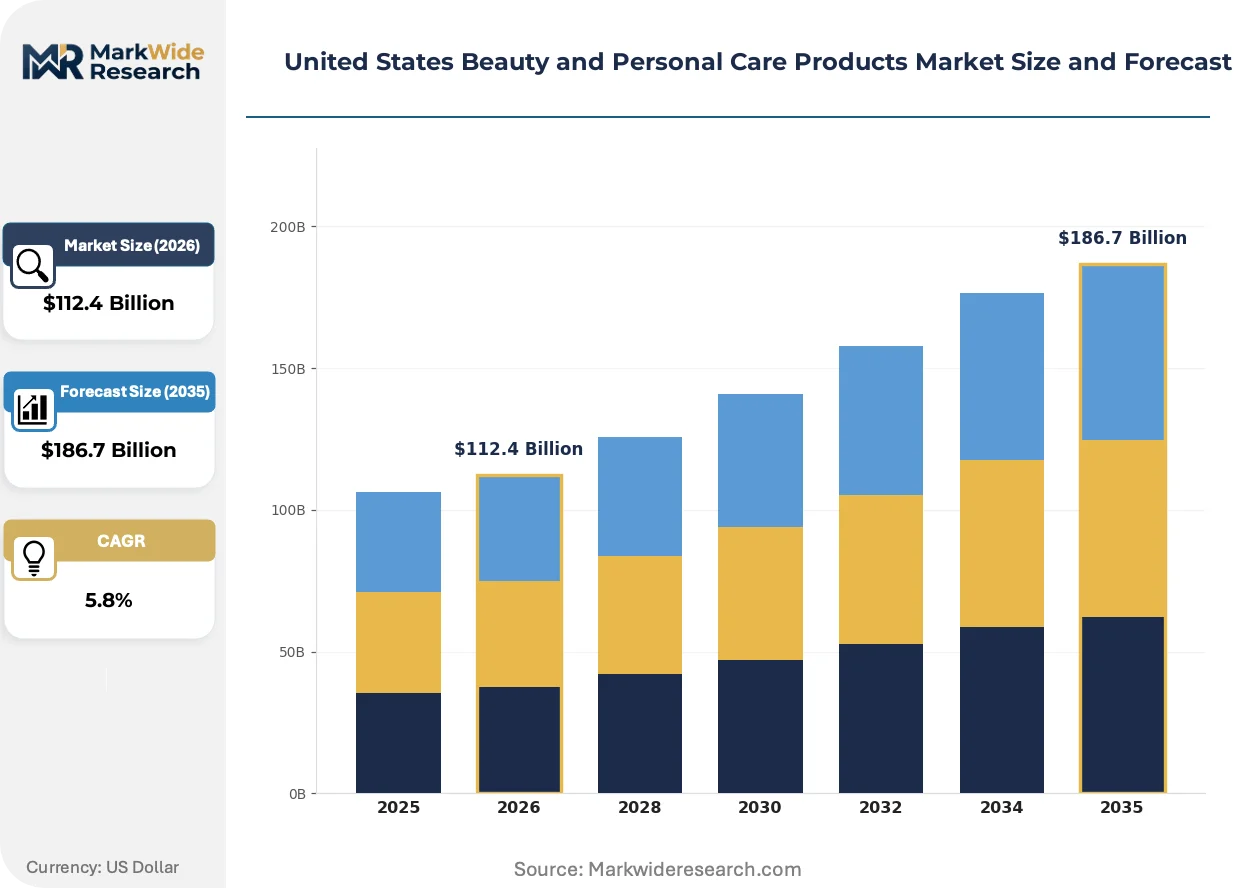
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Consumer Age Group: Teens, Millennials, Gen X, Baby Boomers Gender: Female, Male, Unisex, Non-binary Sales Channel: Online, Drugstores, Supermarkets, Specialty Stores |
| Companies Covered | The Estée Lauder Companies, L'Oréal S.A., Procter & Gamble Company, Unilever PLC, Johnson & Johnson, Shiseido Company Limited, Coty Inc., Revlon Consumer Products LLC, Colgate-Palmolive Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Beauty and Personal Care Products Market Evolving Landscape
Active delivery systems are compressing the efficacy gap between professional treatments and at-home regimens, reshaping how consumers layer products and set performance expectations.
Encapsulation technology is miniaturizing active ingredient penetration through lipid-based or polymer-shell carriers that protect retinoids and peptides from degradation. Prestige skincare buyers are adopting these formats fastest, with dermatologist-recommended brands leading adoption curves. This technology is miniaturizing the distinction between clinical procedures and daily topical use, pressuring medi-spa service pricing.
The FDA's Modernization of Cosmetics Regulation Act now mandates serious adverse event reporting within 15 business days and requires facility registration with biennial renewal. This elevates compliance infrastructure costs for contract manufacturers and co-packers. Smaller California-based formulators are responding by consolidating production into registered third-party facilities rather than maintaining in-house capabilities.
Subscription-based replenishment models are displacing episodic department store purchasing among millennial and Gen Z skincare consumers. Direct-to-consumer channels with auto-replenish algorithms are capturing recurring revenue previously held by physical retail. This shift concentrates most visibly in coastal metropolitan markets where delivery density supports same-day or next-day fulfillment economics.
United States Beauty and Personal Care Products Market Segmentation
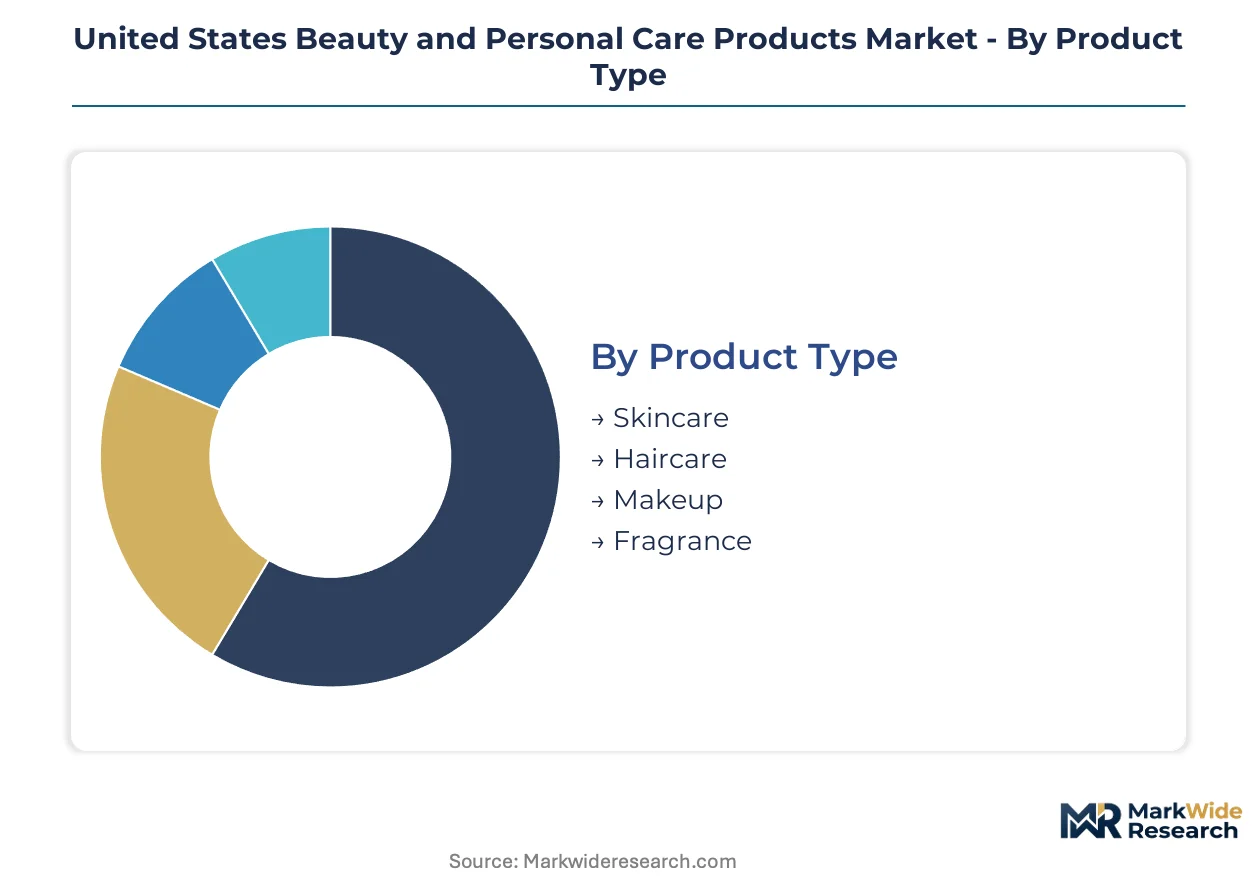
Segmentation reveals how formulation complexity, regulatory exposure, and channel economics concentrate margin pools across distinct consumer cohorts and purchase occasions. Understanding these fault lines enables targeted resource allocation amid FDA facility registration mandates and California ingredient prohibitions.
Product Type:
Substitution pressure runs highest in color cosmetics, where indie brands and private-label alternatives erode loyalty through rapid trend replication and lower price points.
- Skincare:Emulsion-based and serum formulations incorporate retinoids, peptides, and barrier-repair lipids for dermatological conditioning. Demand concentrates in California metropolitan corridors where clean beauty incubation clusters around Los Angeles and San Francisco, driven by millennial income maturation extending regimens into treatment-grade products.
- Haircare:Shampoos, conditioners, and styling products deploy surfactant systems and film-forming polymers for scalp health and fiber maintenance. Volume pools in mass retail channels, constrained by raw material concentration among Swiss and South Korean specialty active suppliers exposing brands to currency volatility.
- Makeup:Color cosmetics rely on pigment dispersions, binding agents, and finish modifiers for aesthetic enhancement.
- Fragrance:Scent formulations combine natural extracts and synthetic aroma chemicals through batch compounding processes.
Skincare retains volume leadership; fragrance holds the steepest expansion curve as premium positioning recovers from pandemic-era demand compression.
Consumer Age Group:
Cost tier stratification separates premium investment from maintenance purchasing, with younger cohorts driving trial volume and older segments anchoring replenishment loyalty.
- Millennials:This demographic commands premium skincare spending expansion as purchasing power matures, shifting volume toward serums and encapsulation technology formats. California coastal markets concentrate subscription-based auto-replenishment adoption, displacing episodic department store purchasing through direct-to-consumer algorithms.
- Gen X:Consumers in this bracket balance treatment investment with efficiency demands, favoring multi-functional formulations that compress regimen steps. Drugstore and supermarket channels capture this pragmatism, though specialty store penetration rises in metropolitan corridors with medi-spa adjacencies.
- Teens:Entry-level consumers drive trial frequency through social commerce and influencer-curated selections.
- Baby Boomers:This segment anchors replenishment loyalty in established prestige houses with controlled distribution footprints.
Millennials represent the fastest-growing trajectory; Baby Boomers retain the highest per-transaction value concentration.
Gender:
Application-based segmentation separates daily grooming maintenance from aesthetic expression rituals, with unisex formulations eroding traditional binary marketing frameworks.
- Female:Products in this segment dominate absolute volume through comprehensive regimen architectures spanning skincare, color cosmetics, and fragrance. Department store counters and dedicated e-commerce platforms anchor prestige distribution, supported by in-house clinical testing capabilities that satisfy FTC influencer marketing substantiation requirements.
- Unisex:Gender-neutral positioning attracts new brand entrants seeking consumers outside traditional marketing binaries. Indie skincare labs in California incubate these formats fastest, though female-identified products still command the majority share.
- Male:Grooming-focused formulations emphasize efficiency and functional benefits over ritual extension.
- Non-binary:Explicit positioning beyond unisex neutrality targets identity-aligned consumption.
Female-identified products retain volume leadership; unisex offerings gain share fastest through coastal metropolitan early adoption.
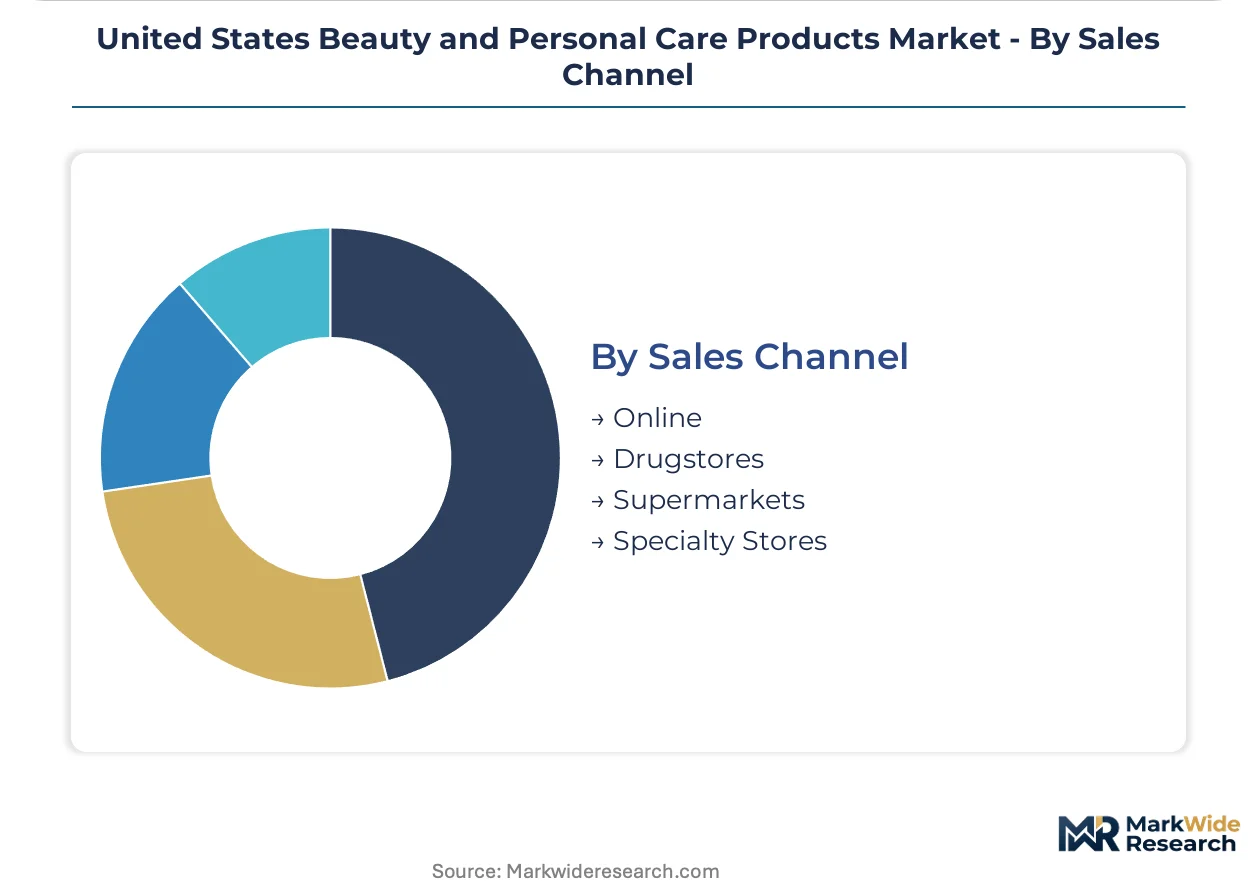
Sales Channel:
Customer type stratification separates replenishment-driven subscription adopters from discovery-oriented episodic purchasers, with channel choice correlating to urban density and delivery infrastructure maturity.
- Online:Direct-to-consumer platforms with auto-replenish algorithms capture recurring revenue previously held by physical retail. Same-day and next-day fulfillment economics concentrate in coastal metropolitan markets where delivery density supports subscription model viability.
- Specialty Stores:Controlled distribution through dedicated physical footprints enables prestige houses to anchor brand equity and deliver personalized consultation. FTC guideline adaptation on influencer marketing substantiation favors these operators with in-house clinical testing capabilities.
- Drugstores:Mass retail channels filter for FDA MoCRA-compliant mid-tier brands as facility registration mandates eliminate informal operators.
- Supermarkets:High-frequency purchase occasions capture basic hygiene and maintenance volume.
Online channels gain share fastest; specialty stores retain the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California metropolitan corridors consume beauty products through clean beauty incubation clusters, while Texas and Florida markets emphasize mass retail efficiency and Hispanic-targeted brand positioning. Northeast corridors maintain prestige department store density, contrasting with direct-to-consumer subscription penetration on the West Coast.
California
Millennial income maturation drives premium skincare spending toward serums and encapsulation formats in Los Angeles and San Francisco metros. The state's Safer Consumer Products program imposes ingredient disclosure requirements beyond FDA baselines. Clean beauty venture funding concentrates in Santa Monica and Oakland labs, pulling cosmetic chemist talent from legacy fragrance houses.
Texas
Hispanic consumer demographics expand color cosmetics trial frequency through social commerce and influencer-curated selections. The Texas Department of State Health Services aligns with FDA MoCRA facility registration timelines for contract manufacturers. Dallas-Fort Worth anchors mass retail distribution hubs serving Southwestern markets with efficiency-focused replenishment models.
New York
Prestige house controlled distribution maintains department store counter density in Manhattan and Westchester County. The New York State Department of Health enforces adverse event reporting infrastructure requirements for smaller formulators. Brooklyn-based indie skincare labs incubate unisex gender-neutral positioning outside traditional binary marketing frameworks.
Florida
Retiree demographics anchor replenishment loyalty in established prestige houses with anti-aging regimen architectures. The Florida Department of Business and Professional Regulation coordinates with FDA on facility registration compliance for coastal contract manufacturers. Miami-Dade serves as Latin American market entry point for US-based brand expansion.
Illinois
Midwest mass retail channels capture Gen X pragmatism through multi-functional formulations compressing regimen steps. The Illinois Department of Public Health monitors cosmetic manufacturing facilities for MoCRA-aligned registration standards. Chicago metropolitan corridors concentrate drugstore and supermarket purchase occasions for basic hygiene maintenance volume.
United States Beauty and Personal Care Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding proprietary active delivery systems and controlled distribution footprints. The middle tier fragments across indie skincare labs and venture-backed clean beauty incubators competing on formulation transparency. Three archetypes dominate: scale-driven mass market operators with raw material procurement advantages, prestige houses anchoring brand equity through dedicated physical counters, and digital-native specialists leveraging subscription algorithms. Competitive moves concentrate on M&A to capture clean beauty talent and capacity expansion into registered third-party manufacturing facilities.
Among the integrated leaders, The Estée Lauder Companies and L'Oréal S.A. occupy positions exemplifying the prestige-mass dual-tier strategy, while Procter & Gamble Company represents the scale-driven R&D campus model with in-house formulation capabilities. These entities anchor competitive dynamics through controlled distribution architectures and biennial FDA facility registration compliance infrastructure that smaller operators struggle to replicate.
| Leading Market Players |
|---|
| The Estée Lauder Companies |
| L'Oréal S.A. |
| Procter & Gamble Company |
| Unilever PLC |
| Johnson & Johnson |
| Shiseido Company Limited |
| Coty Inc. |
| Revlon Consumer Products LLC |
| Colgate-Palmolive Company |
| Others |
Value Network & Pricing Analysis
FDA MoCRA facility registration gates both supplier qualification and price tier access simultaneously, compressing informal operators into commodity positioning while compliant mid-tier brands capture shelf space premiums. This bifurcation concentrates pricing power among registered manufacturers with adverse event reporting infrastructure.
Pricing Analysis
Long-term subscription contracts dominate millennial and Gen Z skincare purchasing, displacing spot-based department store transactions. Three-tier pricing structure across prestige, masstige, and mass levels separates encapsulated active delivery systems from basic emulsion formulations. Cost compression in mass tiers intensifies as private-label alternatives replicate trend cycles faster. Gen X consumers in drugstore channels exhibit highest price sensitivity, while prestige skincare buyers show lowest elasticity.
Supply Chain Analysis
Switzerland and South Korea anchor specialty active ingredient production for retinoid and peptide encapsulation systems. Domestic formulation draws from lipid-based carriers, polymer-shell technologies, and fragrance compounds. Single-source vulnerability concentrates around Swiss biotech suppliers exposed to currency volatility. Distribution runs through registered third-party manufacturing facilities rather than in-house operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Modernization of Cosmetics Regulation Act creates a high-growth disruption window as facility registration mandates filter out informal competitors and consolidate shelf space among compliant operators.
For Market Incumbents: Shield market position through backward integration into registered manufacturing capacity and captive supply of encapsulation technology. Acquire California-based indie skincare labs to secure cosmetic chemist talent before rotation accelerates. Prioritize in-house clinical testing infrastructure to satisfy FTC influencer marketing substantiation requirements. For New Entrants and Emerging Players: Differentiate on unisex gender-neutral positioning outside traditional binary marketing frameworks. Target Brooklyn and Oakland incubation clusters for venture funding access. Pursue direct-to-consumer subscription algorithms with auto-replenish capabilities in coastal metropolitan markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FDA-registered third-party manufacturing facilities. Focus acquisition screening on mid-tier brands with MoCRA compliance infrastructure and clean beauty formulation transparency. Watch cosmetic chemist migration patterns from legacy fragrance houses as talent scarcity signal.| Strategic Initiative | Industry Significance |
|---|---|
| MoCRA Facility Registration | Compliance infrastructure filters informal operators and opens mass retail shelf space. |
| Encapsulation Technology Licensing | Active delivery systems compress efficacy gaps between clinical and at-home treatments. |
| Direct-to-Consumer Platform Launch | Subscription algorithms capture recurring revenue from millennial auto-replenishment adoption. |
| Clean Beauty Brand Acquisition | California lab talent pools accelerate unisex formulation development timelines. |
| Department Store Counter Expansion | Controlled distribution footprints anchor prestige brand equity against digital-native competitors. |
Research Methodology
Desk research of FDA facility registration databases, California Safer Consumer Products filings, and FTC influencer marketing enforcement actions preceded structured interviews with cosmetic chemists, contract manufacturing executives, prestige brand R&D directors, and mass retail category buyers. Secondary validation drew from SEC 10-K disclosures, customs import records for specialty actives, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, consumer age cohort, gender positioning, and sales channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending applied to baseline volume estimates. Forecast inputs incorporated millennial income trajectory assumptions and MoCRA enforcement phase timing.
Material uncertainties — regulatory enforcement intensity, cosmetic chemist supply elasticity, subscription model churn rates — sit outside the modeled envelope. Forecasts reflect assumptions about clean beauty venture funding continuity and California ingredient prohibition expansion. Recalibration cycles align with material shifts in FDA adverse event reporting thresholds and facility registration renewal waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Digitalization of Beauty Industry Market