
 Body Shaper Market | 2026-2036
Body Shaper Market Size, Share, and Industry Trends Forecast 2026-2036
Body Shaper Market Analysis
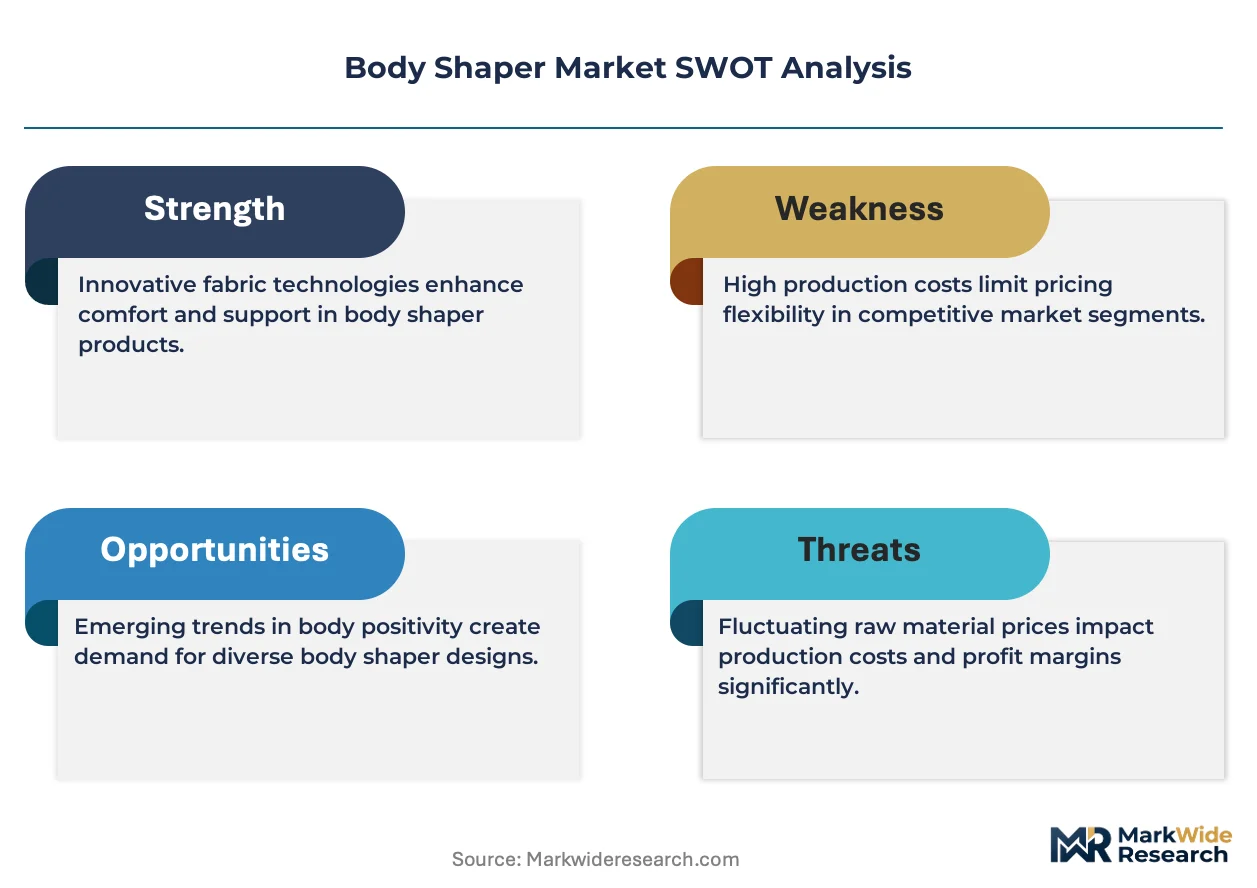
Premium-grade compression engineering is collapsing the boundary between medical recovery wear and everyday fashion apparel. Spanx, Inc. leverages its direct-to-consumer infrastructure to sustain premium pricing power across North American markets. Skims differentiates through inclusive sizing architecture that occupies a distinctive position between luxury and mass-market tiers. Wacoal Holdings Corp anchors its competitive stance on Japanese precision manufacturing standards and specialized fit technology.
Body shapers are engineered compression garments constructed from blended elastomeric fabrics—typically combining nylon and spandex in ratios calibrated to deliver graduated pressure measured in millimeters of mercury—for silhouette modification, postural support, and post-operative tissue stabilization. Bodysuits command the dominant share of value pools due to their full-torso coverage and higher unit economics, while waist trainers represent the fastest-expanding product type driven by social media fitness culture and influencer endorsement cycles. The material dimension shows spandex-dominant blends leading in performance positioning, though cotton-infused variants are carving out a growing niche among skin-sensitivity-conscious consumers.
The US Federal Trade Commission enforces strict labeling standards for textile fiber content and compression claims, while the EU REACH regulation governs chemical safety in elastomeric fabric treatments; together these frameworks elevate compliance costs for new entrants but simultaneously protect established manufacturers with certified supply chains. China's SAMR and national GB standards for textile products add a third layer of conformity requirements for brands sourcing manufacturing capacity from mainland facilities. Stakeholders must monitor evolving regulatory convergence between medical-device classification and consumer apparel standards, as this boundary shift could fundamentally reshape which competitors qualify for market participation.
Market Dynamics
Medical-grade compression certification is redrawing competitive boundaries as EU REACH chemical standards and US FTC labeling enforcement force dual-track compliance investments that smaller manufacturers cannot absorb.
Growth Catalysts
- Post-surgical recovery protocols:Physician endorsement of compression garments for liposuction and abdominoplasty recovery is institutionalizing medical-channel distribution. Hospital procurement committees now specify millimeter-of-mercury pressure ratings.
- REACH chemical compliance:EU textile safety standards are accelerating substitution of legacy elastomeric treatments with bio-based alternatives. Certified suppliers capture shelf space at major European retailers.
- Brazilian aesthetic culture:Beachwear fashion norms and year-round warm climate sustain the world's highest per-capita shapewear penetration. Local manufacturing clusters serve both domestic and Latin American export demand.
Market Restraints
- Spandex price volatility:Petroleum-derived elastane feedstock costs fluctuate with crude oil benchmarks. Brands without long-term polymer supply contracts face margin compression during energy price spikes.
- Guangdong manufacturing concentration:Overreliance on Pearl River Delta cut-and-sew facilities creates single-point-of-failure risk. Geopolitical friction or port disruptions cascade through global inventory pipelines.
- Compression measurement standardization gaps:Absence of unified millimeter-of-mercury testing protocols across jurisdictions forces redundant certification spending. Cross-border product launches face delayed market entry.
Strategic Opportunities
- Indian urban middle-class expansion:Metro-area women in Mumbai, Delhi, and Bangalore are adopting Western-influenced workwear norms. BIS textile quality certification creates trusted positioning for early entrants.
- Smart textile integration:Convergence of conductive thread weaving with compression engineering enables biometric monitoring garments. Sports medicine and pregnancy tracking applications open premium pricing tiers.
- Direct-to-consumer subscription models:Size-matching algorithms and quarterly replenishment cycles reduce customer acquisition costs. Digital-native brands bypass wholesale margin splits entirely.
Industry Challenges
- Specialized pattern engineering talent scarcity:Graduated compression mapping requires rare expertise in 3D body scanning and pressure gradient calculation. Technical schools lack dedicated curriculum pipelines.
- Medical-device classification uncertainty:Pending FDA determinations on post-surgical garment status threaten existing inventory and labeling investments. Legal teams must prepare dual compliance scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Shaper Market |
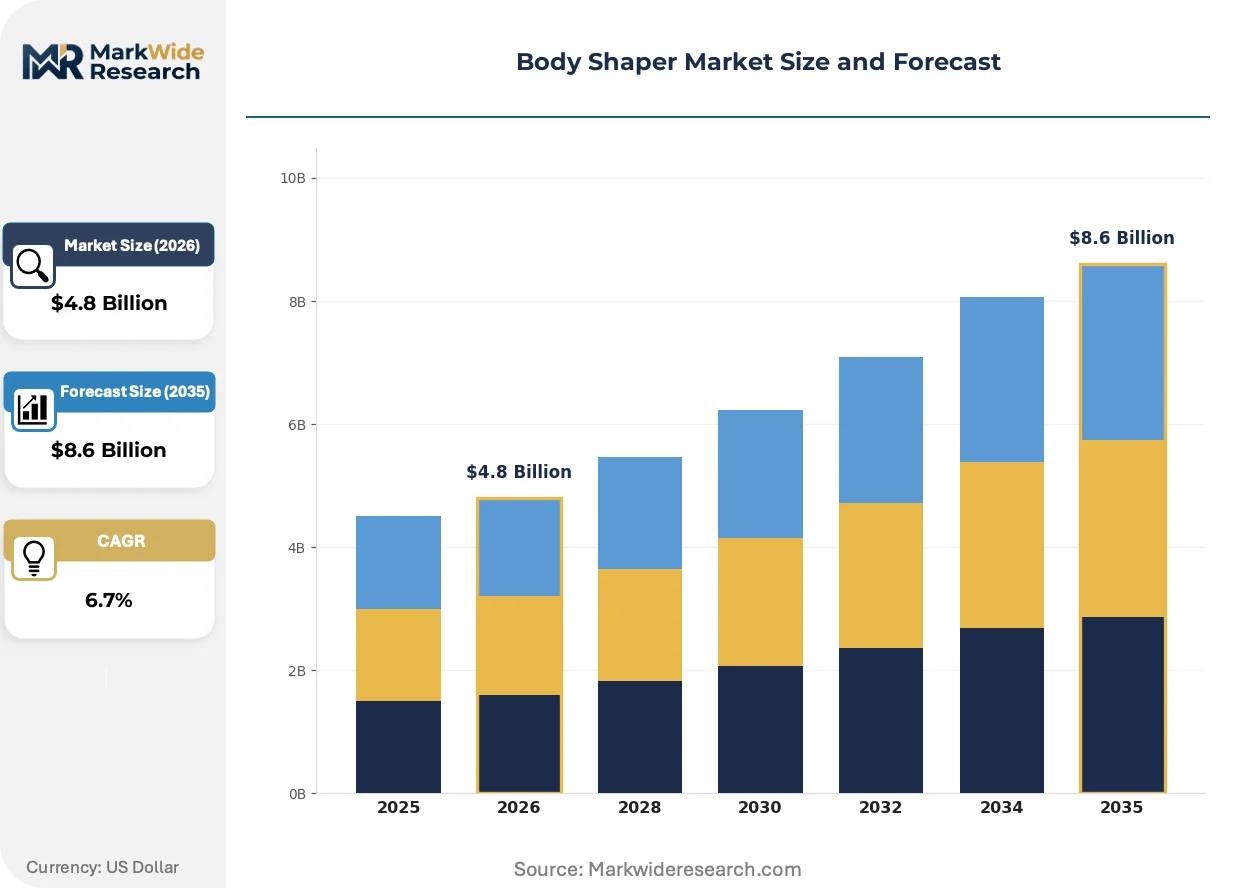
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waist Trainers, Bodysuits, Shapewear Shorts, Tank Tops Material: Nylon, Spandex, Cotton, Polyester Target Audience: Women, Men, Plus Size, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Fitness Centers |
| Companies Covered | Spanx, Inc., Skims, Hanesbrands Inc., Wacoal Holdings Corp, Triumph International, Jockey International, Inc., Under Armour Inc., Nike, Inc., Adidas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Shaper Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are converging to compress product development cycles while elevating performance thresholds for market participation.
Seamless knitting technology is displacing traditional cut-and-sew construction in mid-market compression garments. Post-operative recovery patients and athletic users now expect zone-specific pressure mapping without seam irritation. This manufacturing shift is displacing legacy sewing-floor infrastructure across Asian contract manufacturers.
EU REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent residues are forcing reformulation of spandex finishing treatments. European supply chains absorb 18-24 month compliance timelines while Asian exporters face border rejection risks. Medical-grade certification bodies in Germany and France now prioritize REACH-compliant documentation for hospital procurement eligibility.
Size-inclusivity mandates from major North American retailers are compressing traditional sample-size development models. Brands must now engineer fit systems spanning 32A to 44G bra sizes and XXS to 6XL body shapes. This proliferation is most visible in direct-to-consumer channels where algorithmic fit prediction replaces physical trial.
Body Shaper Market Segmentation
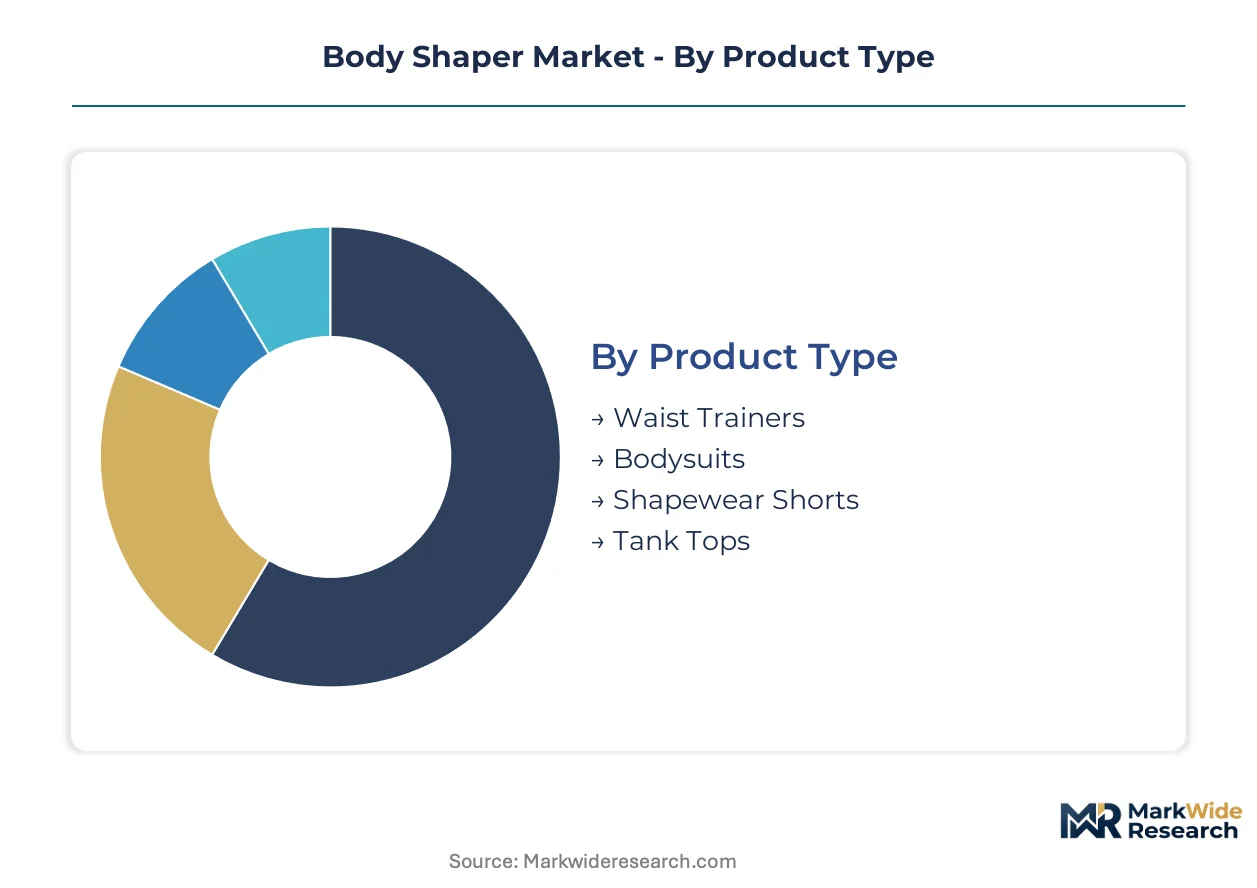
Compression garment purchasing decisions fragment across four distinct axes. Product architecture determines functional use case and price tier. Material composition governs skin tolerance and regulatory compliance eligibility. Target audience selection shapes marketing channel allocation and sizing system complexity. Distribution channel choice dictates margin structure and customer acquisition economics.
Product Type:
Margin pools concentrate in full-torso coverage garments where unit economics support premium engineering investments.
- Bodysuits:Full-torso construction integrates graduated compression zones across abdomen, back, and hip regions. Post-surgical recovery protocols in Brazil and hospital procurement committees in Germany specify millimeter-of-mercury ratings that elevate certified suppliers above commodity competitors.
- Waist Trainers:Targeted abdominal compression systems utilize rigid boning or high-density elastomeric panels. Social media fitness culture in Los Angeles and Miami sustains demand cycles tied to influencer endorsement calendars, though medical regulators in France question therapeutic claims.
- Shapewear Shorts:Thigh-smoothing panels with silicone grip edges prevent roll-up during movement.
- Tank Tops:Upper-torso coverage for posture correction and bust support in athletic contexts.
Bodysuits hold installed capacity. Waist trainers are rotating up the share rankings.
Material:
Cost tier stratification separates medical-grade certification pathways from mass-market commodity positioning.
- Spandex:Petroleum-derived elastane delivers calibrated stretch recovery and graduated pressure retention. REACH Annex XVII compliance timelines in European supply chains favor bio-based alternative investments, with certified German and French suppliers capturing hospital procurement eligibility.
- Nylon:Polyamide base fabrics provide durability and moisture-wicking performance. Japanese precision manufacturing standards anchor premium positioning in Tokyo and Osaka specialty retail channels.
- Cotton:Natural fiber blends address dermatological sensitivity concerns among post-operative patients and pregnancy wear users.
- Polyester:Cost-engineered synthetic for entry-level price points in high-volume online retail.
Spandex commands technical specification authority. Cotton-infused variants are climbing the fastest in skin-sensitivity positioning.
Target Audience:
Volume concentration sits with female consumers, though male and plus-size segments expand addressable market boundaries.
- Women:Core demand segment spanning everyday silhouette modification through medical recovery applications. Size-inclusivity mandates from North American retailers force fit system proliferation from 32A to 44G bra sizes and XXS to 6XL body shapes.
- Plus Size:Extended sizing requirements demand specialized pattern engineering and 3D body scanning infrastructure. Algorithmic fit prediction replaces physical trial in direct-to-consumer channels serving Mumbai, Delhi, and Bangalore metro areas.
- Men:Postural support and athletic recovery applications in gym and workplace contexts.
- Athletes:Biometric monitoring integration through conductive thread weaving for sports medicine tracking.
Women hold installed capacity. Plus Size is rotating up the share rankings.
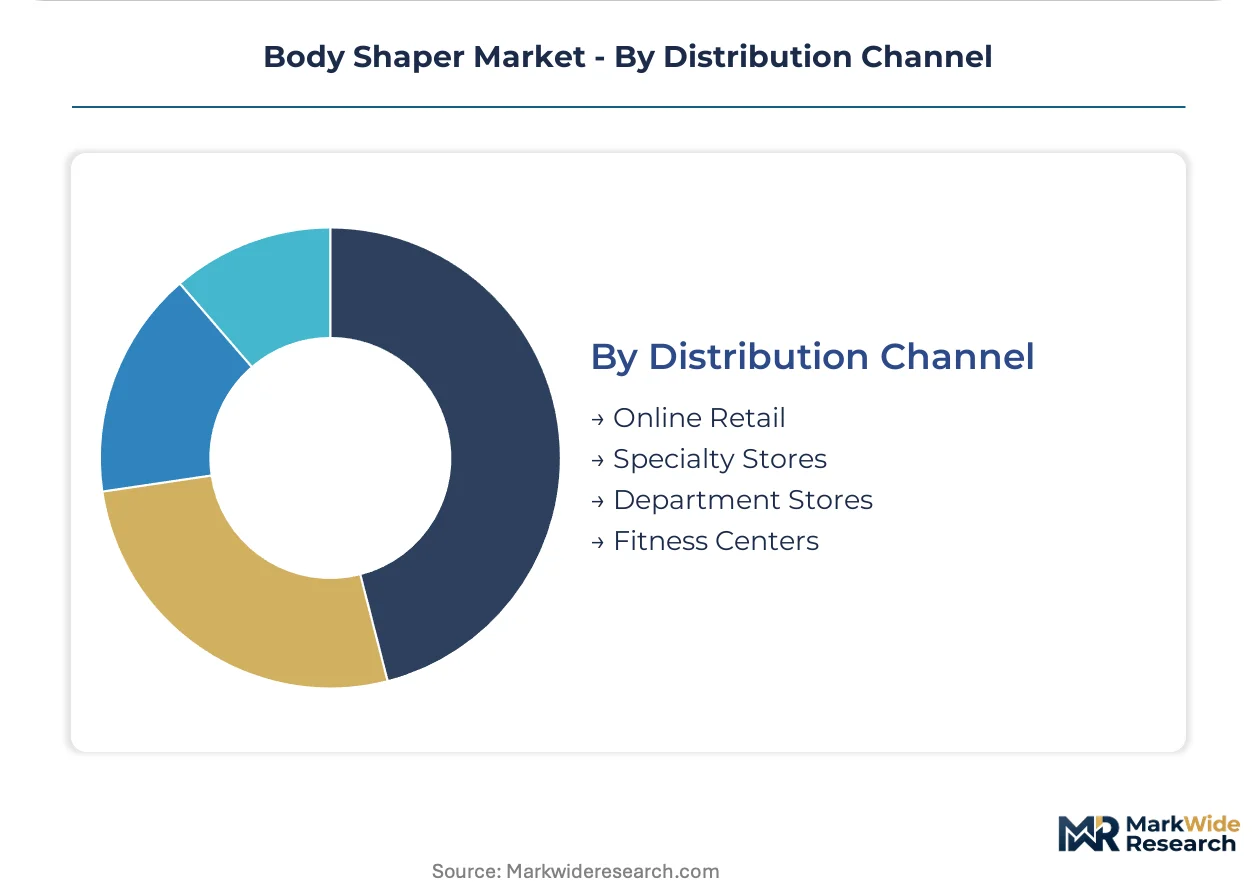
Distribution Channel:
Customer acquisition economics favor digital-native pathways that bypass wholesale margin splits entirely.
- Online Retail:Direct-to-consumer infrastructure sustains premium pricing power through size-matching algorithms and subscription replenishment cycles. FTC labeling enforcement in US markets elevates compliance costs that protect established manufacturers with certified supply chains.
- Specialty Stores:Professional fitting services and medical-grade certification consultation. Hospital procurement committees in Germany and France specify REACH-compliant documentation for post-surgical garment eligibility.
- Department Stores:Mass-market visibility with standardized sizing and lower price points.
- Fitness Centers:Athletic compression and waist trainer placement tied to membership demographics.
Online Retail holds installed capacity. Specialty Stores are rotating up the share rankings in medical-channel positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in Asia-Pacific supply compression garment demand across North America and Europe, while Brazil and the United States function as net importers of finished shapewear despite hosting significant domestic brand headquarters.
United States
Post-surgical recovery protocols and social media fitness culture drive demand for medical-grade compression and waist trainers. The FTC enforces strict textile fiber content and compression claim labeling standards that elevate compliance costs for new entrants. Los Angeles and Miami host influencer marketing clusters that sustain seasonal demand cycles for aesthetic-focused products.
Germany
Hospital procurement committees specify REACH-compliant documentation for post-operative garment eligibility, creating certified supplier advantages. The ECHA's Annex XVII restrictions on solvent residues force 18-24 month reformulation timelines for elastomeric treatments. The Rhine-Ruhr industrial corridor concentrates textile finishing facilities serving European medical channels.
Brazil
Beachwear fashion norms and year-round warm climate sustain the world's highest per-capita shapewear penetration. ANVISA regulates medical-device classifications for post-surgical garments, creating dual-track compliance requirements. São Paulo manufacturing clusters serve domestic demand and Latin American export markets with specialized fit systems.
China
Pearl River Delta cut-and-sew facilities supply global contract manufacturing capacity for mid-market compression garments. SAMR and national GB standards for textile products add conformity layers for brands sourcing mainland production. Guangdong province faces single-point-of-failure risks from geopolitical friction or port disruptions affecting inventory pipelines.
India
Metro-area women in Mumbai, Delhi, and Bangalore adopt Western-influenced workwear norms that expand addressable markets. BIS textile quality certification creates trusted positioning for early entrants in organized retail. The Tiruppur knitwear cluster in Tamil Nadu develops seamless knitting capacity for export-oriented compression garment production.
Body Shaper Market Vendor Landscape
Concentration sits with vertically integrated apparel conglomerates that combine direct-to-consumer infrastructure with certified medical-channel distribution. The vendor base spans three tiers: premium positioning anchored by precision manufacturing standards, mass-market scale driven by wholesale retail penetration, and digital-native challengers exploiting algorithmic fit prediction. Strategic moves center on M&A for pattern engineering talent and backward integration into elastomeric yarn production to hedge petroleum feedstock volatility.
Within the premium positioning tier, Spanx, Inc. and Skims occupy distinctive archetypes that exemplify divergent paths to pricing power. Spanx leverages direct-to-consumer infrastructure to sustain premium positioning across North American markets. Skims differentiates through inclusive sizing architecture spanning extended fit ranges. Wacoal Holdings Corp anchors Japanese precision manufacturing standards in specialty retail channels. These three entities represent the competitive spectrum from digital-native challenger to heritage precision manufacturer.
| Leading Market Players |
|---|
| Spanx, Inc. |
| Skims |
| Hanesbrands Inc. |
| Wacoal Holdings Corp |
| Triumph International |
| Jockey International, Inc. |
| Under Armour Inc. |
| Nike, Inc. |
| Adidas AG |
| Others |
Supply Flow & Price Mechanics
Bio-based elastomeric substitution for petroleum-derived spandex is relocating finishing capacity toward REACH-certified European facilities while compressing margin structures for uncertified Asian suppliers. This material transition simultaneously elevates procurement costs for medical-grade certification and fragments pricing power across compliant and non-compliant supply tiers.
Pricing Analysis
Post-surgical recovery patients anchor pricing stratification across premium, standard, and economy tiers. Price differentiation rests on millimeter-of-mercury certification grade and REACH-compliant documentation status. Cost compression in economy segments is intensifying because uncertified Asian suppliers face border rejection risks at European ports. Hospital procurement committees exhibit lowest price sensitivity, while mass-market online retailers drive aggressive unit economics.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for REACH Annex XVII reformulation compliance in European supply chains. Manufacturing concentrates in China, Brazil, and India, with raw material sourcing drawing from petroleum-derived elastane feedstocks, polyamide yarn production, and cotton-blend finishing. Single-source vulnerability concentrates in Guangdong cut-and-sew capacity. Distribution runs through direct-to-consumer platforms, specialty medical channels, and department store wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as medical-device classification uncertainty creates compliance-tier niches, splitting competitors between certified hospital suppliers and uncertified fashion retailers.
For Market Incumbents: Shield certified supply chain investments by accelerating backward integration into bio-based elastomeric yarn production. Secure long-term polymer contracts to hedge petroleum feedstock volatility. Defend against digital-native challengers through exclusive hospital procurement committee relationships and REACH-compliant documentation lock-in. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for post-surgical compression garments open white-space penetration. Target algorithmic fit prediction in plus-size direct-to-consumer segments where specialized pattern engineering talent scarcity limits incumbent response. Pursue BIS certification in Indian metro markets as beachhead positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-native brands possessing direct-to-consumer infrastructure but lacking medical-channel certification. Five-to-ten year viability hinges on regulatory convergence between medical-device and apparel classifications. Watch FDA determination timelines on post-surgical garment status as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Transition | Bio-based elastomeric certification captures hospital procurement eligibility in Germany and France. |
| Seamless Knitting Capacity Expansion | Tiruppur cluster investments displace legacy cut-and-sew infrastructure for zone-specific pressure mapping. |
| Direct-to-Consumer Subscription Launch | Algorithmic size-matching reduces customer acquisition costs for extended fit range proliferation. |
| Medical-Channel Partnership | Hospital procurement committee relationships institutionalize millimeter-of-mercury specification requirements. |
| Smart Textile Integration | Conductive thread weaving enables biometric monitoring premiums in sports medicine applications. |
Methodological Framework
A spread of perspectives from hospital procurement managers, compression garment brand executives, textile finishing plant managers, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, ECHA REACH registration databases, ANVISA medical-device classifications, and BIS textile quality standards. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product architecture, material composition, target audience demographics, and distribution channel economics. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated REACH Annex XVII compliance timelines and spandex feedstock price volatility indices.
Decision-makers should treat outputs as directional under stable regulatory classification assumptions; material deviation would warrant model refresh. Specific risk factors include FDA medical-device reclassification, ECHA solvent restriction expansion, and Pearl River Delta logistics disruption. Revision becomes warranted when bio-based elastomeric substitution rates cross certification threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
US Thermal Underwear Market