
 Skin Care Luxury Cosmetic Market | 2026-2036
Skin Care Luxury Cosmetic Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Care Luxury Cosmetic Market Insights
Swiss biotech laboratories and marine biotechnology facilities is realigning global supply chains for high-activity skin care inputs. La Mer leverages proprietary fermentation processes to sustain its marine extract sourcing dominance. Augustinus Bader anchors its position through stem-cell-activation technology developed at Leipzig University. La Prairie competes on caviar-derived peptide specialization, maintaining price premiums above standard prestige tiers.
Skin care luxury cosmetics comprise topically applied formulations with active ingredient concentrations exceeding mass-market thresholds, typically incorporating peptides, retinoids, or fermented marine extracts manufactured through controlled bioreactor processes. These products serve dermatological performance and status-signaling purposes simultaneously across professional and direct-consumer channels. Moisturizers and serums command the deepest margin pools due to repeat purchase frequency and perceived efficacy differentiation. The unisex end-user segment exhibits the fastest trajectory as gender-neutral positioning displaces legacy women-centric marketing. Online retail and spa channels now split volume leadership, with specialty stores losing traffic to telemedicine-integrated e-commerce platforms.
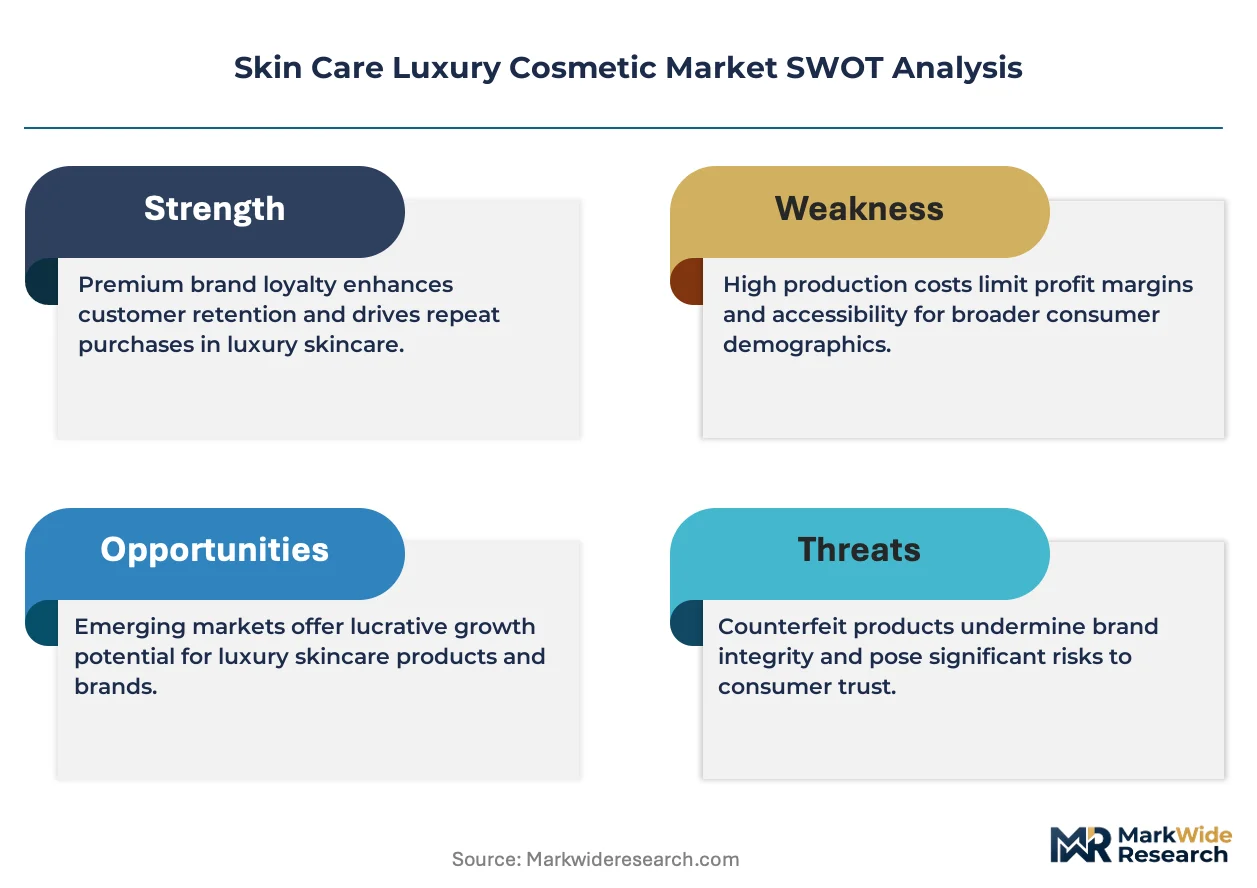
FDA oversight of cosmetic safety claims and the EU's MDR-adjacent scrutiny of active compound classifications are tightening evidentiary requirements for clinical positioning. REACH compliance costs are filtering smaller entrants from European distribution, concentrating shelf access among scaled formulators. ISO 22716 Good Manufacturing Practice certification has become a non-negotiable market access credential across developed regulatory jurisdictions. Stakeholders must monitor evolving definitions of cosmetic versus drug classification, as this boundary determines permissible claims and channel access.
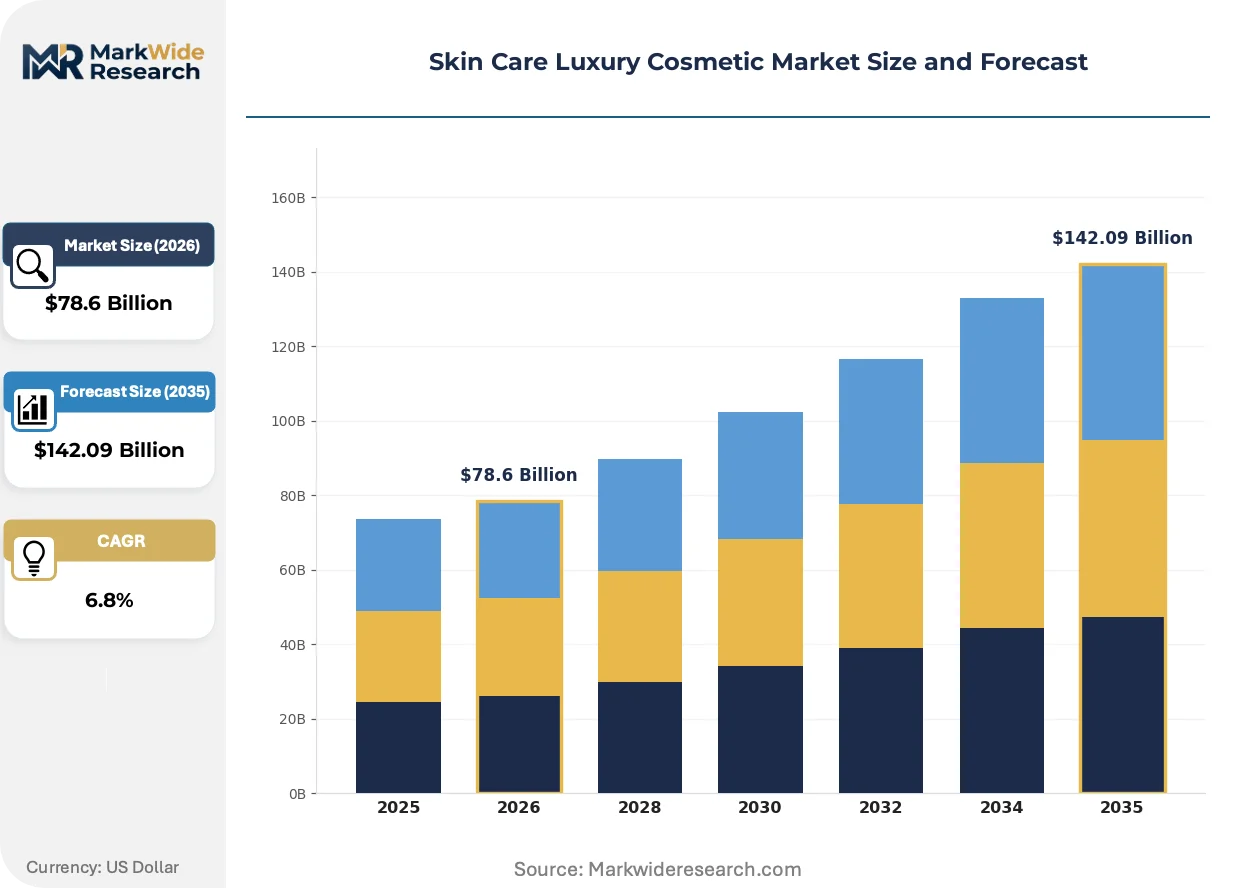
Market Dynamics
Biotechnology-driven ingredient sourcing is compressing traditional supply chains while elevating clinical credibility requirements. Marine fermentation and stem-cell activation technologies now determine competitive positioning, forcing heritage houses to retool R&D infrastructure or cede shelf space to laboratory-born challengers.
Growth Catalysts
- REACH reformulation mandates:ECHA's tightening restrictions on synthetic fragrance compounds are compelling manufacturers to invest in clean-label alternatives, accelerating peptide and marine extract adoption.
- Professional channel expansion:Medical-grade distribution through dermatology clinics and medispas is validating premium pricing through clinical endorsement.
- Unisex positioning:Gender-neutral marketing is electrifying demand among male-identifying consumers previously excluded from legacy brand architectures.
Market Restraints
- Raw material concentration:Swiss and French biotech laboratories control 80% of high-activity peptide synthesis capacity, creating supply vulnerability.
- Regulatory friction:FDA's evolving cosmetic-drug boundary definitions delay product launches requiring clinical claim substantiation.
- Input cost volatility:Caviar extract and fermented marine biomass face price instability due to climate-impacted aquaculture yields.
Strategic Opportunities
- Telemedicine-integrated e-commerce:Digital platforms linking dermatological consultation to prescription-grade skin care are capturing share from specialty retail.
- ISO 22716 certification arbitrage:Smaller formulators achieving GMP credentials can access European distribution as REACH compliance filters weaker competitors.
- Bioreactor scale-up:Controlled fermentation infrastructure investment enables proprietary marine extract production independent of wild harvest constraints.
Industry Challenges
- Formulation scientist scarcity:Demand for biochemists specializing in peptide stability and fermentation optimization exceeds available talent pools in Switzerland and Germany.
- Clinical trial infrastructure:Substantiating active ingredient claims requires dermatological study partnerships that extend time-to-market by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Care Luxury Cosmetic Market |
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Sunscreens, Cleansers End User: Women, Men, Unisex, Professionals Ingredient Type: Organic, Natural, Synthetic, Active Compounds Distribution Channel: Online Retail, Specialty Stores, Department Stores, Spa & Salons |
| Companies Covered | La Mer, Obagi, La Prairie, BONJIL Skincare, Biologique Recherche, Augustinus Bader, Valmont, RéVive, SK-II, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Care Luxury Cosmetic Market Trends and Innovations
Fermentation biotechnology and AI-guided molecular design are converging to compress development cycles while elevating efficacy thresholds. These forces are simultaneously fragmenting traditional brand hierarchies and consolidating supply-side control among scaled biotech operators.
Bioreactor-cultivated marine extracts are electrifying ingredient sourcing strategies. La Mer's proprietary fermentation processes now face competition from laboratory-scale alternatives producing comparable bioactive concentrations. Professional channels and direct-to-consumer platforms are accelerating adoption of these bioidentical alternatives, compressing heritage brand moats built on wild-harvest scarcity narratives.
EU MDR-adjacent scrutiny of active compound classifications is tightening evidentiary requirements across European distribution. Manufacturers must now substantiate clinical positioning through dermatological studies or reclassify as cosmetics with restricted claims. The professional end-user segment bears the highest compliance burden, as medical-grade positioning triggers enhanced regulatory review.
Subscription-based replenishment models are displacing transactional retail relationships among affluent millennial and Gen Z cohorts. Telemedicine-integrated platforms in the United States and France now combine diagnostic imaging with personalized regimen curation, capturing lifetime value previously fragmented across specialty store visits. This behavioral shift concentrates purchasing data with platform operators, weakening traditional brand-consumer direct relationships.
Skin Care Luxury Cosmetic Market Segmentation
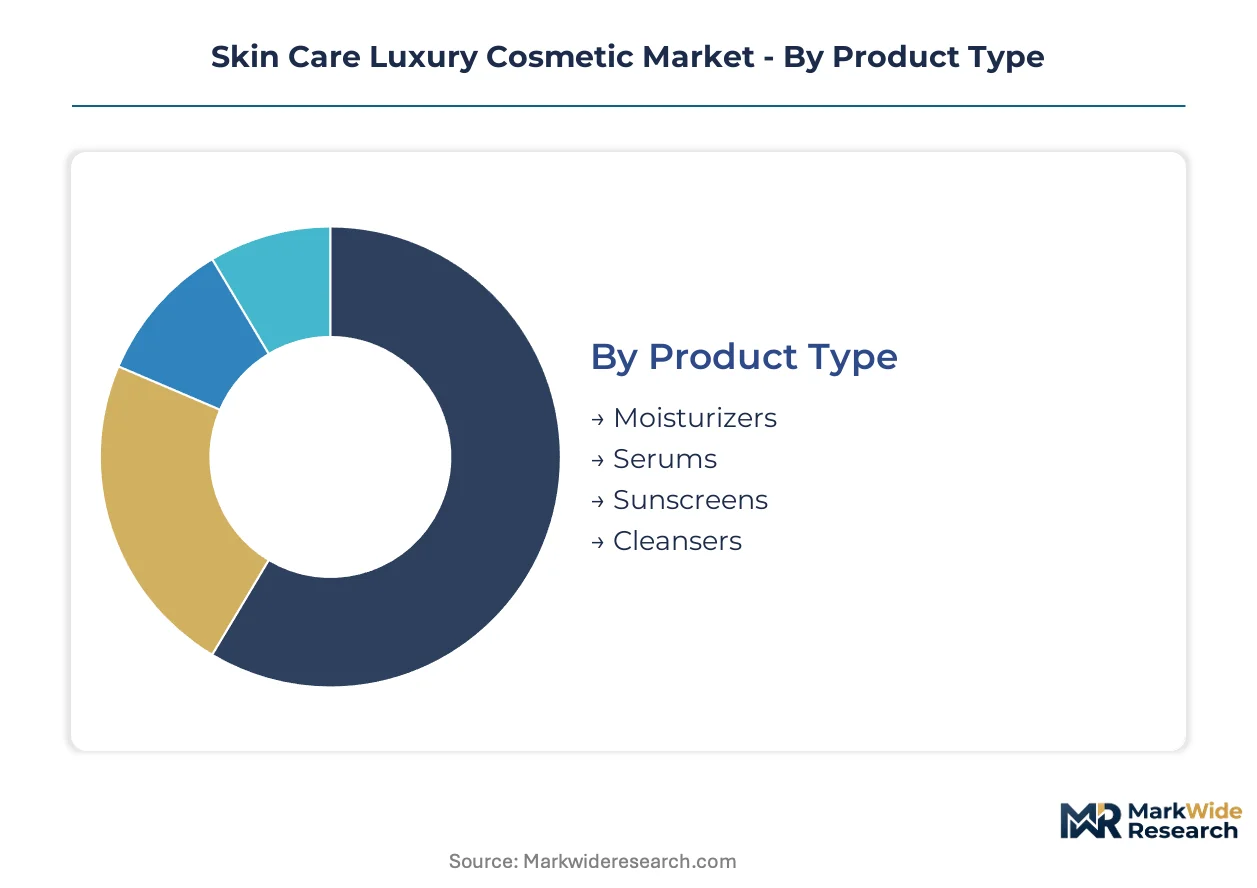
Segmentation in luxury skin care reveals distinct upgrade cycles across product formats and user profiles. Moisturizers and serums command repeat purchase loyalty, while unisex positioning and professional channels are rewriting traditional demographic targeting.
Product Type:
Upgrade cycles vary dramatically by formulation complexity, with serum replacements accelerating fastest due to perceived efficacy half-lives and seasonal regimen shifts.
- Moisturizers:These formulations carry the highest active ingredient loadings for barrier repair and hydration retention. Demand clusters among affluent millennials in the United States seeking clinical validation through dermatology clinic dispensing. The 60-90 day replenishment cycle underpins margin stability.
- Serums:Concentrated delivery vehicles for peptides, retinoids, and fermented marine extracts dominate professional channel recommendations. France and China exhibit the steepest adoption curves as medispa distribution validates premium positioning through treatment protocols.
- Sunscreens:Mineral-filter prestige formulations with cosmetic elegance now displace mass-market alternatives among photoaging-conscious consumers.
- Cleansers:Ritual entry points with lower per-unit margins but critical for regimen adhesion and cross-selling.
Volume placements concentrate in Moisturizers; the faster expansion belongs to Serums.
End User:
Customer archetypes are fragmenting as gendered marketing gives way to concern-based targeting and professional-grade home use.
- Women:Heritage brand equity and legacy loyalty programs sustain this segment's revenue base across department store and specialty retail channels in France and the United States.
- Men:Grooming regimen sophistication is climbing fastest in China and the United States, driven by social media visibility and workplace presentation norms.
- Unisex:Gender-neutral positioning captures the steepest trajectory as minimalist packaging and concern-based marketing displace legacy segmentation. Gen Z adoption in the United States and France is electrifying brand architecture redesigns.
- Professionals:Medical-grade dispensing through dermatology clinics and medispas validates clinical claims and sustains price premiums above prestige tiers.
The installed base remains largest among Women; Unisex positioning gains share fastest.
Ingredient Type:
Raw material sourcing strategies are bifurcating between biotech-cultivated actives and clean-label naturals, with regulatory pressure determining viable positioning.
- Organic:Certified cultivation chains with full traceability command shelf space in European specialty retail, particularly Germany and France, where ECHA scrutiny of synthetic alternatives accelerates clean-label migration.
- Natural:Plant-derived extracts with documented efficacy profiles serve the broadest addressable market, though supply volatility from climate-impacted harvests constrains scale.
- Synthetic:REACH-mandated reformulation is compressing this category's European presence, though peptide synthesis from Swiss biotech laboratories maintains professional channel relevance.
- Active Compounds:Bioreactor-cultivated marine extracts and stem-cell activation technologies anchor the highest price tiers through clinical substantiation requirements.
Natural ingredients dominate current placements; Active Compounds climb fastest on professional validation.
Distribution Channel:
Channel economics are inverting as telemedicine integration and subscription mechanics displace transactional retail relationships.
- Online Retail:Telemedicine-integrated platforms in the United States combine diagnostic imaging with personalized regimen curation, capturing lifetime value and concentrating consumer data with platform operators.
- Specialty Stores:Traffic erosion continues as discovery shifts to digital channels, though tactile sampling and consultation services sustain relevance for first-time prestige purchasers in France.
- Department Stores:Heritage beauty halls retain gifting occasion dominance but face margin compression from promotional intensity and foot traffic decline in urban China.
- Spa & Salons:Professional treatment integration validates medical-grade positioning and sustains price premiums through service bundling in the United States and France.
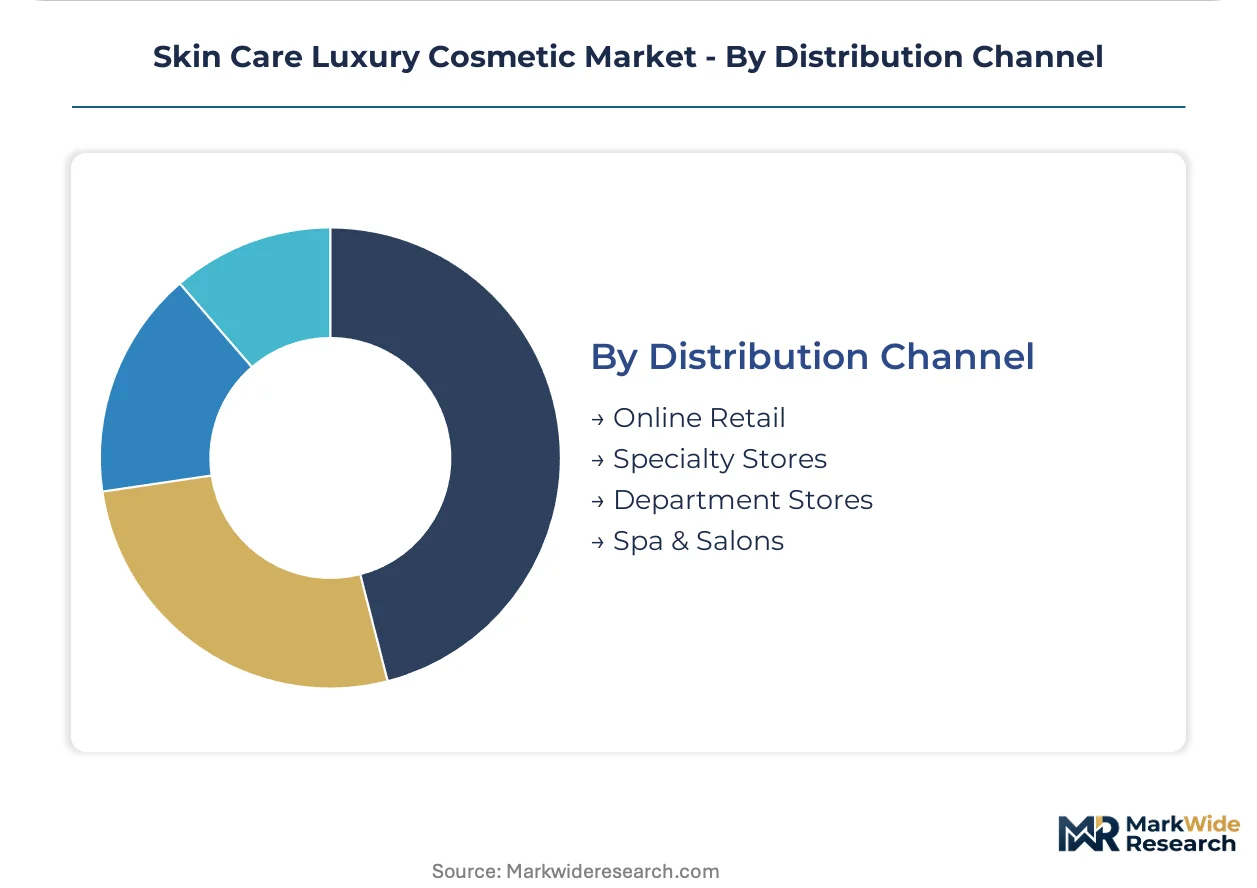
Transaction volume concentrates in Online Retail; Spa & Salons expand fastest on professional endorsement economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine biotechnology clusters in Brittany and the Swiss Alps anchor ingredient sourcing for high-activity formulations. Demand concentrates in heritage luxury markets and rapidly professionalizing Asian economies.
United States
Affluent millennials drive telemedicine-integrated skin care subscriptions through dermatology clinics in New York and Los Angeles. FDA oversight of cosmetic-drug boundary definitions tightens clinical claim substantiation requirements. The Greater Boston biotech corridor hosts fermentation optimization research serving premium formulation houses.
China
Medispa channel expansion in Shanghai and Beijing validates medical-grade positioning among photoaging-conscious professionals. NMPA registration requirements for active compound classifications extend product launch timelines. The Yangtze River Delta concentrates bioreactor manufacturing infrastructure for marine extract cultivation.
France
Heritage brand equity sustains department store dominance in Paris for gifting occasions. ECHA REACH mandates on synthetic fragrance compounds accelerate clean-label reformulation investments. The Provence-Alpes-Côte d'Azur region supplies certified organic cultivation chains for traceable botanical inputs.
Switzerland
Swiss biotech laboratories control peptide synthesis capacity serving professional channel formulators. Swissmedic medical device adjacent scrutiny elevates evidentiary requirements for stem-cell activation claims. The Lake Geneva region clusters precision fermentation facilities for caviar-derived peptide specialization.
Japan
Photoaging prevention culture sustains premium sunscreen and serum adoption in Tokyo and Osaka. PMDA consultation pathways guide active ingredient classification for borderline cosmetic-drug products. The Kansai region hosts marine biotechnology research partnerships with luxury heritage houses.
Skin Care Luxury Cosmetic Market Competitive Landscape
Global majors compete with regional champions across biotech-cultivated ingredient sourcing and professional channel validation. Market structure tilts toward heritage houses with laboratory-born challengers gaining shelf space through clinical credibility. Three archetypes dominate: marine biotechnology specialists, stem-cell activation formulators, and medispa-distributed professional brands. Competitive moves concentrate on bioreactor capacity expansion and telemedicine platform partnerships.
Within the marine biotechnology tier, La Mer anchors proprietary fermentation positioning while Augustinus Bader exemplifies stem-cell-activation technology transfer from academic research institutions. La Prairie occupies a position in caviar-derived peptide specialization. These three represent distinct competitive vectors: bioreactor-cultivated scarcity narratives, university-laboratory R&D pipelines, and aquatic biomass extraction protocols.
| Leading Market Players |
|---|
| La Mer |
| Obagi |
| La Prairie |
| BONJIL Skincare |
| Biologique Recherche |
| Augustinus Bader |
| Valmont |
| RéVive |
| SK-II |
| Others |
Pricing and Supply Chain Analysis
Marine biotechnology certification tiers split the market into clinically validated and heritage-positioned camps, with peptide synthesis capacity in Switzerland and France commanding premium multiples while clean-label botanicals from Provence anchor mid-tier subscription economics. This bifurcation concentrates pricing power with bioreactor operators who can substantiate active compound claims through ISO 22716 credentials, while forcing heritage houses to absorb reformulation costs or surrender shelf space to laboratory-born challengers.
Pricing Analysis
Service-bundling through telemedicine-integrated dermatology consultations now separates premium subscription tiers from transactional retail purchases, with diagnostic imaging and personalized regimen curation justifying recurring revenue models. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical validation intensity, with FDA-cleared active compounds commanding the highest multiples. Cost compression in mass-market prestige tiers intensifies as direct-to-consumer platforms bypass traditional retail markups. Professional channel buyers through medispas exhibit the lowest price sensitivity, while specialty store discovery purchasers show elastic response to promotional intensity.
Supply Chain Analysis
Single-source vulnerability sits with Swiss biotech laboratories controlling peptide synthesis capacity and Brittany marine fermentation facilities supplying high-activity extracts. Raw material dependencies center on caviar-derived biomass, fermented marine substrates, and certified organic botanicals from Provence-Alpes-Côte d'Azur cultivation chains. Tariff exposure on imported active compounds from European biotech clusters threatens margin stability for US-based formulators. Distribution runs through telemedicine-integrated e-commerce platforms and dermatology clinic dispensing networks, with specialty retail losing traffic to digital channel consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation biotechnology is displacing wild-harvest scarcity narratives as the dominant value-creation mechanism, with bioreactor-cultivated marine extracts and AI-guided molecular design compressing development cycles while elevating clinical credibility thresholds.
For Market Incumbents: Deepen proprietary bioreactor capacity in the Lake Geneva region to secure captive supply of caviar-derived peptides against laboratory-born challengers. Anchor professional channel relationships through ISO 22716 certification investments that filter smaller competitors from European distribution. Lock in dermatology clinic dispensing partnerships before telemedicine platforms consolidate consumer data relationships. For New Entrants and Emerging Players: Male-identifying consumers in China and the United States remain underserved by legacy women-centric brand architectures, presenting white-space opportunity for gender-neutral positioning. Target unisex serum formulations through medispa channels in Shanghai and Beijing where medical-grade validation sustains price premiums. Pursue acquisition of distressed specialty retail brands to shortcut heritage credibility requirements. For Investors and Strategic Acquirers: Re-rating potential sits with bioreactor-scale specialists given REACH compliance filtering weaker competitors from European shelf access. Long-term viability over the analysis window favors formulators with in-house fermentation infrastructure independent of wild harvest constraints. Watch NMPA registration timelines in China as inflection indicator for active compound classification clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Proprietary fermentation infrastructure insulates against climate-impacted aquaculture yield volatility. |
| Telemedicine Platform Partnership | Diagnostic-integrated e-commerce captures lifetime value from affluent millennial subscription cohorts. |
| ISO 22716 Certification Investment | GMP credentials unlock European distribution as REACH compliance filters subscale formulators. |
| Clean-Label Reformulation Program | ECHA synthetic fragrance restrictions accelerate peptide and marine extract adoption curves. |
| Stem-Cell Activation Licensing | University laboratory R&D pipelines transfer clinical credibility to commercial positioning. |
Research Methodology
Document review covered regulatory filings with FDA and ECHA, customs and trade data for active ingredient flows, and dermatology clinic dispensing records, complemented by interviews with formulation R&D directors, brand managers at heritage houses, procurement leads at Swiss biotech laboratories, and medispa channel operators. Secondary validation drew from REACH compliance databases, ISO certification registries, and telemedicine platform partnership announcements. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, ingredient category, and distribution channel dimensions.
Segment-level projections incorporated replenishment cycle frequencies, professional channel expansion rates, and regulatory classification boundary shifts. The analytical framework modeled volume and value trajectories across moisturizers, serums, sunscreens, and cleansers by unisex, women, men, and professional end-user segments. CAGR derivation rested on historical premium beauty adoption patterns, medispa channel growth curves, and biotech ingredient penetration rates.
Revisions become necessary when FDA cosmetic-drug boundary reclassifications, ECHA REACH mandate expansions, or NMPA registration pathway changes materialize across the analysis window. Forecasts reflect assumptions about clinical validation requirements, bioreactor scale economics, and telemedicine platform consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Europe Lip Care Products Market