
 Europe Passive Electronic Components in Aerospace and Defense Market | 2026-2036
Europe Passive Electronic Components in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Passive Electronic Components in Aerospace and Defense Market Insights
Missile systems and radar modernization is restructuring procurement priorities across European defense ministries. TDK Corporation leverages extensive dielectric material expertise to dominate high-voltage capacitor supply for radar transmitters. Vishay Intertechnology Inc. anchors its position through military-grade resistor lines qualified to MIL-PRF standards. KEMET Corporation specializes in tantalum and ceramic capacitors for avionics environments requiring extreme temperature stability.
Europe passive electronic components in aerospace and defense encompass resistors, capacitors, inductors, and filters engineered to operate across temperature extremes from minus 55°C to 175°C with failure rates below 0.001% per 1,000 hours. These components stabilize voltage, filter electromagnetic interference, and store energy in flight-critical systems where active semiconductors cannot survive radiation or thermal stress. Capacitors command the largest value share due to dielectric development costs and qualification cycles for space-grade parts. Surface mount technology leads volume deployment in modern avionics, while thru-hole technology persists in legacy military platforms with decades-long service obligations. Filters represent a concentrated margin pool as electromagnetic compatibility requirements tighten for fifth-generation fighter integration.
EMA medical device standards, REACH substance restrictions, and EU Green Deal material compliance frameworks collectively shape component qualification pathways and supplier eligibility across European aerospace programs. ECHA substance-of-very-high-concern listings are forcing reformulation of electrode materials and termination finishes in capacitor manufacturing. Stakeholders must monitor evolving defense procurement localization mandates and dual-use export control harmonization between EU member states and NATO allies.
Market Dynamics
REACH substance restrictions and EU Green Deal material mandates are forcing capacitor manufacturers to reformulate electrode materials and termination finishes, compressing qualification timelines while defense ministries accelerate radar and satellite procurement.
Growth Catalysts
- Satellite constellation deployment:European defense ministries are expanding procurement of high-reliability capacitors and inductors for unmanned aerial platforms and low-earth orbit systems.
- REACH compliance innovation:ECHA substance-of-very-high-concern listings are accelerating development of tin-lead alternatives and rare-earth substitution strategies across the supplier base.
- Radar transmitter modernization:Dielectric material advances are enabling higher-voltage operation in fifth-generation fighter integration programs.
Market Restraints
- Raw material concentration:Tantalum ore supply concentrates in conflict-affected regions, creating price volatility and ethical sourcing verification costs for capacitor manufacturers.
- Qualification cycle rigidity:MIL-PRF certification requirements impose 18-36 month validation periods that prevent rapid product iteration.
- Substitution limitations:Active semiconductor alternatives cannot survive radiation or thermal stress in flight-critical applications, locking in passive component dependency.
Strategic Opportunities
- Eastern European defense localization:Poland and Romania are establishing domestic assembly capabilities for military-grade resistors and filters under NATO supply chain diversification mandates.
- Copper-nickel-tin alloy development:Advanced termination metallurgy is expanding into space-grade ceramic capacitors as REACH-compliant alternatives to traditional leaded finishes.
- Dual-use export harmonization:EU-NATO alignment on export controls is creating streamlined qualification pathways for components serving both civilian aerospace and defense applications.
Industry Challenges
- Electromagnetic compatibility engineering shortage:Filter design expertise for fifth-generation fighter integration is concentrated among aging specialists in France and Germany.
- Legacy platform support obligations:Thru-hole technology production lines must be maintained for military aircraft with 40-year service lives while surface mount capacity expands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Passive Electronic Components in Aerospace and Defense Market |
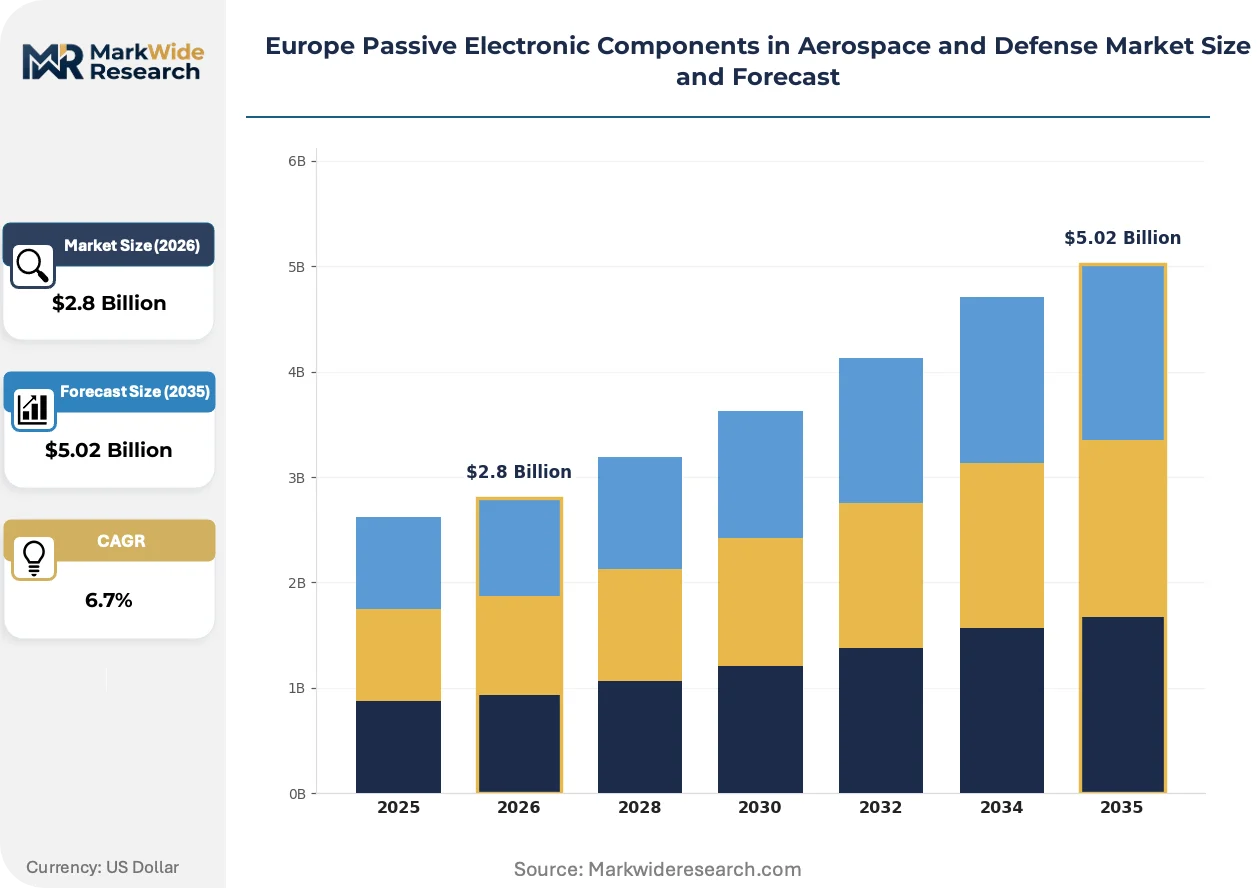
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Resistors, Capacitors, Inductors, Filters Application: Avionics, Communication Systems, Missile Systems, Radar Systems Technology: Passive RFID, Surface Mount Technology, Thru-Hole Technology, Hybrid Technology End User: Aerospace Manufacturers, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | KEMET Corporation, TDK Corporation, Vishay Intertechnology Inc., Murata Manufacturing Co. Ltd, AVX Corporation, Panasonic Corporation, Taiyo Yuden Co., Ltd., Cornell Dubilier Electronics Inc., Bourns Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Passive Electronic Components in Aerospace and Defense Market Trends and Innovations
Component miniaturization and material substitution are converging with tightening electromagnetic compatibility requirements, reshaping how European primes qualify suppliers for next-generation platforms.
Nanocomposite dielectric materials are expanding into high-voltage capacitor applications for radar transmitters. Thales and BAE Systems are qualifying these formulations for phased array systems operating above 40 GHz. This technology is expanding into previously inaccessible frequency bands while compressing form factors by 30 percent compared to conventional ceramic constructions.
EU Green Deal material compliance frameworks are mandating full supply chain traceability for rare-earth elements and conflict minerals. ECHA substance-of-very-high-concern listings now cover 233 chemicals, forcing reformulation of electrode pastes and termination platings. Capacitor manufacturers serving Airbus Defence and Space programs are responding with copper-nickel-tin alloy substitutions and blockchain-tracked material provenance systems.
Defense procurement localization mandates are fragmentizing traditional pan-European supplier relationships. French, German, and British ministries now require domestic content thresholds for critical passive components, compelling TDK Corporation and Vishay Intertechnology to establish qualified production cells within each national jurisdiction. This pattern is most visible in filter and inductor categories where electromagnetic interference specifications vary by national platform requirements.
Europe Passive Electronic Components in Aerospace and Defense Market Segmentation
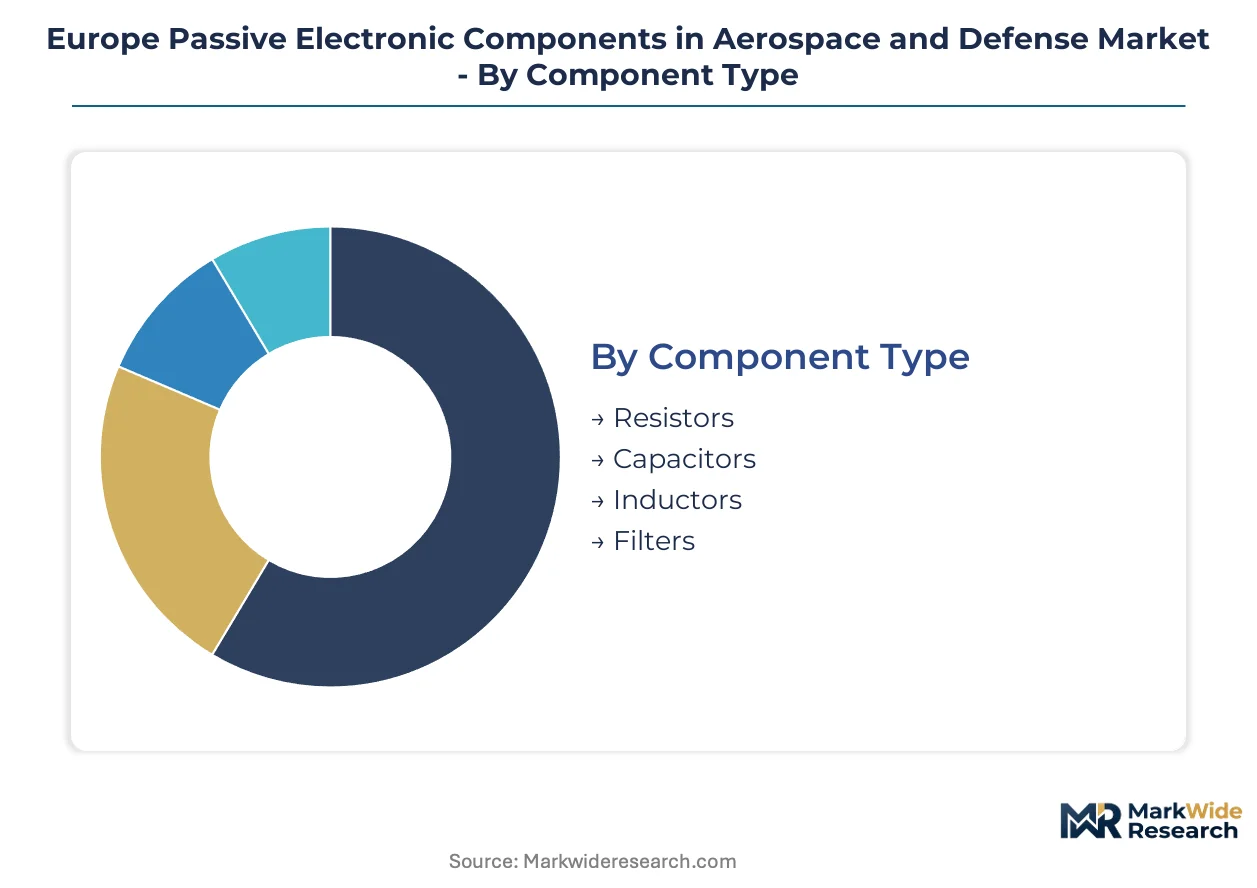
Passive electronic components in European aerospace and defense exhibit distinct procurement patterns across component categories and mounting technologies. Segmentation reveals how qualification requirements and platform modernization priorities reshape supplier strategies across national defense programs.
Component Type:
Capacitors dominate procurement value due to dielectric development costs and space-grade qualification cycles, while resistors anchor volume deployment across legacy military platforms.
- Capacitors:Dielectric formulations stabilize voltage and store energy across temperature extremes from minus 55°C to 175°C. Demand concentrates in French and German radar modernization programs where high-voltage ceramic and tantalum constructions face REACH-mandated electrode reformulation.
- Resistors:Military-grade thin-film and wirewound constructions qualified to MIL-PRF standards anchor avionics signal conditioning. British and Polish defense ministries drive procurement for fifth-generation fighter integration programs requiring failure rates below 0.001% per 1,000 hours.
- Inductors:Ferrite and iron-core constructions filter electromagnetic interference in power distribution networks.
- Filters:Electromagnetic compatibility components command concentrated margins as NATO platforms tighten emission specifications.
Mature deployment sits with resistors sustaining decades-long military aircraft service obligations. Newer deployment is concentrated in capacitors serving satellite constellation expansion and phased array radar programs.
Application:
Radar and missile systems are absorbing premium component allocations as European defense ministries accelerate transmitter modernization and precision strike capabilities.
- Radar Systems:Phased array transmitters operating above 40 GHz demand high-voltage capacitors with nanocomposite dielectric materials. Thales and BAE Systems qualification programs in France and the United Kingdom are compressing form factors by 30% compared to conventional ceramic constructions.
- Missile Systems:Guidance and fuzing electronics require extreme temperature stability from tantalum and ceramic capacitors. German and Italian procurement channels prioritize miniaturized surface-mount components for loitering munitions and hypersonic platforms.
- Avionics:Flight-critical systems deploy passive components where active semiconductors cannot survive radiation or thermal stress.
- Communication Systems:Electromagnetic interference filtering secures signal integrity across encrypted NATO datalinks.
Established platforms sustain avionics demand. Steepest expansion trajectory belongs to radar systems as European primes qualify suppliers for next-generation fighter integration.
Technology:
Mounting technology selection reflects a platform age divide, with surface mount dominating new avionics while thru-hole persists where service lives exceed 40 years.
- Surface Mount Technology:Miniaturized chip resistors, multilayer ceramic capacitors, and compact inductors populate modern European fighter and drone avionics. Airbus Defence and Space programs in France and Germany specify these formats for weight-critical satellite payloads.
- Thru-Hole Technology:Axial and radial leaded components maintain production lines for British Tornado and German Tornado fleet sustainment. Defense contractors face dual-capacity burdens as legacy platform support obligations conflict with surface mount expansion.
- Hybrid Technology:Mixed mounting approaches bridge upgrade pathways for mid-life avionics refresh programs.
- Passive RFID:Identification and tracking applications expand in supply chain asset management for NATO logistics.
Volume concentration rests with thru-hole formats sustaining legacy fleets. Technology transition is accelerating in surface mount as new platform procurement outpaces replacement cycles.
End User:
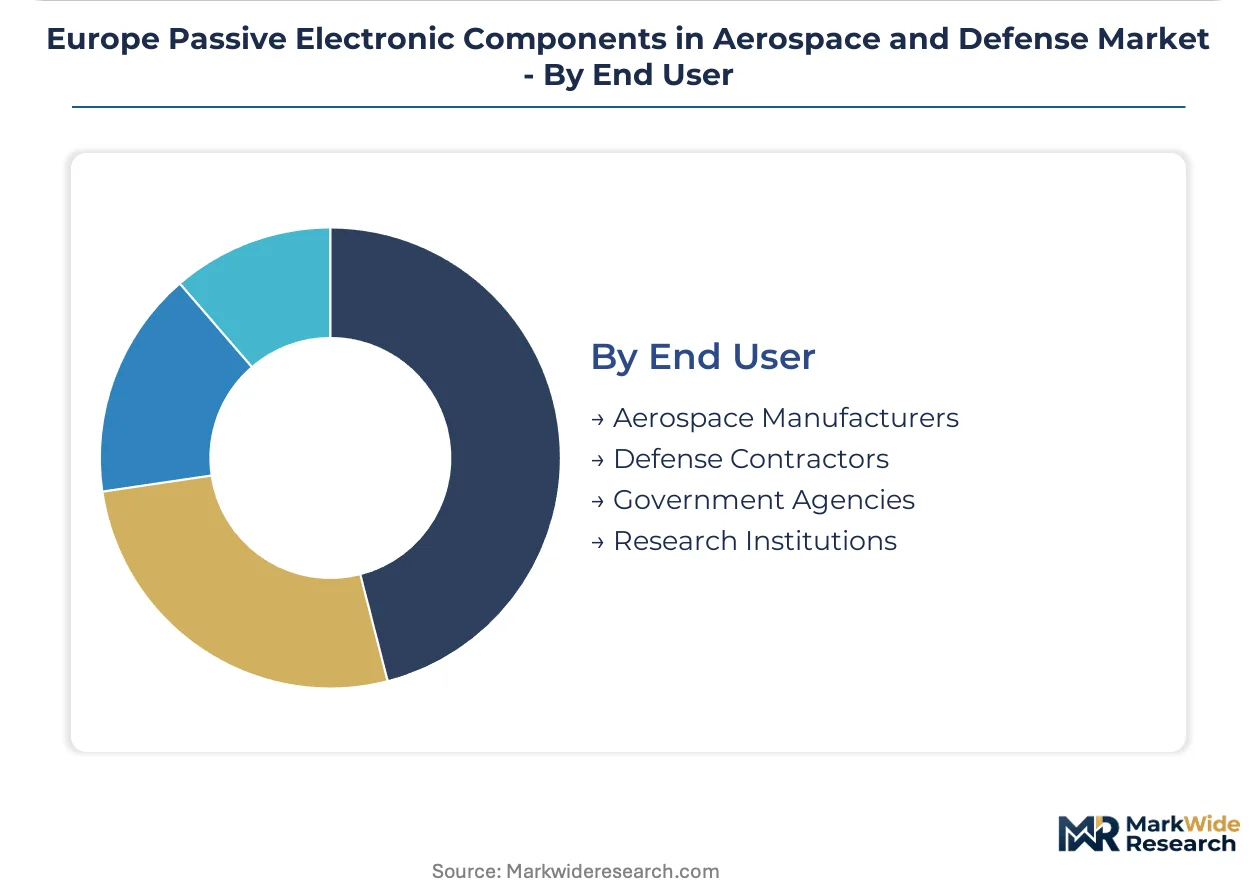
Defense contractors and aerospace manufacturers split procurement authority, with government agencies increasingly mandating domestic content thresholds.
- Defense Contractors:Thales, BAE Systems, and Leonardo integrate passive components into national platform programs. French and British localization requirements compel these primes to qualify supplier production cells within each jurisdiction, fragmenting traditional pan-European relationships.
- Aerospace Manufacturers:Airbus Defence and Space anchors European satellite and military transport demand. REACH and EU Green Deal compliance frameworks force reformulation of electrode materials and termination finishes across their supplier base.
- Government Agencies:Defense ministries in Germany, France, and the United Kingdom establish procurement specifications and domestic content mandates.
- Research Institutions:European Space Agency and national aerospace laboratories qualify advanced dielectric formulations for future mission profiles.
Procurement authority concentrates with defense contractors executing national platform programs. Emerging influence is shifting toward government agencies as localization mandates and dual-use export harmonization reshape supplier eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement localization mandates are concentrating passive component demand in specialized economic zones across France, Germany, and the United Kingdom. National content thresholds established by EASA and individual defense ministries are reshaping supplier qualification pathways.
France
Airbus Defence and Space anchors capacitor procurement for satellite constellations and military transport platforms from its Toulouse headquarters. ANSM and DGAC compliance frameworks enforce REACH-mandated electrode reformulation across the supplier base. The Île-de-France aerospace cluster around Paris-Saclay hosts Thales qualification programs for phased array radar systems.
Germany
Diehl Defence and Rheinmetall Electronics drive demand for high-voltage ceramic capacitors in missile guidance and radar modernization programs. KBA and BAAINBw procurement specifications require domestic production cells for critical passive components. The Bavarian aerospace corridor between Munich and Augsburg concentrates filter manufacturing for electromagnetic compatibility applications.
United Kingdom
BAE Systems and Leonardo UK sustain resistor procurement for Tornado fleet avionics and fifth-generation fighter integration. UK Ministry of Defence localization mandates compel supplier establishment of qualified production facilities within British jurisdiction. The South East England defense technology belt around Farnborough and Basingstoke hosts electromagnetic interference engineering specialists.
Italy
Leonardo Electronics and Avio Aero generate demand for tantalum capacitors in precision strike systems and satellite propulsion controls. ANAC and Ministry of Defence dual-use export frameworks shape component qualification for NATO interoperability. The Lombardy aerospace district around Milan and Bergamo concentrates inductor manufacturing for power distribution networks.
Poland
Polish Armaments Group and WB Electronics are establishing domestic assembly capabilities for military-grade resistors under NATO supply chain diversification directives. Polish Ministry of National Defence procurement localization requirements accelerate qualified supplier onboarding. The Central Industrial Region around Radom and Kielce hosts emerging filter production for unmanned aerial platforms.
Europe Passive Electronic Components in Aerospace and Defense Market Competitive Landscape
Top-tier vendors anchor premium qualification tiers, while mid-scale specialists occupy niche technology segments. The European passive component supply base exhibits moderate consolidation around dielectric material expertise and MIL-PRF certification holdings. Three strategic archetypes dominate: Japanese conglomerates with ceramic formulation depth, American specialists with military-grade resistor portfolios, and European heritage manufacturers with legacy platform support obligations. Competitive positioning hinges on geographic production cell establishment and REACH-compliant material reformulation speed.
Within the dielectric specialization tier, TDK Corporation and KEMET Corporation exemplify contrasting approaches to European defense market access. TDK Corporation occupies a position anchored in high-voltage capacitor supply for radar transmitters, while KEMET Corporation represents the tantalum and ceramic capacitor archetype for extreme temperature stability applications. Vishay Intertechnology Inc. sits within the military-grade resistor qualification tier, anchoring MIL-PRF standard compliance across avionics signal conditioning segments.
| Leading Market Players |
|---|
| KEMET Corporation |
| TDK Corporation |
| Vishay Intertechnology Inc. |
| Murata Manufacturing Co. Ltd |
| AVX Corporation |
| Panasonic Corporation |
| Taiyo Yuden Co., Ltd. |
| Cornell Dubilier Electronics Inc. |
| Bourns Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal material compliance frameworks gate qualified supply access and premium-tier pricing power across European aerospace programs, compelling capacitor manufacturers to absorb reformulation costs while defense ministries accelerate procurement of REACH-certified components for satellite and radar platforms.
Pricing Analysis
Short lead-time premiums command substantial markups in high-reliability capacitor procurement, while spot inventory of military-grade resistors trades at discounts due to qualification surplus in British and Polish defense channels. Three-tier pricing structure across space-grade, military-specification, and industrial-commercial levels separates components by MIL-PRF certification tier and dielectric material grade. Cost compression in standard-grade ceramic capacitors is intensifying because Eastern European localization mandates are fragmenting volume consolidation. Tier 1 primes such as Airbus Defence and Space exhibit lowest price sensitivity due to mission-critical failure rate requirements, while emerging Polish and Romanian assemblers drive hardest bargaining on resistor and filter categories.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the United Kingdom operate hub-and-spoke patterns feeding qualified production cells established under national content mandates. Tantalum ore supply draws from conflict-affected Central African regions, while rare-earth elements for high-permeability inductor cores rest on Chinese and Vietnamese refining capacity. Single-source vulnerability concentrates in space-grade dielectric formulations qualified exclusively through Japanese ceramic expertise. Distribution runs through defense contractor consignment warehouses before final integration at Thales, BAE Systems, and Leonardo assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended MIL-PRF qualification cycles prop pricing power for incumbent suppliers, as 18-36 month validation periods prevent rapid capacity expansion and lock buyer relationships.
For Market Incumbents: Extend qualified production cell footprints into Poland and Romania before NATO localization mandates harden, while accelerating copper-nickel-tin alloy substitution to preempt REACH substance restrictions. Backward integration into rare-earth magnet powder processing reduces Chinese supply exposure. Certification investment in dual-use export harmonization pathways preserves cross-border sales elasticity. For New Entrants and Emerging Players: Begin with filter design services for fifth-generation fighter electromagnetic compatibility programs, where aging specialist concentration in France and Germany creates immediate talent arbitrage. Poland's Central Industrial Region offers the most penetrable geography for military-grade resistor assembly partnerships. Go-to-market leverage rests on ANAC and Ministry of Defence dual-use qualification brokerage rather than component manufacturing scale. For Investors and Strategic Acquirers: ECHA substance-of-very-high-concern listing announcements are the leading indicator that capacitor manufacturer valuations will bifurcate between reformulation-capable and legacy-dependent suppliers. Long-term viability favors vertically integrated dielectric material specialists with captive ceramic powder supply. Acquisition targets should exhibit MIL-PRF certification holdings plus established production cells in at least two of France, Germany, and the United Kingdom.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | Copper-nickel-tin alloy substitutions preserve Airbus Defence and Space supplier eligibility under tightening ECHA listings. |
| Domestic Production Cell Establishment | Qualified manufacturing in Poland satisfies NATO supply chain diversification directives for military-grade resistors. |
| Dual-Use Export Harmonization | Streamlined EU-NATO qualification pathways reduce redundant certification costs for components serving civilian and defense applications. |
| Nanocomposite Dielectric Development | Thales and BAE Systems qualification programs for phased array radar above 40 GHz compress form factors by thirty percent. |
| Blockchain Material Provenance | Full supply chain traceability for rare-earth elements satisfies EU Green Deal mandates across European Space Agency programs. |
Research Methodology
Document review covered ECHA substance restriction filings, BAAINBw procurement specifications, and ANAC dual-use export frameworks, complemented by interviews with component qualification engineers at Thales and BAE Systems, electromagnetic compatibility specialists in the South East England defense belt, and supply chain directors at Polish Armaments Group. Secondary validation drew from ESA mission qualification databases, REACH compliance disclosure registries, and NATO standardization office publications. Bottom-up demand modeling across radar, missile, avionics, and communication system applications triangulated against top-down defense budget allocation analysis.
Segment-level value outputs across capacitors, resistors, inductors, and filters were derived through dielectric material cost buildup and qualification premium estimation over the projection horizon. The analytical framework incorporated mounting technology splits between surface mount and thru-hole formats, end-user concentration across defense contractors and aerospace manufacturers, and geographic production cell distribution patterns. CAGRs were computed from defense ministry procurement acceleration indices and satellite constellation deployment schedules.
Underlying measurement precision varies by segment; space-grade capacitor categories carry tighter precision than legacy thru-hole resistor sustainment markets due to concentrated prime qualification data availability. Forecasts reflect assumptions on REACH listing expansion timelines and NATO localization mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Thrust Vector Control Market