
 Robot for Public Service Market | 2026-2036
Robot for Public Service Market Size, Share, and Industry Trends Forecast 2026-2036
Robot for Public Service Market Insights
Capital-intensity divergence between sensor-fusion specialists and hardware-assemblers is unwinding competitive hierarchies in public service robotics. Boston Dynamics leverages advanced locomotion engineering to dominate emergency response deployments. SoftBank Robotics anchors its position through persistent channel control in educational and municipal settings. DJI sustains manufacturing scale advantages that extend across surveillance and delivery product lines.
Robots for public service integrate autonomous mobility platforms, multi-sensor arrays, and task-specific end effectors to execute municipal functions without continuous human oversight. These systems typically operate on lithium-ion powertrains with operational spans of eight to twelve hours, communicating through encrypted municipal networks to centralized command interfaces. Surveillance robots command the largest current revenue pool, while delivery robots represent the fastest-expanding segment as last-mile logistics contracts proliferate. Cleaning robots occupy a mature, replacement-driven position in facility maintenance budgets, whereas maintenance robots with robotic arms capture premium pricing in infrastructure inspection roles.
The EU AI Act imposes conformity requirements on autonomous decision-making in public spaces, while FDA-equivalent pathways through national health regulators govern hospital robot deployments. Japan's METI standards for service robot safety create additional certification layers for vendors targeting municipal procurement. Stakeholders must monitor how procurement rules evolve around liability allocation between robot operators and technology suppliers.
Market Dynamics
The EU AI Act is forcing municipal procurement offices to requalify autonomous navigation systems ahead of deployment deadlines, compressing vendor certification timelines and redrawing competitive hierarchies around compliance infrastructure.
Growth Catalysts
- EU AI Act Conformity Mandates:Municipalities across Germany, France, and Italy must source only certified autonomous systems for public space deployment, creating immediate replacement demand for legacy surveillance platforms.
- Tokyo Metropolitan Aging Infrastructure:Japan's capital requires automated inspection robots for tunnel maintenance and bridge monitoring as workforce availability contracts.
- LiDAR-Sensor Fusion Maturation:Cost reductions in solid-state ranging arrays enable mid-tier vendors to field navigation systems previously restricted to defense contractors.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production clusters in China's Fujian and Hunan provinces expose European and North American robot assemblers to input volatility and export control friction.
- CE Marking Complexity:The Machinery Directive and emerging AI Act overlap creates dual certification pathways that extend time-to-revenue by eight to fourteen months for autonomous public-facing units.
- Human Security Personnel Cost Arbitrage:Municipal budget constraints in Southern European markets sustain reliance on contracted guard services rather than capital-intensive robot procurement.
Strategic Opportunities
- Seoul Smart City Infrastructure:The Korean capital's integrated command-and-control network offers plug-and-play deployment environments for multi-robot coordination systems.
- Hospital Logistics Convergence:FDA-equivalent pathways through national health regulators create cross-certification potential between municipal emergency response and clinical delivery robot platforms.
- Subscription-Based Fleet Management:Procurement offices in Dutch and Belgian municipalities are piloting robot-as-a-service contracts that transfer obsolescence risk from capital budgets to vendor balance sheets.
Industry Challenges
- Autonomy Software Talent Scarcity:Robotics firms compete with autonomous vehicle developers for perception engineers and SLAM specialists, inflating compensation costs.
- Legacy Municipal Network Integration:Encrypted command interfaces must interface with decades-old SCADA and emergency dispatch architectures, requiring custom middleware development.
- Product Liability Allocation:Ambiguity in operator-versus-manufacturer responsibility for autonomous decision outcomes delays insurance underwriting and procurement sign-off.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot for Public Service Market |
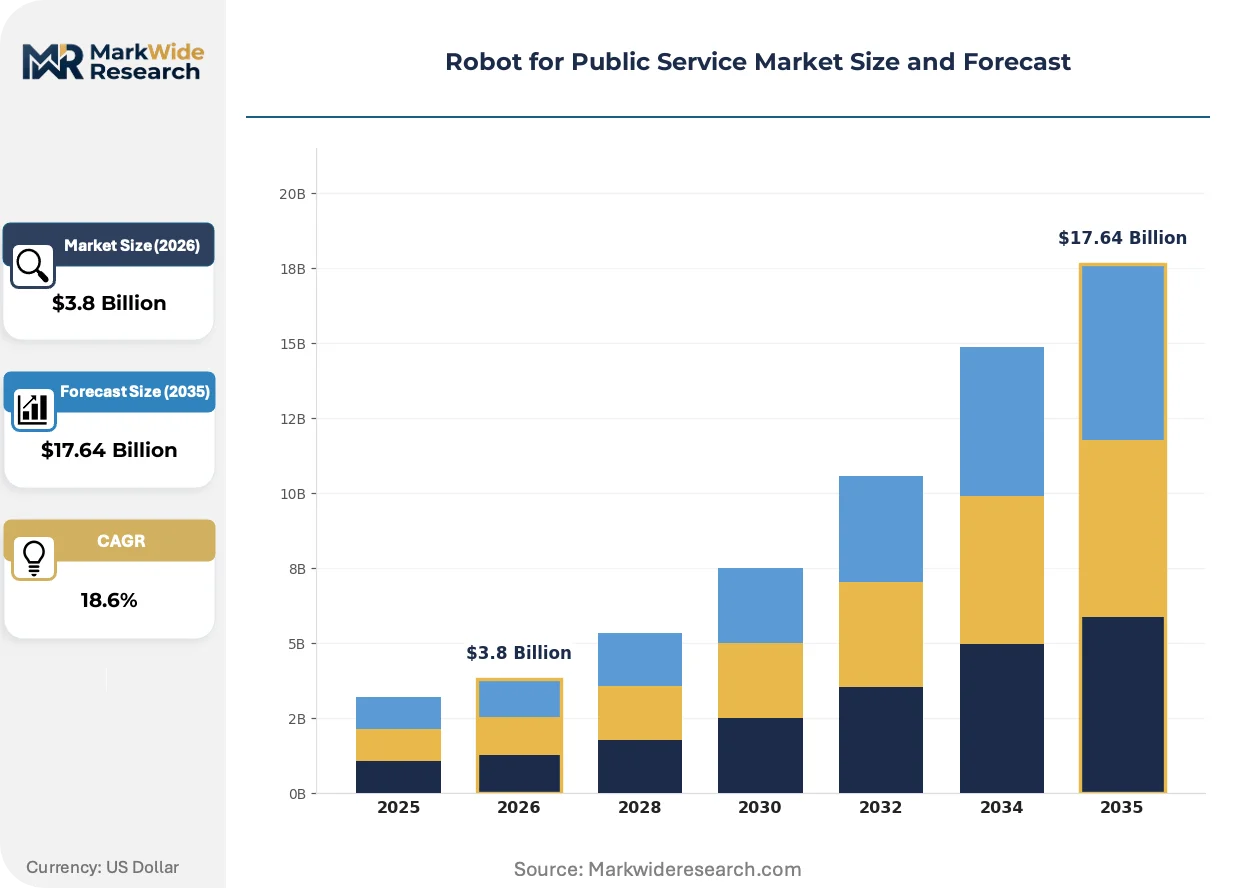
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Robots, Delivery Robots, Maintenance Robots, Cleaning Robots End User: Municipalities, Educational Institutions, Hospitals, Parks Application: Public Safety, Waste Management, Facility Maintenance, Emergency Response Technology: AI Navigation, Autonomous Driving, Sensor Fusion, Robotic Arms |
| Companies Covered | Boston Dynamics, SoftBank Robotics Group, iRobot Corporation, Intuitive Surgical Operations, DJI, ABB, KUKA AG, Blue Ocean Robotics, Daifuku Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot for Public Service Market Trends and Innovations
Edge computing architectures are migrating perception processing from cloud relays to onboard units, reducing latency for collision-avoidance decisions in dense urban environments.
Solid-state LiDAR arrays with MEMS beam-steering are supplanting mechanical spinning units in surveillance and delivery robot platforms. Seoul's metropolitan procurement office has mandated solid-state configurations for all new fleet acquisitions starting in 2026. This transition compresses unit costs while eliminating the primary failure mode that grounded first-generation municipal deployments.
The EU AI Act's risk-classification framework imposes conformity assessment requirements on autonomous decision-making in public spaces. High-risk system providers must maintain technical documentation and human oversight protocols that extend engineering overhead by twenty to thirty percent. Vendors targeting German municipal markets are restructuring product architectures to isolate decision logic for auditability.
Leasing structures now dominate Dutch and Belgian municipal procurement for cleaning and surveillance robot fleets. Capital-constrained cities prefer operational expenditure treatment over balance-sheet ownership. This preference is most visible in Rotterdam and Antwerp, where multi-year service contracts with uptime guarantees have displaced traditional equipment purchasing.
Robot for Public Service Market Segmentation
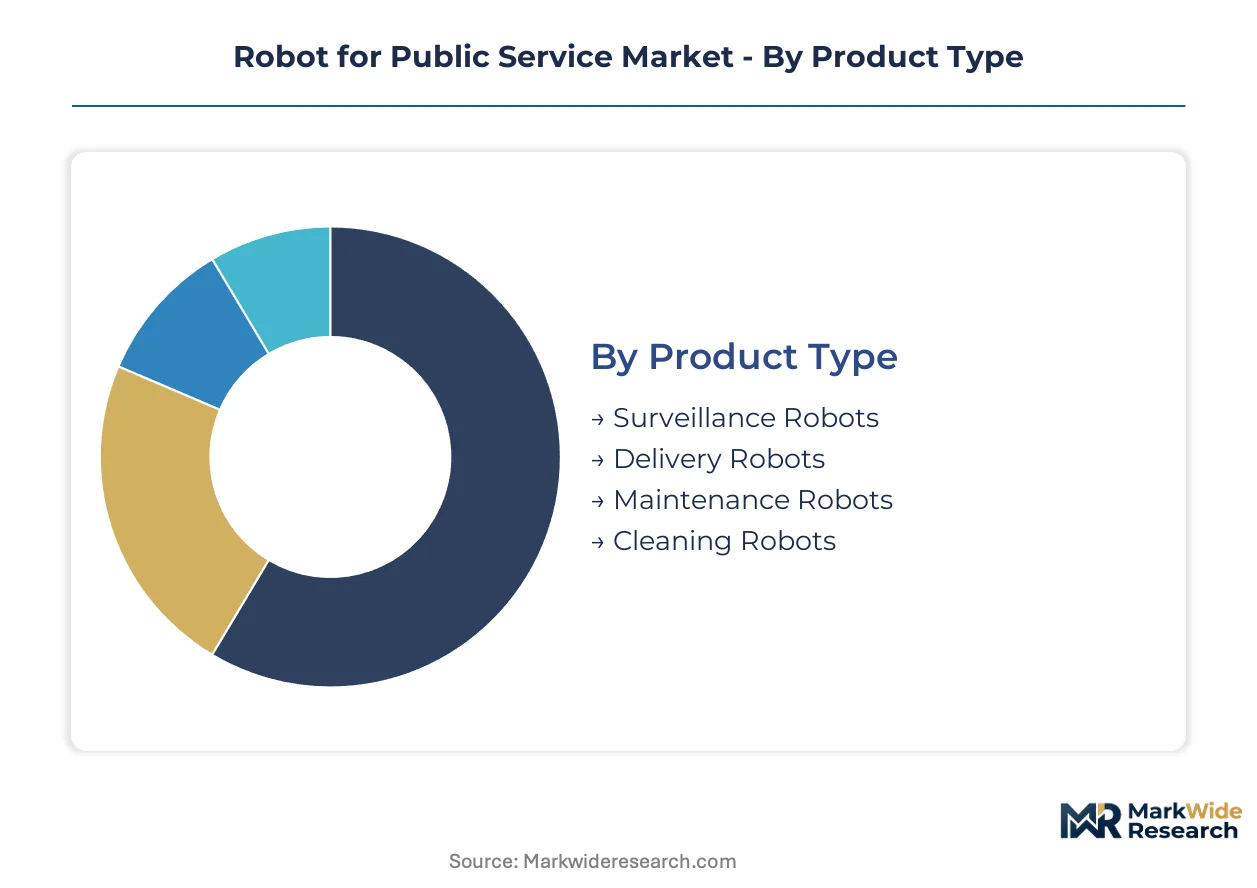
Segmentation reveals how procurement priorities diverge across municipal budgets and operational mandates. Understanding these fault lines exposes where substitution pressure from legacy systems or competing technologies threatens incumbent robot categories.
Product Type:
Substitution pressure from contracted human services and legacy equipment varies sharply across product categories, with some segments facing immediate displacement risk while others enjoy protected demand corridors.
- Surveillance Robots:AI-guided platforms integrate thermal imaging and acoustic sensors for crowd monitoring in German municipal deployments. Demand concentrates in Tokyo and Seoul where aging security workforces and dense urban corridors drive procurement. The EU AI Act conformity requirements compress vendor timelines and favor established sensor-fusion specialists.
- Delivery Robots:Last-mile autonomous platforms operate on encrypted municipal networks with eight-to-twelve-hour lithium-ion endurance. Rotterdam and Antwerp procurement offices favor robot-as-a-service contracts that transfer obsolescence risk to vendors. Solid-state LiDAR cost reductions enable mid-tier market entry.
- Maintenance Robots:Tunnel inspection and bridge monitoring units with robotic arms capture premium pricing in Tokyo Metropolitan infrastructure budgets.
- Cleaning Robots:Mature replacement-driven position in Dutch and Belgian facility maintenance budgets with uptime-guarantee leasing structures.
Surveillance robots anchor the volume base while delivery robots gain share at the steepest rate.
End User:
Procurement authority fragmentation across budget types shapes robot deployment velocity, with capital expenditure constraints discriminating against ownership models in favor of operational expenditure treatment.
- Municipalities:City procurement offices in Germany, France, and Italy must source only EU AI Act certified autonomous systems for public space deployment. Rotterdam and Antwerp pilot subscription-based fleet management for cleaning and surveillance units.
- Hospitals:Clinical delivery platforms face FDA-equivalent pathways through national health regulators, creating cross-certification potential with municipal emergency response systems.
- Educational Institutions:SoftBank Robotics maintains persistent channel control in school and university settings through established distribution relationships.
- Parks:Open-space surveillance and maintenance applications in Seoul's integrated command-and-control network enable plug-and-play multi-robot coordination.
Municipalities dominate current procurement volume while hospitals represent the most rapid certification expansion pathway.
Application:
Task criticality determines autonomy tolerance, with life-safety applications demanding higher engineering overhead and documentation burdens under emerging regulatory frameworks.
- Public Safety:Crowd management and threat detection systems operate under strict EU AI Act high-risk classification requirements with twenty-to-thirty percent engineering overhead increases for auditability protocols.
- Emergency Response:Boston Dynamics leverages advanced locomotion engineering to dominate disaster relief and hazardous environment deployments.
- Facility Maintenance:Cleaning and infrastructure inspection robots integrate with decades-old SCADA architectures requiring custom middleware development.
- Waste Management:Autonomous collection platforms face human security personnel cost arbitrage in Southern European municipal budget constraints.
Public safety commands the largest current revenue pool while emergency response climbs the fastest on defense and disaster preparedness spending.
Technology:
Component maturation curves are unwinding competitive hierarchies, with solid-state sensor advances democratizing navigation capabilities previously restricted to defense contractors.
- Sensor Fusion:Solid-state LiDAR arrays with MEMS beam-steering supplant mechanical spinning units as Seoul mandates solid-state configurations for all fleet acquisitions. Cost compression eliminates primary failure modes that grounded first-generation deployments.
- AI Navigation:Edge computing architectures migrate perception processing from cloud relays to onboard units, reducing collision-avoidance latency in dense urban environments.
- Autonomous Driving:SLAM specialist scarcity inflates compensation costs as robotics firms compete with autonomous vehicle developers for perception engineering talent.
- Robotic Arms:End effector precision requirements for infrastructure inspection capture premium pricing in Tokyo tunnel maintenance and bridge monitoring contracts.
Sensor fusion underpins current platform differentiation while AI navigation expands most quickly on edge computing cost reductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European municipalities prioritize regulatory compliance in procurement specifications, while East Asian urban centers emphasize fleet scale and multi-robot coordination. North American demand clusters on emergency response and defense-adjacent applications.
Germany
Municipal procurement offices in Berlin, Munich, and Hamburg must source only EU AI Act certified autonomous systems for public space deployment. The Machinery Directive overlap with emerging AI Act requirements creates dual certification pathways that extend vendor timelines. Bavaria's industrial corridor hosts testing facilities for tunnel inspection robots.
Japan
Tokyo Metropolitan infrastructure budgets drive automated inspection robot demand for aging tunnel and bridge maintenance as workforce availability contracts. METI standards for service robot safety create additional certification layers for municipal procurement. Osaka-Kansai corridor concentrates manufacturing partnerships for solid-state LiDAR integration.
South Korea
Seoul's integrated command-and-control network offers plug-and-play deployment environments for multi-robot coordination systems. The metropolitan procurement office mandates solid-state LiDAR configurations for all fleet acquisitions. Busan-Ulsan industrial zone supplies battery cell components to regional robot assemblers.
United States
Emergency response and disaster relief applications dominate municipal and federal procurement, with FAA regulations governing aerial platform deployments in urban airspace. Boston Dynamics anchors defense-adjacent positioning through advanced locomotion engineering. Pittsburgh and Boston metropolitan areas concentrate SLAM specialist talent pools.
Netherlands
Rotterdam and Antwerp procurement offices pilot robot-as-a-service contracts that transfer obsolescence risk from capital budgets to vendor balance sheets. CE marking complexity under Machinery Directive implementation favors established sensor-fusion specialists. Randstad urban corridor leads subscription-based fleet management adoption in facility maintenance.
Robot for Public Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in public service robotics. Boston Dynamics leverages advanced locomotion engineering to dominate emergency response deployments. SoftBank Robotics anchors its position through persistent channel control in educational and municipal settings. DJI sustains manufacturing scale advantages that extend across surveillance and delivery product lines. Competitive moves concentrate on compliance infrastructure investment and subscription-based fleet management restructuring.
Within the integrated locomotion tier, Boston Dynamics exemplifies defense-adjacent positioning through quadruped and humanoid platforms. SoftBank Robotics occupies a position in educational and municipal channel control. DJI represents manufacturing scale archetypes extending from consumer drones into municipal surveillance and delivery applications. These three anchors illustrate how engineering specialization, channel persistence, and production scale create defensible positioning against mid-tier sensor-fusion entrants.
| Leading Market Players |
|---|
| Boston Dynamics |
| SoftBank Robotics Group |
| iRobot Corporation |
| Intuitive Surgical Operations |
| DJI |
| ABB |
| KUKA AG |
| Blue Ocean Robotics |
| Daifuku Co. |
| Others |
Pricing and Supply Chain Analysis
Solid-state LiDAR substitution for mechanical spinning units simultaneously concentrates sensor sourcing in China's Fujian and Hunan provinces while compressing navigation system pricing tiers across municipal procurement offices. This input transition redistributes value capture from legacy hardware assemblers toward software-integrated vendors with direct foundry relationships.
Pricing Analysis
After-sales service contracts and uptime-guarantee subscriptions drive lifetime value for robot-as-a-service providers in Rotterdam and Antwerp municipal fleets. Three-tier pricing structure across premium, standard, and economy levels reflects EU AI Act certification grade and sensor-fusion complexity. Cost compression in mid-tier navigation systems intensifies because solid-state LiDAR cost curves democratize previously defense-restricted capabilities. Municipal procurement offices exhibit highest price sensitivity, whereas hospital logistics platforms with FDA-equivalent pathways tolerate premium positioning.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells dominates inventory strategy for European robot assemblers exposed to export control friction from China's Fujian and Hunan production clusters. Battery cell production draws from concentrated Chinese provinces, South Korean cathode processing, and Japanese electrolyte formulation. Single-source vulnerability in solid-state LiDAR MEMS foundries threatens multi-robot coordination deployments in Seoul. Distribution runs through municipal procurement offices with encrypted network integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Seoul's integrated command-and-control network demonstrates how multi-robot coordination systems create winner-take-most dynamics for vendors with plug-and-play interoperability.
For Market Incumbents: Compound channel control in educational and municipal settings through subscription-based fleet management restructuring that transfers obsolescence risk to vendor balance sheets. Deepen backward integration into solid-state LiDAR foundries to defend margin position against mid-tier sensor-fusion entrants exploiting cost compression. Prioritize EU AI Act compliance infrastructure investment ahead of German deployment deadlines. For New Entrants and Emerging Players: Lead with hospital logistics convergence as the most penetrable segment, exploiting cross-certification potential between municipal emergency response and clinical delivery platforms. Target Southern European municipalities with waste management applications where human security personnel cost arbitrage sustains reliance on contracted services. Deploy robot-as-a-service contracts to bypass capital expenditure constraints in Dutch and Belgian procurement offices. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor-fusion specialists holding EU AI Act conformity infrastructure and established municipal channel relationships. Five-to-ten year viability hinges on sustained procurement shift from ownership to operational expenditure treatment. Watch Seoul metropolitan procurement mandates as the signal indicating solid-state LiDAR configuration standardization crossing threshold to regional adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure | Technical documentation and human oversight protocols extend engineering overhead for German municipal certification. |
| Solid-State LiDAR Integration | MEMS beam-steering configurations eliminate primary failure modes that grounded first-generation municipal deployments. |
| Robot-as-a-Service Contracting | Rotterdam and Antwerp procurement offices transfer obsolescence risk from capital budgets to vendor balance sheets. |
| Multi-Robot Coordination Systems | Seoul's integrated command-and-control network enables plug-and-play deployment environments for fleet-scale vendors. |
| Hospital Logistics Cross-Certification | FDA-equivalent pathways through national health regulators create clinical-municipal platform convergence opportunities. |
Research Methodology
Desk research of EU regulatory filings, METI safety standards documentation, and municipal procurement databases preceded structured interviews with robotics engineering directors, municipal procurement officers, SLAM software specialists, and hospital biomedical engineering heads. Primary fieldwork combined with secondary validation from SEC 10-K filings, patent landscape analysis, and foundry capacity disclosures. Bottom-up unit economics triangulated against top-down market sizing across sensor fusion, AI navigation, and autonomous driving technology segments.
Variance decomposition across product type, end user, application, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by procurement budget elasticity and regulatory compliance timelines. Solid-state LiDAR cost trajectories and EU AI Act implementation schedules served as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in EU AI Act, METI, and FDA-equivalent regimes; material policy shifts would require re-modeling of vendor certification timelines and municipal replacement demand. Revision becomes warranted when lithium-ion supply concentration or autonomy software talent scarcity crosses thresholds that compress vendor margins beyond sustainable levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
South America AUV Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Industrial Robotics Market