
 Singapore Cloud Robotics Market | 2026-2036
Singapore Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Cloud Robotics Market Insights
Edge-native silicon is realigning compute economics for cloud robotics deployments. Gaussian Robotics leverages proprietary navigation stacks to sustain fleet management margins in commercial cleaning applications. Movel AI Pte Ltd anchors software-defined autonomy for third-party hardware integrators. LionsBot competes through manufacturing scale in local assembly of service-class units.
Singapore Cloud Robotics denotes distributed robotic systems that offload computation, mapping, and machine-learning inference to remote cloud infrastructure via sub-10ms latency links, primarily enabling real-time coordination across multi-robot fleets in dynamic environments. Industrial robots retain the dominant installed base, though autonomous mobile robots represent the fastest-expanding product category as logistics operators retrofit brownfield warehouses. Machine learning commands the largest technology spend, while sensor fusion captures emerging interest from healthcare providers deploying patient-monitoring mobile platforms.
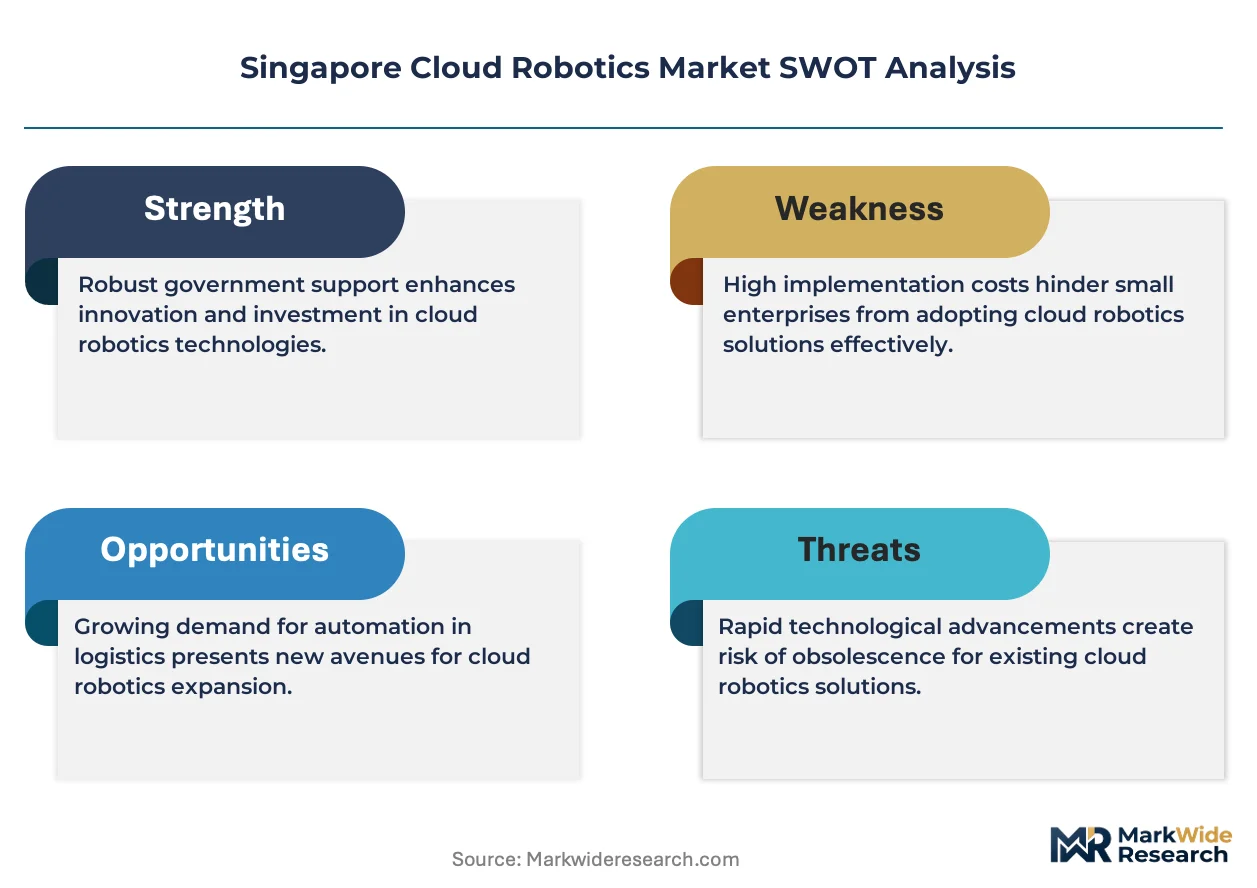
The Infocomm Media Development Authority shapes demand through 5G corridor certifications and robotics sandbox grants. The Personal Data Protection Commission constrains cross-border telemetry flows, forcing edge-resident processing architectures for sensitive operational data. Stakeholders must weigh localization requirements against cloud economics when architecting fleet control systems.
Market Dynamics
The Personal Data Protection Commission's cross-border data restrictions are forcing edge-resident architectures for fleet control systems, fundamentally reshaping how operators balance cloud economics against localization mandates.
Growth Catalysts
- IMDA 5G corridor certifications:Sub-10ms latency links enable real-time multi-robot coordination across logistics hubs and smart port facilities.
- Logistics brownfield retrofits:Warehouse operators deploy autonomous mobile robots to automate existing infrastructure without greenfield construction.
- Healthcare sensor fusion:Patient-monitoring mobile platforms drive emerging technology spend from medical providers.
Market Restraints
- Edge silicon cost volatility:Proprietary navigation stacks and custom compute modules inflate unit economics for fleet operators.
- PDPC localization mandates:Cross-border telemetry restrictions fragment cloud architectures and duplicate infrastructure investment.
- Technical limitation in brownfield mapping:Dynamic warehouse environments degrade SLAM accuracy without continuous cloud updates.
Strategic Opportunities
- Jurong Innovation District concentration:Advanced manufacturing clusters create captive demand for service-class robot assembly.
- Machine learning inference convergence:Federated learning across edge nodes reduces bandwidth costs while preserving fleet intelligence.
- IMDA robotics sandbox grants:Subsidized pilot programs lower adoption barriers for mid-scale logistics operators.
Industry Challenges
- Cloud-edge orchestration talent scarcity:Fleet management platforms require specialists fluent in distributed systems and robotics middleware.
- Legacy warehouse management integration:Brownfield deployments demand custom API bridges to incumbent ERP and WMS stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Cloud Robotics Market |
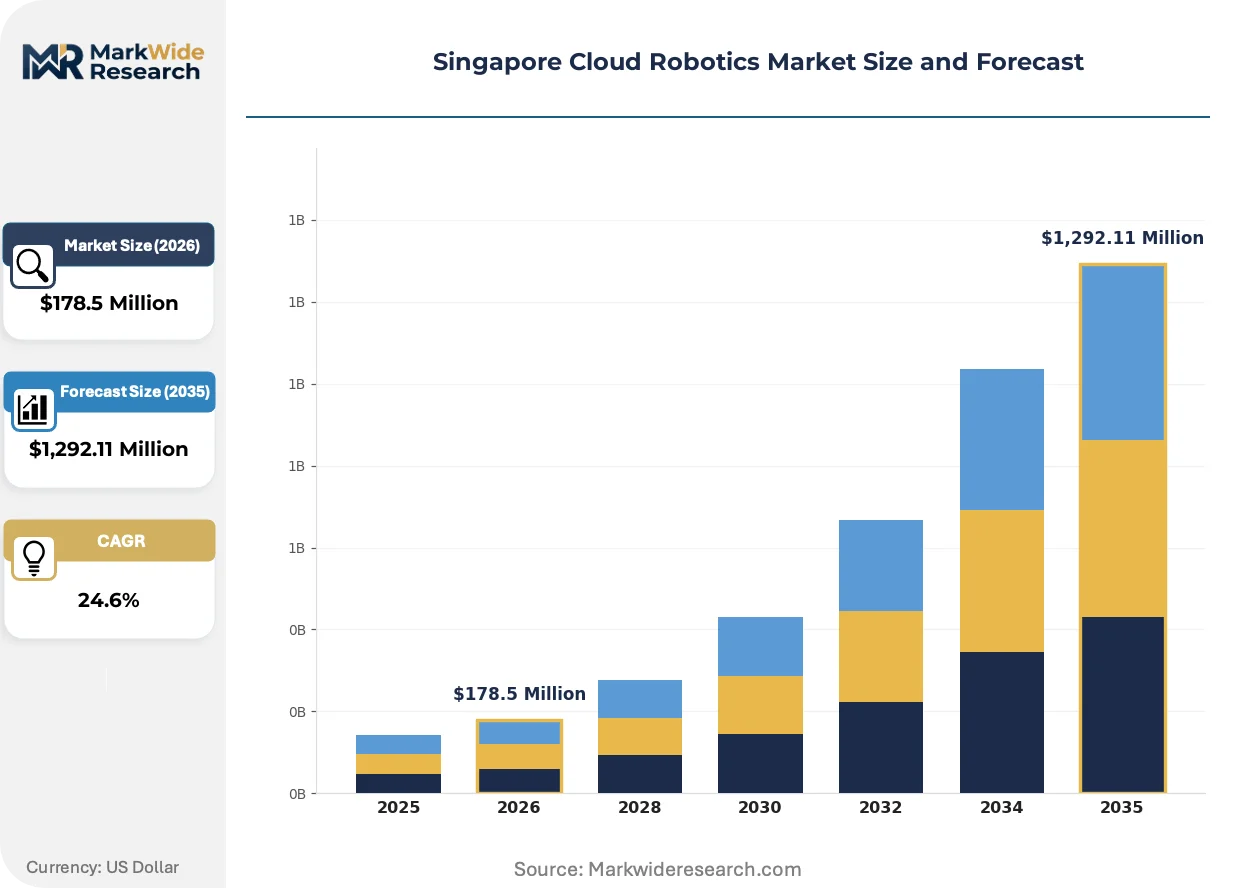
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $1,292.11 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots Technology: Machine Learning, Computer Vision, Natural Language Processing, Sensor Fusion Application: Warehouse Automation, Agriculture, Healthcare, Retail End User: Manufacturing, Logistics, Food & Beverage, Healthcare Providers |
| Companies Covered | Gaussian Robotics, Fabrica AI, Syrius Robotics, CTRL Robotics pte ltd, Movel AI Pte Ltd, LionsBot, Augmentus, Botsync Pte Ltd, FJ Dynamics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Cloud Robotics Market Trends and Innovations
Compute architectures are bifurcating between latency-sensitive edge inference and training-heavy cloud workloads, with navigation autonomy emerging as the decisive battleground for fleet economics.
Edge-native silicon with dedicated neural processing units is electrifying autonomous navigation stacks for commercial cleaning and logistics applications. Facility operators in Singapore's airport and seaport zones deploy these systems at pilot-to-fleet scale within eighteen-month windows. The shift compresses cloud dependency for real-time path planning while preserving centralized fleet optimization.
IMDA's 5G corridor certification framework mandates latency benchmarks that effectively standardize connectivity specifications for multi-robot deployments. Industrial users must now architect systems around guaranteed sub-10ms links rather than best-effort WiFi. Logistics operators in Tuas Port and Changi Airfreight Centre face the steepest compliance curves given fleet density requirements.
Buying patterns among warehouse operators now favor robot-as-a-service contracts with uptime guarantees over capital procurement. Third-party logistics providers at Pandan Logistics Hub and Penjuru Lane facilities displace traditional equipment financing with operational expenditure models. This preference shift concentrates vendor selection power among fleet management platforms capable of absorbing maintenance risk.
Singapore Cloud Robotics Market Segmentation
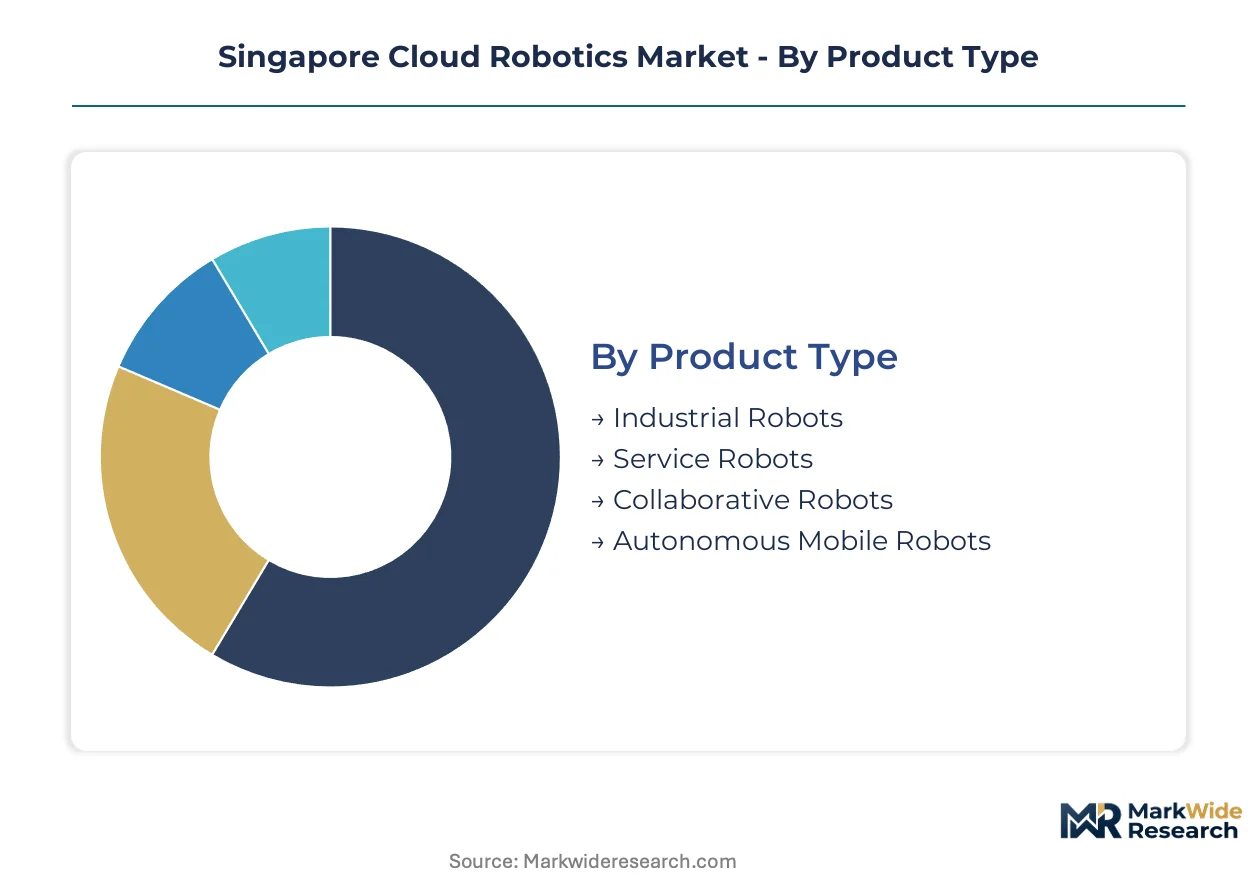
Cloud robotics deployments in Singapore fragment across four distinct dimensions, each revealing how operators balance latency requirements against computational economics. Understanding these segment boundaries clarifies where infrastructure investment concentrates and which technology stacks command premium positioning.
Product Type:
Supply concentration in local assembly favors service-class units, while logistics demand pulls autonomous mobile platforms through brownfield retrofit cycles.
- Industrial Robots:Fixed-base articulated systems dominate legacy manufacturing footprints with high payload precision. Demand concentrates in Jurong Innovation District advanced manufacturing clusters where IMDA robotics sandbox grants subsidize fleet modernization.
- Autonomous Mobile Robots:Wheeled platforms with cloud-connected navigation stacks enable dynamic path planning across warehouse floors. Logistics operators at Tuas Port and Changi Airfreight Centre deploy these units for container yard and airfreight centre automation under sub-10ms latency requirements.
- Service Robots:Human-interactive units for cleaning and hospitality applications leverage edge-native silicon for real-time obstacle avoidance.
- Collaborative Robots:Force-limited articulated arms enable shared workspaces with human operators in precision assembly tasks.
Industrial robots absorb the bulk of installed capacity; autonomous mobile robots are expanding most quickly.
Technology:
Cost tier differentiation separates training-heavy cloud workloads from latency-constrained edge inference, with navigation autonomy emerging as the decisive margin battleground.
- Machine Learning:Cloud-resident model training and federated learning across distributed fleets consume the largest technology spend. Logistics operators at Pandan Logistics Hub deploy these systems for predictive maintenance and demand forecasting.
- Sensor Fusion:Multi-modal data integration from LiDAR, cameras, and IMUs enables robust localization in dynamic environments. Healthcare providers deploy patient-monitoring mobile platforms with edge-resident processing to satisfy PDPC cross-border data restrictions.
- Computer Vision:Real-time object detection and classification pipelines run on edge-native neural processing units.
- Natural Language Processing:Voice-enabled human-robot interaction modules for service applications in hospitality and retail settings.
Machine learning commands the dominant share of technology investment; sensor fusion is climbing the fastest as healthcare and logistics operators pursue richer environmental awareness.
Application:
Volume concentration in logistics automation creates economies of scale for fleet management platforms, while healthcare applications demand specialized compliance architectures.
- Warehouse Automation:Brownfield retrofit deployments dominate installed base with autonomous mobile robots navigating existing racking infrastructure. Third-party logistics providers at Penjuru Lane facilities favor robot-as-a-service contracts with uptime guarantees over capital procurement.
- Healthcare:Patient-monitoring mobile platforms and sterilization robots require edge-resident processing for sensitive telemetry. PDPC localization mandates force fragmented cloud architectures that duplicate infrastructure investment across hospital networks.
- Agriculture:Precision farming robots for urban vertical agriculture in Lim Chu Kang agricultural zones.
- Retail:Inventory scanning and customer service robots deployed in Orchard Road shopping districts.
Warehouse automation absorbs the bulk of installed capacity; healthcare is gaining share fastest as medical providers accelerate sensor fusion deployments.
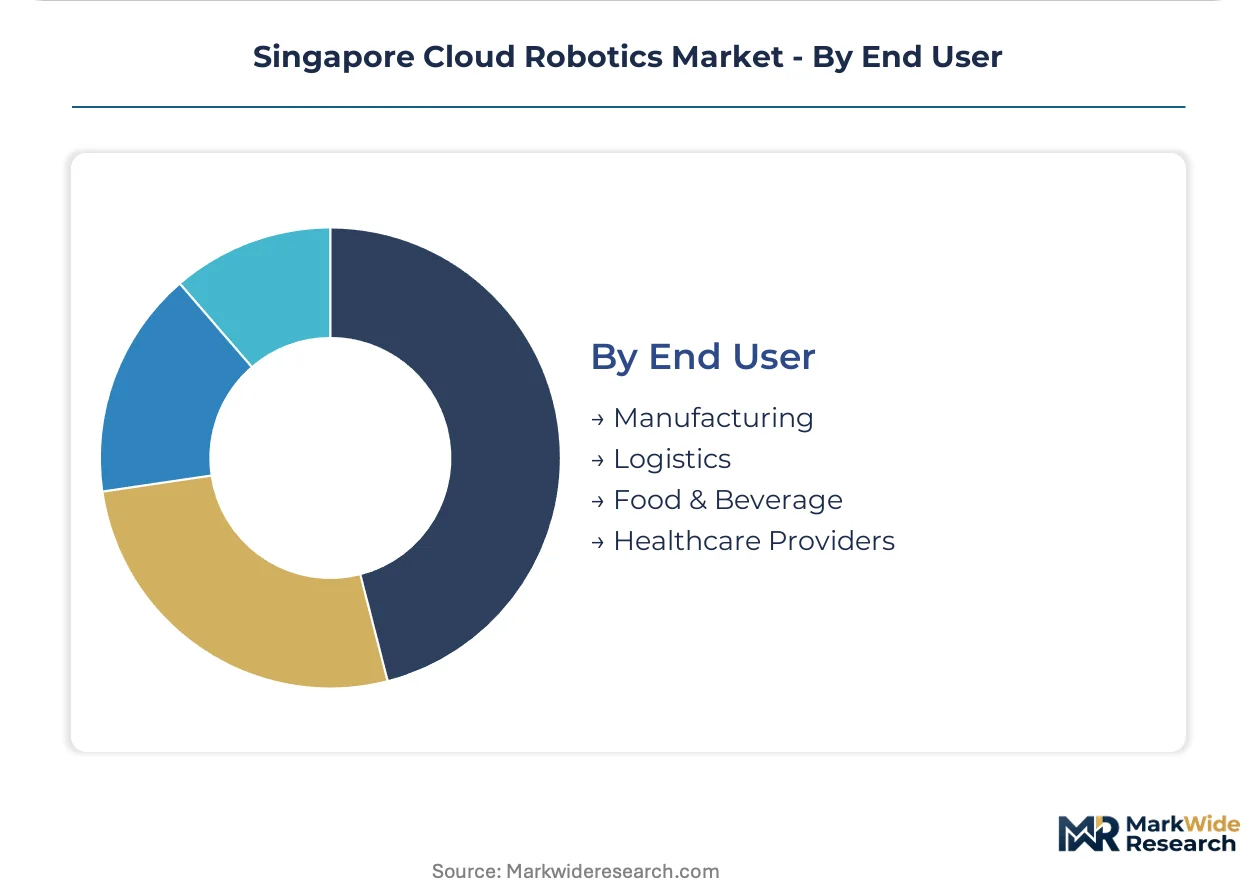
End User:
Customer type maturity separates asset-heavy manufacturers from operational-expenditure-focused logistics operators, with procurement patterns diverging sharply on ownership versus service models.
- Logistics:Third-party and in-house operators at Tuas Port, Changi Airfreight Centre, and Pandan Logistics Hub drive fleet-scale autonomous mobile robot adoption. Buying patterns favor vendor-absorbed maintenance risk through subscription pricing.
- Manufacturing:Precision assembly and quality inspection applications in Jurong Innovation District anchor industrial robot demand. These users retain capital procurement preferences with longer depreciation cycles.
- Healthcare Providers:Hospitals and eldercare facilities deploying patient-monitoring and logistics support robots.
- Food & Beverage:Commercial kitchens and central distribution facilities utilizing collaborative robots for repetitive preparation tasks.
Logistics absorbs the bulk of installed capacity; healthcare providers are expanding most quickly as PDPC-compliant edge architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics automation clusters concentrate cloud robotics demand across Singapore's port zones and innovation districts. The Infocomm Media Development Authority's 5G corridor certifications and robotics sandbox grants shape infrastructure deployment timelines. Sub-regional variation reflects proximity to maritime freight terminals versus advanced manufacturing enclaves.
Jurong Innovation District
Advanced manufacturing clusters anchor industrial robot demand with precision assembly applications. IMDA robotics sandbox grants subsidize fleet modernization for producers integrating collaborative systems. The district's captive demand for service-class robot assembly sustains local manufacturing scale.
Tuas Port
Container yard automation drives autonomous mobile robot deployment under sub-10ms latency mandates. The Maritime and Port Authority of Singapore coordinates with IMDA on 5G infrastructure specifications. Fleet density requirements at Southeast Asia's largest transshipment hub steepen compliance curves for operators.
Changi Airfreight Centre
Air cargo handling automation pulls cloud-connected navigation systems through brownfield retrofit cycles. Civil Aviation Authority of Singapore safety protocols intersect with PDPC data localization requirements for cross-border telemetry. Third-party logistics providers favor robot-as-a-service contracts with uptime guarantees over capital procurement.
Pandan Logistics Hub
Mid-scale warehouse operators pilot federated learning architectures for predictive maintenance. IMDA robotics sandbox grants lower adoption barriers for operators lacking internal fleet management expertise. Penjuru Lane facilities displace traditional equipment financing with operational expenditure models.
Orchard Road District
Retail and hospitality applications concentrate service robot demand for cleaning and customer interaction. Edge-native silicon with dedicated neural processing units enables real-time obstacle avoidance in high-footfall environments. Commercial cleaning operators deploy these systems at pilot-to-fleet scale within compressed eighteen-month windows.
Singapore Cloud Robotics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bridge hardware manufacturing with software-defined autonomy. The vendor base clusters around three archetypes: local assemblers of service-class units, navigation stack specialists, and fleet management platform providers. Technology licensing agreements proliferate between silicon vendors and robot manufacturers. Portfolio diversification into adjacent automation segments separates scale players from niche specialists.
Within the navigation software tier, Movel AI Pte Ltd and Augmentus exemplify the shift toward hardware-agnostic autonomy stacks. Gaussian Robotics and LionsBot represent contrasting approaches to vertical integration—proprietary navigation systems versus manufacturing scale in local assembly. Among China-connected hardware suppliers, FJ Dynamics occupies a position bridging agricultural automation expertise with logistics applications.
| Leading Market Players |
|---|
| Gaussian Robotics |
| Fabrica AI |
| Syrius Robotics |
| CTRL Robotics pte ltd |
| Movel AI Pte Ltd |
| LionsBot |
| Augmentus |
| Botsync Pte Ltd |
| FJ Dynamics |
| Others |
Pricing and Supply Chain Analysis
Robot-as-a-service procurement preferences among third-party logistics operators at Pandan Logistics Hub and Penjuru Lane facilities are compressing upfront capital outlays while shifting maintenance risk to vendors, forcing fleet management platforms to absorb lifecycle costs and restructure hardware sourcing around recurring revenue economics.
Pricing Analysis
Volume concentration in warehouse automation creates a bifurcated margin structure where fleet-scale deployments command subscription premiums while single-unit service robot sales face cost compression. Three-tier pricing structure across premium, standard, and economy levels separates uptime-guaranteed enterprise contracts from pilot-program rates and bare-hardware transactions. Pricing pressure stems from edge silicon cost volatility and proprietary navigation stack licensing fees that inflate unit economics. Logistics operators exhibit highest price sensitivity due to thin warehousing margins, whereas healthcare providers absorb premium tiers for PDPC-compliant edge-resident architectures.
Supply Chain Analysis
Reverse-logistics flows for autonomous mobile robot fleets concentrate refurbishment capacity in Singapore's Jurong Innovation District, where LionsBot maintains local assembly lines for service-class unit redeployment. Hardware components draw from Taiwan for neural processing units, South Korea for LiDAR sensors, and China for battery systems. Single-source vulnerability in edge-native silicon creates exposure to foundry allocation constraints. Distribution runs through vendor-direct fleet management platforms and systems integrators like Movel AI Pte Ltd rather than traditional industrial equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-native silicon fabrication capacity constraints prop pricing power for fleet management platforms capable of securing dedicated compute allocations, sustaining margin premiums despite buyer pressure for subscription rate compression.
For Market Incumbents: Anchor fleet management platform stickiness through backward integration into edge-native silicon sourcing, securing allocation priority at Taiwan and South Korea foundries. Deepen API bridge investments for legacy warehouse management system integration to raise switching costs against emerging navigation stack competitors. Defend against hardware-agnostic autonomy challengers by embedding proprietary sensor fusion calibration into subscription contracts. For New Entrants and Emerging Players: The mid-market pricing gap between premium uptime-guaranteed fleet contracts and economy-tier pilot programs offers entry space for regional logistics operators at Tuas Port satellite facilities. Target brownfield retrofit specialists lacking internal robotics integration expertise with modular navigation licensing that layers atop existing autonomous mobile robot hardware. Pursue IMDA robotics sandbox grant qualification to subsidize initial deployment credibility. For Investors and Strategic Acquirers: The window for entry favors fleet management platforms with demonstrated PDPC-compliant edge architectures and established 5G corridor certification relationships. Long-term viability hinges on federated learning infrastructure ownership that reduces bandwidth costs while preserving intelligence centralization. Monitor IMDA grant recipient conversion rates from pilot to fleet-scale deployment as inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Infrastructure Deployment | Reduces bandwidth costs for logistics operators at Tuas Port while preserving fleet-wide model updates. |
| PDPC-Compliant Edge Architecture Certification | Enables healthcare provider deployments at Singapore hospital networks without cross-border telemetry fragmentation. |
| 5G Corridor Certification Partnership | Secures sub-10ms latency guarantees for Changi Airfreight Centre multi-robot coordination mandates. |
| Backward Integration into Edge Silicon Sourcing | Captures allocation priority at Taiwan foundries amid compute module supply constraints. |
| Robot-as-a-Service Platform Expansion | Absorbs maintenance risk for Penjuru Lane logistics operators displacing capital procurement preferences. |
Research Methodology
Document review covered IMDA policy circulars, PDPC guidance notes, and Maritime and Port Authority of Singapore infrastructure specifications, complemented by interviews with fleet operations directors at third-party logistics providers, robotics sandbox grant administrators, edge silicon procurement leads, and warehouse management system integration specialists. Secondary validation drew from customs trade data, 5G corridor certification registries, and robotics deployment permit filings. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Cross-referencing historical fleet adoption curves against expert panel inputs on latency requirement evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology stack, application vertical, and end-user procurement maturity. CAGRs derived from logistic curve fitting to brownfield retrofit penetration rates, with inputs from 5G infrastructure rollout timelines and robotics sandbox grant budget allocations.
Inputs from IMDA program administrators and PDPC compliance officers were available through the study window; gaps in proprietary edge silicon pricing data and fleet management platform unit economics introduce uncertainty bands around vendor margin projections. Practitioners should monitor 5G corridor certification completion rates and robotics sandbox grant conversion metrics for early signals of infrastructure readiness inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Modular Robotics Market