
 Automotive Temperature Sensor Market | 2026-2036
Automotive Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Temperature Sensor Market Intelligence
Asset-light manufacturing models, which rely on outsourced fabrication, is tilting the competitive landscape toward fabless semiconductor firms. This shift allows companies like NXP Semiconductors NV to focus on design innovation and intellectual property. In contrast, established Tier-1 suppliers such as Robert Bosch GmbH leverage extensive in-house production capabilities for scale and quality control. Continental AG differentiates through its deep integration with automotive OEMs on system-level solutions.
Automotive temperature sensors are devices that measure thermal conditions within various vehicle systems. They often utilize negative temperature coefficient (NTC) thermistors, converting resistance changes into precise temperature readings for engine control units. Among applications, battery monitoring systems are expanding rapidly due to electric vehicle proliferation. Engine control and climate management constitute mature, high-volume segments primarily serving OEMs and Tier-1 suppliers.
Product specifications are governed by international standards like ISO 26262 for functional safety. Emissions-related mandates from the US Environmental Protection Agency (EPA) and the EU's F-Gas Regulation influence sensor requirements for climate and exhaust systems. Component suppliers must decide whether to specialize in high-precision EV battery sensors or defend their position in traditional internal combustion engine applications.
Market Dynamics
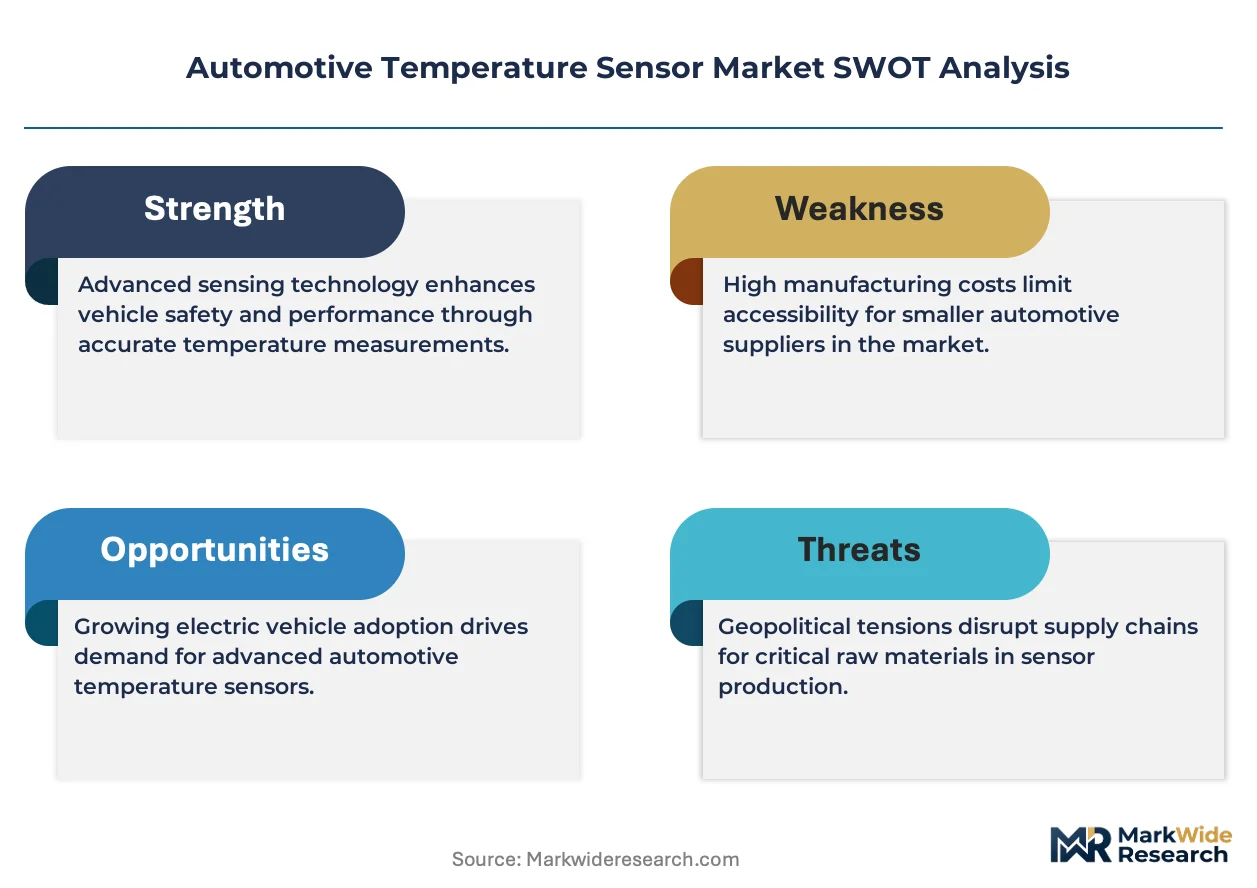
The market's central dynamic is the tension between mature, high-volume internal combustion engine applications and the rapid, technology-driven expansion into electric vehicle battery systems. This dual demand environment is forcing suppliers to allocate resources between defending legacy positions and investing in new EV-specific capabilities.
Growth Catalysts
- EV Proliferation:Demand for precise thermal monitoring within electric vehicle battery packs, motors, and charging systems is expanding rapidly, creating a primary growth vector for high-performance negative temperature coefficient (NTC) thermistors.
- Emissions Regulations:Mandates like the US EPA's vehicle standards and China's dual carbon goals necessitate more sophisticated sensors for precise engine combustion, exhaust gas after-treatment, and powertrain thermal management to minimize pollutants.
- Functional Safety Standards:The increasing adoption of ISO 26262 for functional safety requires more redundant and reliable temperature sensors in critical systems like braking and advanced driver-assistance systems (ADAS), boosting sensor content per vehicle.
Market Restraints
- Component Commoditization:In mature segments like engine and climate control for internal combustion engines, intense price pressure from automotive OEMs leads to the commoditization of standard temperature sensors, squeezing supplier margins.
- Supply Chain Concentration:The consolidation of manufacturing within specific geographic hubs, notably in China and Germany, creates vulnerability to regional trade policies, logistical disruptions, and localized material shortages, posing a risk to global supply stability.
- Threat of Integration:The trend toward system-on-chip (SoC) solutions in vehicle electronics threatens to integrate temperature sensing functions directly into larger semiconductor packages, potentially reducing the market for discrete sensor components.
Strategic Opportunities
- Fast-Charging Infrastructure:The build-out of DC fast-charging stations for electric vehicles presents an opportunity for specialized, high-temperature sensors to monitor cable, connector, and power electronics thermal conditions to ensure safety and efficiency.
- Sensor Fusion Modules:Combining temperature sensors with pressure, humidity, or current sensors into compact, pre-calibrated modules offers a value-added solution for OEMs, simplifying integration and improving system-level data quality for complex applications.
- Alternative Refrigerant Systems:The EU's F-Gas Regulation drives a shift to new climate control refrigerants, creating an opportunity for sensors specifically designed to operate accurately and reliably with the unique thermal properties of these new fluids.
Industry Challenges
- Certification Hurdles:Achieving and maintaining compliance with automotive standards, particularly ISO 26262 for functional safety, is a time-consuming and costly process that can delay the introduction of new sensor technologies for safety-critical applications.
- Legacy System Integration:Integrating advanced, high-data-rate sensors into older vehicle electronic architectures poses a significant challenge, often requiring complex software adaptations or gateway modules to ensure compatibility with existing engine control units (ECUs).
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Temperature Sensor Market |
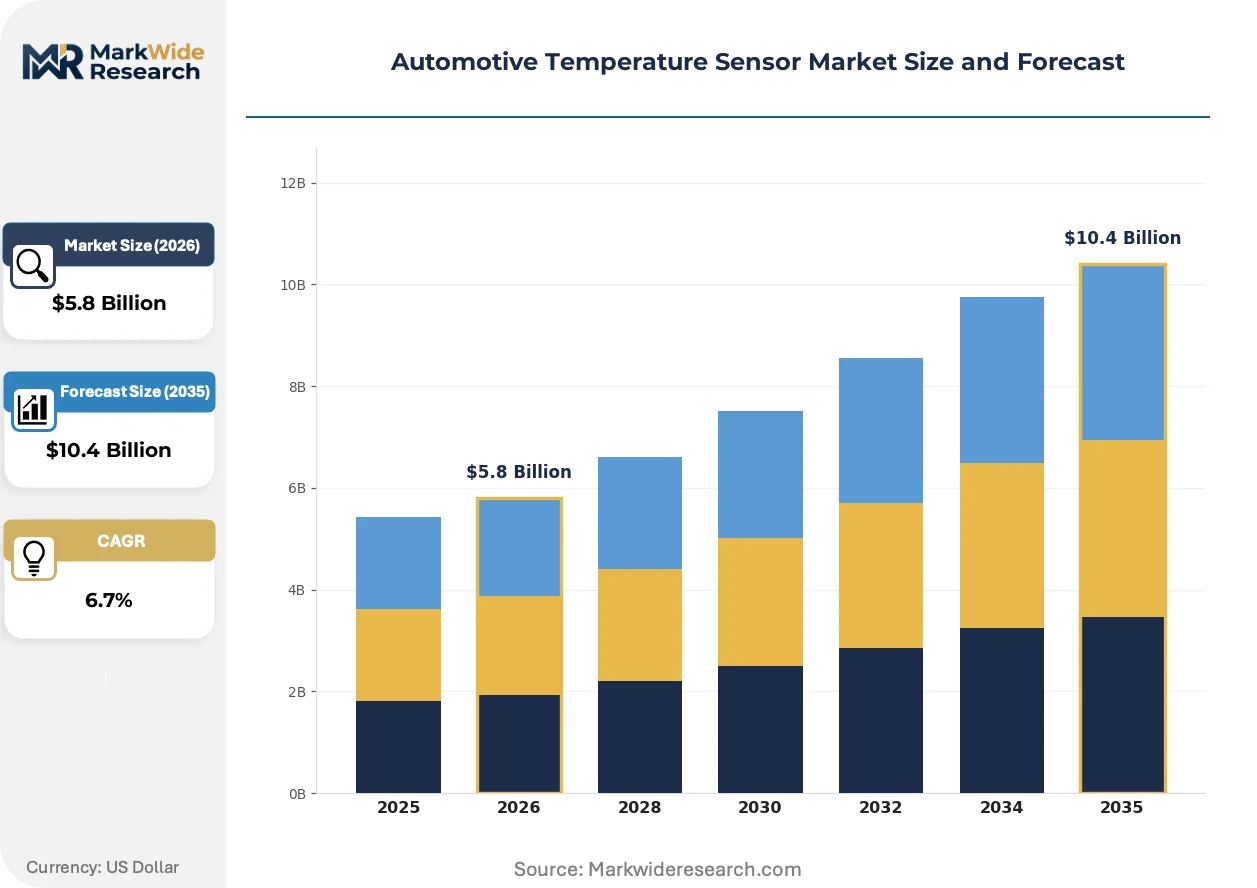
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermistor Sensors, Resistance Temperature Detectors, Infrared Sensors, Thermocouples, Semiconductor Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Microelectromechanical Systems, Contactless Sensors Application: Engine Control, Climate Management, Battery Monitoring, Exhaust Gas Analysis, Transmission Systems End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Component Manufacturers |
| Companies Covered | NXP Semiconductors NV, Panasonic Holdings Corporation, Continental AG, TE Connectivity Ltd., Denso Corporation, Robert Bosch GmbH, Analog Devices Inc., Texas Instruments Incorporated, Sensata Technologies Holding plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Temperature Sensor Market Strategic Shifts & Innovations
The transition to electric and software-defined vehicles is fundamentally altering the role of thermal data. It is evolving from a simple control input for isolated components into a critical dataset for holistic vehicle performance, safety, and battery longevity management.
Smart sensors with embedded processing capabilities are gaining traction. These devices integrate a sensing element with a microcontroller to perform local signal conditioning, linearization, and diagnostics. Automotive OEMs and Tier-1 suppliers are adopting them for advanced battery management, as this trend is digitizing thermal control by delivering pre-processed, network-ready data directly from the measurement point.
Regulatory frameworks are directly shaping sensor design requirements for specific vehicle systems. The European Union's F-Gas Regulation, which phases down certain refrigerants, is compelling a redesign of automotive climate control systems. This directly impacts the HVAC sensor segment by requiring new sensors optimized for the thermodynamic profiles and safety protocols of alternative, low-GWP refrigerants.
A notable shift in purchasing behavior involves OEMs co-developing thermal management systems with suppliers, moving away from procuring discrete components. This disrupts the traditional, specification-driven procurement model in favor of deeper, system-level partnerships that leverage supplier expertise in thermal modeling and integration. The trend is most visible in the competitive EV sector, where battery thermal performance is a key differentiator.
Automotive Temperature Sensor Market Segmentation
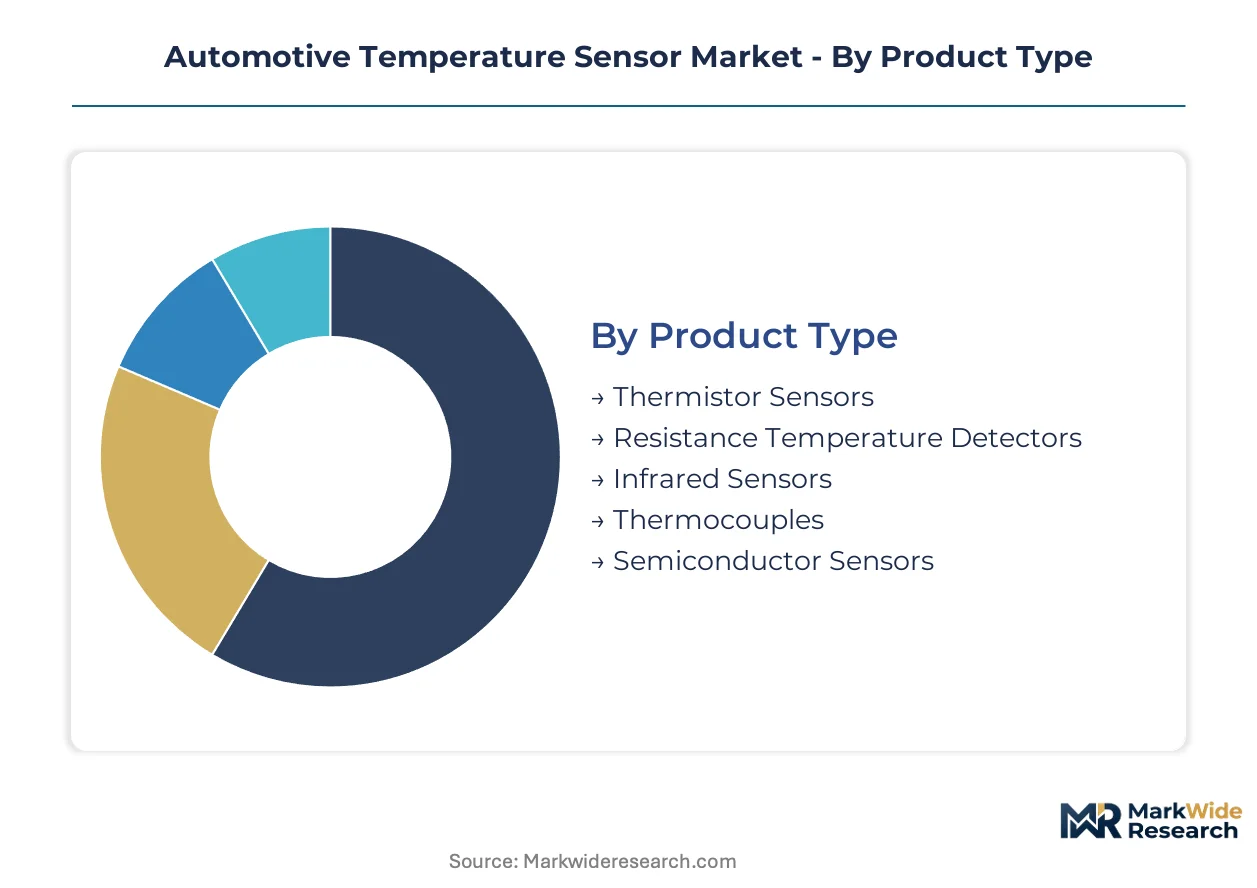
The automotive temperature sensor market segmentation provides a granular view of product evolution and strategic resource allocation. It highlights where innovation is concentrated versus where mature product lines still command significant volume. Understanding these segments is crucial for identifying areas of growth and competitive differentiation within the diverse automotive ecosystem.
Product Type:
Product types exhibit varying development cycles, from rapidly evolving EV-specific solutions to long-established components for conventional powertrains.
- Thermistor Sensors:These devices often utilize negative temperature coefficient (NTC) materials, where electrical resistance decreases as temperature rises, enabling precise thermal measurement. Demand is concentrating in battery monitoring systems for electric vehicles, driven by the need for accurate cell temperature management to optimize performance and longevity.
- Infrared Sensors:These non-contact sensors measure thermal radiation emitted by objects, allowing for rapid and remote temperature detection without physical contact. Their adoption is accelerating in advanced driver-assistance systems (ADAS) for brake temperature monitoring and in fast-charging infrastructure for detecting thermal hotspots in connectors and cables to enhance safety.
- Resistance Temperature Detectors:RTDs, typically platinum-based, offer high accuracy and stability over broad temperature ranges by measuring changes in electrical resistance. These are often specified for critical engine control functions where long-term reliability and precision are paramount for emissions compliance.
- Thermocouples:Formed by two dissimilar metal wires, thermocouples generate a voltage proportional to temperature differences, suitable for high-temperature exhaust gas analysis and after-treatment systems.
- Semiconductor Sensors:Integrating sensing elements with signal conditioning on a single chip, these offer compact solutions for ambient temperature measurement and cabin climate control systems.
Thermistor Sensors anchor the volume base while Infrared Sensors gain share at the steepest rate.
Technology:
Technological segmentation reflects the maturity curve of sensor integration, from foundational analog signals to advanced digital and wireless communication protocols.
- Digital Sensors:These devices integrate analog-to-digital converters and often microcontrollers, providing pre-processed, linearized temperature data directly to vehicle networks. Adoption is accelerating in advanced battery management systems for electric vehicles, where data integrity and direct communication with the ECU are critical for performance optimization.
- Wireless Sensors:Employing radio frequency communication, these sensors transmit thermal data without physical wiring, simplifying installation and reducing harness weight, particularly in complex battery packs. Their deployment is expanding in modular battery architectures and tire pressure monitoring systems, driven by demands for flexible design and reduced assembly costs.
- Analog Sensors:These provide a continuous voltage or current output proportional to temperature, requiring external signal conditioning by the engine control unit. They remain prevalent in cost-sensitive applications like basic engine coolant temperature sensing and climate control systems.
- Microelectromechanical Systems:MEMS-based sensors combine mechanical and electrical components on a silicon chip, offering compact, low-power solutions for localized temperature measurement in various vehicle subsystems.
- Contactless Sensors:These sensors measure temperature without physical contact, often using infrared technology, enabling monitoring of moving parts or high-temperature surfaces in powertrain components.
Digital Sensors drive system-level intelligence, whereas Analog Sensors maintain their role in cost-sensitive applications.
Application:
Application segments delineate sensor criticality and volume requirements, ranging from high-precision safety functions to high-volume environmental controls.
- Battery Monitoring:This segment involves precise thermal management within electric vehicle battery packs, motors, and charging systems to ensure optimal performance, safety, and longevity. Demand in China and Germany for high-performance NTC thermistors is expanding due to stringent EV safety standards.
- Engine Control:Sensors in this segment provide critical thermal data for optimizing fuel combustion, managing exhaust gas recirculation, and ensuring efficient engine operation in internal combustion vehicles. Regulatory mandates from the US EPA necessitate highly accurate sensors for precise emissions control.
- Climate Management:Temperature sensors regulate cabin comfort by monitoring ambient, vent, and evaporator temperatures, influencing heating, ventilation, and air conditioning (HVAC) system performance. The EU's F-Gas Regulation is compelling new sensor designs optimized for alternative refrigerants.
- Exhaust Gas Analysis:Sensors measure the temperature of exhaust gases at various stages to optimize catalytic converter efficiency and ensure compliance with emissions regulations.
- Transmission Systems:These sensors monitor fluid temperatures within the transmission to prevent overheating, ensuring smooth gear changes and extending component lifespan.
Battery Monitoring dictates sensor design priorities, while Engine Control represents a critical safety domain.
End User:
End-user categories reflect distinct procurement models and integration depths within the automotive supply chain.
- OEMs:Original Equipment Manufacturers integrate temperature sensors directly into vehicle platforms during the design and manufacturing phases, often co-developing solutions with Tier-1 suppliers. Their purchasing behavior is shifting towards system-level thermal management partnerships, particularly in the competitive EV sector.
- Tier-1 Suppliers:These companies supply integrated modules and subsystems directly to OEMs, often incorporating temperature sensors into larger assemblies like engine control units or battery management systems. Robert Bosch GmbH leverages extensive in-house production capabilities to serve this segment.
- Aftermarket Providers:This segment includes companies supplying replacement temperature sensors for vehicle maintenance and repair after initial sale. Demand is driven by component failure rates and the need for readily available, compatible parts for older vehicle models.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, procuring pre-integrated modules and components from Tier-1 suppliers rather than discrete sensors.
- Component Manufacturers:These firms produce the raw sensing elements and basic sensor packages that are then supplied to Tier-1s or directly to OEMs for further integration.
Procurement patterns from OEMs shape market dynamics, contrasted with the specialized needs of Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent emissions regulations and electric vehicle proliferation drive demand for automotive temperature sensors across major manufacturing regions. Policies like the US EPA vehicle standards and China's dual carbon goals necessitate advanced thermal management. These regulatory pressures accelerate sensor integration into critical vehicle systems.
China
China's dual carbon goals intensely drive the demand for high-performance NTC thermistors in EV battery monitoring. The government's new energy vehicle subsidies and safety standards mandate precise thermal control. Manufacturing hubs in the Yangtze River Delta concentrate production, integrating advanced sensor technologies into EV platforms.
Germany
German automotive OEMs increasingly integrate advanced temperature sensors for functional safety and engine control in their premium vehicles. The EU's F-Gas Regulation influences climate control sensor redesign for alternative refrigerants. Baden-Württemberg and Bavaria host major automotive and sensor component clusters, fostering deep OEM-supplier co-development.
United States
United States demand for temperature sensors stems from strict EPA vehicle emissions standards and the rapid expansion of EV charging infrastructure. The Inflation Reduction Act (IRA) incentives bolster domestic EV production, increasing sensor content per vehicle. Michigan's automotive corridor and Silicon Valley's tech ecosystem drive innovation in smart sensor integration.
Japan
Japanese automotive manufacturers prioritize high-accuracy temperature sensors for advanced driver-assistance systems and hybrid powertrain optimization. METI initiatives support research into next-generation sensor materials and production techniques. The Aichi Prefecture, home to major carmakers, remains a critical center for sensor technology development and integration.
South Korea
South Korea's robust EV production and emphasis on battery safety standards fuel demand for precise thermal sensors. Government support for electric mobility and smart vehicle technologies accelerates sensor adoption. The Gyeonggi Province, surrounding Seoul, serves as a key hub for semiconductor and automotive component manufacturing.
Automotive Temperature Sensor Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in automotive temperature sensing. The market exhibits a tiered structure, with established Tier-1 suppliers alongside specialized fabless semiconductor firms. Strategic archetypes include integrated system providers, component specialists, and intellectual property-focused designers. Portfolio diversification and strategic partnerships represent dominant competitive moves.
On the integrated system provider vector, Robert Bosch GmbH leverages extensive in-house production capabilities for scale and quality control. Continental AG occupies a position through its deep integration with automotive OEMs on system-level solutions. NXP Semiconductors NV exemplifies the fabless semiconductor firm archetype, focusing on design innovation and intellectual property.
| Leading Market Players |
|---|
| NXP Semiconductors NV |
| Panasonic Holdings Corporation |
| Continental AG |
| TE Connectivity Ltd. |
| Denso Corporation |
| Robert Bosch GmbH |
| Analog Devices Inc. |
| Texas Instruments Incorporated |
| Sensata Technologies Holding plc |
| Others |
Cost & Logistics Intelligence
Manufacturing concentration in China and Germany centralizes component production, influencing pricing power for specialized temperature sensors further downstream. This geographic focus shifts margin capture towards regions with advanced fabrication capabilities.
Pricing Analysis
Certification level, particularly ISO 26262 for functional safety, creates the primary price differentiation across automotive temperature sensors. A tiered pricing model separates high-precision EV battery sensors from commoditized engine and climate control components. Price erosion in mature segments stems from intense OEM pressure, squeezing supplier margins for standard analog sensors. OEMs procuring high-volume, legacy components exhibit the highest price sensitivity, while EV manufacturers prioritize performance over cost for critical battery monitoring.
Supply Chain Analysis
Export-control regimes on advanced semiconductor manufacturing equipment introduce potential friction into the automotive temperature sensor supply chain. Supply concentrates within manufacturing hubs in China and Germany, creating dependencies on NTC thermistors and silicon-based components. This geographic consolidation creates vulnerability to regional trade policies and localized material shortages. Distribution runs primarily through direct channels to Tier-1 suppliers, who then integrate sensors into modules for OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive temperature sensor market is entering a cyclical recovery, driven by renewed investment in electric vehicle platforms. This upswing follows a period of supply chain disruptions and production volatility in the broader automotive industry, now stabilizing.
For Market Incumbents: Insulate core internal combustion engine (ICE) sensor businesses from commoditization by leveraging extensive in-house production capabilities and functional safety certifications like ISO 26262. Deepen system-level partnerships with automotive OEMs, particularly for advanced battery management systems in electric vehicles. This strategy defends against the threat of integrated system-on-chip solutions displacing discrete components.
For New Entrants and Emerging Players: Establish a beachhead in specialized EV segments, such as fast-charging infrastructure thermal monitoring, where high-temperature and reliability demands are unmet. Focus on developing compact, pre-calibrated sensor fusion modules combining temperature with other parameters, offering simplified integration for OEMs. This approach targets the high-growth battery monitoring application in China and Germany, bypassing commoditized legacy markets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized component manufacturers focused on high-precision EV battery sensors, offering long-term viability through the electric vehicle transition. Target fabless semiconductor firms with strong intellectual property in smart digital sensors and advanced signal processing. The increasing trend of OEM co-development with suppliers for system-level thermal management serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smart Sensor Integration | Drives digitization of thermal control, delivering pre-processed data for advanced battery management systems. |
| Deepen OEM Co-development Partnerships | Secures long-term contracts and leverages supplier expertise in thermal modeling for competitive EV platforms. |
| Specialize in EV Fast-Charging Sensors | Addresses critical safety and efficiency needs for high-power DC charging infrastructure components. |
| Expand Functional Safety Certification | Ensures compliance with ISO 26262, enabling adoption in critical braking and ADAS systems. |
| Diversify Beyond NTC Thermistors | Captures growth in ADAS (infrared) and high-temperature exhaust applications (thermocouples). |
Research Approach
Desk research of regulatory filings, vehicle production databases, and company annual reports preceded structured interviews with Tier-1 supplier procurement leads, OEM platform engineers, and R&D directors. This approach combined primary insights with secondary validation, ensuring a robust data foundation. Bottom-up market sizing was triangulated with top-down industry forecasts to establish overall market parameters.
Assumptions regarding electric vehicle adoption rates and the stringency of emissions regulations were held constant across the analysis window, while technological advancements were varied. The analytical framework segmented the market by product type, technology, application, end-user, and regional production cluster. Compound annual growth rates were derived from historical data, projected EV content per vehicle, and anticipated regulatory impacts.
Stress conditions across geopolitical trade policies and raw material price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, but do not account for black swan events. Material shifts in major automotive OEM production strategies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Jump Starter Market