
 Africa Vehicle Tracking System Market | 2026-2036
Africa Vehicle Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Vehicle Tracking System Market Intelligence
Satellite connectivity is consolidating as the dominant communication backbone for remote-area fleet visibility across sub-Saharan routes. Cartrack leverages its vertically integrated stolen-vehicle-recovery infrastructure to anchor premium service tiers in Southern Africa. MiX Telematics competes through specialized oil-and-gas fleet solutions that sustain high-margin contracts in Nigerian extractive zones.
Africa vehicle tracking systems encompass GPS, RFID, OBD II, and telematics hardware paired with cellular, satellite, Wi-Fi, or Bluetooth communication layers to deliver real-time location, diagnostics, and driver-behavior analytics for commercial and consumer vehicle operators. Cellular-network-dependent telematics dominates current installation volumes due to lower module cost and pervasive 2G/3G coverage in peri-urban freight corridors, though satellite-system deployments are capturing faster growth in cross-border mining and agriculture logistics where terrestrial infrastructure remains sparse. Fleet operators represent the most mature end-user segment with established procurement frameworks, while ride-hailing services constitute the fastest-expanding demand pool as platform economics force asset-light operators to outsource vehicle monitoring to third-party telematics providers.
South Africa's National Regulator for Compulsory Specifications mandates type-approved tracking hardware for stolen-vehicle recovery, compelling fitment upgrades that shape product certification requirements across the Southern African Development Community trade zone. Kenya's National Transport and Safety Authority enforces speed-governor integration with tracking devices for commercial passenger vehicles, creating a combined regulatory compliance burden that favors hardwired installation solutions over plug-and-play alternatives. Stakeholders must monitor how Nigeria's Federal Road Safety Corps evolves its proposed national vehicle registry linkage with telematics data, as this integration would fundamentally alter data sovereignty and platform interoperability requirements for cross-border fleet operators.
Market Dynamics
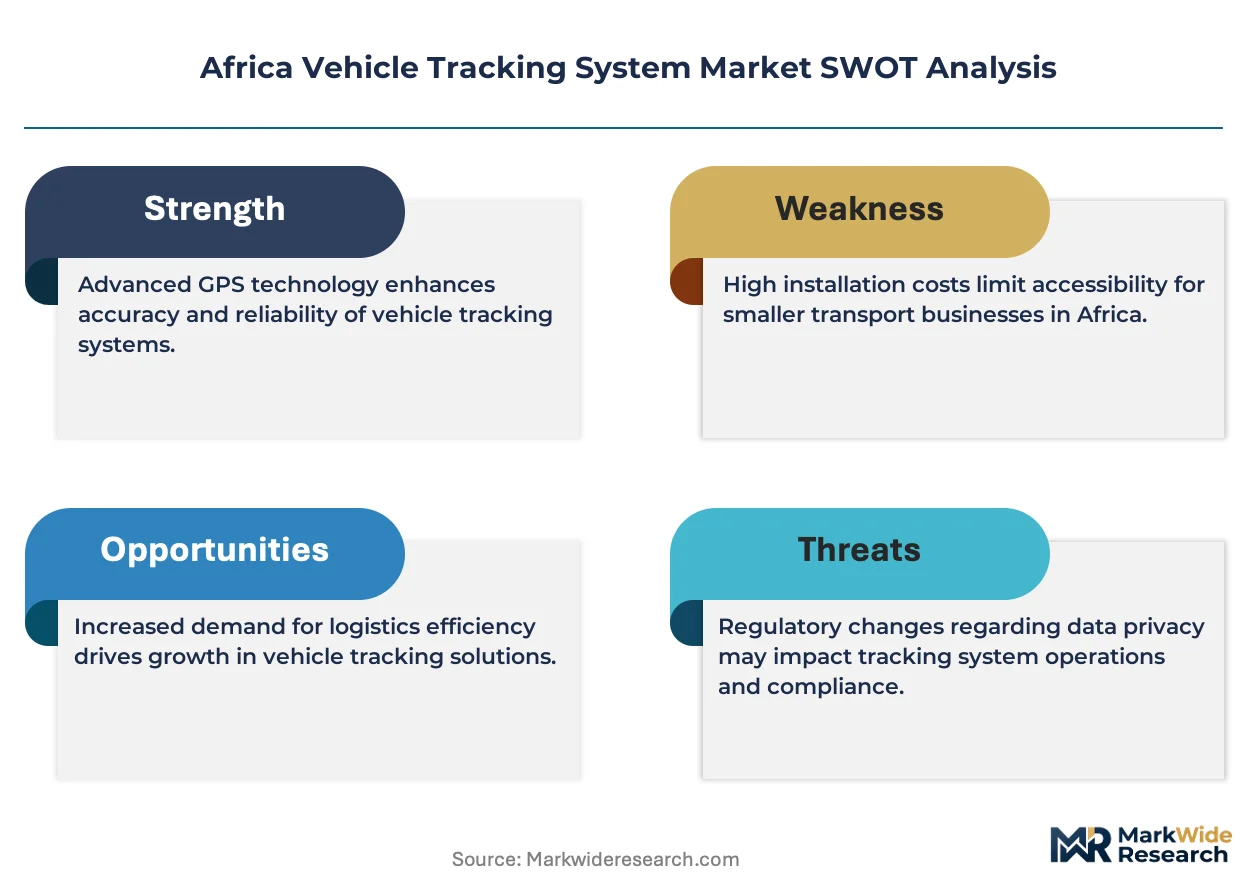
Satellite-to-cellular hybrid connectivity is compressing hardware margins while expanding addressable fleet coverage across sub-Saharan corridors previously unreachable by terrestrial networks alone.
Growth Catalysts
- Fuel-cost volatility:Johannesburg-based long-haul operators deploy driver-behavior analytics to cut diesel consumption by 12-18% on cross-border routes to Maputo and Gaborone.
- South Africa's NRCS mandate:Compulsory fitment of type-approved stolen-vehicle recovery hardware forces periodic hardware refresh cycles across the Southern African Development Community trade zone.
- Last-mile insurance requirements:Lagos and Nairobi cargo underwriters now require real-time cargo visibility as a condition of freight liability coverage.
Market Restraints
- Import tariff stacking:Kenyan and Nigerian customs regimes impose cumulative duties exceeding 35% on Chinese-manufactured GPS modules, inflating landed hardware costs.
- Cellular coverage gaps:Cross-border mining fleets operating between Lubumbashi and Durban lose telemetry handoffs where 2G infrastructure terminates.
- Power infrastructure instability:Grid unreliability in Nigerian urban corridors forces redundant battery backup systems that add 15-20% to installation complexity.
Strategic Opportunities
- Ethiopia's freight corridor modernization:The Addis Ababa-Djibouti rail-road intermodal expansion creates first-mover positioning for cold-chain telematics in pharmaceutical logistics.
- Speed-governor integration mandates:Kenya's National Transport and Safety Authority requires hardwired installation of combined tracking and speed-limiting devices on matatu fleets.
- Bluetooth-to-satellite handoff protocols:Warehouse yard management systems in Durban and Cape Town container terminals are converging short-range asset tracking with long-haul fleet visibility.
Industry Challenges
- Certification timeline compression:South Africa's NRCS type-approval process for new hardware variants stretches 8-14 months, delaying product launches behind competitor cycles.
- Legacy fleet integration:Nigerian petroleum distributors operate mixed-vintage truck pools where 1990s-era CAN bus architectures resist plug-and-play telematics retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Vehicle Tracking System Market |
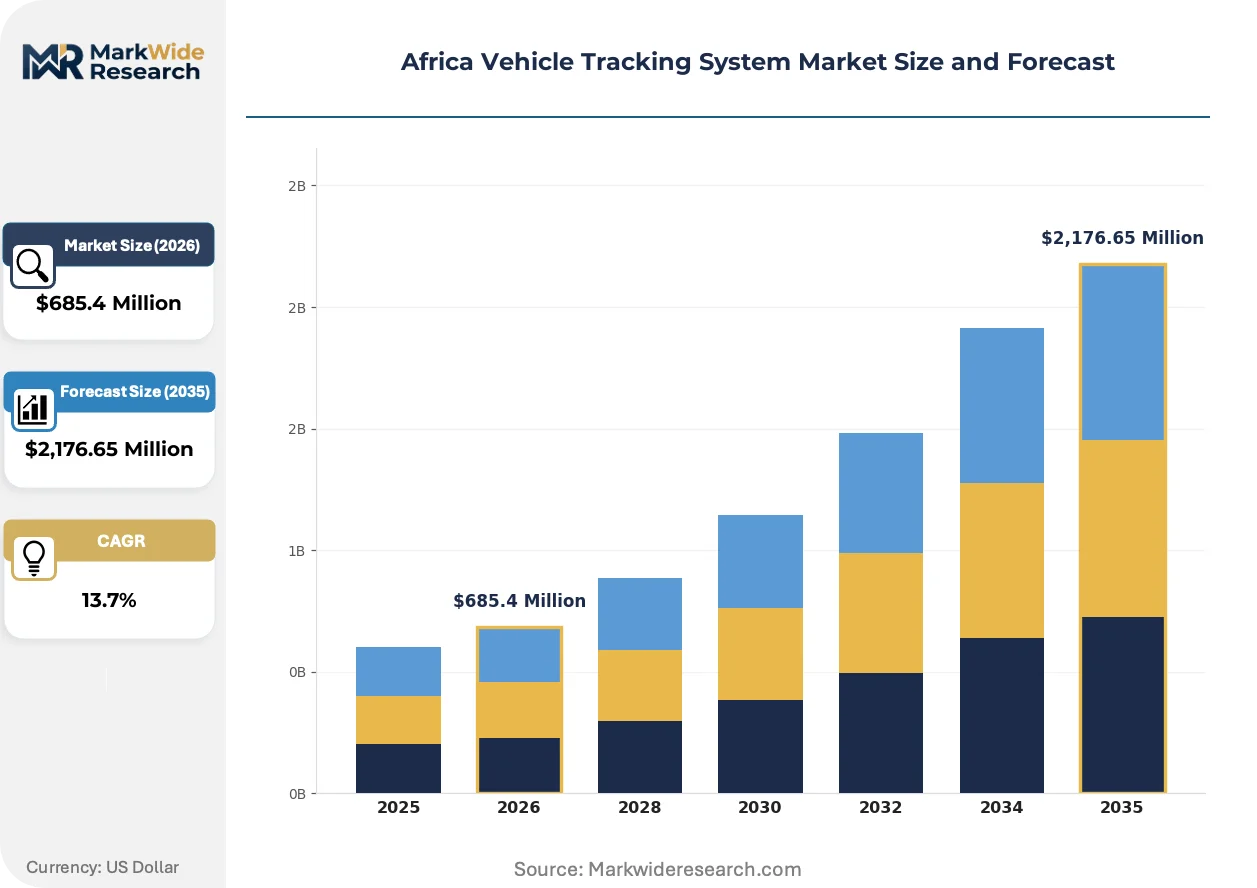
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Tracking, RFID Tracking, OBD II Devices, Telematics Solutions End User: Fleet Operators, Individual Car Owners, Government Agencies, Ride-Hailing Services Technology: Cellular Networks, Satellite Systems, Wi-Fi Systems, Bluetooth Technology Installation: Hardwired Solutions, Plug-and-Play Devices, Mobile Applications, DIY Kits |
| Companies Covered | Cartrack, Tracker, Ctrack, Netstar, MiX Telematics, Geotab, TomTom Telematics, Verizon Connect, Fleet Complete, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Vehicle Tracking System Market Strategic Shifts & Innovations
Hardware commoditization is forcing telematics providers to differentiate through software-layer analytics and vertical-specific compliance modules rather than device specifications alone.
Dual-mode satellite-cellular modems are consolidating as the standard communication architecture for cross-border African fleet operators. Mining and agriculture logistics buyers in Zambia and Mozambique now specify seamless handoff capability as a procurement baseline. This consolidation is compressing pure-cellular hardware margins while expanding the addressable market into previously unserved trans-Sahelian routes.
Kenya's National Transport and Safety Authority has tightened enforcement of speed-governor integration with tracking devices for commercial passenger vehicles. The industrial consequence is a forced shift from aftermarket plug-and-play units toward hardwired installation by certified technicians. Matatu operator associations in Nairobi and Mombasa are responding by consolidating procurement through approved installer networks to maintain compliance documentation.
Fleet procurement patterns now favor subscription-based platform access over perpetual hardware ownership. East African logistics operators in the Rwanda-Uganda corridor are displacing capital-intensive telematics purchases with per-vehicle-month service fees bundled with insurance and maintenance. This shift is most visible among asset-light ride-hailing fleet lessors in Nairobi and Lagos who outsource all monitoring infrastructure to third-party providers.
Africa Vehicle Tracking System Market Segmentation
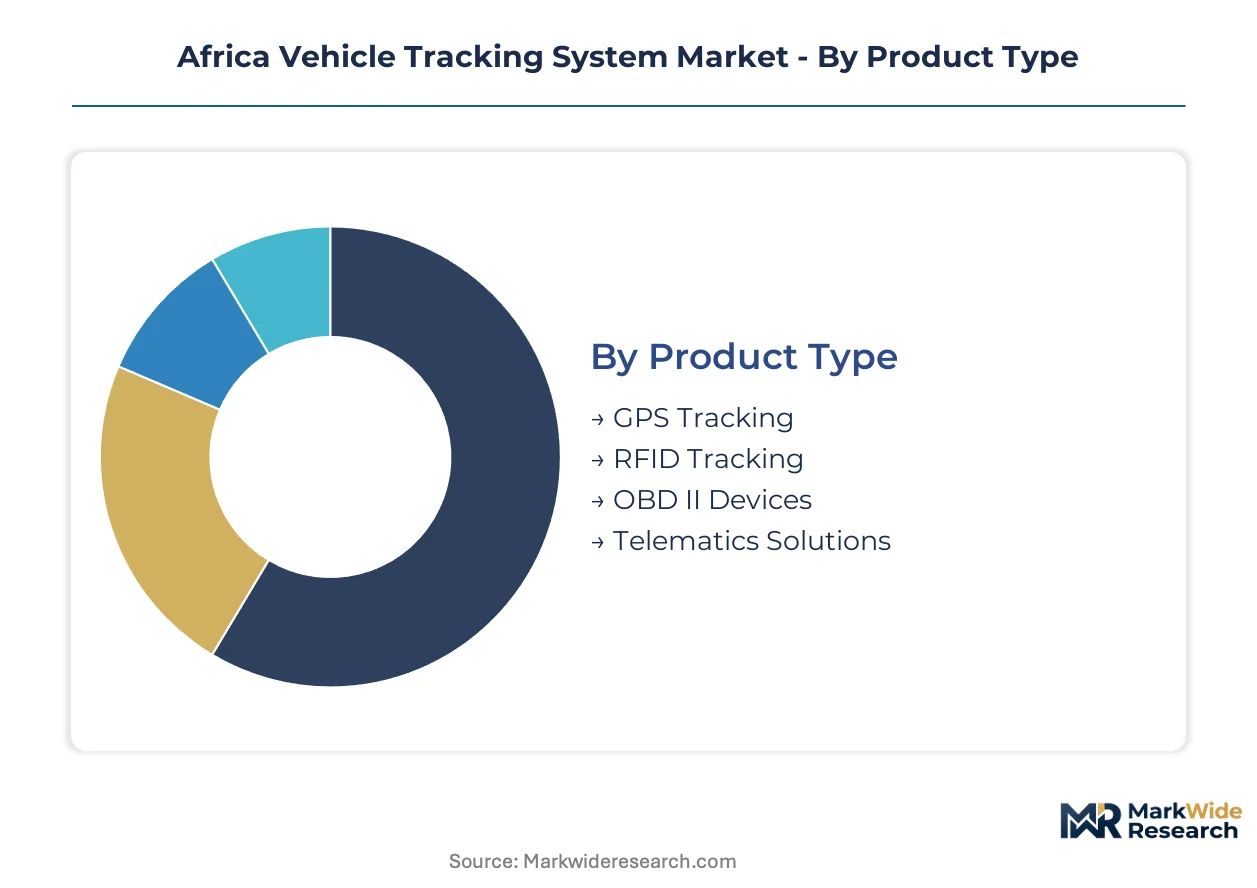
Technology choices in African vehicle tracking reflect infrastructure asymmetry across the continent. Buyers optimize for connectivity reliability, regulatory compliance burdens, and installation labor costs rather than feature density alone.
Product Type:
Hardware differentiation centers on data granularity versus unit economics, with fleet procurement teams weighing diagnostic depth against per-vehicle capital outlay.
- Telematics Solutions:Integrated platforms combine location tracking with engine diagnostics, driver scoring, and fuel analytics through cloud dashboards. Mining contractors in Zambia's Copperbelt and agribusiness operators in Kenya's Rift Valley specify these systems for equipment utilization optimization. Volume sits with telematics; growth tilts toward OBD II plug-ins among cost-constrained last-mile operators.
- GPS Tracking:Standalone satellite-receiver modules deliver position reporting without vehicle bus integration. South Africa's stolen-vehicle recovery mandate drives fitment in passenger vehicles, while Nigerian freight brokers deploy basic GPS for cross-border cargo monitoring where cellular handoffs remain unreliable.
- RFID Tracking:Short-range radio identification supports yard management and access control at container terminals in Durban and Mombasa port complexes.
- OBD II Devices:Diagnostic port plug-ins extract engine fault codes and mileage data without hardwired installation, appealing to ride-hailing fleet lessors in Lagos seeking rapid deployment.
Telematics commands procurement budgets in formal fleet segments; OBD II devices expand fastest among asset-light mobility platforms.
End User:
Customer maturity varies sharply, with compliance mandates forcing adoption in some segments while ROI demonstration drives voluntary uptake in others.
- Fleet Operators:Long-haul logistics companies and mining contractors maintain structured procurement frameworks with multi-year telematics contracts. Johannesburg-based operators leverage driver-behavior analytics to reduce insurance premiums and fuel theft exposure on routes to Maputo and Walvis Bay. Volume sits with fleet operators; growth tilts toward ride-hailing services.
- Ride-Hailing Services:Asset-light platform economics compel outsourcing of vehicle monitoring to third-party telematics providers. Nairobi and Lagos fleet lessors favor per-vehicle-month subscriptions bundling tracking, insurance, and maintenance.
- Government Agencies:Public transit regulators and road safety authorities mandate device fitment for commercial passenger vehicles, creating compliance-driven demand independent of operator willingness.
- Individual Car Owners:Stolen-vehicle recovery subscriptions dominate this segment in South Africa's high-theft urban corridors, with limited penetration elsewhere due to subscription cost sensitivity.
Fleet procurement maintains volume leadership; ride-hailing platform expansion drives steepest trajectory acceleration.
Technology:
Communication layer selection follows route geography, with terrestrial coverage gaps in cross-border corridors forcing hybrid architectures.
- Cellular Networks:2G and 3G modules dominate peri-urban freight corridors due to lower hardware cost and established tower infrastructure. Kenyan and Nigerian last-mile operators standardize on cellular-dependent units for urban delivery visibility.
- Satellite Systems:Iridium and Thuraya connectivity serves trans-Sahelian mining logistics and agricultural supply chains where terrestrial infrastructure terminates. Volume sits with cellular; growth tilts toward satellite-to-cellular hybrid modems specified by cross-border fleet buyers.
- Wi-Fi Systems:Warehouse yard management and depot-based asset tracking utilize short-range wireless for inventory positioning in Durban and Cape Town container terminals.
- Bluetooth Technology:Proximity-based handoff protocols bridge warehouse management systems with long-haul fleet visibility for seamless cargo tracking.
Cellular hardware retains installation volume; hybrid satellite-cellular configurations capture fastest expansion in remote-route logistics.
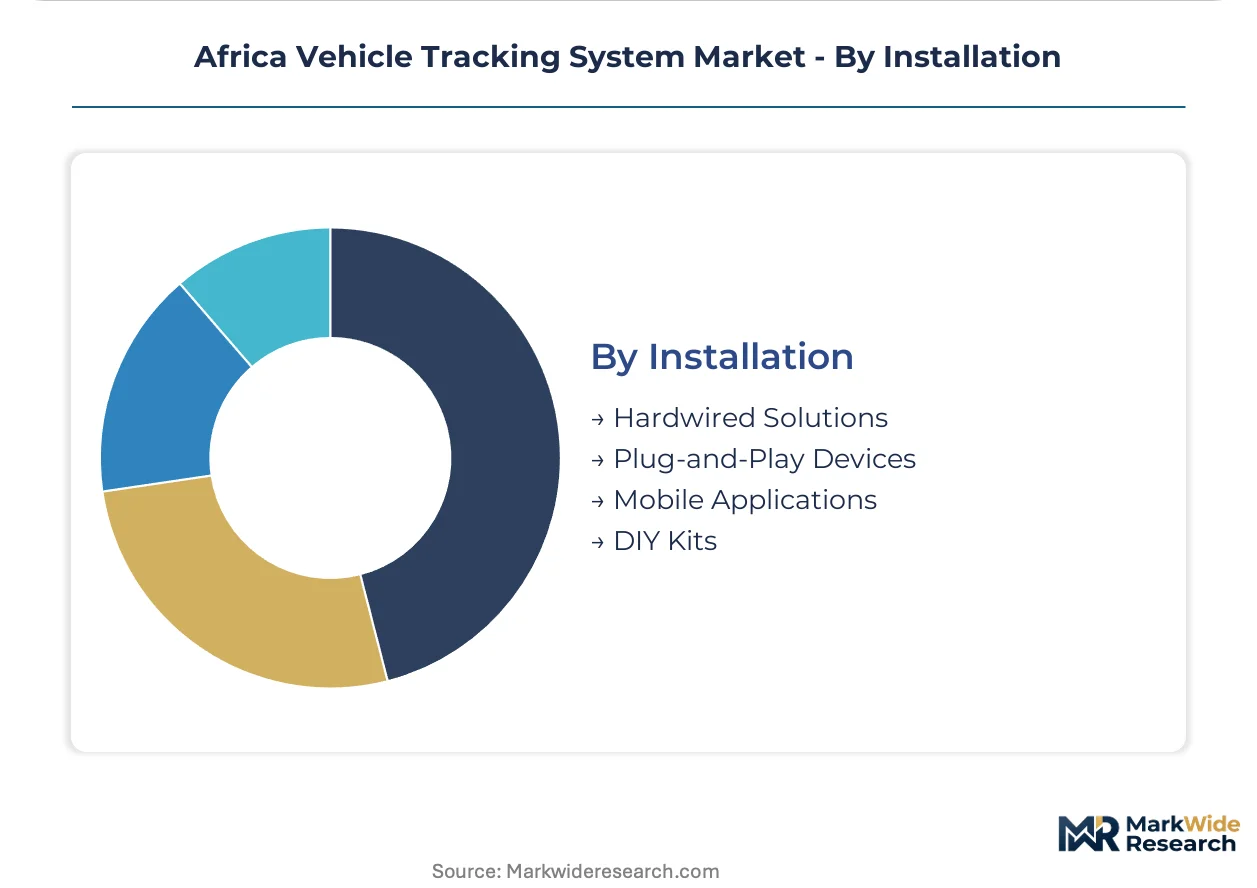
Installation:
Fitment method selection reflects regulatory enforcement intensity and fleet technical capabilities, with hardwired mandates reshaping installer network economics.
- Hardwired Solutions:Direct vehicle electrical system integration supports tamper-resistant compliance documentation required by Kenya's National Transport and Safety Authority for speed-governor pairing. Certified technician installation adds labor cost but satisfies insurance underwriter requirements in Nairobi and Mombasa matatu segments. Volume sits with hardwired; growth tilts toward plug-and-play among informal fleet operators.
- Plug-and-Play Devices:OBD port and cigarette lighter adapters enable rapid deployment without specialized labor. Nigerian petroleum distributors with mixed-vintage truck pools utilize these for retrofitting legacy vehicles lacking modern CAN bus architectures.
- Mobile Applications:Smartphone-based tracking leverages driver devices for basic location reporting, minimizing hardware capital for micro-fleet operators in informal urban logistics.
- DIY Kits:Self-installation packages appeal to individual vehicle owners in South Africa's stolen-vehicle recovery market seeking subscription cost reduction.
Hardwired installation dominates formal compliance segments; plug-and-play formats expand most quickly in retrofit-constrained legacy fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Coega Special Economic Zone near Port Elizabeth concentrates telematics hardware assembly for Southern African distribution, leveraging duty-free import privileges to offset tariff burdens on GPS modules.
South Africa
Johannesburg-based fleet operators deploy driver-behavior analytics to reduce diesel consumption on cross-border routes to Maputo and Gaborone. The National Regulator for Compulsory Specifications enforces type-approved stolen-vehicle recovery hardware fitment, compelling periodic compliance-driven upgrades. The Durban-Cape Town freight corridor hosts the continent's densest telematics installer networks serving container terminal logistics.
Nigeria
Lagos cargo underwriters mandate real-time visibility as a condition of freight liability coverage for last-mile operators. The Federal Road Safety Corps advances a proposed national vehicle registry linkage with telematics data that would reshape cross-border data sovereignty requirements. Petroleum distributors in the Niger Delta operate mixed-vintage truck pools requiring retrofit solutions for legacy CAN bus architectures.
Kenya
Nairobi and Mombasa matatu fleet lessors consolidate procurement through approved installer networks to maintain speed-governor compliance documentation. The National Transport and Safety Authority requires hardwired installation of combined tracking and speed-limiting devices on commercial passenger vehicles. The Northern Corridor transit route connecting Mombasa port to Kampala drives demand for hybrid satellite-cellular connectivity.
Ethiopia
The Addis Ababa-Djibouti rail-road intermodal expansion creates positioning opportunities for cold-chain telematics in pharmaceutical logistics. The country's national transport regulator maintains vehicle fitness certification programs that increasingly reference telematics integration. Industrial zones around Modjo Dry Port concentrate freight forwarding operations requiring cargo security demonstration to international insurers.
Zambia
Copperbelt mining contractors specify dual-mode satellite-cellular modems for equipment utilization optimization across remote extraction sites. The national road transport agency enforces commercial vehicle registration standards that incorporate tracking device specifications. Cross-border hauliers operating the Tazara corridor to Dar es Salaam face telemetry handoff challenges where terrestrial infrastructure terminates.
Africa Vehicle Tracking System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated service providers commanding premium tiers in stolen-vehicle recovery while hardware-assemblers serve price-sensitive fleet retrofit segments. The vendor base organizes into three archetypes: full-stack platform operators bundling hardware, connectivity and analytics; component suppliers selling white-label GPS modules to regional integrators; and mobile-network operators embedding telematics into enterprise data contracts. Consolidation pressure favors acquisition of installer networks and certification expertise over pure technology plays, while geographic expansion into Francophone West Africa represents the dominant competitive move for Southern African incumbents.
Among Southern African full-stack operators, Cartrack and Tracker anchor premium service tiers through vertically integrated stolen-vehicle-recovery infrastructure, while MiX Telematics occupies a position exemplifying specialized extractive-industry fleet solutions. These three represent distinct strategic postures: compliance-driven consumer retention, insurance-channel integration, and vertical-sector depth respectively.
| Leading Market Players |
|---|
| Cartrack |
| Tracker |
| Ctrack |
| Netstar |
| MiX Telematics |
| Geotab |
| TomTom Telematics |
| Verizon Connect |
| Fleet Complete |
| Others |
Cost & Logistics Intelligence
Semiconductor price indices for GPS chipsets cascade through three distinct pricing tiers in African vehicle tracking, with premium hardwired telematics units absorbing component volatility while economy OBD plug-ins pass cost swings directly to fleet lessors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to certified hardwired installations meeting Kenya's National Transport and Safety Authority speed-governor mandates, while spot inventory of cellular-only modules trades at discounts in Lagos grey markets. Three-tier pricing structure across premium, standard, and economy levels separates NRCS-type-approved stolen-vehicle recovery systems from fleet telematics and basic GPS trackers. Pricing pressure stems from Chinese module dumping through Kenyan and Nigerian customs regimes with cumulative duties exceeding 35%. Ride-hailing fleet lessors in Nairobi exhibit highest price sensitivity, prioritizing per-vehicle-month subscriptions over capital hardware purchases.
Supply Chain Analysis
Regional distribution centers in the Coega Special Economic Zone near Port Elizabeth anchor hub-and-spoke patterns serving Southern African Development Community markets. Manufacturing concentrates in China, Taiwan, and South Africa for GPS modules, cellular modems, and final assembly respectively. Raw material dependencies span semiconductor wafers, lithium-ion cells for backup power, and rare-earth magnets for antenna assemblies. Tariff exposure through stacked import duties on Chinese-manufactured components constitutes the dominant structural risk. Distribution runs through certified installer networks in formal compliance segments and informal electronics channels in retrofit-constrained markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware commoditization is forcing consolidation as margin compression eliminates pure-device vendors lacking software-layer differentiation or regulatory certification depth.
For Market Incumbents: Cement market position by acquiring certified installer networks in Nairobi and Lagos to control compliance documentation channels. Deepen backward integration into satellite connectivity partnerships that secure hybrid modem supply for cross-border mining contracts. MiX Telematics exemplifies vertical-sector defense through specialized oil-and-gas fleet solutions that sustain premium pricing against generic telematics entrants.
For New Entrants and Emerging Players: The premium-to-economy price gap in hardwired matatu installations offers white-space entry for certified technicians bundling speed-governor integration with tracking hardware. Target Ethiopian pharmaceutical cold-chain logistics as first-mover geography for temperature-monitoring telematics on the Addis Ababa-Djibouti corridor. Pursue white-label partnerships with mobile network operators embedding tracking into enterprise data contracts rather than competing for direct fleet procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated service providers with captive stolen-vehicle recovery infrastructure in Southern African high-theft urban corridors. Long-term viability over the next decade hinges on regulatory compliance depth rather than hardware innovation velocity. Watch Nigeria's Federal Road Safety Corps vehicle registry linkage proposals as the critical inflection signal for data sovereignty requirements reshaping platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Acquisition | Captures compliance documentation revenue from Kenya's NTSA speed-governor mandates. |
| Satellite-Cellular Hybrid Modem Development | Expands addressable market into trans-Sahelian mining routes beyond terrestrial coverage. |
| Speed-Governor Integration Partnership | Locks in matatu fleet procurement through combined regulatory compliance offerings. |
| Cold-Chain Telematics Platform Launch | Positions for Ethiopian pharmaceutical logistics on the Addis Ababa-Djibouti corridor. |
| Mobile Network Operator White-Label Agreement | Accesses ride-hailing fleet lessors through embedded enterprise data contracts. |
Research Approach
Regulatory filings from South Africa's National Regulator for Compulsory Specifications, Kenya's National Transport and Safety Authority enforcement bulletins, and Nigerian customs trade data formed the secondary backbone. Fleet procurement managers, certified telematics installers, and insurance underwriters in Johannesburg, Lagos, and Nairobi provided primary input through structured interviews. Bottom-up triangulation against top-down macroeconomic indicators validated volume estimates across the analysis window.
Historical trendline analysis of fleet telematics adoption rates informed projection modeling across product type, end user, technology, and installation method segments. CAGRs were derived from regression analysis of equipment fitment growth correlated with fuel price volatility and regulatory mandate implementation timelines. Forecast inputs incorporated cellular infrastructure expansion maps, satellite coverage footprints, and cross-border freight corridor development schedules.
Inputs from NTSA enforcement statistics and NRCS type-approval registries were available through the study window; gaps in informal fleet operator survey coverage introduce uncertainty bands around plug-and-play segment estimates. Forecasts reflect documented assumptions regarding regulatory implementation pace and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market