
 Automotive Fault Circuit Controllers Market | 2026-2036
Automotive Fault Circuit Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fault Circuit Controllers Market Analysis
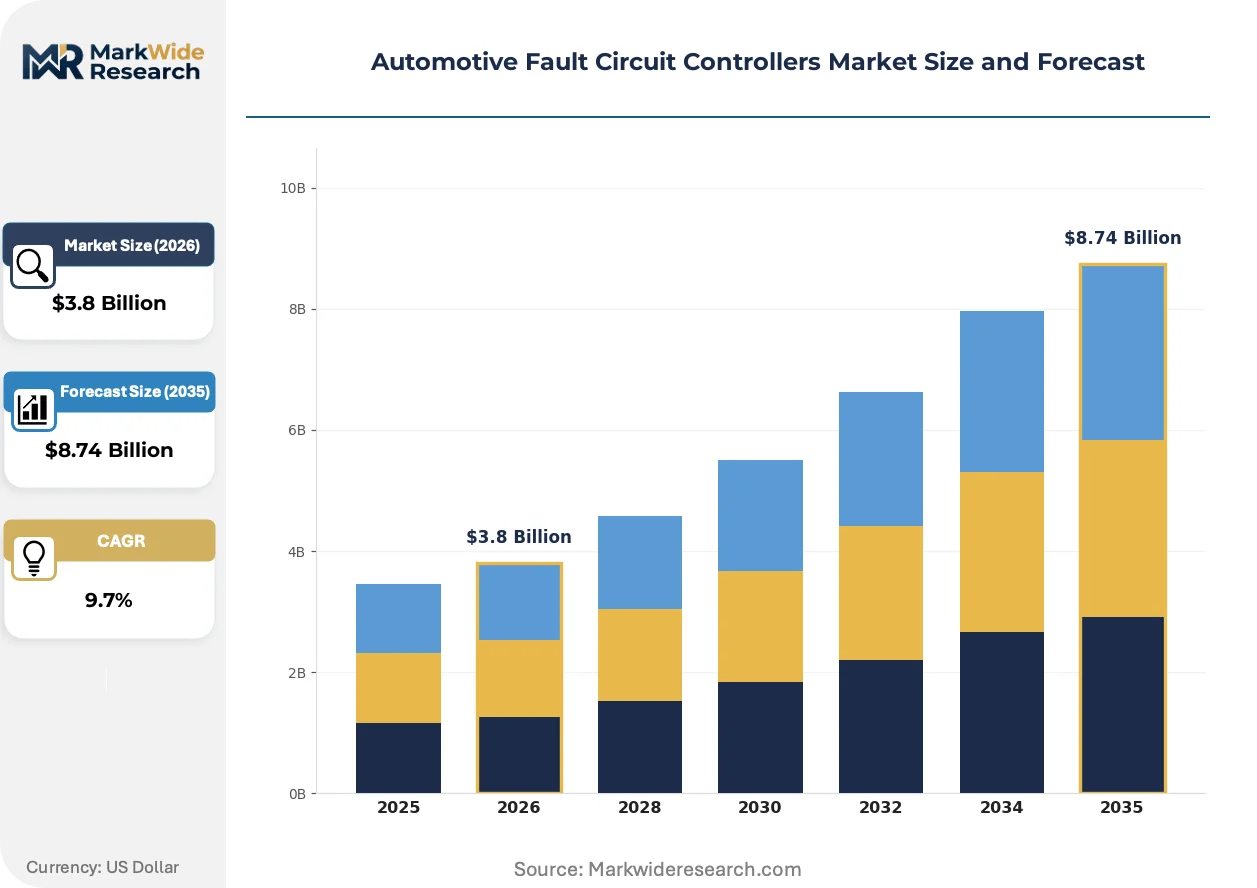
Tier-1 suppliers is reorganizing procurement priorities around fault circuit controllers as OEMs electrify vehicle architectures. Bosch Automotive Electronics leverages captive semiconductor fabrication to secure controller supply amid chip scarcity. Infineon Technologies anchors its position through silicon carbide expertise tied to high-voltage EV protection systems. STMicroelectronics competes across microcontroller-integrated fault detection platforms for hybrid powertrains.
Automotive fault circuit controllers are electromechanical or solid-state devices that monitor electrical pathways for overcurrent, short-circuit, or ground-fault conditions and interrupt power flow within milliseconds to prevent thermal runaway or fire propagation. These controllers typically integrate current sensors, logic gates, and power semiconductors rated for 400V to 800V operation in modern electric vehicle platforms. Relay controllers and circuit breakers now command the largest revenue pools as OEMs consolidate protection functions into modular assemblies. Digital and microcontroller-based technologies represent the fastest-expanding category, displacing analog architectures in premium EV segments where real-time diagnostics and over-the-air updates prove essential.
NHTSA in the United States, ECE R100 under United Nations Economic Commission for Europe frameworks, and China's GB/T standards collectively mandate functional safety thresholds for high-voltage circuit protection in electrified vehicles. These regulations force suppliers to certify controllers against ISO 26262 automotive safety integrity levels, creating barriers for entrants lacking embedded software validation capabilities. Stakeholders must track how battery platform voltages evolve beyond 800V, as this threshold will determine whether silicon-based or wide-bandgap semiconductor architectures dominate the next controller generation.
Market Dynamics
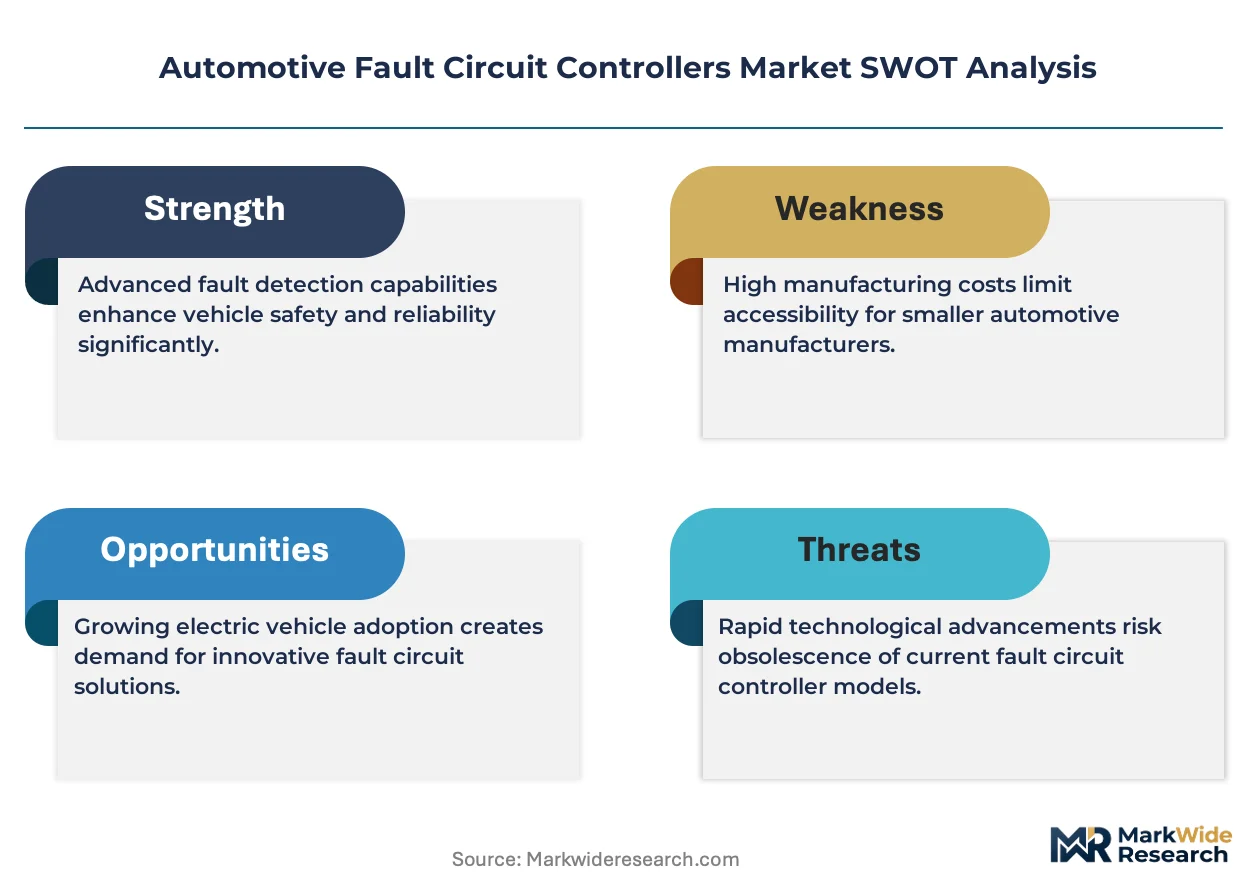
Powertrain electrification is forcing automotive OEMs to consolidate high-voltage protection functions into fewer, more intelligent modules, compressing supplier tiers and raising software certification barriers.
Growth Catalysts
- EU Green Deal:The framework mandates carbon-neutral vehicle fleets by 2035, accelerating OEM procurement of fault circuit controllers for battery-electric architectures.
- Solid-state semiconductor migration:Silicon carbide and gallium nitride devices enable faster fault interruption times, opening design wins in 800V EV platforms.
- Germany-Japan-South Korea electronics clusters:Dense concentrations of tier-1 R&D headquarters concentrate controller innovation and OEM validation partnerships.
Market Restraints
- Wafer supply concentration:Captive silicon carbide substrate production remains concentrated among three integrated device manufacturers, constraining controller output scaling.
- ISO 26262 validation costs:Functional safety certification for ASIL-D controllers demands 18-24 month validation cycles and seven-figure tooling investments.
- Analog controller residual demand:Cost-optimized hybrid vehicles in emerging markets sustain demand for legacy electromechanical protection, delaying full digital transition.
Strategic Opportunities
- Over-the-air diagnostic integration:Microcontroller-based controllers with embedded telemetry enable predictive maintenance revenue streams and remote parameter updates.
- India automotive electrification:PLI scheme subsidies for domestic EV manufacturing create localized controller demand outside established supply chain hubs.
- Bidirectional charging protection:Vehicle-to-grid architectures require new fault detection topologies for reverse power flow scenarios.
Industry Challenges
- Embedded software talent scarcity:Functional safety firmware engineers with automotive experience command premium compensation and extended recruitment timelines.
- Legacy 12V system integration:New high-voltage controllers must coexist with decades-old electrical architectures without false-trip interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fault Circuit Controllers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relay Controllers, Fuses, Circuit Breakers, Sensors Technology: Analog, Digital, Hybrid, Microcontrollers End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Service Centers Application: Electric Vehicles, Hybrid Vehicles, Internal Combustion Engines, Heavy-duty Vehicles |
| Companies Covered | Bosch Automotive Electronics, Continental, Denso, Infineon Technologies, ABB, Siemens AG, Eaton Corporation, Texas Instruments, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fault Circuit Controllers Market Emerging Trajectories
Fault detection architectures are bifurcating between centralized battery management integration and distributed edge-computing nodes, with semiconductor material choices determining performance ceilings.
Silicon carbide MOSFETs are fragmenting the incumbent IGBT-dominated protection landscape. These wide-bandgap devices switch at frequencies above 100kHz, enabling sub-millisecond fault isolation. Premium EV manufacturers in Germany and Japan are qualifying SiC-based controllers for 800V battery platforms. The technology is fragmenting procurement patterns, as OEMs now dual-source silicon and SiC variants to hedge against substrate supply volatility.
ECE R100 revision cycles are compressing controller redesign timelines. The United Nations regulation mandates updated short-circuit withstand tests for high-voltage systems, forcing suppliers to revalidate thermal models. European OEMs are pre-certifying controllers against anticipated 2027 amendments. This regulatory compression favors incumbents with established homologation relationships.
Fleet operators are consolidating controller procurement through battery-leasing structures rather than discrete component purchasing. Commercial vehicle buyers in North America and Europe now specify protection performance as a service-level metric within total-cost-of-ownership contracts. This model transfers technical risk to tier-1 suppliers and accelerates standardization around modular, swappable controller designs.
Automotive Fault Circuit Controllers Market Segmentation
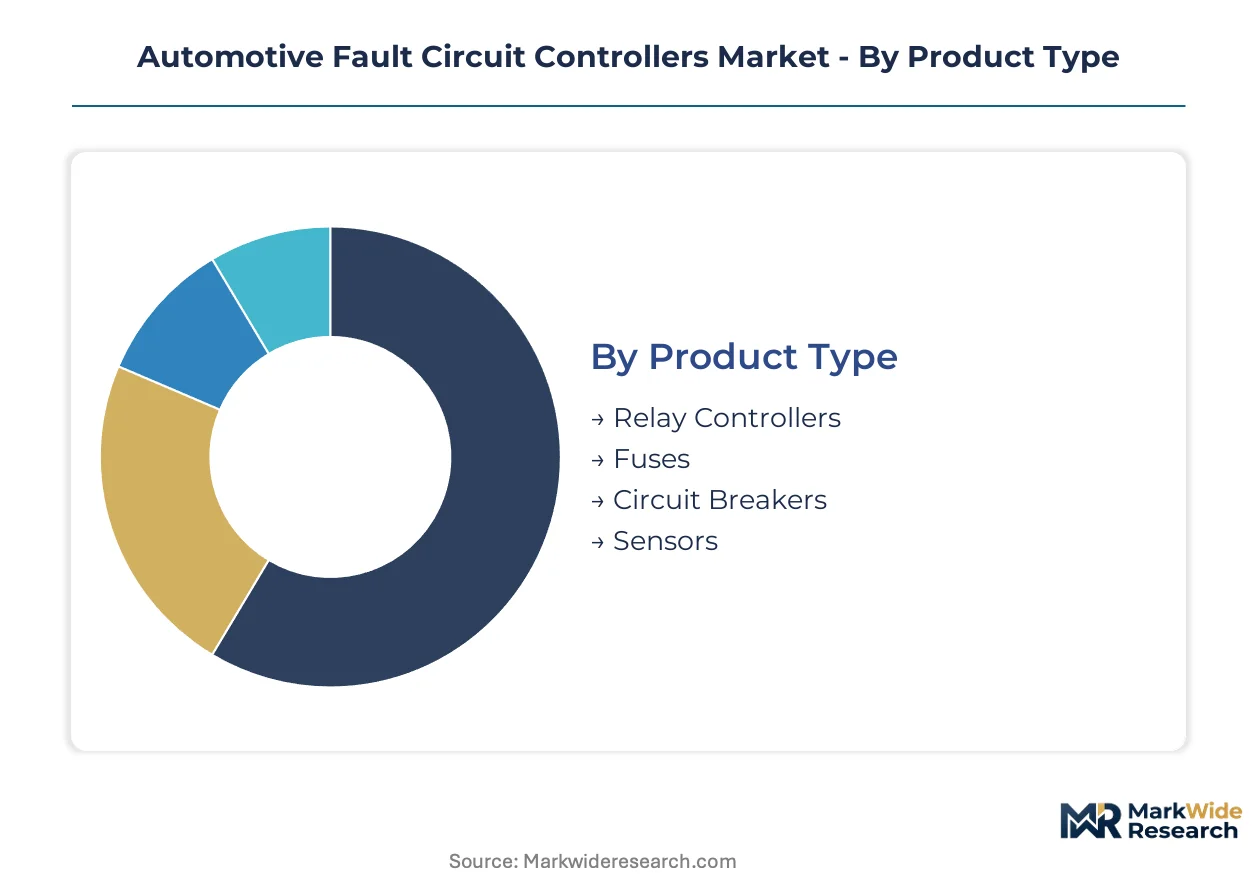
Fault circuit controller procurement patterns diverge sharply across product architectures and customer types. Technology choices determine semiconductor content and software certification burden, while application mix shapes voltage ratings and thermal management requirements.
Product Type:
Relay controllers and circuit breakers face intensifying substitution pressure from solid-state alternatives as silicon carbide costs decline, while fuses and sensors retain residual demand in cost-optimized vehicle segments.
- Relay Controllers:Electromechanical switching devices rated for 400V to 800V operation dominate high-current pathways in battery-electric powertrains. German and Japanese OEMs specify these for main contactor functions where mechanical isolation provides definitive safety assurance.
- Circuit Breakers:Resettable protection devices with thermal-magnetic trip characteristics serve hybrid vehicle architectures where service accessibility matters. South Korean tier-1 suppliers integrate these into modular battery disconnect units for 400V platforms.
- Fuses:Single-use overcurrent protection remains specified in emerging market hybrids where component cost sensitivity overrides maintenance convenience.
- Sensors:Current and voltage sensing elements feed diagnostic data to battery management systems, with Hall-effect architectures displacing shunt resistors in 800V applications.
Relay controllers anchor the volume base while circuit breakers gain share at the steepest rate as hybrid production scales.
Technology:
Controller architectures stratify by software complexity and functional safety certification tier, with cost structures separating premium EV platforms from mass-market hybrids.
- Analog:Discrete component designs with fixed trip thresholds persist in 12V legacy systems and entry-level hybrids where microcontroller overhead is uneconomical.
- Digital:Programmable logic devices with configurable protection curves enable OEM-specific calibration without hardware redesign. These controllers concentrate in mid-range battery-electric vehicles from Chinese and European manufacturers.
- Hybrid:Mixed-signal architectures combine analog sensing front-ends with digital processing cores, offering a migration path for suppliers serving both legacy and next-generation platforms.
- Microcontrollers:Integrated fault detection platforms with embedded ASIL-D firmware support over-the-air updates and predictive diagnostics. Infineon and STMicroelectronics compete most aggressively in this tier for 800V EV design wins.
Analog architectures retain the installed base while microcontroller-based systems expand most quickly in premium electrified segments.
End User:
Procurement authority is consolidating upward as OEMs internalize high-voltage system design responsibility, compressing traditional tier-1 and tier-2 boundaries.
- OEMs:Vehicle manufacturers increasingly specify controller performance requirements directly, bypassing tier-1 intermediaries for strategic electrification components. Volkswagen and Hyundai have established captive controller qualification programs.
- Tier-1 Suppliers:Bosch, Denso, and Continental aggregate controller procurement into powertrain module assemblies, wielding volume leverage over semiconductor vendors.
- Aftermarket Providers:Independent distributors serve collision repair and refurbishment demand, though high-voltage safety training requirements limit channel participation.
- Service Centers:Authorized dealer networks handle warranty-related controller replacement, with diagnostic equipment investments creating switching costs.
Tier-1 suppliers command the revenue concentration while OEM direct procurement climbs fastest as platform architectures consolidate.
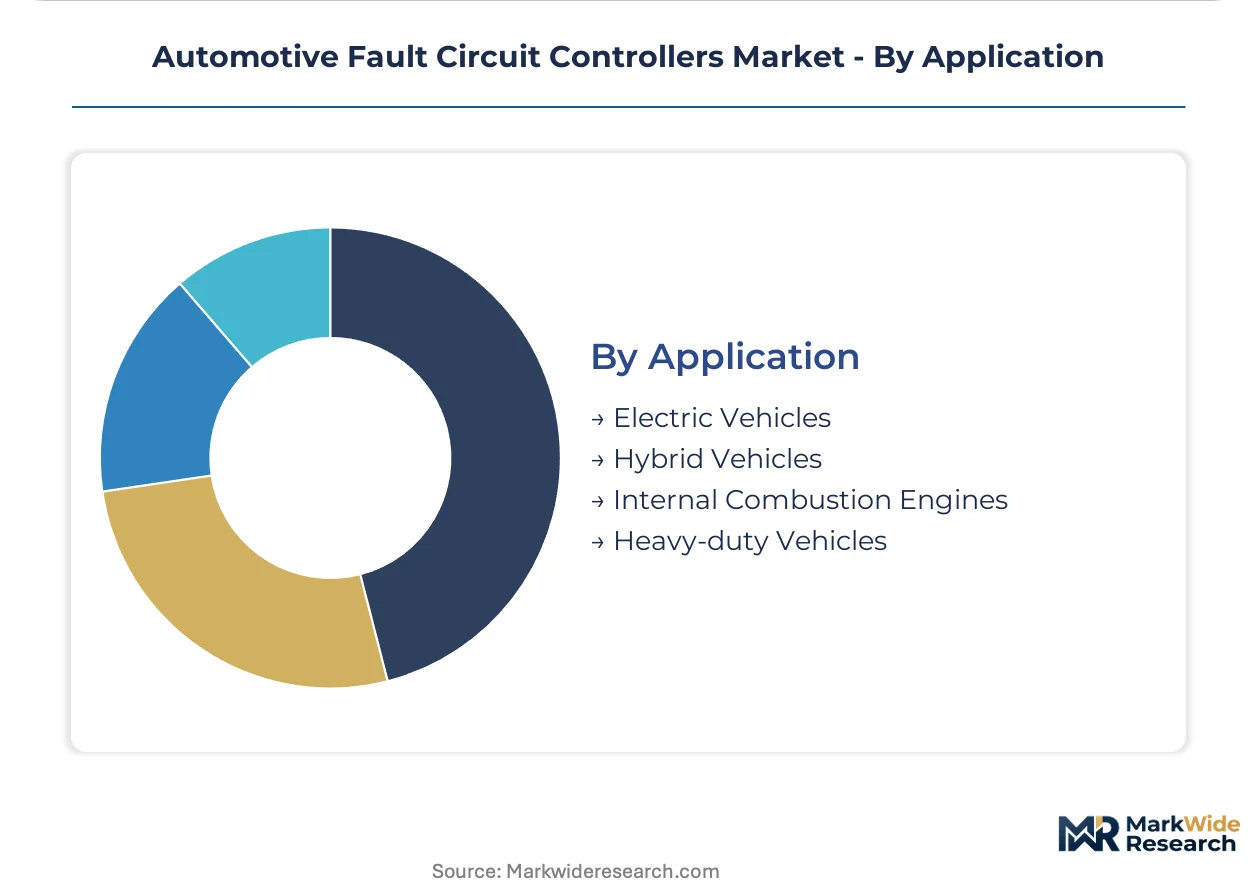
Application:
Voltage platform differentiation creates distinct controller specification clusters, with thermal runaway protection mandates tightening fastest in passenger electric vehicles.
- Electric Vehicles:Battery-electric architectures demand 800V-rated controllers with sub-millisecond interruption capability. ECE R100 and China's GB/T standards mandate specific short-circuit withstand tests for this segment.
- Hybrid Vehicles:Dual-voltage systems combining 400V traction batteries with 12V auxiliary networks require controllers with cross-domain isolation. Japanese OEMs lead qualification of compact hybrid-specific protection modules.
- Internal Combustion Engines:Legacy 12V electrical systems sustain demand for conventional relay and fuse technologies, though volumes contract as powertrain electrification accelerates.
- Heavy-duty Vehicles:Commercial truck and bus electrification imposes extended duty cycle requirements, with controllers specified for million-cycle mechanical endurance.
Internal combustion applications retain the largest installed base while electric vehicle controllers demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-1 suppliers export fault circuit controllers to electrification programs in China and North America, establishing the primary trade-flow corridor for high-voltage protection hardware.
United States
NHTSA mandates functional safety thresholds for high-voltage circuit protection, accelerating OEM validation cycles. The Inflation Reduction Act subsidizes domestic EV battery manufacturing, expanding controller demand in Michigan and Ohio assembly corridors. Detroit-based engineering centers coordinate qualification programs with German semiconductor vendors.
Germany
Stuttgart and Munich host the densest concentrations of automotive electronics R&D, with OEMs consolidating procurement into modular powertrain assemblies. KBA enforces ECE R100 homologation standards, compressing redesign timelines for 800V platforms. Bavarian semiconductor fabs supply silicon carbide substrates to captive controller production lines.
China
GB/T standards mandate short-circuit withstand tests for battery-electric architectures, forcing suppliers to recertify thermal models. MIIT production quotas for NEVs drive controller procurement from Yangtze River Delta battery plants. Shanghai-based tier-1s integrate protection functions into platform-scale module assemblies.
Japan
Hybrid vehicle architectures sustain demand for compact dual-voltage protection modules from Nagoya and Tokyo engineering clusters. METI subsidies for solid-state battery development cascade into controller specification updates. Toyota and Honda captive suppliers qualify mixed-signal architectures for 400V traction systems.
South Korea
Seoul Capital Area battery manufacturers specify 800V-rated controllers with sub-millisecond interruption capability for export-bound EV platforms. MFDS-aligned safety protocols align with ECE R100 frameworks, easing European homologation. Busan-Ulsan industrial corridors concentrate module assembly for Hyundai-Kia electrification programs.
Automotive Fault Circuit Controllers Market Vendor Landscape
Player mix skews toward diversified automotive electronics conglomerates with captive semiconductor fabrication or deep tier-1 integration. The supplier base concentrates around three strategic archetypes: integrated device manufacturers controlling substrate supply, tier-1 module assemblers wielding OEM volume leverage, and specialized semiconductor vendors competing on silicon carbide expertise. Dominant competitive moves include backward integration into wafer production and strategic partnerships for 800V platform co-development.
Among Germany-based diversified industrials, Bosch Automotive Electronics and Siemens AG occupy positions spanning module assembly through semiconductor supply. Infineon Technologies anchors the specialist tier with wide-bandgap device expertise tied to high-voltage protection systems. STMicroelectronics exemplifies the microcontroller-integrated platform archetype competing for premium EV design wins. These three represent distinct competitive vectors: captive fabrication, silicon carbide specialization, and embedded software integration.
| Leading Market Players |
|---|
| Bosch Automotive Electronics |
| Continental |
| Denso |
| Infineon Technologies |
| ABB |
| Siemens AG |
| Eaton Corporation |
| Texas Instruments |
| STMicroelectronics |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with silicon carbide substrate manufacturers lock in supply access for tier-1 suppliers while providing multi-year price visibility against raw material volatility. These arrangements concentrate procurement leverage among German and South Korean module assemblers who can commit to volume thresholds that emerging entrants cannot match.
Pricing Analysis
The technology-generation pricing gap separates legacy analog controllers from microcontroller-integrated platforms and emerging silicon carbide-based designs. Pricing stratifies across premium, standard, and economy tiers based on ASIL certification grade and volume commitment scale. Pricing pressure stems from ISO 26262 validation costs transferring downstream to module assemblers. Fleet operators demonstrate lowest price sensitivity due to total-cost-of-ownership contracting, while emerging market hybrid OEMs remain most cost-constrained.
Supply Chain Analysis
Inventory buffers for silicon carbide wafers stretch to 26-32 weeks as substrate production concentrates among German, Japanese, and United States integrated device manufacturers. Controller assembly draws from silicon carbide substrates, copper busbars, and automotive-grade microcontroller units. Single-source vulnerability persists at the substrate level where three manufacturers control captive production. Distribution runs through tier-1 powertrain module assemblers who consolidate controller procurement into platform-scale assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating upward as OEMs internalize high-voltage system design responsibility, compressing traditional tier boundaries and forcing suppliers to accept performance-based contracting terms.
For Market Incumbents: Consolidate silicon carbide substrate supply through backward integration or exclusive offtake agreements to defend against emerging wide-bandgap specialists. Lock in ASIL-D certification pipelines ahead of ECE R100 revision cycles to create regulatory compliance barriers for challengers lacking validation infrastructure. For New Entrants and Emerging Players: Differentiate on over-the-air diagnostic capabilities for India's PLI-subsidized EV manufacturing programs, where incumbent presence remains underdeveloped. Target aftermarket service centers with plug-and-play controller modules that reduce high-voltage safety training investments. Lead with bidirectional charging protection as vehicle-to-grid architectures expand. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors semiconductor specialists with silicon carbide device expertise over legacy electromechanical suppliers. Long-term viability hinges on embedded software capabilities and functional safety certification infrastructure. Watch for battery platform voltage migration beyond 800V as the inflection signal determining wide-bandgap semiconductor dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive wafer production secures controller supply amid substrate scarcity concentrated in Germany and Japan. |
| ASIL-D Certification Pipeline Investment | Functional safety validation creates 18-24 month barriers against entrants lacking embedded software capabilities. |
| Over-the-Air Diagnostic Platform Development | Predictive maintenance revenue streams differentiate microcontroller-based controllers in premium EV segments. |
| India Manufacturing Localization Partnership | PLI scheme subsidies enable cost-competitive production outside established German-Japanese supply chain hubs. |
| Bidirectional Charging Protection R&D | Vehicle-to-grid fault detection topologies address reverse power flow scenarios in emerging energy trading markets. |
Methodological Framework
The analysis maps relay controllers, circuit breakers, solid-state protection modules, and sensing elements, each validated through primary engagement with OEM platform engineers, tier-1 procurement directors, semiconductor device specialists, and aftermarket service technicians. Secondary sources include ECE R100 regulatory filings, NHTSA safety recall databases, MIIT production quota disclosures, and vehicle registration data from IHS Markit. Bottom-up component demand modeling triangulates against top-down OEM electrification platform forecasts.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor vendor shipment disclosures and battery-electric vehicle production tracking. The forecast framework segments by propulsion architecture, voltage platform tier, functional safety certification level, and regional production cluster. CAGRs derive from installed base replacement cycles and content-per-vehicle scaling across hybrid and battery-electric platforms. Key inputs include silicon carbide device adoption curves and ISO 26262 certification timeline assumptions.
Forecasts assume regulatory continuity in ECE R100, GB/T, and NHTSA frameworks; material policy shifts around short-circuit withstand testing or functional safety thresholds would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Interface Chip Market