
 Plastic Lubricants Market | 2026-2036
Plastic Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Lubricants Market Outlook
The capital-intensity gap between integrated petrochemical majors and specialty additive houses is collapsing as backward integration into base-stock refining becomes table stakes. ExxonMobil leverages its integrated polyethylene and polypropylene value chains to captive-supply wax-based lubricant feedstocks. FUCHS anchors its position through dedicated R&D centers for polymer-processing chemistry. Evonik Industries AG differentiates via high-performance ester additives engineered for engineered plastics compatibility.
Plastic lubricants comprise formulated products—typically synthetic esters, polyalphaolefins, or refined hydrocarbon waxes blended with polar additives—that reduce friction between polymer melts and metal surfaces during injection molding, extrusion, and thermoforming operations. These formulations operate at temperatures between 150°C and 350°C while maintaining thermal stability and leaving minimal residue on finished parts. Oil-based formulations currently dominate volume in automotive and industrial equipment applications where continuous high-temperature processing demands consistent film strength. Wax-based segments lead margin pools in consumer goods molding, where food-contact compliance and surface finish quality command specification premiums. Grease-based pastes concentrate in construction-related extrusion of PVC profiles and weatherseals, where anti-seize properties between die walls and polymer stock prove critical.
The U.S. EPA regulates volatile organic compound emissions from lubricant formulations under 40 CFR 59, while REACH restricts certain chlorinated paraffin carriers historically common in plastic lubricant bases. The EU F-Gas Regulation indirectly pressures fluoropolymer lubricant alternatives by constraining perfluorinated compound production inputs. Stakeholders must monitor pending amendments to FDA 21 CFR 178.3570 for incidental food-contact lubricants, as these standards increasingly determine qualification for packaging and consumer goods molding contracts.
Market Dynamics
REACH's tightening volatile organic compound limits are forcing wholesale reformulation across European polymer processing, while automotive OEMs simultaneously demand faster injection molding cycle times that only high-performance synthetic esters can deliver.
Growth Catalysts
- Automotive lightweighting mandates:OEMs specify plastic lubricants enabling thinner-wall molding of structural polymer components to meet Corporate Average Fuel Economy standards in the United States.
- REACH Annex XVII restrictions:Chlorinated paraffin bans accelerate migration toward bio-based ester formulations that processors in Germany's tool-and-die corridor now require for contract qualification.
- Extrusion speed targets:PVC profile manufacturers adopt high-temperature stable lubricants to push line speeds beyond 40 meters per minute in construction weatherseal production.
Market Restraints
- Feedstock concentration:Polyalphaolefin base stocks depend on ethylene oligomerization capacity concentrated along the U.S. Gulf Coast, exposing formulators to hurricane-related supply disruptions.
- Technical ceiling:Existing synthetic esters thermally degrade above 320°C, limiting their deployment in engineering plastics processing such as PEEK and PPS injection molding.
- Substitution pressure:Internal mold release coatings from fluoropolymer suppliers capture specification share in high-precision optical polymer molding where residue-free surfaces are mandatory.
Strategic Opportunities
- Bio-based ester white space:Castor oil-derived formulations qualify for USDA BioPreferred procurement preferences in federal packaging contracts currently underpenetrated by specialty lubricant houses.
- Medical device molding:FDA 21 CFR 178.3570 compliance for incidental food-contact lubricants transfers directly to ISO 13485 medical polymer processing, opening device component manufacturing.
- Digital formulation platforms:Machine learning tools that predict polymer-lubricant compatibility are compressing R&D cycles from 18 months to 90 days for custom compounders.
Industry Challenges
- Tribochemistry expertise scarcity:Formulators struggle to recruit polymer rheologists who understand both metal-polymer interface physics and additive chemistry at processing temperatures.
- Dual certification timelines:Simultaneous FDA food-contact and EPA Safer Choice qualification requires 24-36 month documentation cycles that delay new product commercialization.
- Legacy equipment incompatibility:Older extrusion lines lack closed-loop temperature control needed for next-generation low-residue lubricants, forcing processor capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Lubricants Market |
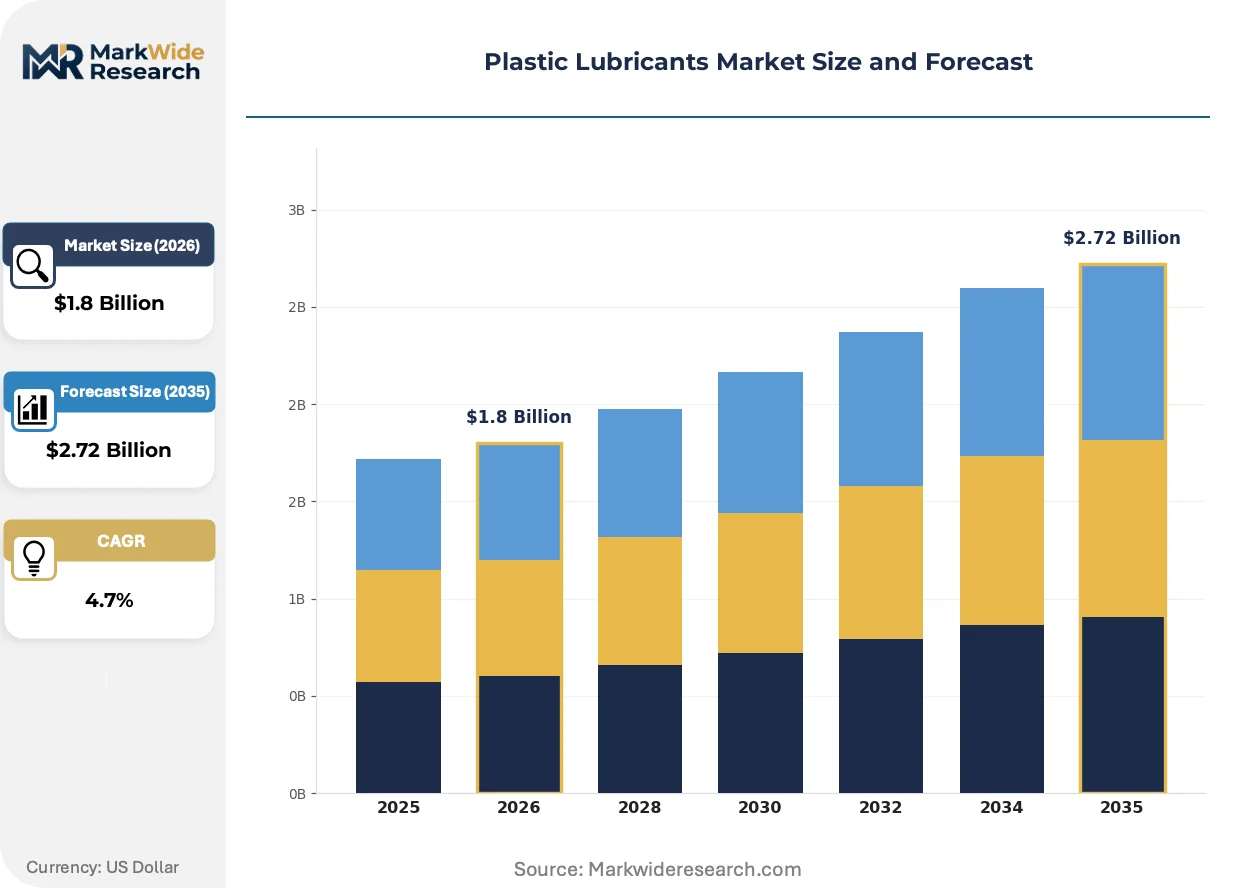
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax-based, Oil-based, Grease-based, Additives Application: Automotive, Industrial Equipment, Consumer Goods, Construction Form: Liquid, Paste, Solid, Emulsion End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, FUCHS, BP PLC, TotalEnergies, Phillips 66 Company, Valvoline, LANXESS, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Lubricants Market Strategic Shifts
Synthetic base-stock innovation and regulatory chemistry mandates are compressing formulation development cycles while simultaneously elevating performance thresholds for thermal stability and residue control.
Polyalkylene glycol synthetic lubricants are displacing hydrocarbon waxes in high-temperature nylon and PBT molding where oxidative stability above 300°C prevents carbon deposit formation on hot runner systems. Tier-1 automotive suppliers in Stuttgart and Detroit have adopted these formulations for under-hood component production. The shift is compressing margin pools for traditional paraffin-based suppliers while expanding addressable volume in engineering plastics processing.
EPA's 40 CFR 59 National Volatile Organic Compound Emission Standards for Consumer Products now capture plastic lubricant aerosol formulations, forcing repackaging into bulk liquid delivery systems for mold sprayers. Industrial compounders in Ohio and Michigan have converted spray lines to precision pump systems to maintain compliance. The regulation is accelerating consolidation among regional distributors unable to absorb packaging infrastructure reinvestment costs.
Specification-driven procurement now dominates polymer processing contracts, with OEM technical teams mandating lubricant brands qualified to specific resin systems rather than leaving selection to mold shop discretion. This pattern concentrates volume with formulators holding broad polymer-compatibility portfolios. The behavior is most visible in Germany's precision engineering corridor, where automotive tier suppliers enforce approved-materials lists that exclude unqualified lubricant alternatives.
Plastic Lubricants Market Segmentation
Plastic lubricant procurement diverges sharply across processing temperatures, regulatory exposure, and surface-finish requirements. Specification engineers select formulations based on polymer melt behavior, metal surface compatibility, and residue tolerance thresholds unique to each end-use environment.
Product Type:
REACH Annex XVII chlorinated paraffin restrictions and FDA 21 CFR 178.3570 food-contact standards create divergent compliance burdens across formulation chemistries, pushing processors toward synthetic esters in regulated applications while wax-based products retain position in cost-sensitive molding.
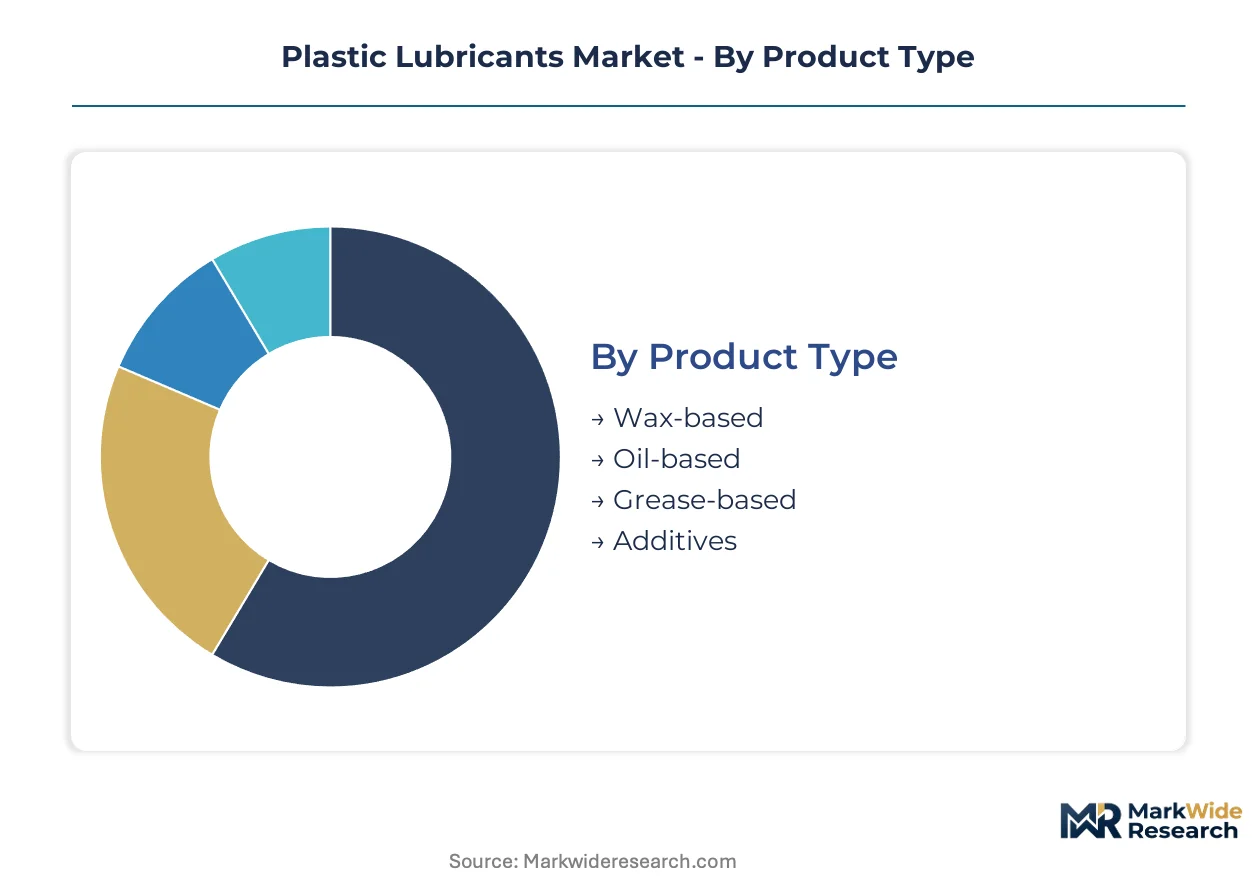
- Wax-based:Refined hydrocarbon and synthetic wax formulations deliver food-contact compliance and premium surface finish in consumer goods packaging. German tool-and-die shops specify these grades for high-clarity polycarbonate molding where residue-free demolding commands specification premiums.
- Oil-based:Synthetic esters and polyalphaolefins maintain thermal stability between 150°C and 320°C in continuous high-temperature processing. Automotive under-hood component manufacturers in Stuttgart and Detroit rely on these formulations for nylon and PBT injection molding where oxidative stability prevents carbon deposit formation.
- Grease-based:Anti-seize paste formulations concentrate in PVC profile extrusion where die wall adhesion resistance proves critical.
- Additives:Polar ester and friction-modifier concentrates enable custom compounding for engineered plastics compatibility.
Established volume favors oil-based formulations; emerging adoption favors wax-based segments climbing the fastest on food-contact compliance mandates.
Application:
Automotive lightweighting mandates and construction extrusion speed targets generate divergent performance specifications, with OEMs demanding sub-30-second cycle times while profile manufacturers prioritize line-speed economics above thermal ceiling.
- Automotive:Tier-1 suppliers specify high-performance synthetic esters enabling thinner-wall structural polymer molding to meet Corporate Average Fuel Economy standards. Under-hood component production in Michigan and Baden-Württemberg drives specification upgrades for heat-resistant formulations.
- Industrial Equipment:Continuous processing environments favor thermally stable lubricants with extended fluid life in high-throughput extrusion systems.
- Consumer Goods:Food-contact compliance and aesthetic surface requirements concentrate demand in wax-based segments for packaging applications.
- Construction:PVC weatherseal and profile manufacturers adopt high-temperature stable lubricants to push extrusion line speeds beyond 40 meters per minute.
Procurement concentration sits with automotive; margin expansion favors construction as speed targets intensify.
Form:
EPA 40 CFR 59 aerosol regulations and processor infrastructure legacy determine delivery system selection, with bulk liquid systems displacing spray formats in U.S. facilities while paste and solid forms retain position in specialized die lubrication.
- Liquid:Pump-delivery systems dominate high-volume injection molding where precise metering controls lubricant film thickness. Ohio and Michigan compounders converted spray lines to precision pump systems to maintain EPA compliance.
- Paste:Grease-based formats concentrate in construction extrusion and large-diameter pipe manufacturing where manual die application remains economical.
- Solid:Wax sticks and bars serve specialty thermoforming operations with intermittent lubrication requirements.
- Emulsion:Water-based dispersions address low-temperature molding and environmental discharge constraints in selected European processors.
Liquid forms capture volume leadership; paste formats defend niche positions in heavy-profile extrusion.
End User:
Specification authority migration from mold shops to OEM technical teams restructures channel economics, with manufacturers capturing direct procurement relationships while distributors consolidate around technical service capabilities.
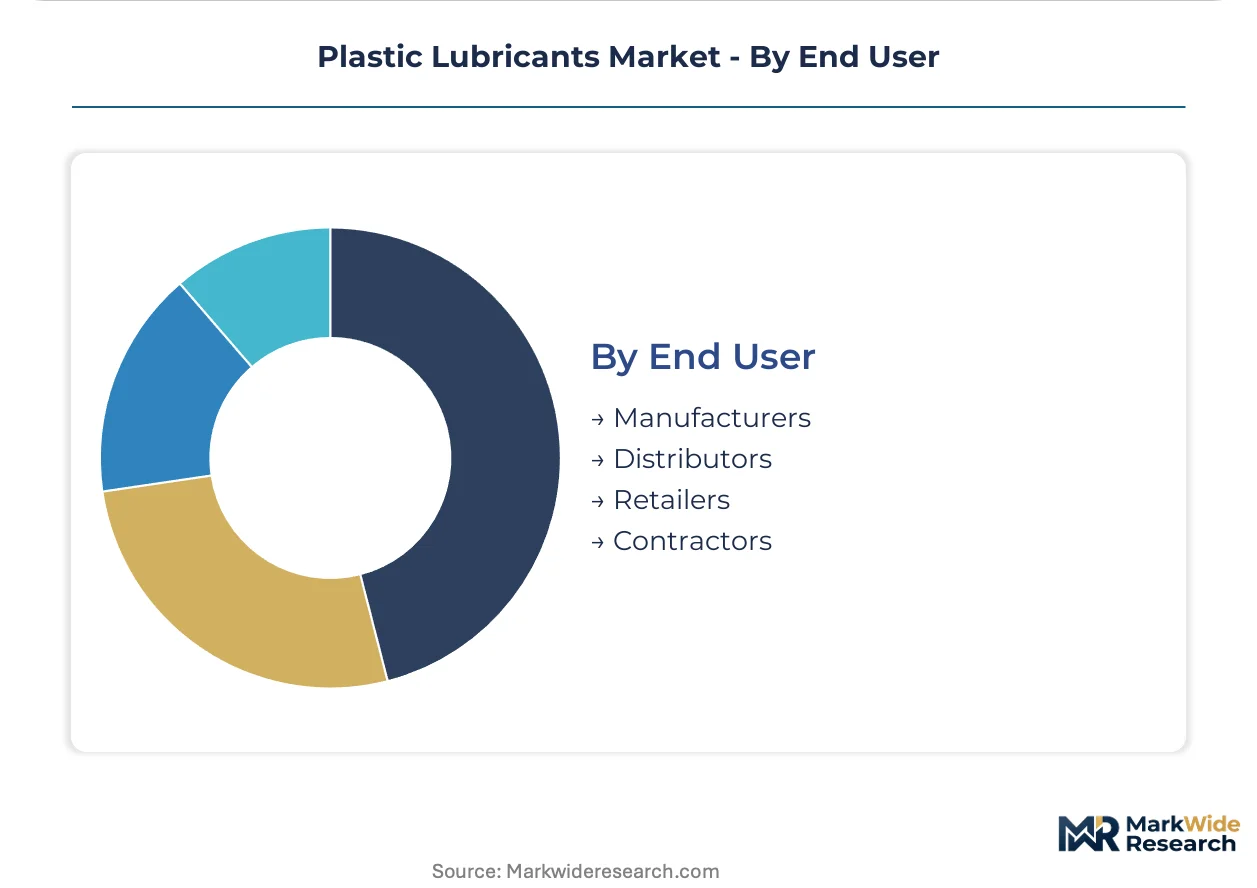
- Manufacturers:Automotive tier suppliers and packaging converters now mandate approved-materials lists that exclude unqualified lubricant alternatives. Germany's precision engineering corridor exhibits this pattern most visibly.
- Distributors:Regional compounders absorb packaging infrastructure reinvestment costs to maintain EPA compliance, accelerating consolidation among smaller players.
- Retailers:Specialty lubricant houses serve maintenance and repair operations with packaged goods for legacy equipment.
- Contractors:Construction extrusion operators procure bulk paste formulations for field-based PVC profile production.
Direct procurement concentrates with manufacturers; distributor relevance depends on technical formulation support capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tool-and-die shops command specification premiums that outprice comparable North American compounders by 15-20 percent. This pricing-power asymmetry reflects tighter REACH compliance burdens and automotive OEM direct-procurement authority concentrated in Baden-Württemberg.
United States
Automotive lightweighting mandates from NHTSA drive synthetic ester adoption for thinner-wall structural polymer molding. EPA 40 CFR 59 aerosol regulations force bulk liquid conversion across Ohio and Michigan extrusion facilities. Detroit-area tier suppliers enforce approved-materials lists that exclude unqualified lubricant alternatives.
Germany
Precision engineering corridors in Baden-Württemberg and North Rhine-Westphalia specify high-performance formulations for sub-30-second injection molding cycle times. REACH Annex XVII chlorinated paraffin bans accelerate bio-based ester migration. Stuttgart's automotive tier-1 suppliers mandate lubricant brands qualified to specific resin systems.
China
Domestic automotive production growth propels demand for thermally stable lubricants in nylon and PBT under-hood component molding. MIIT industrial upgrading guidelines favor synthetic base stocks over legacy hydrocarbon waxes. Yangtze River Delta processors adopt polyalkylene glycol formulations for high-temperature engineering plastics.
Japan
METI energy-efficiency standards for manufacturing equipment incentivize low-friction lubricant deployment in continuous extrusion systems. Osaka-based packaging converters prioritize food-contact compliant wax formulations for high-clarity polycarbonate molding. Kansai industrial clusters drive specification upgrades for surface-finish-critical applications.
India
Plastics Processing Machinery Manufacturing clusters in Gujarat and Maharashtra absorb imported synthetic ester formulations for automotive component exports. BIS standards for industrial lubricants gradually align with REACH-equivalent volatile organic compound limits. Pune and Ahmedabad mold shops upgrade specifications to qualify for European OEM supply contracts.
Plastic Lubricants Market Competitive Environment
Concentration sits with integrated petrochemical majors that captive-supply base-stock feedstocks through backward integration into polyethylene and polypropylene value chains. Specialty additive houses anchor positions through dedicated polymer-processing R&D centers. Three archetypes dominate: integrated oil majors with captive wax supply, European specialty chemical houses with ester chemistry expertise, and regional compounders serving legacy equipment segments. Competitive moves center on portfolio diversification into bio-based formulations and strategic partnerships with automotive OEM technical teams.
Among integrated oil majors, ExxonMobil Corporation and Chevron Corporation exemplify the captive-feedstock archetype through their polyethylene and polypropylene value chain control. FUCHS occupies a position representing the European specialty house model with dedicated polymer-processing chemistry capabilities. Evonik Industries AG anchors the high-performance additive tier through ester chemistry engineering for engineered plastics compatibility. These three players illustrate the strategic divergence between scale-driven base-stock control and formulation-level technical differentiation.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| FUCHS |
| BP PLC |
| TotalEnergies |
| Phillips 66 Company |
| Valvoline |
| LANXESS |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for polyalphaolefin base stocks concentrate pricing power with integrated petrochemical majors along the U.S. Gulf Coast, while specialty additive houses absorb margin compression from REACH-driven reformulation costs. This lead-time asymmetry rewards backward-integrated suppliers with captive polyethylene value chains and exposes regional compounders to feedstock volatility.
Pricing Analysis
Configured-to-order synthetic ester formulations command premium spreads over standard paraffin-based grades, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and thermal performance ceiling. FDA 21 CFR 178.3570 food-contact qualification and REACH Annex XVII compliance drive price differentiation between regulated and industrial tiers. Cost compression in standard hydrocarbon waxes is intensifying because of chlorinated paraffin substitution mandates. Tier-1 automotive suppliers exhibit lowest price sensitivity; construction profile manufacturers show highest.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp chemical corridors to German tool-and-die shops fluctuate with Rhine water levels and container availability at Hamburg port. Supply concentrates in the United States, Germany, and China for synthetic base stocks and polar additive concentrates. Formulation draws from ethylene oligomerization capacity, castor oil bio-feedstocks, and refined hydrocarbon wax streams. Single-source vulnerability sits with Gulf Coast hurricane exposure. Distribution runs through direct procurement relationships with automotive OEM technical teams and regional compounder networks serving legacy extrusion equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII chlorinated paraffin bans and EPA 40 CFR 59 aerosol restrictions constitute a dual regulatory inflection, compressing formulation cycles while elevating thermal stability thresholds across polymer processing.
For Market Incumbents: Shield margin pools by accelerating backward integration into bio-based ester feedstocks and securing dual FDA-EPA certification pipelines before qualification timelines lengthen. Fluoropolymer mold release coatings threaten specification share in optical polymer segments; defend through R&D investment in sub-320°C thermal stability extension for engineered plastics compatibility. For New Entrants and Emerging Players: Lead with USDA BioPreferred-compliant castor oil formulations targeting federal packaging contracts in the United States, where incumbent specialty houses remain underpenetrated. Medical device molding under ISO 13485 offers adjacent qualification pathway; pursue direct technical partnerships with polymer processors seeking FDA 21 CFR 178.3570 compliance transfer. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because specification-driven procurement concentrates volume with formulators holding broad polymer-compatibility portfolios and captive base-stock supply. Target additive houses with dedicated polymer-processing R&D capabilities and established automotive OEM technical relationships. Monitor EPA Safer Choice program expansion as signal for bio-based formulation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Castor oil supply agreements secure USDA BioPreferred qualification for federal packaging contracts. |
| Dual Certification Investment | Simultaneous FDA food-contact and EPA Safer Choice qualification opens medical device and consumer goods molding. |
| Digital Formulation Platform Deployment | Machine learning compatibility tools compress R&D cycles from eighteen months to ninety days for custom compounders. |
| Automotive OEM Technical Partnership | Direct collaboration with Stuttgart and Detroit tier suppliers locks in approved-materials list positioning. |
| Regional Distributor Consolidation | Acquisition of EPA-compliant compounders in Ohio and Michigan captures spray-to-pump conversion infrastructure. |
Study Parameters
A standing panel of polymer processing plant managers, automotive tier supplier procurement leads, specialty lubricant R&D directors, and distribution channel partners provided ongoing calibration across primary interview cycles. Secondary validation drew from U.S. EPA 40 CFR 59 regulatory filings, ECHA REACH Annex XVII restriction updates, ACC and Cefic chemical industry reports, and customs trade data for base-stock flows. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework segmented by formulation chemistry, polymer compatibility grade, regulatory compliance tier, and regional production hub. CAGRs derived from elasticity-adjusted demand curves incorporating automotive lightweighting mandates and extrusion speed targets. Industry-specific inputs included injection molding cycle time specifications and thermal degradation thresholds for engineering plastics.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, stable Gulf Coast feedstock supply, and continued automotive OEM direct-procurement authority would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and polymer processing technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
South America Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Cutting Fluid Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
US Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
ASEAN Lubricants Market