
 Automotive Active Safety Sensors Market | 2026-2036
Automotive Active Safety Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Safety Sensors Market Intelligence
The EU Green Deal's vehicle safety provisions is decoupling active sensor deployment from purely premium vehicle lines. Continental AG leverages its captive radar and lidar fabrication to sustain integrated module supply across European OEM platforms. Robert Bosch GmbH anchors its competitive stance through deep manufacturing scale in frequency modulated continuous wave chipsets. Denso Corporation specializes in compact ultrasonic arrays for parking assistance, dominating Japanese domestic assembler contracts.
Automotive active safety sensors are electromechanical transducers and optical devices that detect proximal objects, lane markings, or traffic participants through electromagnetic wave emission, acoustic pulse reflection, or image capture at frame rates exceeding 30 Hz; their primary purpose is to generate real-time data streams for electronic control units executing collision mitigation or pathkeeping interventions. Radar sensors occupy the largest volume share given their all-weather reliability for adaptive cruise control and blind spot detection applications. Camera sensors represent the fastest-expanding margin pool as infrared imaging and neural network processing enable nighttime pedestrian recognition and traffic sign interpretation. Lidar sensors compete at the premium tier for high-definition mapping in emerging highway automation architectures.
The European New Car Assessment Programme (Euro NCAP) and the United States National Highway Traffic Safety Administration (NHTSA) enforce diverging test protocols for automatic emergency braking and lane-keeping performance, compelling suppliers to maintain dual certification trajectories. Japan's Ministry of Economy, Trade and Industry (METI) coordinates domestic standards alignment with United Nations Economic Commission for Europe (UNECE) regulations to preserve export market access for its sensor manufacturers. Stakeholders must monitor whether China's Ministry of Industry and Information Technology (MIIT) mandates domestic data processing architectures that fragment sensor-to-ECU communication protocols across supply regions.
Market Dynamics
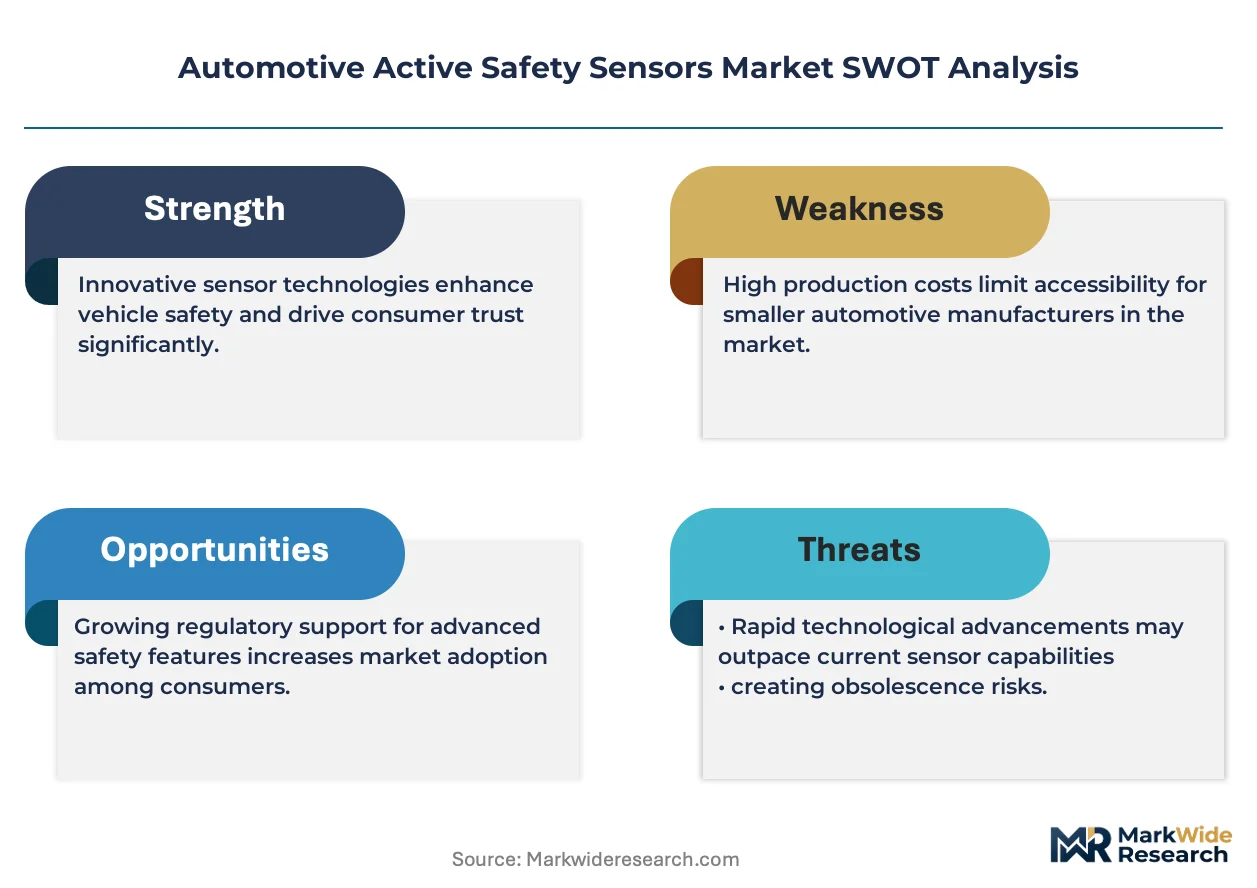
OEM procurement of multi-sensor fusion suites is intensifying as Euro NCAP protocols mandate pedestrian automatic emergency braking, compressing supplier certification timelines and concentrating volume among integrated module providers.
Growth Catalysts
- Euro NCAP pedestrian AEB mandates:European automakers must equip new vehicles with automatic emergency braking systems, forcing sensor suite upgrades across mass-market vehicle lines previously limited to premium segments.
- Level 2+ highway assist proliferation:Camera-radar fusion for hands-free highway driving is penetrating mid-price vehicle categories in Germany, Japan, and the United States, expanding addressable sensor volumes.
- Silicon carbide substrate advances:Wide-bandgap semiconductor materials enable higher-frequency radar operation with reduced thermal footprint, allowing compact sensor packaging for vehicle integration constraints.
Market Restraints
- Compound semiconductor supply concentration:Gallium nitride and silicon carbide wafer fabrication concentrates among limited foundry operators in Taiwan and Japan, creating input cost volatility for radar front-end modules.
- Lidar unit economics:Solid-state lidar remains structurally expensive for mass-market deployment, constraining adoption to premium highway automation architectures where hardware cost absorption permits negative gross margins at volume.
- Divergent NHTSA-Euro NCAP test protocols:Dual certification requirements for automatic emergency braking and lane-keeping performance force suppliers to maintain parallel validation trajectories, inflating R&D overhead.
Strategic Opportunities
- Indian domestic market penetration:Underpenetrated active safety fitment in India's passenger vehicle fleet creates white space as the country's Ministry of Road Transport and Highways contemplates mandatory AEB alignment with UNECE regulations.
- Infrared imaging convergence:Thermal camera integration with neural network processing enables nighttime pedestrian recognition without lidar dependency, opening cost-optimized sensor architectures for emerging market OEMs.
- Software-defined sensor calibration:Over-the-air update capabilities allow post-sale performance enhancement, creating recurring revenue attachment and reducing warranty exposure for misalignment defects.
Industry Challenges
- Multi-sensor fusion algorithm talent scarcity:Shortage of engineers proficient in Kalman filtering and deep learning integration for camera-radar-lidar data synthesis extends product development cycles.
- Functional safety certification timelines:ISO 26262 ASIL-D validation for safety-critical sensor modules requires 18-24 month lead times, compressing competitive response windows to regulatory changes.
- Legacy vehicle electrical architecture integration:Older CAN bus implementations lack bandwidth for high-resolution lidar point cloud transmission, forcing costly gateway module redesigns for retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Safety Sensors Market |
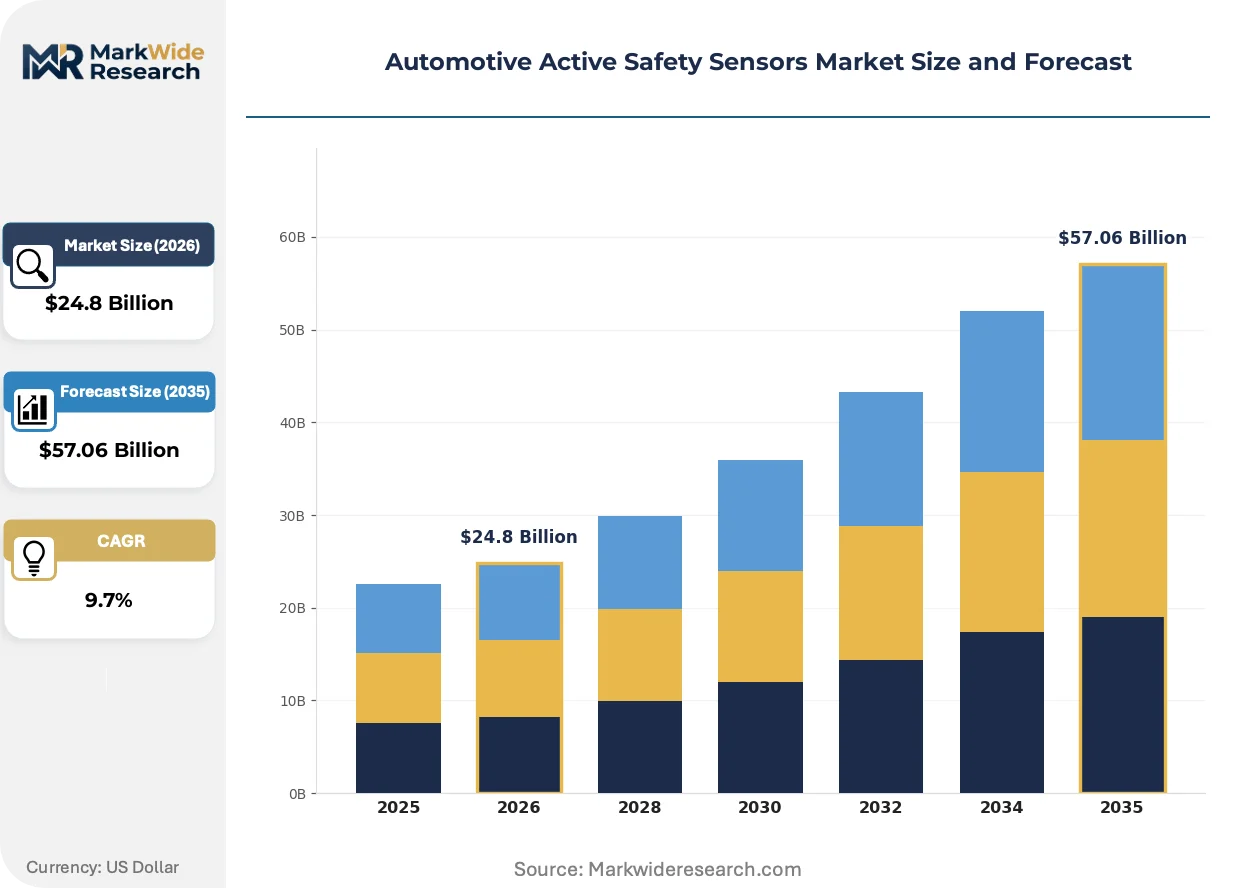
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Radar Sensors, Lidar Sensors, Camera Sensors Technology: Time-of-Flight, Frequency Modulated Continuous Wave, Pulsed Radar, Infrared Imaging Application: Collision Avoidance, Lane Departure Warning, Blind Spot Detection, Adaptive Cruise Control, Parking Assistance End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, ZF Friedrichshafen AG, Aptiv PLC, Valeo SA, Magna International Inc., Autoliv Inc., Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Safety Sensors Market Strategic Shifts & Innovations
Automotive active safety sensors are undergoing architectural transformation as electromechanical transducers merge with edge computing substrates, compressing latency budgets and enabling real-time pathkeeping interventions without centralized processing bottlenecks.
Frequency modulated continuous wave radar is converging with machine learning inference engines at the sensor edge, enabling single-chip modules to classify road debris and stationary objects without host processor dependency. Tier 1 suppliers in Germany and Japan are accelerating deployment of these intelligent radar units for blind spot detection and cross-traffic alert functions. This convergence is compressing the traditional tiered supplier hierarchy, allowing semiconductor foundries to capture value previously retained by module integrators.
The EU Green Deal's vehicle safety provisions are decoupling active sensor deployment from purely premium vehicle lines, mandating pedestrian protection systems across all powertrain categories including battery electric and hydrogen fuel cell platforms. European OEMs must comply with expanded test scenarios covering vulnerable road users in urban environments. This regulatory expansion is forcing sensor suppliers to redesign optical and electromagnetic systems for low-speed collision avoidance in dense traffic conditions.
Fleet operators and mobility service providers are consolidating sensor procurement through direct semiconductor sourcing, bypassing traditional Tier 1 module suppliers for standardized camera and radar components. This channel disintermediation concentrates in the United States where autonomous vehicle test fleets negotiate volume contracts with image sensor foundries. The shift is most visible among robotaxi operators in California and Arizona, where vehicle uptime requirements favor component-level repair strategies over integrated module replacement.
Automotive Active Safety Sensors Market Segmentation
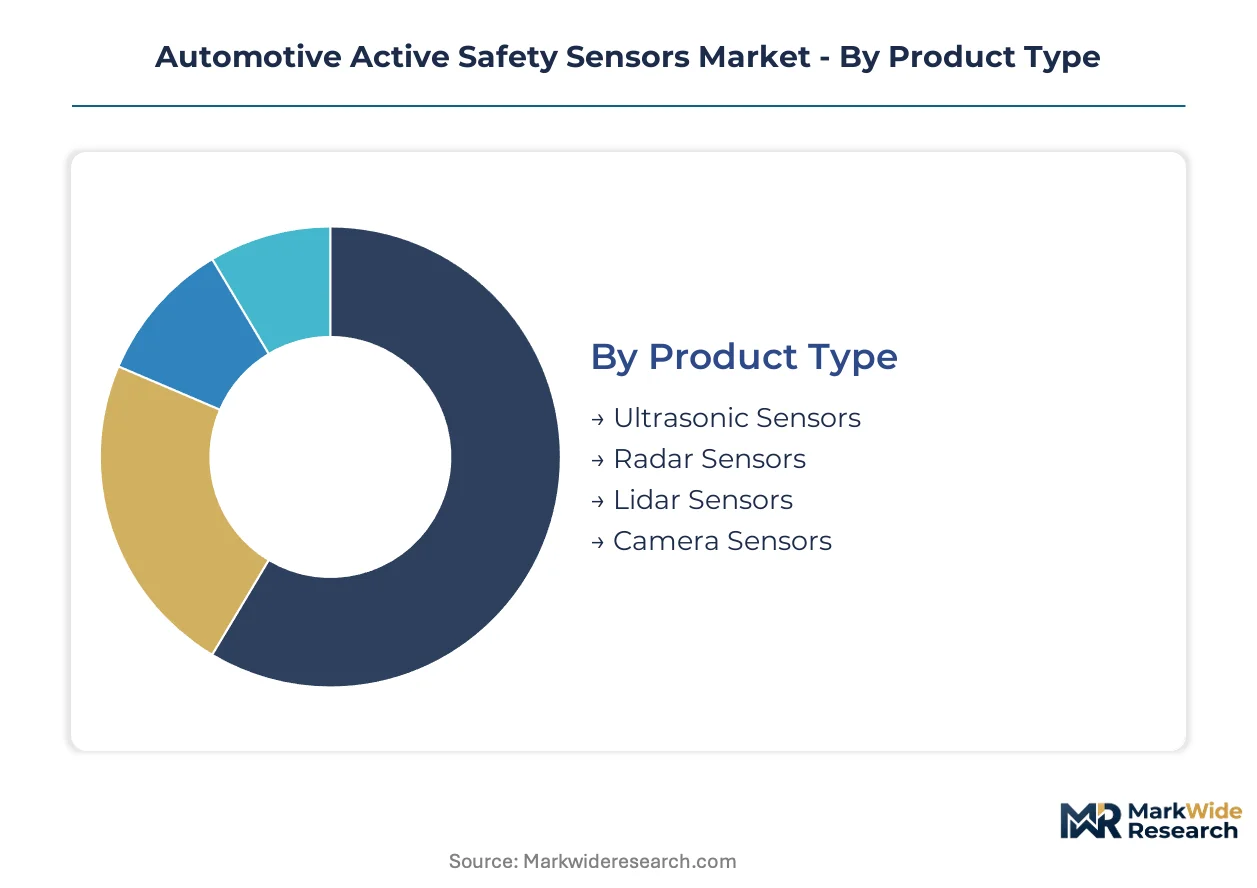
Automotive active safety sensors segment across four critical dimensions that determine procurement patterns, certification requirements, and margin structures. Suppliers must navigate divergent technical specifications and customer integration demands across each axis.
Product Type:
Supply concentration for core sensing modalities varies sharply, with captive fabrication capabilities determining competitive access to automotive OEM platforms.
- Radar Sensors:Electromagnetic transducers operating at 24 GHz and 77-81 GHz bands for all-weather object detection and velocity measurement. Demand concentrates in Germany and the United States for adaptive cruise control and highway automation suites, driven by Euro NCAP and NHTSA mandates for automatic emergency braking.
- Camera Sensors:CMOS and infrared imaging arrays capturing 30+ frames per second for lane marking recognition and traffic sign interpretation. Japanese and South Korean vehicle assemblers are expanding procurement for Level 2+ hands-free driving functions, constrained by neural network training data scarcity for edge-case scenarios.
- Ultrasonic Sensors:Compact acoustic pulse devices for low-speed parking assistance and obstacle proximity alerting.
- Lidar Sensors:Solid-state and mechanical scanning units generating high-density point clouds for highway automation mapping.
Radar sensors absorb the bulk of installed capacity; camera sensors are expanding most quickly.
Technology:
Cost tier differentiation separates premium performance architectures from mass-market implementations, with semiconductor substrate choices driving unit economics.
- Frequency Modulated Continuous Wave:Continuous-wave radar modulation enabling simultaneous range and velocity measurement through single-chip integration. Robert Bosch GmbH and Continental AG dominate European supply for blind spot detection, with silicon carbide substrate adoption reducing thermal management costs.
- Infrared Imaging:Thermal detection arrays operating beyond visible spectrum for nighttime pedestrian recognition without active illumination. Demand clusters in premium German OEM platforms, constrained by germanium lens supply concentration and cryogenic cooling requirements for high-resolution variants.
- Time-of-Flight:Optical distance measurement through modulated light pulse timing for short-range interior sensing.
- Pulsed Radar:Discrete transmission bursts for long-range object detection in highway cruising applications.
Frequency Modulated Continuous Wave captures the greatest production volume; Infrared Imaging is climbing the fastest.
Application:
Customer type segmentation reveals divergent procurement authority, with OEMs consolidating specification control while Tier-1 suppliers retain integration responsibility.
- Collision Avoidance:Multi-sensor fusion systems executing automatic emergency braking and forward collision warning through radar-camera data synthesis. OEMs in Japan and Germany mandate ASIL-D functional safety certification, compressing supplier qualification timelines to 18-24 months.
- Adaptive Cruise Control:Longitudinal speed and distance maintenance through forward-facing radar arrays. Aftermarket providers in the United States are expanding retrofit offerings for legacy vehicle fleets, constrained by CAN bus bandwidth limitations and calibration complexity.
- Blind Spot Detection:Side-facing radar and ultrasonic monitoring for adjacent lane vehicle presence alerting.
- Lane Departure Warning:Camera-based lane marking tracking for unintended drift alerting and corrective steering intervention.
- Parking Assistance:Surround-view camera and ultrasonic array integration for automated maneuvering in confined spaces.
Collision Avoidance commands the largest share of sensor unit shipments; Adaptive Cruise Control is gaining share fastest.
End User:
Maturity differentiation separates established supply relationships from emerging channel disintermediation, particularly in autonomous vehicle development fleets.
- OEMs:Vehicle manufacturers specifying sensor performance requirements and validating module integration across platform architectures. Direct semiconductor sourcing is accelerating among California and Arizona robotaxi operators, bypassing traditional Tier-1 module suppliers for component-level procurement.
- Tier-1 Suppliers:Integrated module providers combining sensor elements with housing, thermal management, and ECU interface electronics. Continental AG and Denso Corporation dominate Japanese and European assembler contracts through captive radar and ultrasonic fabrication.
- Vehicle Assemblers:Contract manufacturing partners executing final sensor mounting and calibration sequences.
- Aftermarket Providers:Independent distributors serving collision repair and fleet retrofit segments with replacement modules.
OEMs direct the majority of procurement volume; Tier-1 Suppliers are experiencing the steepest margin compression from direct sourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor production concentrates in Germany and Japan while consumption scales fastest in the United States and China. This geographic split shapes supplier facility placement and certification investments.
United States
NHTSA mandates for automatic emergency braking and pedestrian detection are accelerating sensor fitment across Detroit Three vehicle lines. The National Highway Traffic Safety Administration enforces test protocols diverging from Euro NCAP standards, forcing dual validation trajectories. California and Arizona robotaxi operators in the San Francisco Bay Area and Phoenix metro are consolidating direct semiconductor procurement, bypassing traditional Tier-1 module suppliers.
Germany
Euro NCAP pedestrian protection protocols are compressing supplier certification timelines for Stuttgart and Munich-based OEM platforms. The EU Green Deal's vehicle safety provisions mandate active sensor deployment across all powertrain categories including battery electric architectures. Bavaria's automotive corridor hosts captive radar and lidar fabrication facilities supplying integrated modules across European assembler contracts.
Japan
METI coordinates domestic standards alignment with UNECE regulations to preserve export market access for sensor manufacturers serving Toyota and Honda supply chains. The Ministry of Economy, Trade and Industry facilitates technical harmonization with European regulatory frameworks. Chubu region fabricators in Aichi Prefecture dominate compact ultrasonic array production for parking assistance systems.
China
MIIT oversight of domestic data processing architectures is fragmenting sensor-to-ECU communication protocols across supply regions. The Ministry of Industry and Information Technology mandates local content requirements for intelligent connected vehicle deployments. Yangtze River Delta clusters in Shanghai and Jiangsu Province are scaling camera sensor assembly for domestic OEM highway automation programs.
India
Underpenetrated active safety fitment creates white space as the Ministry of Road Transport and Highways contemplates mandatory AEB alignment with UNECE regulations. Domestic passenger vehicle fleet expansion is driving Tier-1 supplier localization investments. Tamil Nadu and Maharashtra automotive corridors are attracting radar module assembly operations from Japanese and European component manufacturers.
Automotive Active Safety Sensors Market Key Industry Players
The competitive structure tilts toward integrated module providers with captive semiconductor fabrication capabilities. Tier-1 suppliers with in-house radar and lidar production sustain platform-level contracts across German and Japanese OEMs. Three archetypes dominate: diversified automotive electronics conglomerates with full-stack sensor portfolios, specialized frequency modulated continuous wave chipset manufacturers, and compact ultrasonic array specialists serving parking assistance segments. Competitive moves center on silicon carbide substrate integration for thermal management reduction and strategic partnerships with semiconductor foundries to secure gallium nitride wafer supply.
Among European integrated module providers, Continental AG and Robert Bosch GmbH exemplify the diversified conglomerate archetype through their manufacturing scale across frequency modulated continuous wave radar chipsets. Denso Corporation represents the specialized compact sensor tier, anchoring Japanese domestic assembler contracts through ultrasonic array dominance. These three entities collectively illustrate how geographic fabrication concentration and captive supply capabilities determine competitive access to mass-market vehicle platforms.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Valeo SA |
| Magna International Inc. |
| Autoliv Inc. |
| Hyundai Mobis |
| Others |
Cost & Logistics Intelligence
Captive radar and lidar fabrication by Continental AG and Robert Bosch GmbH anchors supply positions across European OEM platforms while compressing margin pools for module integrators lacking in-house semiconductor production. This integration choice concentrates pricing power among diversified conglomerates capable of silicon carbide substrate adoption, forcing specialized suppliers toward cost-down pressure on standard-grade components.
Pricing Analysis
Margin tightening in mass-market radar modules reflects gallium nitride wafer cost volatility from Taiwan and Japan foundry concentration. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified collision avoidance systems from parking assistance arrays. Price differentiation rests on ISO 26262 certification grade and volume scale commitments. Fleet operators and robotaxi developers exhibit lowest price sensitivity given uptime requirements, while Indian aftermarket providers face acute cost compression.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs require qualification of secondary gallium nitride and silicon carbide wafer suppliers beyond dominant Taiwan and Japan foundries. Raw material dependencies center on germanium lens substrates for infrared imaging, cryogenic cooling systems for high-resolution thermal arrays, and wide-bandgap semiconductor wafers for radar front-ends. Single-source vulnerability concentrates in compound semiconductor fabrication. Distribution runs through Tier-1 module integrators for OEM contracts, with direct semiconductor sourcing accelerating among California and Arizona autonomous vehicle fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive active safety sensors represent a consolidation play as Euro NCAP and NHTSA certification timelines compress competitive response windows below 24 months, forcing capital-constrained specialists toward exit or acquisition.
For Market Incumbents: Deploy silicon carbide substrate integration to reduce thermal management costs and defend margin position against semiconductor foundries encroaching on module integration value. Deepen backward integration into gallium nitride wafer supply through strategic partnerships with Taiwan and Japan foundry operators. Accelerate ASIL-D certification pipelines ahead of pending Indian AEB mandates to preempt competitor qualification. For New Entrants and Emerging Players: The price-point gap between premium German OEM infrared imaging suites and economy-grade ultrasonic parking arrays creates white-space opportunity for cost-optimized thermal camera architectures. Target Indian domestic market penetration as the Ministry of Road Transport and Highways aligns with UNECE regulations. Pursue software-defined sensor calibration capabilities enabling over-the-air revenue attachment as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified automotive electronics conglomerates seeking captive radar fabrication capabilities. Long-term viability favors suppliers with demonstrated ISO 26262 ASIL-D validation track records and established OEM platform integration relationships. Watch for MIIT mandates on domestic data processing architectures as the inflection signal for supply chain fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Adoption | Enables higher-frequency radar operation with reduced thermal footprint for compact vehicle integration. |
| Multi-Sensor Fusion Algorithm Development | Addresses talent scarcity in Kalman filtering and deep learning integration for camera-radar-lidar synthesis. |
| Direct Semiconductor Sourcing Partnerships | Bypasses Tier-1 module suppliers for California and Arizona robotaxi fleet procurement consolidation. |
| Infrared Imaging Convergence Investment | Opens cost-optimized nighttime pedestrian recognition without lidar dependency for emerging market OEMs. |
| Indian Manufacturing Localization | Positions for anticipated Ministry of Road Transport and Highways AEB mandate alignment with UNECE. |
Research Approach
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and semiconductor foundry account managers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with aftermarket distributors and dealership operations heads with secondary validation against vehicle production databases, IHS Markit registration data, Euro NCAP test protocol disclosures, and NHTSA regulatory filings. Bottom-up sensor unit demand modeling and top-down automotive electronics market sizing were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from installed base projections and replacement cycle assumptions. Forecast inputs incorporated Euro NCAP protocol evolution timelines, silicon carbide substrate adoption curves, and neural network processing cost decline trajectories.
Underlying measurement precision varies by segment; collision avoidance and adaptive cruise control applications carry tighter precision than parking assistance due to higher regulatory disclosure requirements. Forecasts reflect documented assumptions regarding OEM platform launch schedules and foundry capacity expansion plans. Deviation in MIIT data localization mandates or compound semiconductor supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market