
 Steering Column Locks Market | 2026-2036
Steering Column Locks Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Column Locks Market Analytics
Electronic immobilizer integration with steering column lock housings is reshaping supplier engineering priorities across passenger and commercial vehicle programs. Robert Bosch GmbH leverages its powertrain electronics portfolio to bundle immobilizer logic with mechanical lock barrels, reducing OEM wiring complexity. Tokai Rika Co., Ltd. anchors Japanese kei-car and compact vehicle supply through dedicated factory installation lines with Toyota and Honda. ZF Friedrichshafen AG extends its chassis systems footprint into electromechanical steering lock modules for electric vehicle platforms.
A steering column lock is a mechanical or electromechanical security device mounted at the base of the steering shaft that prevents rotational movement when engaged, typically constructed from hardened steel tumblers, zinc alloy housings, and polymer actuator components manufactured through precision die-casting and CNC machining processes. Its primary purpose is theft deterrence by disabling vehicle directional control while integrating with ignition systems or standalone immobilizer architectures. Electric locks and smart locking technology command expanding share as OEMs phase out traditional keyed ignition switches, while mechanical locks retain dominance in aftermarket retrofit channels where cost sensitivity shapes procurement. Factory installation captures the deepest margin pools through multi-year platform supply agreements, whereas DIY kits compete on price in aging vehicle segments.
Federal Motor Vehicle Safety Standard 114 enforced by NHTSA mandates steering column lock performance for U.S. light vehicles, while the EU's ECE R116 regulation establishes uniform theft-resistance certification across member states. Germany's KBA administers type approval testing that determines market access for imported lock assemblies. Stakeholders must monitor divergence between U.S. keyless-entry mandates and European biometric authentication pilots as regulatory frameworks evolve for connected vehicle security.
Market Dynamics
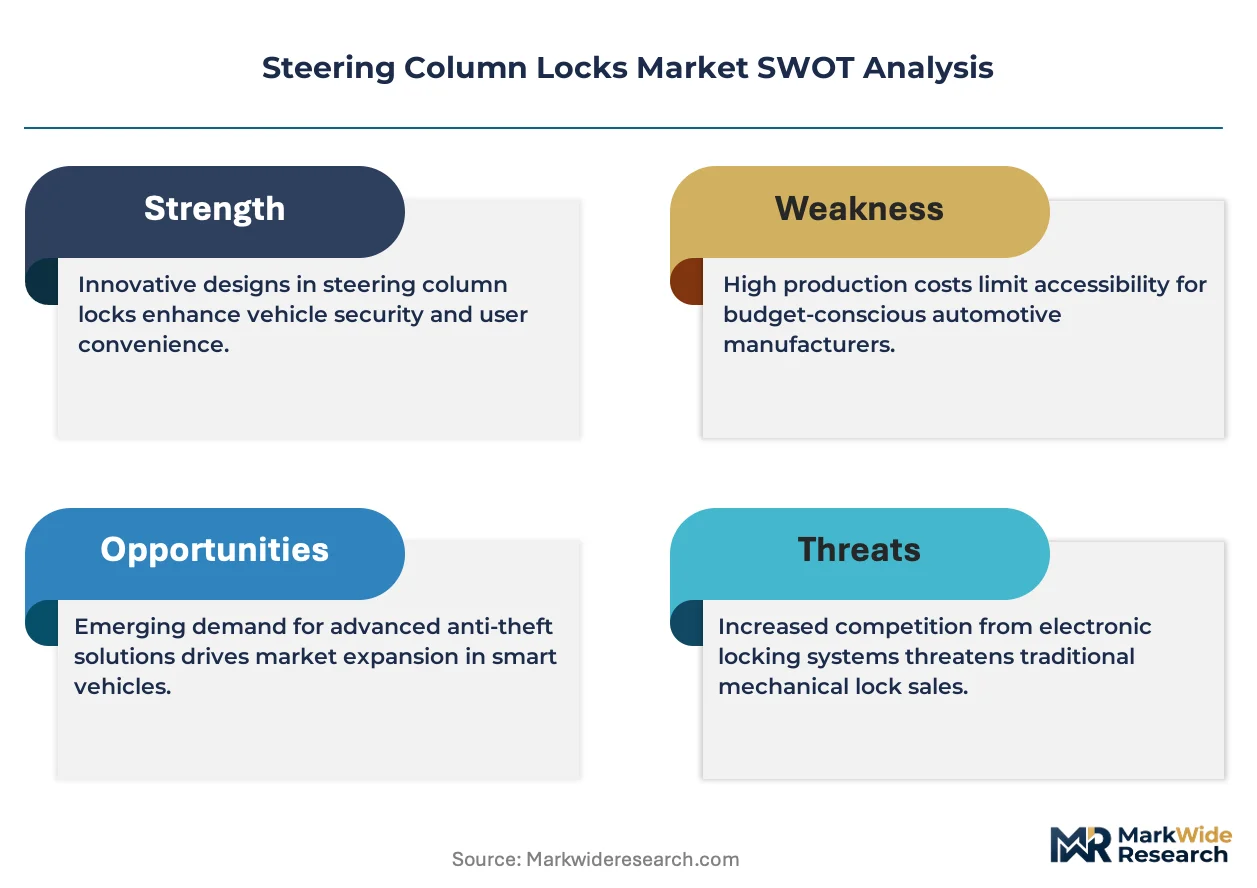
The migration from mechanical keyed systems to electromechanical steering column locks is compressing supplier margins while elevating firmware validation costs across passenger and commercial vehicle programs.
Growth Catalysts
- NHTSA FMVSS 114 enforcement:U.S. federal mandates for theft-deterrent performance sustain baseline demand for certified lock assemblies across light vehicle production.
- Keyless entry architecture proliferation:Commercial fleet operators in Mexico's automotive manufacturing corridors are integrating electronic immobilizers with steering column housings to reduce vehicle theft exposure.
- Zinc alloy die-casting clusters:Precision metalworking capabilities in Guanajuato and Puebla supply hardened lock components to North American OEM assembly networks at scale.
Market Restraints
- Semiconductor input volatility:Microcontroller shortages for immobilizer logic disrupt electromechanical lock production schedules and inflate unit costs.
- Supplier concentration in Germany:KBA type-approval testing requirements create bottlenecks for non-European manufacturers seeking EU market access.
- Biometric authentication substitution:Fingerprint and facial recognition systems for vehicle access threaten long-term displacement of mechanical lock barrels in premium segments.
Strategic Opportunities
- Electric vehicle platform integration:Electromechanical steering lock modules for battery-electric architectures offer white-space expansion as OEMs redesign cockpit electronics.
- Aftermarket retrofit channels:Aging vehicle parc in the United States sustains demand for DIY mechanical lock kits where cost sensitivity dominates procurement.
- ECE R116 harmonization:EU-wide theft-resistance certification streamlines cross-border approval for suppliers holding German KBA test documentation.
Industry Challenges
- Embedded software validation:Functional safety certification for immobilizer firmware extends development timelines and requires specialized automotive cybersecurity expertise.
- Legacy ignition integration:Electromechanical locks must maintain backward compatibility with existing steering column geometries while accommodating new electronic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Column Locks Market |
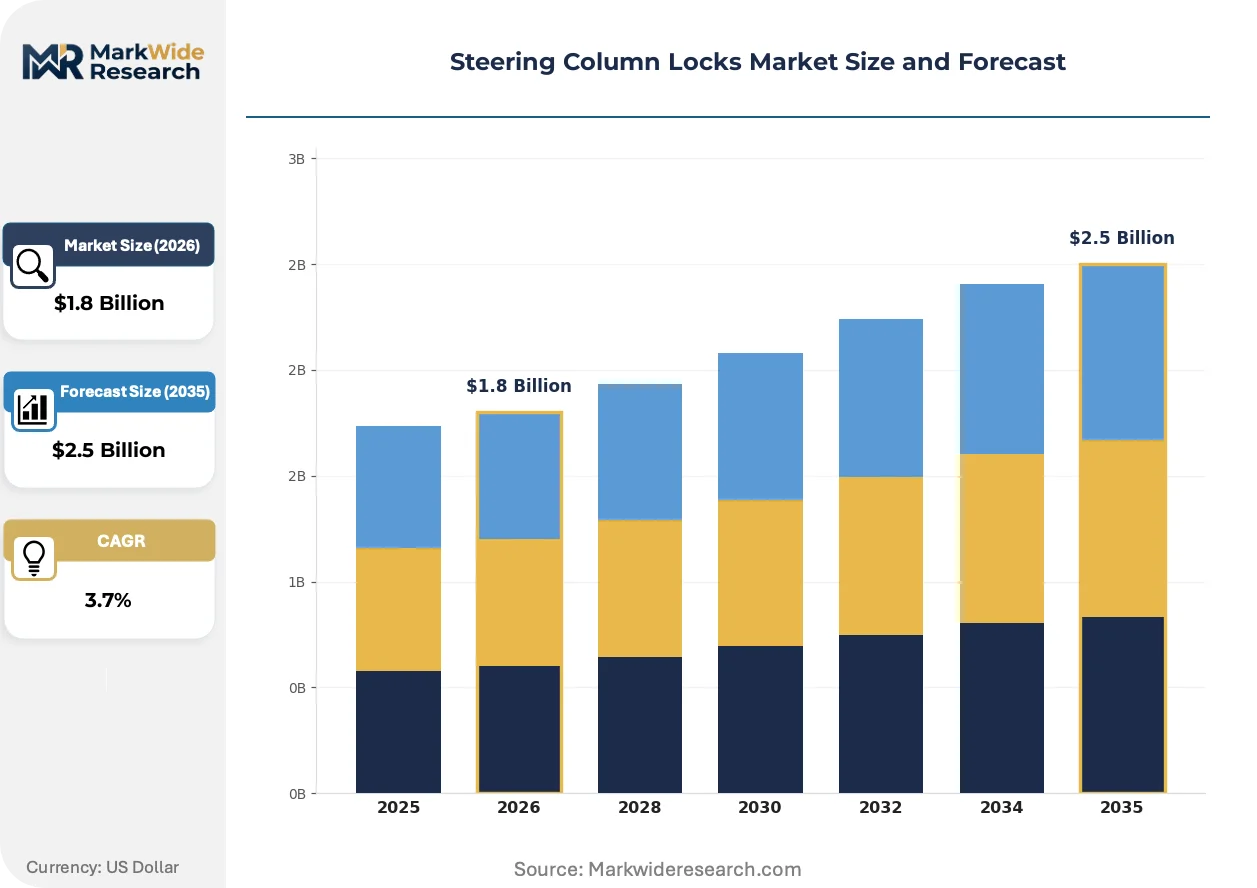
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Locks, Mechanical Locks, Hybrid Locks, RFID Locks End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Keyless Entry, Biometric Systems, Traditional Keys, Smart Locking Installation: Factory Installation, Retrofit, Custom Installation, DIY Kits |
| Companies Covered | Valeo S.A., Robert Bosch GmbH, ZF Friedrichshafen AG, Tokai Rika Co., Ltd., U-Shin Ltd., Nexteer Automotive, Denso Corporation, Huf Hülsbeck & Fürst GmbH & Co. KG, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Column Locks Market Evolving Landscape
Electromechanical architectures are displacing pure mechanical designs across OEM factory installations, while aftermarket channels retain legacy keyed systems for cost-constrained vehicle owners.
Electromechanical steering column locks is hybridizing mechanical security with digital immobilizer protocols. Tier-1 suppliers are embedding microcontroller-based authentication into zinc alloy housings for electric vehicle platforms. This convergence is compressing the addressable market for standalone mechanical barrels while expanding firmware service revenue pools.
NHTSA's evolving interpretation of FMVSS 114 for keyless-start vehicles is forcing suppliers to demonstrate equivalent theft resistance without physical key cylinders. Manufacturers must submit alternative compliance documentation for electronic-only access systems. German KBA testing protocols are adapting slower, creating divergence in approval pathways between U.S. and EU submissions.
Fleet procurement departments are consolidating steering column lock sourcing through multi-year platform agreements rather than spot purchases. Large commercial operators in North America now bundle electromechanical locks with telematics security packages. This concentration is squeezing independent aftermarket distributors in the United States who historically supplied replacement mechanical barrels.
Steering Column Locks Market Segmentation
Steering column lock procurement patterns diverge sharply between OEM factory programs and aftermarket channels, with technology choices and installation methods determining margin structures and supplier relationships across passenger and commercial vehicle segments.
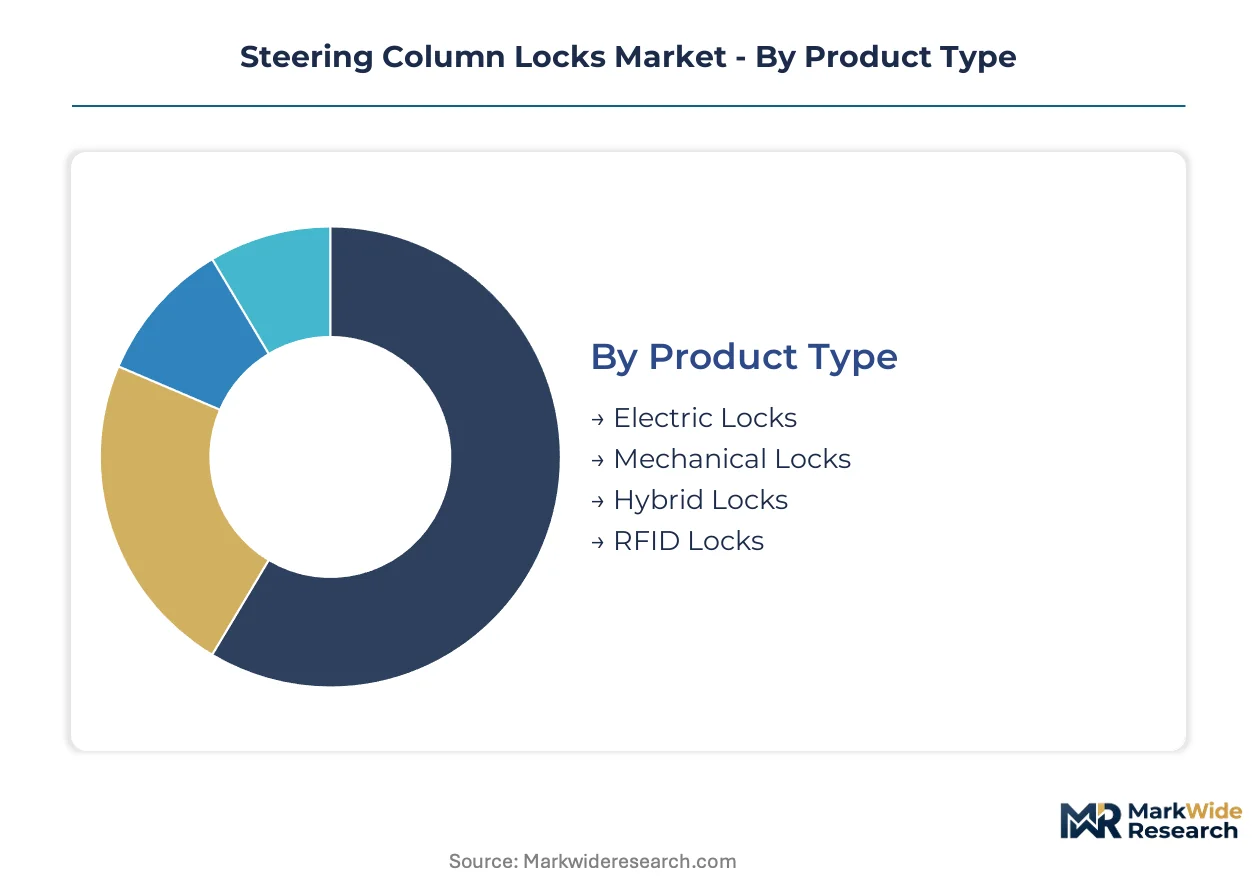
Product Type:
Cost tier differentiation separates premium electromechanical systems from commodity mechanical barrels, with hybrid architectures emerging at the intersection.
- Electric Locks:Microcontroller-driven actuators housed in zinc alloy castings enable keyless-start compatibility. Demand concentrates in North American OEM electric vehicle platforms where NHTSA FMVSS 114 compliance for electronic-only access systems requires alternative certification pathways.
- Mechanical Locks:Hardened steel tumbler assemblies with precision-machined barrels dominate aftermarket retrofit channels. Cost sensitivity in aging U.S. vehicle parc sustains procurement volumes despite OEM phase-out trends.
- Hybrid Locks:Dual-mode mechanical-electronic architectures bridge legacy ignition systems with immobilizer integration.
- RFID Locks:Passive transponder authentication embedded in steering column housings supports commercial fleet security protocols.
Electric locks hold installed capacity. Hybrid locks are rotating up the share rankings.
End User:
Customer type determines contract structure, with multi-year platform agreements contrasting spot-market procurement in fragmented channels.
- OEMs:Original equipment manufacturers specify electromechanical lock modules through integrated cockpit electronics tenders. Factory installation lines in Mexico's Guanajuato and Puebla clusters supply North American assembly networks under long-term supply agreements with embedded firmware service clauses.
- Aftermarket Providers:Independent distributors and service chains procure mechanical replacement barrels for vehicle parc maintenance. Price compression from online retail channels erodes traditional wholesale margins in the United States.
- Vehicle Assemblers:Contract manufacturers and kit car builders source lock assemblies through tiered supplier networks.
- Fleet Operators:Commercial vehicle managers bundle steering security with telematics packages across North American logistics corridors.
OEMs anchor volume concentration. Fleet operators are climbing the fastest as procurement consolidates.
Technology:
Maturity gradients separate established keyed architectures from emerging biometric protocols, with regulatory divergence shaping adoption timelines.
- Keyless Entry:Radio-frequency and passive entry-go systems eliminate physical key cylinders while maintaining steering lock functionality. NHTSA's evolving FMVSS 114 interpretation for keyless-start vehicles forces suppliers to demonstrate equivalent theft resistance through alternative compliance documentation.
- Biometric Systems:Fingerprint and facial recognition authentication threatens long-term displacement of mechanical barrels in premium vehicle segments. German KBA testing protocols adapt slower than U.S. frameworks, creating approval pathway divergence.
- Traditional Keys:Physical tumbler-and-key mechanisms retain dominance in cost-constrained aftermarket applications.
- Smart Locking:Connected vehicle architectures enable remote lock status monitoring and over-the-air authentication updates.
Traditional keys hold residual share. Keyless entry is gaining share fastest across new vehicle programs.
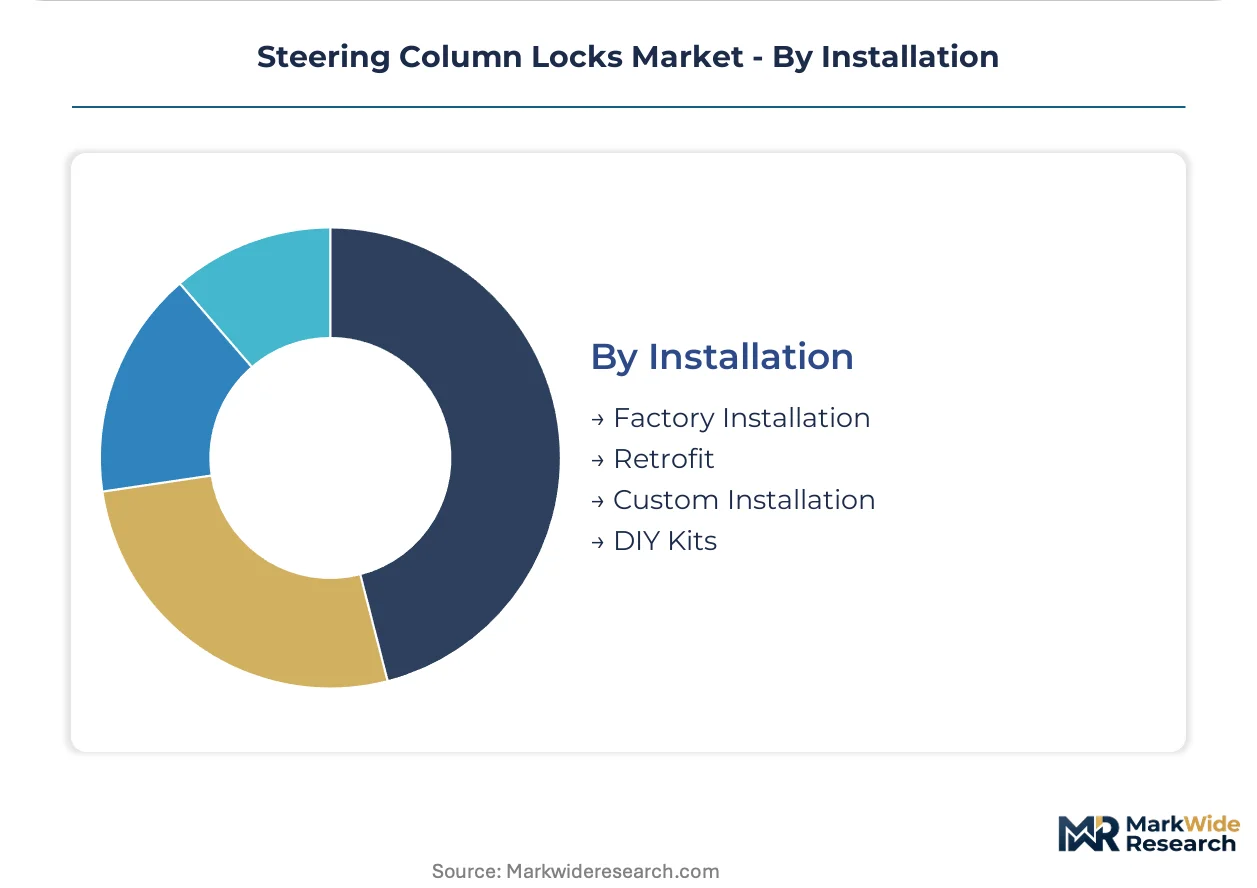
Installation:
Application context determines margin capture, with factory-integrated systems commanding premium pricing against price-sensitive retrofit alternatives.
- Factory Installation:Lock modules integrated during steering column assembly capture the deepest margin pools through multi-year platform supply agreements. OEM engineering collaboration requirements elevate barriers for non-incumbent suppliers.
- Retrofit:Professional installation of aftermarket lock systems serves vehicle security upgrade demand in commercial and specialty applications.
- Custom Installation:Specialist fabricators and restoration shops commission bespoke lock configurations for collector and modified vehicles.
- DIY Kits:Consumer-installable mechanical lock packages compete on price in aging vehicle segments with expired warranties.
Factory installation commands margin concentration. DIY kits represent the steepest expansion trajectory in value-tier channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports steering column lock assemblies to U.S. and Canadian OEM assembly networks through integrated supply corridors. German regulatory frameworks shape EU market access requirements. Japanese kei-car production sustains compact vehicle security component demand.
United States
NHTSA FMVSS 114 enforcement sustains baseline demand for certified lock assemblies across light vehicle production lines. The federal mandate requires demonstrated theft-deterrent performance for all new vehicles sold domestically. Detroit-area OEM engineering centers collaborate with tier-1 suppliers on electromechanical lock integration for keyless-start platforms.
Germany
KBA type-approval testing determines market access for imported lock assemblies seeking EU certification. ECE R116 regulation establishes uniform theft-resistance standards across member states. Stuttgart and Munich automotive clusters house development centers for electromechanical steering lock modules serving premium vehicle platforms.
Mexico
Guanajuato and Puebla precision metalworking clusters supply hardened zinc alloy lock components at scale. NHTSA-aligned production standards enable seamless North American supply chain integration. Querétaro and Aguascalientes assembly corridors export finished lock modules to U.S. OEM factory installation lines.
Japan
Kei-car and compact vehicle production sustains dedicated factory installation demand for space-efficient lock designs. METI industrial standards govern automotive component quality certification. Aichi Prefecture manufacturing corridors anchor supply relationships with Toyota and Honda assembly networks.
China
Domestic OEM electric vehicle platforms drive electromechanical steering lock module procurement volumes. MIIT automotive regulations establish cybersecurity requirements for connected vehicle security components. Yangtze River Delta manufacturing clusters produce lock housings for both domestic consumption and export markets.
Steering Column Locks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across factory installation and aftermarket retrofit segments. The market structure concentrates around tier-1 automotive suppliers with multi-year OEM platform agreements. Three archetypes dominate: diversified automotive conglomerates with chassis electronics portfolios, precision metalworking specialists with die-casting capabilities, and electromechanical system integrators targeting electric vehicle architectures. Competitive moves center on firmware service bundling and backward integration into zinc alloy casting operations.
Within the diversified conglomerate tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify players leveraging powertrain and chassis electronics portfolios to bundle immobilizer logic with mechanical components. Tokai Rika Co., Ltd. occupies a specialist position anchoring Japanese kei-car supply through dedicated factory installation relationships. These three represent distinct strategic postures: European engineering conglomerates, Japanese precision component specialists, and regionally anchored tier-1 suppliers.
| Leading Market Players |
|---|
| Valeo S.A. |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Tokai Rika Co., Ltd. |
| U-Shin Ltd. |
| Nexteer Automotive |
| Denso Corporation |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| NSK Ltd. |
| Others |
Value Network & Pricing Analysis
Zinc alloy die-casting clusters in Guanajuato and Puebla concentrate upstream capacity for hardened lock housings, anchoring margin capture at the OEM factory installation tier while aftermarket distributors face price compression from online retail channels.
Pricing Analysis
Electromechanical lock modules command premium positioning against legacy mechanical barrels, with hybrid architectures occupying a mid-tier value band. Pricing stratifies across premium, standard, and economy tiers based on immobilizer firmware complexity and KBA certification grade. Cost compression in DIY mechanical kits is intensifying because Chinese export competition floods aging vehicle parc channels. Fleet operators show least price sensitivity due to telematics bundling, while independent aftermarket buyers drive hardest bargain.
Supply Chain Analysis
Contract manufacturing capacity for precision-machined lock barrels rests with tier-2 metalworking specialists in Mexico, Germany, and Japan. Supply draws from hardened steel feedstock, zinc alloy ingots, and automotive-grade microcontroller inventories. Single-source vulnerability concentrates in German KBA testing facilities for EU market access. Distribution runs through tier-1 supplier direct channels to OEM assembly lines, with aftermarket flowing via independent distributors and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steering column lock procurement is consolidating around platform-economics logic as OEMs bundle immobilizer firmware with cockpit electronics, eroding standalone component margins and elevating ecosystem interoperability requirements.
For Market Incumbents: Pre-empt biometric authentication displacement by deepening firmware service revenue pools and securing multi-year platform agreements with electric vehicle architects. Backward integration into zinc alloy casting operations in Guanajuato defends margin position against Mexican contract manufacturer consolidation. NHTSA's evolving FMVSS 114 interpretation for keyless-start systems demands accelerated cybersecurity certification investment. For New Entrants and Emerging Players: Aftermarket RFID retrofit kits for commercial fleet operators in North American logistics corridors represent the most penetrable entry point, bypassing entrenched OEM supply relationships. Electromechanical module supply to Chinese domestic EV platforms offers second white-space avenue given MIIT cybersecurity regulation alignment. Go-to-market through telematics security bundlers rather than direct fleet sales accelerates customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision metalworking specialists holding KBA test documentation and Mexican manufacturing footprints. Long-term viability hinges on firmware service attach rates rather than hardware shipment volumes. Watch NHTSA-ECE R116 regulatory divergence as inflection signal for regional supplier restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Service Bundling | Immobilizer logic subscriptions with Robert Bosch GmbH and ZF Friedrichshafen AG transform one-time hardware sales into recurring revenue streams. |
| Backward Integration into Zinc Casting | In-house production of lock housings in Guanajuato clusters reduces dependency on Mexican contract manufacturers and stabilizes input costs. |
| Electric Vehicle Platform Standardization | Electromechanical lock modules designed for battery-electric architectures with Nexteer Automotive and Denso Corporation capture cockpit redesign cycles. |
| KBA Certification Pre-Positioning | Early ECE R116 test documentation with German regulators streamlines EU market access before biometric authentication protocols mature. |
| Telematics Security Partnership | Fleet operator consolidation through bundled procurement with North American logistics providers locks out independent aftermarket distributors. |
Research Methodology
Desk research of NHTSA FMVSS 114 enforcement records, ECE R116 regulatory filings, and IHS Markit vehicle production databases preceded structured interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributor operations heads, and commercial fleet security managers. Bottom-up triangulation across factory installation volumes and top-down validation through automotive component trade flows anchored market sizing.
Assumptions held fixed include NHTSA regulatory continuity and zinc alloy input cost stability, while electric vehicle adoption pace and biometric authentication technology readiness were treated as scenario variables. The analytical framework modeled segmentation across propulsion architecture, vehicle class, installation method, and regional production cluster. CAGRs were derived from production-weighted averaging across OEM platform lifecycles, with immobilizer firmware penetration and fleet telematics bundling rates as primary demand drivers.
Practitioners should monitor semiconductor input volatility and KBA testing backlog duration for early signals of supply constraint or regulatory bottleneck. Quarterly review of NHTSA guidance documents, ECE R116 amendment proposals, and Mexican automotive export customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market