
 Automotive Cowl Panel Market | 2026-2036
Automotive Cowl Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cowl Panel Market Outlook
Stamping capacity in the North American Great Lakes automotive corridor is pivoting toward hybrid metal-composite cowl production to serve electrification programs. Magna International leverages its vertically integrated stamping and assembly network to secure long-term OEM supply agreements. Valeo sustains competitive positioning through specialized weather-sealing integration expertise. Denso Corporation anchors its cowl panel operations within broader HVAC and thermal management systems, creating bundled procurement appeal.
An automotive cowl panel is a structural body component spanning the base of the windshield to the engine compartment firewall, typically manufactured from stamped steel, aluminum, or injection-molded polymer blends with integrated water management channels and acoustic insulation layers. The cowl panel serves as a critical barrier against water intrusion, noise transmission, and debris ingress while providing mounting surfaces for windshield wipers, HVAC intake plenums, and electrical routing. Metal cowl panels retain dominance in heavy-duty and commercial vehicle segments where structural rigidity and crashworthiness take priority, though plastic variants are gaining share in passenger cars where weight reduction directly impacts range metrics. The OEM end-user channel commands the deepest integration requirements, with vehicle assemblers specifying cowl modules that incorporate sealing systems, sound dampeners, and sensor mounting provisions as single-source delivered assemblies.
The EPA enforces fuel economy and emissions standards that compel automakers to pursue gram-level weight savings in non-structural body components, directly elevating composite and polymer cowl specifications. NHTSA crashworthiness protocols govern cowl panel deformation characteristics and pedestrian protection geometry, particularly for frontal impact energy management. China's MIIT administers dual carbon goals that accelerate domestic substitution of traditional stamped steel with recycled aluminum and bio-based polymer formulations in Yangtze and Pearl River Delta production bases. Stakeholders must monitor evolving material certification requirements across these regulatory jurisdictions to anticipate specification changes before platform redesign cycles lock in component choices.
Market Dynamics
Material substitution pressure from EPA Corporate Average Fuel Economy standards and parallel efficiency mandates in Germany and Japan is compressing design cycles for lightweight cowl panel architectures. Stamped steel retains structural dominance in commercial vehicles while polymer and aluminum variants capture passenger car platforms where range optimization dictates specification.
Growth Catalysts
- EPA CAFE Standards:Gram-level weight reduction mandates in the United States elevate composite cowl specifications across electrified vehicle platforms.
- China MIIT Dual Carbon Goals:Domestic production bases in the Yangtze River Delta accelerate substitution toward recycled aluminum and bio-based polymer formulations.
- HVAC Integration Demand:OEMs specify cowl modules bundling sealing systems, acoustic dampeners, and sensor mounting provisions as single-source assemblies.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margin stability for lightweight panel producers.
- Stamping Capacity Concentration:North American Great Lakes corridor equipment is locked into legacy steel tooling, constraining rapid composite pivot capacity.
- NHTSA Crashworthiness Protocols:Deformation characteristic requirements for frontal impact energy management limit polymer penetration in heavy-duty segments.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components create localized manufacturing entry points for composite cowl assembly.
- Sensor Integration White Space:LiDAR and camera mounting provisions within cowl modules represent uncontracted specification territory for module suppliers.
- EU Green Deal:Circular economy mandates for recycled content accelerate demand for closed-loop aluminum and thermoplastic formulations.
Industry Challenges
- Multi-Material Bonding Expertise:Hybrid metal-composite assemblies require adhesive and mechanical joining capabilities scarce in traditional stamping operations.
- Platform Redesign Cycle Lock-In:Component specification freezes 36-48 months before production constrain material innovation adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cowl Panel Market |
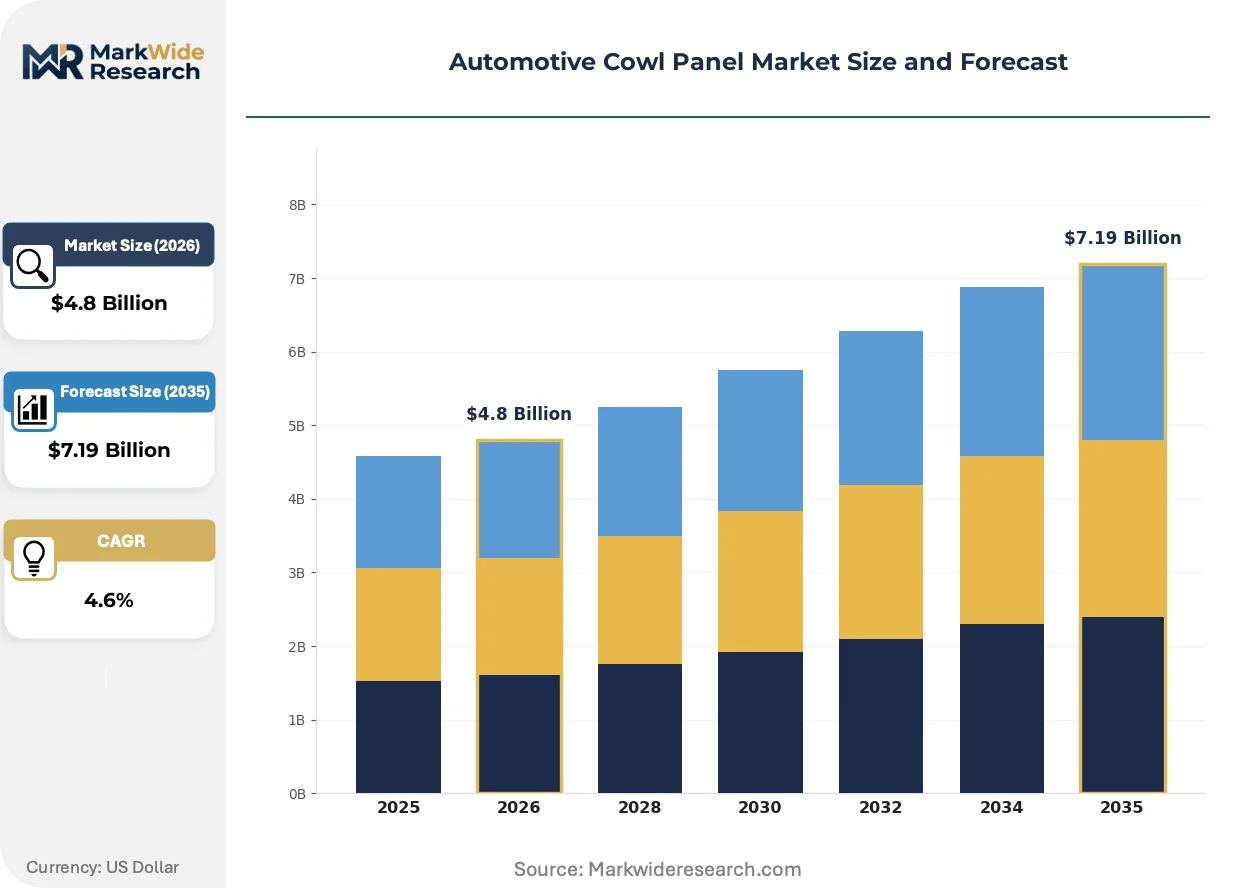
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Carbon Fiber End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Installation Type: Front-Cowl, Rear-Cowl, Integrated-Cowl, Replaceable-Cowl Manufacturing Stage: Injection Molding, Stamping, CNC Machining, Assembly |
| Companies Covered | Valeo, Magna International, Denso Corporation, Plastic Omnium, Futaba Industrial, Toyoda Gosei, CIE Automotive, Montaplast, Inoac Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cowl Panel Market Strategic Shifts
Process automation and regulatory material mandates are compressing traditional manufacturing paradigms while procurement models evolve toward module-level contracting. Specification authority is shifting from tier suppliers to OEM engineering centers.
Hot stamping with press-hardened steel is automating high-strength cowl rail production for electric vehicle architectures requiring enhanced torsional rigidity. European and Chinese OEMs are adopting these lines at replacement cycle pace. The technology is automating labor-intensive forming operations while reducing springback variation in complex cross-car beam integrations.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to zinc-nickel and organic corrosion protection systems across EU-bound production. Surface treatment suppliers are retooling plating lines ahead of sunset dates. Stamped steel cowl panels for export markets face the most concentrated compliance cost pressure.
Module sourcing contracts now bundle weather-sealing, acoustic insulation, and electrical routing into single-supplier agreements displacing component-level procurement. Tier 1 integrators capture specification authority previously held by discrete parts vendors. This consolidation is most visible in German and Japanese OEM program structures.
Automotive Cowl Panel Market Segmentation
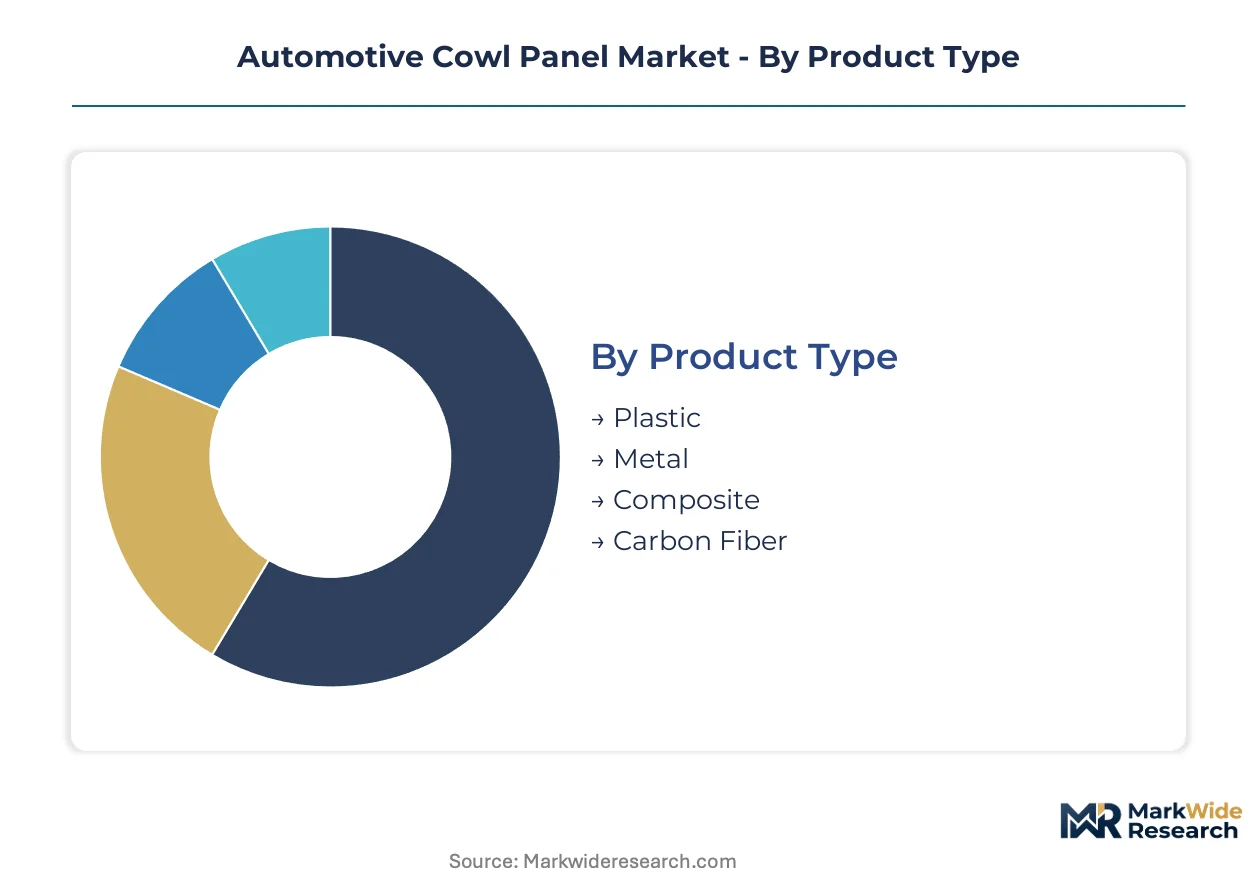
Segmentation in the automotive cowl panel market reveals how material substitution pressures and electrification timelines are fragmenting procurement specifications. OEMs now source distinct formulations for passenger car weight targets versus commercial vehicle crashworthiness mandates.
Product Type:
Supply concentration in stamped steel operations across the North American Great Lakes corridor creates inertia against lightweight material conversion, though polymer and aluminum capacity is expanding fastest in Yangtze River Delta manufacturing clusters.
- Plastic:Injection-molded polymer blends integrate water management channels and acoustic insulation in single-shot forming. Passenger EV platforms in China and Germany specify these variants to trim grams from frontal mass, directly supporting range certification targets under EPA CAFE and parallel EU efficiency mandates.
- Metal:Stamped steel and aluminum cowl panels retain structural dominance in heavy-duty trucks and commercial fleets where NHTSA deformation protocols govern frontal impact energy absorption. The Great Lakes stamping corridor holds the densest installed capacity, constraining rapid pivot to alternative materials.
- Composite:Hybrid metal-polymer assemblies balance rigidity with mass reduction for mid-size crossover platforms.
- Carbon Fiber:High-performance variants serve limited production sports and luxury EV architectures.
Today's leader: Metal. Tomorrow's challenger: Plastic.
End User:
Cost tier stratification separates module-level integrators from component vendors, with bundled procurement commanding premium positioning.
- OEMs:Vehicle assemblers specify cowl modules incorporating sealing systems, sound dampeners, and sensor mounting provisions as single-source delivered assemblies. German and Japanese OEM program structures show the most concentrated shift toward this consolidated sourcing model.
- Vehicle Assemblers:Contract manufacturers and EV startups without captive stamping capacity rely on tier 1 integrators for complete cowl module delivery, creating procurement dependency on suppliers with hot stamping and composite bonding capabilities.
- Aftermarket Providers:Independent distributors serve collision repair and restoration demand.
- Dealerships:Authorized service channels handle warranty replacements and brand-certified repairs.
Volume concentrates with OEMs. Margin expansion sits with integrators serving assemblers.
Installation Type:
Application-specific engineering requirements are diversifying cowl architectures across vehicle platforms.
- Front-Cowl:The primary structural barrier spanning windshield base to firewall, integrating wiper mounts and HVAC intake plenums. Front-cowl specifications dominate engineering resource allocation due to water intrusion and noise transmission performance requirements.
- Integrated-Cowl:Module designs bundling weather-sealing, acoustic layers, and electrical routing into single-supplier agreements. European OEMs are expanding integrated-cowl procurement fastest to reduce assembly line complexity.
- Rear-Cowl:Secondary panels on certain commercial and specialty vehicle architectures.
- Replaceable-Cowl:Service-optimized designs for high-wear fleet applications.
Front-cowl commands specification authority. Integrated-cowl is climbing the fastest.
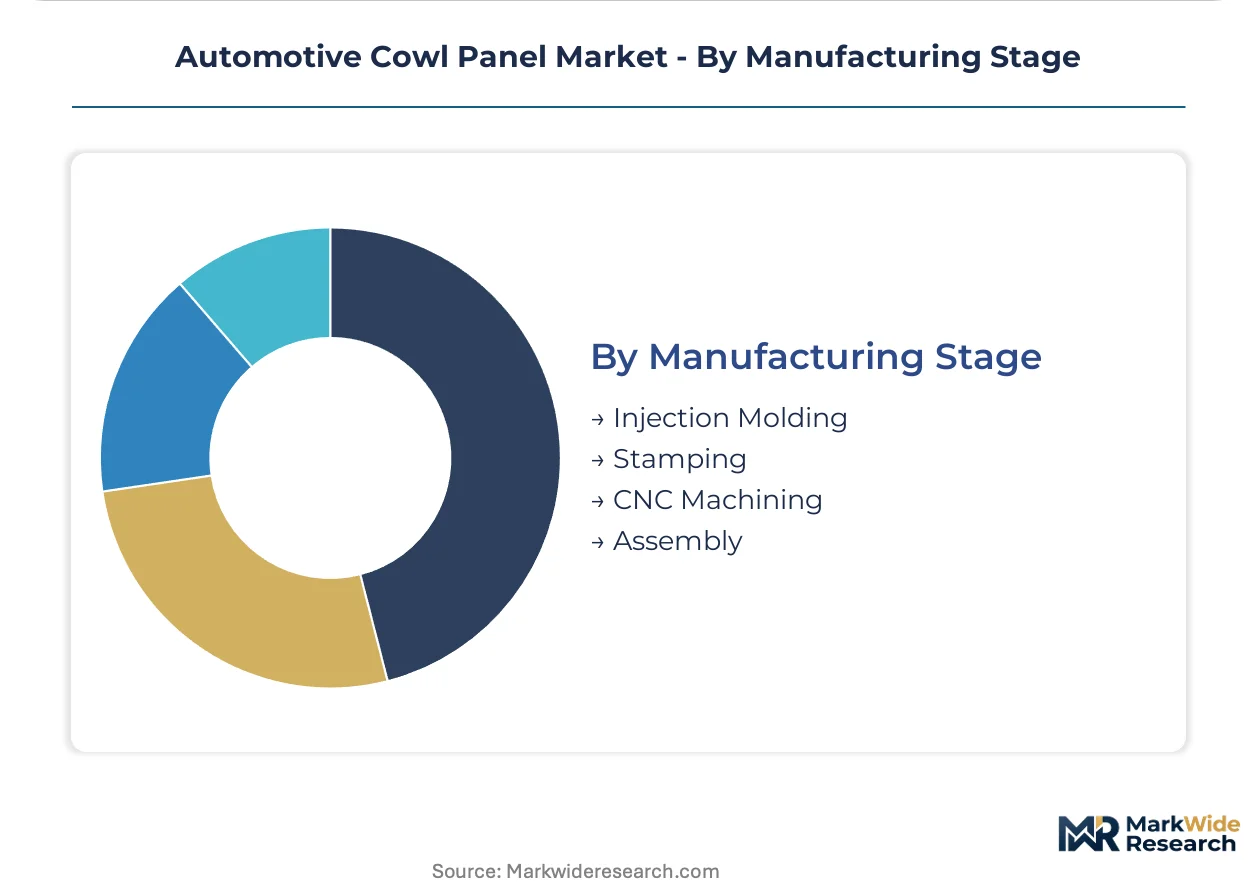
Manufacturing Stage:
Process maturity determines regional competitive positioning, with automation investments reshaping cost structures.
- Stamping:Legacy high-volume production of steel and aluminum panels using mechanical and hydraulic press lines. The North American Great Lakes corridor retains the deepest stamping expertise, though equipment lock-in to legacy tooling constrains hybrid material adoption.
- Injection Molding:Automated polymer processing enabling complex water channel geometries and acoustic layer integration in single operations. Yangtze River Delta facilities are expanding injection molding capacity fastest to serve domestic EV OEM demand under MIIT dual carbon goals.
- CNC Machining:Precision finishing for carbon fiber and composite component integration.
- Assembly:Final module integration of multi-material components with adhesive and mechanical joining.
Stamping holds installed base. Injection molding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cowl panel production is migrating toward jurisdictions where energy costs, labor arbitrage, and regulatory compliance create favorable manufacturing economics. Chinese facilities exploit MIIT dual carbon incentives while German producers navigate REACH substance restrictions. This regulatory-arbitrage dynamic fragments supply chain geography.
United States
EPA CAFE standards and NHTSA crashworthiness protocols shape cowl panel specifications for domestic OEM electrification programs. The Great Lakes stamping corridor retains legacy steel capacity though equipment lock-in constrains composite pivot speed. Detroit-area facilities serve Ford, GM, and Stellantis EV platforms with hybrid metal-composite architectures.
Germany
REACH substance restrictions on hexavalent chromium coatings force surface treatment retooling ahead of regulatory sunset dates. EU Green Deal circular economy mandates accelerate demand for closed-loop aluminum formulations. Bavarian and Baden-Württemberg production bases supply Volkswagen, BMW, and Mercedes-Benz integrated-cowl modules.
China
MIIT dual carbon goals drive substitution toward recycled aluminum and bio-based polymer formulations in passenger EV platforms. Yangtze River Delta manufacturing clusters expand injection molding capacity fastest to serve BYD, NIO, and XPeng demand. Shanghai and Jiangsu province facilities dominate domestic supply.
Japan
METI efficiency mandates and JIS standards govern material specifications for Toyota, Honda, and Nissan electrification timelines. Kanto and Chubu regions concentrate stamping and molding expertise. Aichi prefecture suppliers integrate cowl modules with HVAC thermal management systems.
India
PLI scheme production-linked incentives for advanced automotive components create localized manufacturing entry points for composite cowl assembly. Tamil Nadu and Maharashtra automotive corridors attract tier 1 integrators serving Maruti Suzuki, Tata Motors, and Mahindra EV programs. Domestic OEMs specify cost-optimized polymer variants.
Automotive Cowl Panel Market Competitive Environment
North American producers anchor one tier; European and Japanese specialists hold differentiated positions through module integration expertise. The vendor base segments across consolidated tier 1 integrators and regional component fabricators. Three archetypes dominate: vertically integrated stampers, HVAC-system bundlers, and sealing-specialist module suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as electrification timelines compress procurement cycles.
Within the tier 1 integrator tier, Magna International, Valeo, and Denso Corporation exemplify contrasting strategic positions. Magna International represents the North American vertically integrated archetype with captive stamping and assembly networks. Valeo occupies the European sealing-integration specialist position. Denso Corporation anchors the Japanese HVAC-system bundler model where cowl panels sit within broader thermal management portfolios.
| Leading Market Players |
|---|
| Valeo |
| Magna International |
| Denso Corporation |
| Plastic Omnium |
| Futaba Industrial |
| Toyoda Gosei |
| CIE Automotive |
| Montaplast |
| Inoac Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive injection molding capacity in China's Yangtze River Delta anchors both supply security and pricing leverage for polymer cowl panel suppliers serving domestic EV OEMs. This backward integration into resin compounding and tooling fabrication compresses cost structures while insulating against primary aluminum price volatility that destabilizes lightweight metal competitors.
Pricing Analysis
Distributor markups on aftermarket cowl panels widen spreads between OE and service-channel pricing, with collision repair networks absorbing the steepest premiums. Three-tier pricing structure across premium integrated modules, standard stamped assemblies, and economy polymer replacements reflects certification grade and volume scale differentiation. Cost compression in standard steel tiers is intensifying because Great Lakes stamping corridors face equipment lock-in to legacy tooling. Fleet operators and commercial vehicle buyers exhibit the highest price sensitivity, while luxury EV OEMs prioritize gram-level weight savings over unit cost.
Supply Chain Analysis
Remanufacturing flows for stamped steel cowl panels remain underdeveloped, though EU circular economy mandates are pressuring German suppliers to establish closed-loop aluminum recovery. Primary supply concentrates in China, Germany, and the United States, with Yangtze River Delta facilities dominating polymer injection molding and Bavarian producers anchoring integrated module assembly. The network draws from steel coil, aluminum ingot, and engineering resin feedstocks. Single-source vulnerability around hot stamping press equipment creates concentration risk for EV platform torsional rigidity components. Distribution runs through tier 1 integrators delivering complete modules to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive cowl panel market constitutes a late-cycle quality story as electrification timelines compress procurement toward bundled integrated modules with HVAC and sensor-mount specifications.
For Market Incumbents: Anchor specification authority by deepening captive hot stamping capacity for press-hardened steel cowl rails serving EV architectures requiring enhanced torsional rigidity. Defend against polymer substitution by securing long-term aluminum offtake agreements that stabilize input costs against energy price volatility. Prioritize certification investment for REACH-compliant zinc-nickel surface treatments ahead of hexavalent chromium sunset dates. For New Entrants and Emerging Players: EV startups without captive stamping capacity represent the most penetrable buyer archetype for composite bonding specialists offering complete module delivery. Target India's Tamil Nadu automotive corridor where PLI scheme incentives reduce capital barriers for localized injection molding investment. Pursue sensor integration white space by engineering LiDAR mounting provisions into cowl module designs before specification freezes lock out new suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where tier 2 stamping operations lack hybrid metal-composite bonding capabilities required for next-generation platform awards. The five-to-ten year viability window favors acquisition targets with established OEM module supply relationships and MIIT-compliant recycled aluminum sourcing. Monitor NHTSA pedestrian protection rulemakings for inflection signals that could accelerate polymer penetration beyond current crashworthiness limits.| Strategic Initiative | Industry Significance |
|---|---|
| Hot Stamping Capacity Expansion | Press-hardened steel cowl rail production automates labor-intensive forming for EV torsional rigidity requirements. |
| Sensor Integration Module Development | LiDAR and camera mounting provisions capture uncontracted specification territory before platform redesign cycles freeze. |
| Closed-Loop Aluminum Sourcing | EU Green Deal circular economy mandates accelerate demand for recycled content formulations in German production bases. |
| REACH-Compliant Surface Treatment Retooling | Zinc-nickel and organic corrosion protection systems displace hexavalent chromium ahead of regulatory sunset dates. |
| India PLI Scheme Manufacturing Entry | Production-linked incentives for advanced automotive components reduce capital barriers for composite cowl assembly localization. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC supplier filings, and customs trade records. This triangulation approach ensures demand-side estimates align with supply-side manufacturing footprints across regional production clusters.
Input-output matrices map material flow from steel coil, aluminum ingot, and engineering resin through stamping, injection molding, and assembly stages to finished module delivery. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis of historical production volumes against regulatory efficiency mandate trajectories across the analysis window. Forecast inputs include EPA CAFE compliance timelines, MIIT dual carbon implementation schedules, and platform redesign cycle cadence.
Underlying measurement precision varies by segment; integrated module and composite formulations carry tighter precision than legacy stamped steel due to concentrated supplier reporting. Forecasts reflect assumptions around regulatory enforcement continuity, material substitution elasticity, and OEM procurement consolidation trajectories. Practitioners should monitor NHTSA pedestrian protection rulemakings, EU REACH substance restriction sunset dates, and aluminum LME price volatility bands for early signals of specification or margin shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market