
 Global Automotive Damper Market | 2026-2036
Global Automotive Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Damper Market Analysis
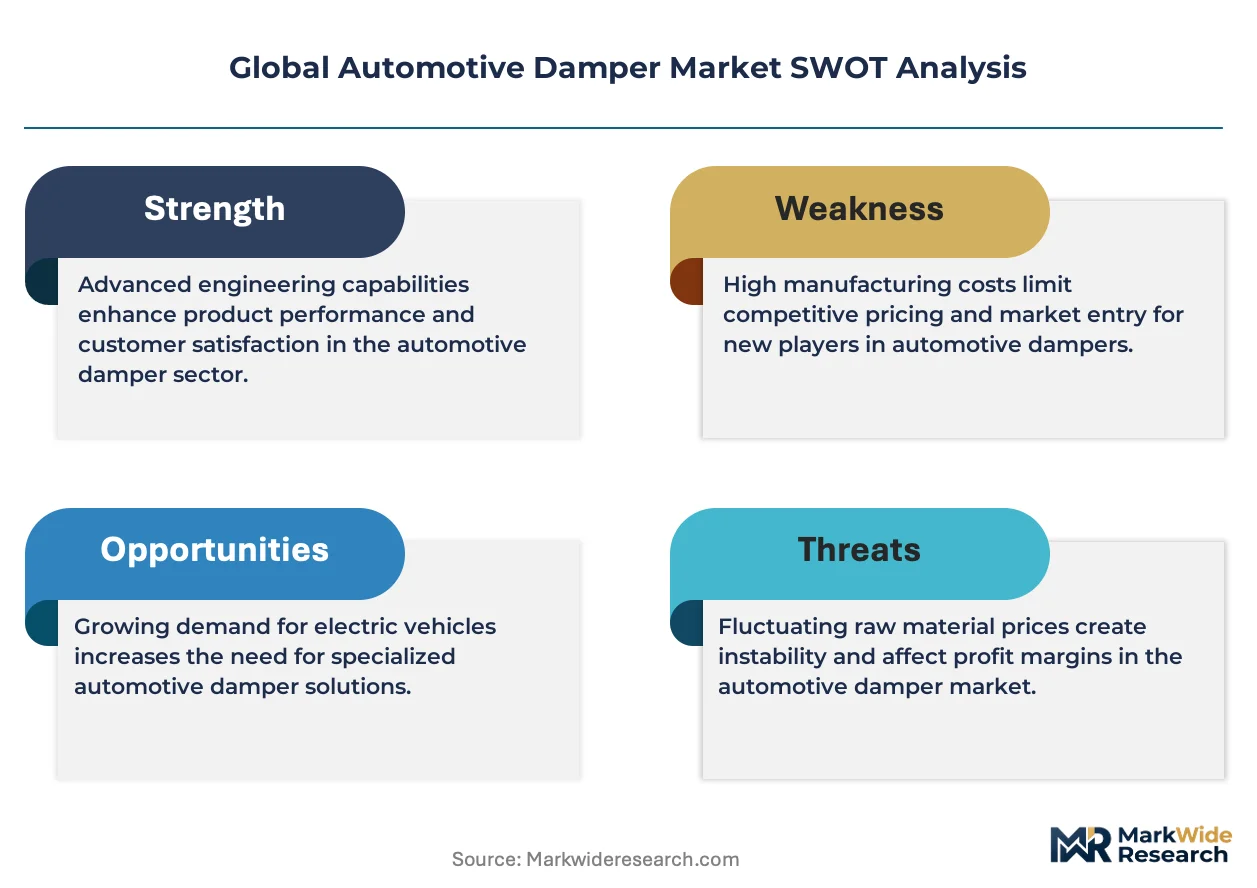
ISO 26262 functional safety certification is redrawing competitive boundaries for damper electronics suppliers. KYB Corporation leverages its integrated monotube manufacturing to sustain cost leadership across Asian supply chains. Tenneco anchors North American aftermarket distribution through captive channel control. ZF Friedrichshafen differentiates via electromagnetic damper portfolios tied to premium OEM platforms.
An automotive damper is a kinetic energy dissipation device, typically comprising a piston-cylinder assembly with hydraulic fluid or compressed gas, engineered to attenuate oscillatory motion between a vehicle's sprung and unsprung masses. Its primary function is to regulate suspension rebound and compression rates, ensuring tire contact stability and occupant comfort across variable road surfaces. Hydraulic dampers occupy mature, high-volume segments where steel-bodied twin-tube architectures dominate cost-sensitive passenger vehicle applications. Electromagnetic dampers represent the fastest-expanding product category, commanding premium positioning as automakers integrate real-time damping adjustment with ADAS sensor feeds. Aftermarket Providers face margin compression from extended OEM warranty periods, while OEM direct procurement concentrates around aluminum-intensive lightweight damper designs for electric vehicle range optimization.
F-Gas Regulation compliance in Europe mandates sealed-system integrity testing for pneumatic damper variants, reshaping supplier qualification timelines. China's NMPA enforces GB-standard crashworthiness protocols that specify damper failure modes under frontal impact scenarios, forcing structural redesigns for vehicles sold domestically. The US NHTSA maintains FMVSS 126 electronic stability control interoperability requirements that cascade into damper control module validation. Stakeholders must monitor regulatory divergence between emissions-focused European frameworks and safety-centric North American standards when allocating R&D budgets across regional product variants.
Market Dynamics
OEM procurement of adaptive suspension systems is concentrating around aluminum-intensive lightweight damper designs as electric vehicle range optimization overrides legacy steel architectures. This shift is compressing supplier margins while elevating electromagnetic damper portfolios tied to premium platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandates for sealed-system integrity testing in pneumatic dampers are accelerating supplier qualification investments and consolidating compliant vendor pools.
- China NMPA GB Standards:Crashworthiness protocols specifying damper failure modes under frontal impact are forcing structural redesigns for domestic-market vehicles.
- ADAS Sensor Convergence:Real-time damping adjustment integrated with autonomous driving feeds is creating new specification tiers for electromagnetic variants.
Market Restraints
- Aluminum Price Volatility:Lightweight damper housings depend on primary aluminum inputs exposed to LME price swings and energy surcharge pass-throughs.
- German Supply Concentration:Stuttgart-Munich engineering corridor clustering leaves Tier-1 procurement exposed to single-region logistics disruptions.
- Hydraulic Architecture Maturity:Steel-bodied twin-tube dampers face technical ceiling effects in thermal dissipation versus electromagnetic alternatives.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components create localized manufacturing offsets for damper electronics suppliers.
- US IRA Clean Vehicle Credits:Domestic content requirements for EV tax eligibility are pulling lightweight damper assembly toward North American facilities.
- Subscription-Based Calibration:Over-the-air damping profile updates represent emerging service revenue streams decoupled from hardware replacement cycles.
Industry Challenges
- ISO 26262 Functional Safety Certification:Electronics suppliers face 18-24 month validation timelines for damper control modules, compressing product launch windows.
- Legacy System Integration:Electromagnetic damper retrofits into existing CAN bus architectures generate protocol incompatibility costs and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Damper Market |
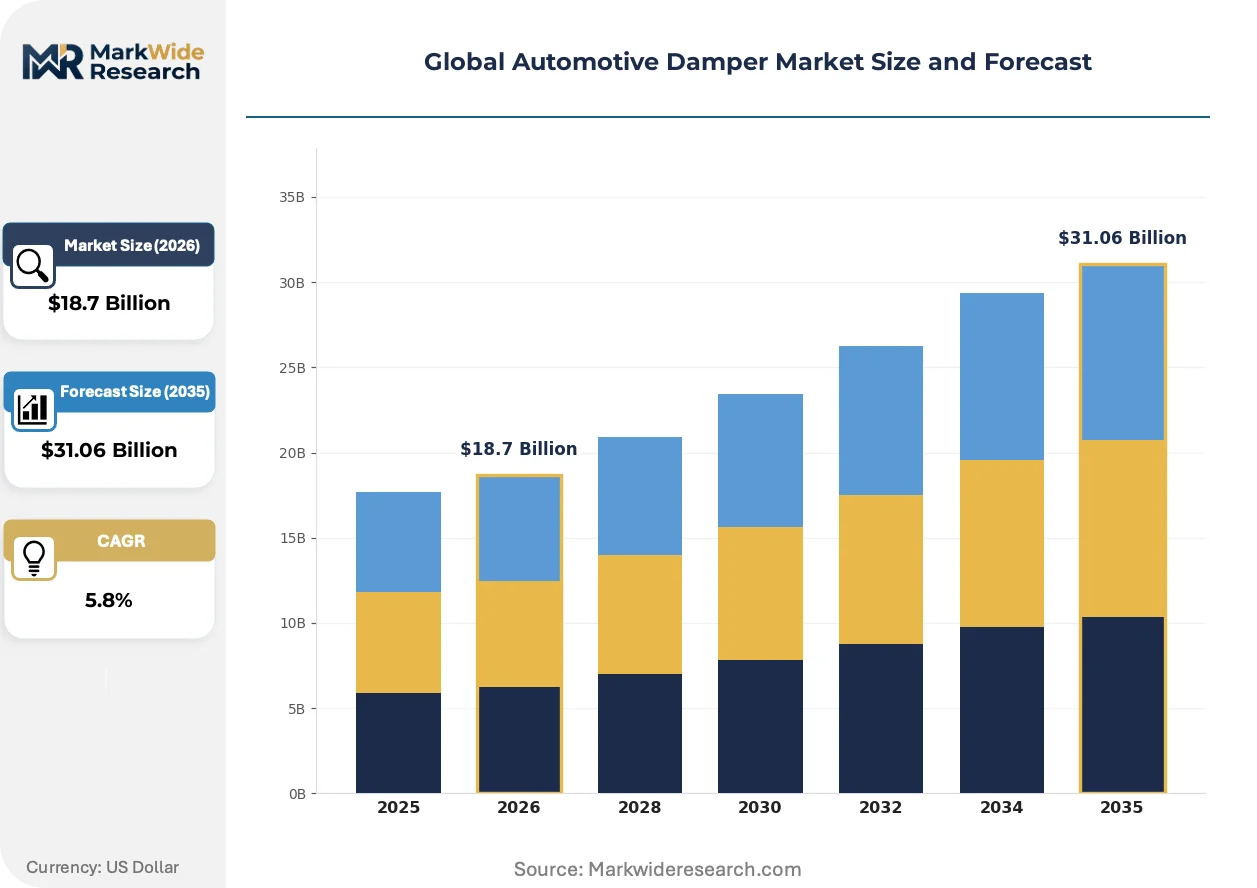
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Dampers, Pneumatic Dampers, Electromagnetic Dampers, Mechanical Dampers End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Aluminum, Steel, Composite, Plastic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles |
| Companies Covered | KYB Corporation, Marelli, Tenneco, BWI Group, HL Mando, ZF Friedrichshafen, Hitachi Astemo, KONI, Bilstein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Damper Market Emerging Trajectories
Damper technology trajectories are diverging between cost-optimized hydraulic architectures and sensor-rich electromagnetic systems, with regulatory compliance acting as the forcing function separating investment tiers.
Electromagnetic damper architectures is bifurcating the supplier base into captive OEM partnerships versus modular aftermarket providers. Premium electric SUV platforms are absorbing these units at accelerated specification rates. The technology is bifurcating competitive positioning between integrated system houses and component specialists unable to bridge electronics-hydraulics convergence.
Europe's F-Gas Regulation mandates refrigerant containment protocols for pneumatic damper variants, extending supplier qualification timelines by 8-12 months. Sealed-system integrity testing now gates market access for non-compliant architectures. Pneumatic damper suppliers serving German premium OEMs are absorbing the bulk of retooling costs.
Fleet procurement of dampers through lifecycle service contracts is displacing transactional aftermarket purchases. Leasing companies and mobility operators are consolidating specification authority previously held by independent repair channels. This pattern concentrates most visibly in corporate fleet segments across Germany and the Netherlands.
Global Automotive Damper Market Segmentation
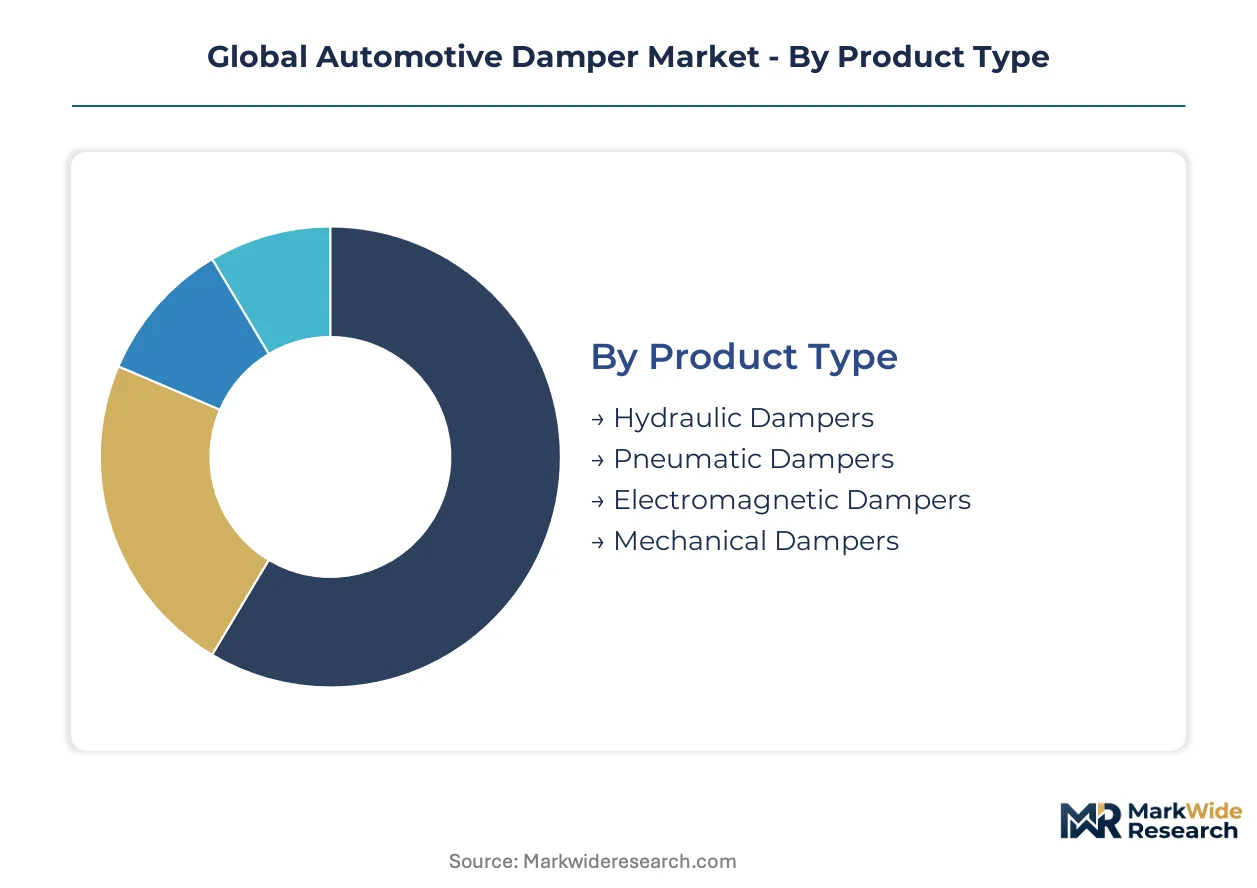
Automotive damper segmentation reveals divergent compliance burdens and material cost structures across product architectures. Regulatory frameworks in Europe, China, and North America impose distinct certification requirements that reshape supplier economics within each category.
Product Type:
Europe's F-Gas Regulation and China's GB standards enforce divergent sealed-system and crashworthiness protocols that segment supplier qualification investments across damper architectures.
- Hydraulic Dampers:Steel-bodied twin-tube assemblies with fixed orifice valving dominate high-volume passenger vehicle programs where cost sensitivity overrides adaptive performance. Procurement concentrates in India's compact vehicle manufacturing corridors and China's domestic-brand assembly plants, constrained by thermal dissipation ceilings that limit continuous duty cycles in heavy commercial applications.
- Electromagnetic Dampers:Real-time variable damping via solenoid-controlled fluid passages integrates with ADAS sensor feeds for premium electric SUV platforms. Specification rates are climbing fastest in Germany's Stuttgart-Munich engineering corridor where OEMs chase ride quality differentiation through suspension-integrated autonomous driving readiness.
- Pneumatic Dampers:Compressed gas spring-damper units face extended EU qualification timelines from sealed-system integrity testing mandates.
- Mechanical Dampers:Friction-based kinetic dissipation occupies two-wheeler and entry-level commercial vehicle segments with minimal electronics content.
Established volume favors hydraulic architectures; emerging adoption favors electromagnetic variants with sensor integration.
End User:
Customer-type segmentation tracks procurement authority migration from independent channels toward captive OEM control and fleet lifecycle contracting.
- OEMs:Direct specification of aluminum-intensive lightweight designs for electric vehicle range optimization concentrates procurement authority at Volkswagen Group, Stellantis, and BYD engineering centers. NHTSA FMVSS 126 stability control interoperability requirements cascade into damper control module validation costs absorbed by in-house integration teams.
- Tier-1 Suppliers:KYB Corporation, ZF Friedrichshafen, and Tenneco anchor damper subsystem supply through co-location with premium vehicle manufacturers in Germany, Japan, and Michigan. ISO 26262 functional safety certification for electronics modules compresses product launch windows to 18-24 months.
- Aftermarket Providers:Margin compression from extended OEM warranty periods and fleet lifecycle service contracts displaces transactional replacement demand.
- Vehicle Assemblers:Contract manufacturing arrangements in Mexico and Eastern Europe source damper modules through turnkey subsystem procurement.
Procurement authority is concentrating at OEMs and Tier-1 suppliers; aftermarket channels face share erosion from fleet contracting.
Material:
Material selection bifurcates between aluminum lightweighting for electric vehicle range targets and steel cost structures for internal combustion volume programs.
- Aluminum:Extruded and cast housing designs reduce unsprung mass for battery electric vehicle efficiency gains. LME price volatility and energy surcharge pass-throughs expose Tier-1 margins to commodity swings.
- Steel:High-strength steel twin-tube architectures retain cost leadership in India's subcompact passenger vehicle segment and China's domestic-brand commercial vehicle production.
- Composite:Carbon fiber reinforced polymer springs and housings penetrate motorsport and limited-production electric hypercar applications.
- Plastic:Glass-filled nylon guide bushings and seal carriers reduce friction in monotube damper assemblies.
Steel retains volume dominance; aluminum gains specification share fastest in premium electric platforms.
Application:
Application segmentation tracks divergent duty cycle requirements and regulatory exposure across vehicle weight classes and operating environments.
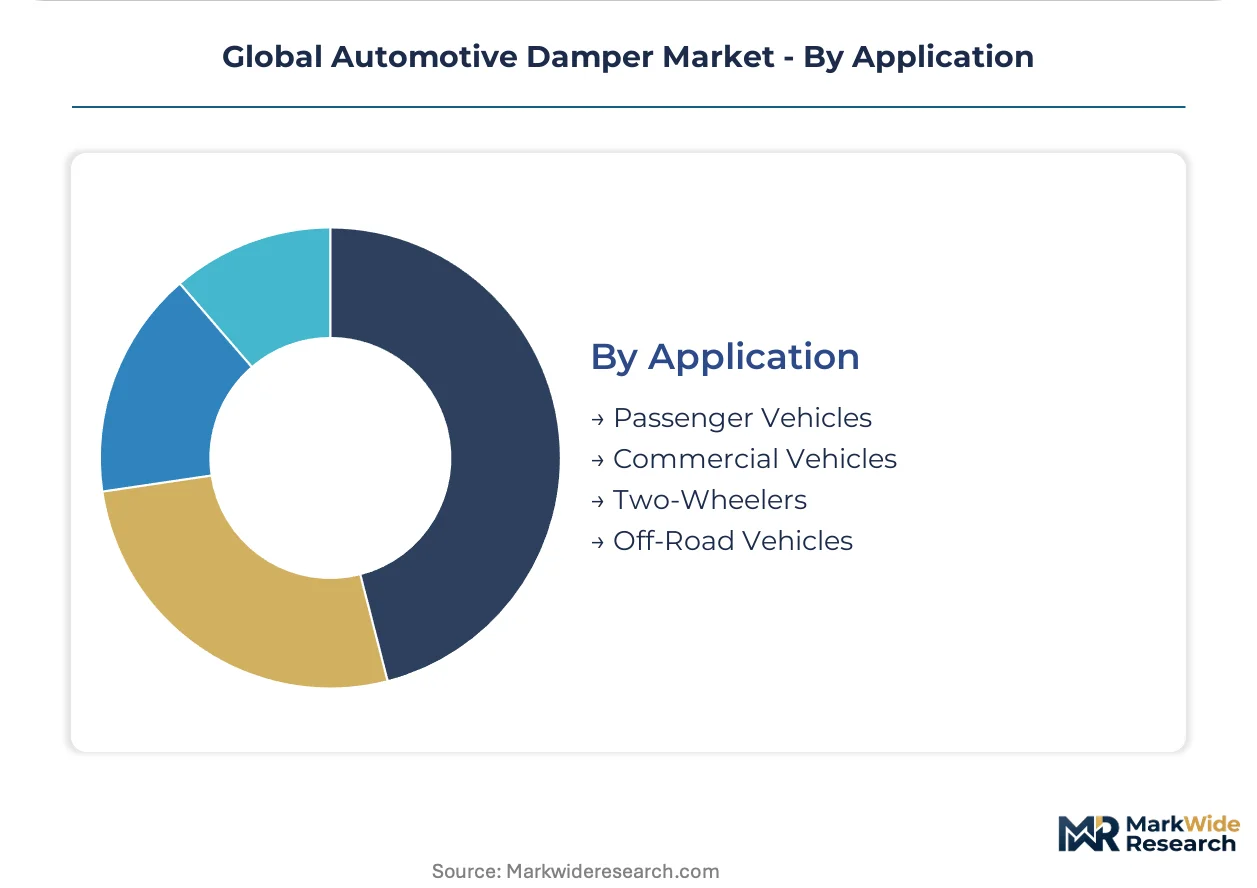
- Passenger Vehicles:Adaptive suspension specification rates are climbing in electric SUV segments where ride quality serves as primary differentiation. China's NMPA GB-standard crashworthiness protocols force structural redesigns for frontal impact damper failure modes in vehicles sold domestically.
- Commercial Vehicles:Heavy-duty truck and bus dampers face thermal loading from continuous highway operation that favors hydraulic architectures with external reservoir cooling.
- Two-Wheelers:Low-cost mechanical and basic hydraulic dampers dominate India's motorcycle and scooter production under PLI scheme localization incentives.
- Off-Road Vehicles:Agricultural and construction equipment dampers prioritize seal durability in contaminated operating environments over adaptive performance.
Passenger vehicle applications absorb the steepest technology investment; commercial vehicle procurement prioritizes durability over adaptive features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and carbon border adjustments are redirecting damper manufacturing footprints across major automotive economies. The EU's F-Gas Regulation and China's NMPA GB standards impose divergent compliance burdens that reshape regional supplier qualification timelines. Electric vehicle lightweighting mandates concentrate procurement authority in engineering corridors co-located with premium OEM headquarters.
China
Domestic-brand electric SUV production absorbs adaptive suspension systems at accelerating specification rates. NMPA enforces GB-standard crashworthiness protocols that mandate specific damper failure modes under frontal impact scenarios. The Yangtze River Delta manufacturing corridor around Shanghai hosts BYD and domestic OEM engineering centers where Tier-1 suppliers co-locate for program development.
Germany
Premium vehicle manufacturers in Stuttgart and Munich drive electromagnetic damper procurement for ride quality differentiation. The EU F-Gas Regulation mandates sealed-system integrity testing for pneumatic variants, extending supplier qualification timelines. Baden-Württemberg's automotive engineering corridor concentrates ZF Friedrichshafen and captive R&D facilities for ADAS-integrated suspension systems.
United States
IRA Clean Vehicle Credits pull lightweight damper assembly toward domestic facilities to satisfy EV tax eligibility content requirements. NHTSA maintains FMVSS 126 electronic stability control interoperability requirements that cascade into damper control module validation. Michigan's automotive supplier ecosystem anchors Tenneco's North American aftermarket distribution infrastructure.
Japan
Integrated monotube manufacturing expertise sustains cost leadership across Asian supply chains for hydraulic architectures. METI industrial policy supports advanced automotive component exports through quality certification harmonization. KYB Corporation's headquarters region in Tokyo anchors engineering coordination with Southeast Asian production networks.
India
PLI scheme incentives for advanced automotive components create localized manufacturing offsets for damper electronics suppliers. BIS standards govern automotive component quality benchmarks that align with export market requirements. Tamil Nadu and Maharashtra vehicle assembly corridors source cost-optimized hydraulic dampers for compact passenger programs.
Global Automotive Damper Market Vendor Landscape
Player mix skews toward integrated system houses with captive electronics capabilities and scale-driven hydraulic specialists serving volume programs. Market structure exhibits tiered consolidation where premium electromagnetic portfolios concentrate around German and Japanese engineering centers, while cost-optimized twin-tube architectures fragment across Asian supply bases. Two strategic archetypes dominate: integrated suspension-electronics system houses and component-focused hydraulic manufacturers. Competitive moves center on aluminum-intensive lightweighting investments and electromagnetic portfolio expansion tied to electric vehicle platforms.
Within the integrated system house tier, ZF Friedrichshafen and KYB Corporation exemplify archetypes bridging electronics-hydraulics convergence. Tenneco occupies a position representing North American aftermarket channel control. These three anchors illustrate divergent geographic specializations: German electromagnetic portfolio development, Japanese monotube cost leadership, and US captive distribution infrastructure.
| Leading Market Players |
|---|
| KYB Corporation |
| Marelli |
| Tenneco |
| BWI Group |
| HL Mando |
| ZF Friedrichshafen |
| Hitachi Astemo |
| KONI |
| Bilstein |
| Others |
Supply Flow & Price Mechanics
Aluminum substitution for steel in lightweight damper housings simultaneously redraws procurement geography toward LME price corridors and compresses supplier margins through energy surcharge pass-throughs. This material transition concentrates pricing power with primary metal traders while fragmenting fabrication economics across German, Chinese, and North American assembly footprints.
Pricing Analysis
Certification level creates the primary spread between ISO 26262-validated electromagnetic modules and basic hydraulic assemblies. Three-tier pricing structure across premium electromagnetic, standard hydraulic, and economy mechanical tiers reflects ADAS integration depth and functional safety investment. Cost compression in steel-bodied twin-tube segments is intensifying because India's PLI scheme localization absorbs margin buffers. Fleet procurement managers exhibit highest price sensitivity; captive OEM engineering centers demonstrate lowest sensitivity due to range-optimization mandates.
Supply Chain Analysis
China, Germany, and Japan anchor damper component fabrication across electromagnetic, hydraulic, and pneumatic architectures respectively. Supply chains draw from primary aluminum smelters, high-strength steel mills, and rare-earth magnet processors for solenoid assemblies. Single-source vulnerability concentrates in German engineering corridors where ZF Friedrichshafen and captive OEM facilities cluster around Stuttgart-Munich logistics nodes. Distribution runs through Tier-1 subsystem suppliers co-located with vehicle assembly plants rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive damper procurement is consolidating around software-defined vehicle platforms where suspension calibration becomes an over-the-air service layer. This ecosystem shift elevates electromagnetic portfolio holders while marginalizing hardware-only suppliers unable to bridge electronics-hydraulics convergence.
For Market Incumbents: Shield electromagnetic damper margins by deepening captive OEM partnerships around ADAS-integrated platforms. Accelerate ISO 26262 certification pipelines to compress competitor launch windows. Aluminum price hedging through long-term offtake agreements with Chinese smelters defends cost position against LME volatility. For New Entrants and Emerging Players: CE marking fast-track for pneumatic damper variants under F-Gas Regulation creates qualification arbitrage against incumbent retooling delays. Target India's PLI scheme corridor for cost-optimized hydraulic assembly serving domestic-brand compact vehicles. White-space exists in subscription-based damping calibration software decoupled from hardware replacement cycles. For Investors and Strategic Acquirers: EU F-Gas Regulation implementation reshapes the acquisition landscape toward sealed-system pneumatic specialists with compliant testing infrastructure. Five-to-ten year viability favors integrated electronics-hydraulics houses over component-focused fabricators. Monitor NMPA GB-standard enforcement velocity in China as inflection indicator for structural redesign cost absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Portfolio Expansion | ADAS sensor convergence with real-time damping adjustment captures premium electric SUV specification. |
| Aluminum Lightweighting Investment | Extruded housing designs reduce unsprung mass for BYD and Stellantis range optimization targets. |
| ISO 26262 Certification Acceleration | Functional safety validation compresses competitor product launch windows to 18-month cycles. |
| India PLI Localization | Tamil Nadu manufacturing offsets serve cost-sensitive domestic-brand compact vehicle programs. |
| Subscription Calibration Service Launch | Over-the-air damping profile updates generate recurring revenue decoupled from hardware replacement. |
Methodological Framework
Cross-validation between Tier-1 supplier procurement interviews and OEM platform engineering disclosures anchors the qualitative findings. Primary fieldwork encompassed damper subsystem directors, vehicle dynamics engineers at premium manufacturers, aftermarket distribution heads, and regulatory compliance officers across Germany, China, and Michigan. Secondary validation drew from NHTSA FMVSS 126 filings, EU F-Gas Regulation implementation guidance, NMPA GB-standard technical bulletins, and vehicle production databases. Bottom-up bill-of-materials costing and top-down market sizing triangulate volume estimates.
Sensitivity analysis around aluminum price trajectories and electromagnetic adoption curves shapes the projection framework. Segmentation dimensions span product architecture, material composition, vehicle application, and regional production cluster. CAGRs derive from installed base modeling and content-per-vehicle escalation across the analysis window. Forecast inputs include EV penetration rates by vehicle class and ADAS sensor integration timelines from OEM platform roadmaps.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation would warrant model refresh. Specific risks include NMPA structural redesign mandates, F-Gas qualification timeline extensions, and IRA domestic content threshold adjustments. Recalibration cycles align with material shifts in regulatory enforcement velocity and primary aluminum LME pricing bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Rear Spoiler Market