
 Ferrocene Market | 2026-2036
Ferrocene Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrocene Market Analysis
Specialty additive formulation revenue is reconfiguring margin pools away from commodity ferrocene sales toward higher-purity grades. Tianyuan Group anchors downstream supply through integrated catalyst manufacturing in Liaoning Province. Tanyun Chemical differentiates via pharmaceutical-grade purification capabilities that command premium positioning. Yixing Lianyang Chemical leverages regional logistics infrastructure to sustain cost leadership in industrial-grade volumes.
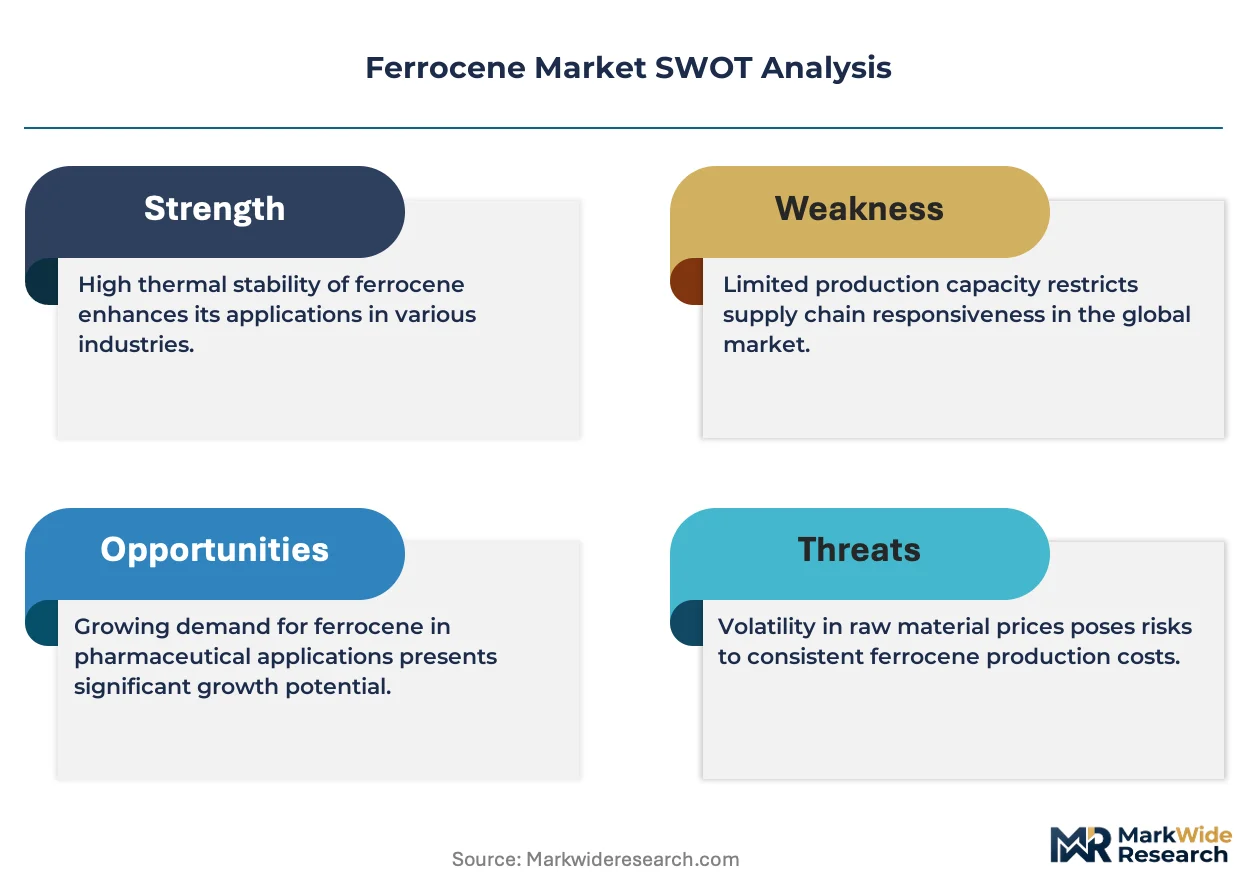
Ferrocene is an organometallic compound with the formula Fe(C5H5)2, consisting of two cyclopentadienyl anions bound to a central iron(II) atom, typically synthesized via the Grignard method or direct reaction of iron salts with cyclopentadiene. It serves primarily as a precursor for high-octane fuel additives, polymerization catalysts, and pharmaceutical intermediates. Industrial-grade ferrocene dominates volume throughput for fuel additive applications, while pharmaceutical-grade commands the highest unit margins due to stringent purity protocols. Catalyst applications represent the fastest-growing demand segment as refiners adopt metallocene-based polymerization systems.
China's SAMR enforces GB standards that dictate ferrocene purity thresholds for domestic chemical distribution, while REACH registration requirements in Europe constrain market access for non-compliant exporters. The EPA oversees residual iron content limits in fuel additive formulations under the Clean Air Act framework. Stakeholders must monitor evolving pharmaceutical-grade certification requirements across multiple jurisdictions to anticipate margin migration toward regulated end uses.
Market Dynamics
Defense procurement of high-purity ferrocene derivatives for solid rocket propellants is restructuring volume allocation toward specialized grades, while China's tightening GB standards are forcing purification capability investments across export-oriented supply chains.
Growth Catalysts
- REACH registration mandates:European chemical compliance requirements are filtering non-compliant producers from Western supply chains, concentrating procurement among certified refiners.
- Metallocene polymerization systems:Refinery adoption of single-site catalyst architectures is accelerating consumption of ferrocene-derived co-catalyst precursors.
- Yangtze River Delta clustering:Chemical manufacturing agglomeration around Shanghai-Ningbo port infrastructure is reducing logistics friction for export-grade ferrocene.
Market Restraints
- Cyclopentadiene feedstock volatility:Crude C5 fraction pricing swings directly compress ferrocene production margins without downstream pass-through mechanisms.
- High-purity synthesis bottlenecks:Pharmaceutical-grade sublimation and recrystallization capacity constraints limit supply elasticity for certified derivatives.
- Iron powder substitution in fuel additives:Lower-cost metallic iron dispersants threaten industrial-grade ferrocene volumes in cost-sensitive burner applications.
Strategic Opportunities
- India's defense indigenization:DRDO propellant formulation programs are creating import substitution demand for domestically manufactured ferrocene.
- Dual carbon policy alignment:China's MEE emissions trading schemes favor ferrocene-based combustion efficiency additives over heavier metal alternatives.
- Continuous flow synthesis:Microreactor process intensification is hybridizing batch Grignard production with real-time quality control for pharmaceutical contracts.
Industry Challenges
- Organometallic chemist scarcity:Specialized synthesis expertise for air-sensitive metallocene production is concentrating among aging technical workforces in Liaoning and Shandong provinces.
- Multi-jurisdiction certification timelines:Pharmaceutical-grade ferrocene requires sequential filings with FDA, EMA, and NMPA, extending revenue recognition cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrocene Market |
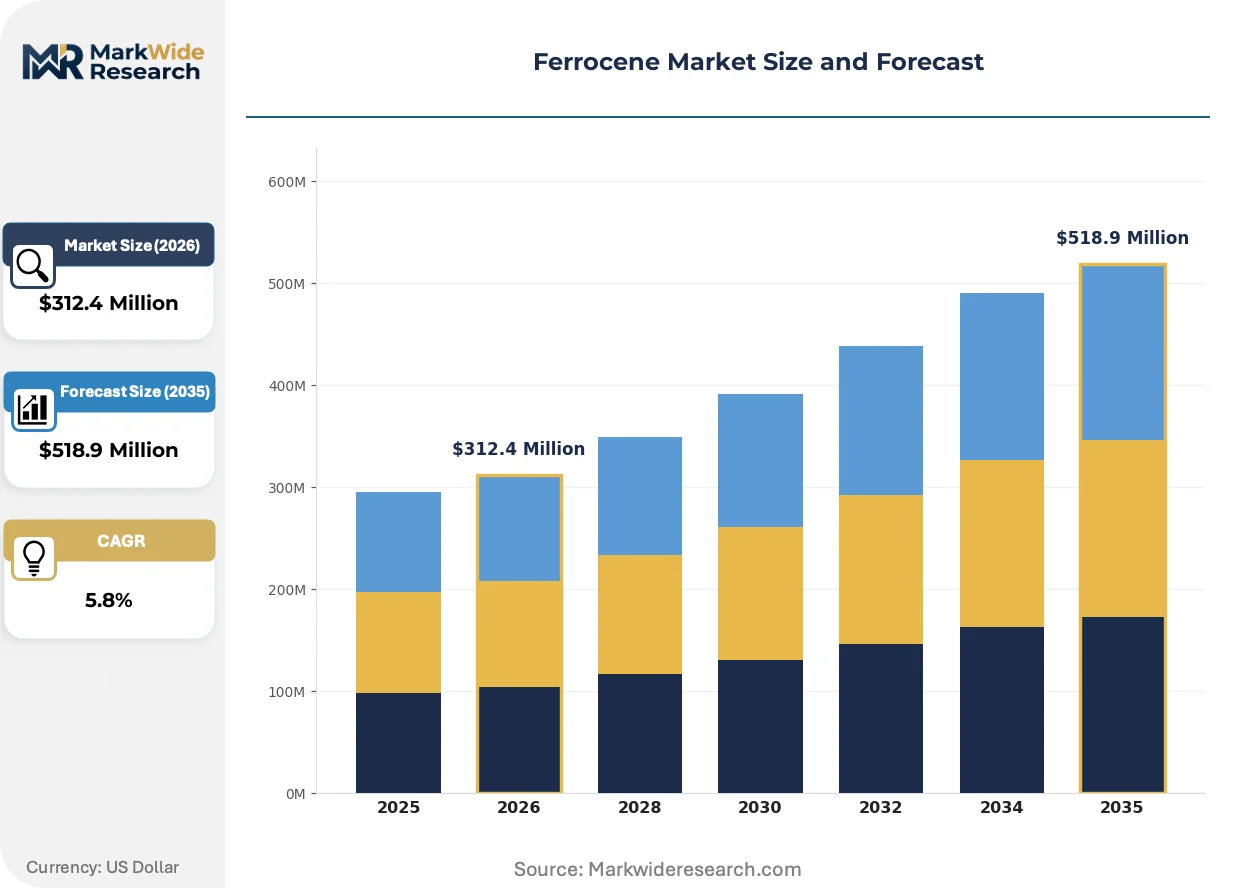
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Research Grade Application: Catalysts, Coatings, Additives, Liquid Crystals End User: Chemicals, Pharmaceuticals, Automotive, Electronics Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | The Third Plant of Haicheng Chemical, Yixing Lianyang Chemical, Yixing Weite, Tianyuan Group, HAIHUA, Binhai Bluesky Chemical, Tanyun Chemical, Hefei TNJ Chemical Industry Co. Ltd., Donggang Xinbao, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrocene Market Emerging Trajectories
Process intensification and regulatory harmonization are compressing traditional batch manufacturing timelines while elevating purity specifications as the primary competitive differentiator across end-use segments.
Continuous sublimation purification is hybridizing traditional batch crystallization with in-line spectroscopic monitoring. Specialty chemical producers serving pharmaceutical intermediates are retrofitting legacy equipment at accelerated capital deployment schedules. This convergence is enabling real-time impurity rejection that previously required multi-week analytical hold periods.
REACH Annex XIV authorization requirements are expanding substance restriction lists to cover ferrocene derivatives with specific impurity profiles. German and French chemical distributors are demanding full SVHC disclosure documentation prior to contract execution. Catalyst formulators targeting European polymer producers are reformulating specifications to preempt regulatory exclusion.
Specification-driven procurement is consolidating buyer decision criteria around certified purity tiers rather than commodity spot pricing. Defense contractors and pharmaceutical intermediates manufacturers are embedding technical audit requirements into multi-year supply agreements. This behavioral pivot is most pronounced in procurement offices across the US Atlantic seaboard and Northern European chemical processing hubs.
Ferrocene Market Segmentation
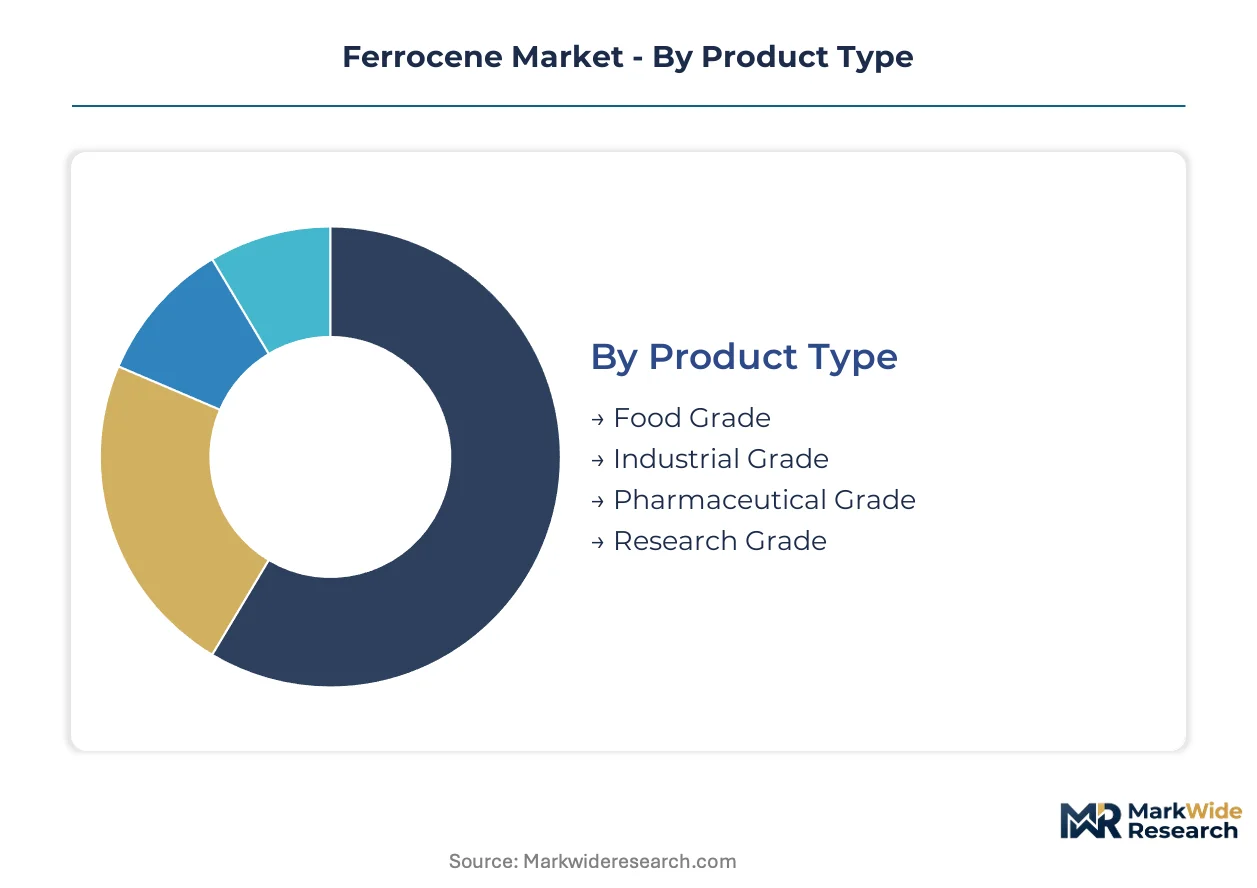
Ferrocene segmentation tracks a stark divergence between commodity-grade fuel additive volumes and pharmaceutical-grade margin capture. Purity thresholds dictate procurement behavior across defense, automotive, and pharmaceutical end uses with minimal overlap in supplier qualification.
Product Type:
Purity tier determines pricing architecture and regulatory burden across all downstream applications.
- Pharmaceutical Grade:Sub-ppm impurity specifications require multi-stage sublimation and recrystallization protocols. US FDA and EU EMA certification timelines extend supplier onboarding to 18-24 months, concentrating viable supply among Liaoning and Shandong purification specialists.
- Industrial Grade:Standard ferrocene serves fuel additive and polymerization catalyst precursors with 98-99% purity thresholds. China's Yangtze River Delta chemical cluster dominates export volume through integrated C5 feedstock access.
- Food Grade:Regulatory authorization for direct food contact remains limited across major jurisdictions, constraining commercial deployment to specialized antioxidant applications.
- Research Grade:Small-batch production for academic and national laboratory procurement operates outside commercial scale economics with highly variable specification requirements.
Industrial grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
Application:
Functional role in downstream chemical processes segments demand by technical performance requirements and substitution risk.
- Catalysts:Metallocene polymerization systems consume ferrocene-derived co-catalyst precursors for single-site polyethylene and polypropylene production. Refinery adoption in Germany, China, and the US is climbing the fastest as Ziegler-Natta displacement accelerates.
- Additives:Combustion efficiency modifiers for solid rocket propellants and high-octane gasoline formulations require precise iron content delivery. Defense procurement in India and the US is concentrating demand for certified high-purity derivatives.
- Coatings:UV-stable organometallic pigments and corrosion inhibitors utilize ferrocene derivatives in specialty automotive and marine applications with moderate volume throughput.
- Liquid Crystals:Niche display material applications exploit ferrocene's electrochemical stability for advanced optoelectronic components in South Korean and Japanese manufacturing.
Catalyst applications command technology premiums. Additive volumes anchor baseline throughput.
End User:
Customer industry determines specification stringency, contract duration, and supplier audit intensity.
- Pharmaceuticals:Active pharmaceutical intermediate synthesis requires NMPA, FDA, and EMA multi-jurisdiction filing compliance. Sequential regulatory approval extends revenue recognition cycles and concentrates procurement among pre-qualified contract manufacturers.
- Chemicals:Bulk catalyst and additive formulation represents the highest volume segment with procurement weighted toward annual supply agreements and technical audit requirements.
- Automotive:Fuel efficiency regulations in China and the US sustain demand for ferrocene-based combustion modifiers as OEMs optimize emissions profiles under MEE and EPA frameworks.
- Electronics:Specialty materials for semiconductor and display manufacturing utilize ultra-high purity ferrocene with stringent particulate and ionic contamination limits.
Chemical sector procurement holds contract volume. Pharmaceutical qualification is tightening supplier concentration.
Distribution Channel:
Channel structure reflects customer scale, geographic dispersion, and technical service requirements.
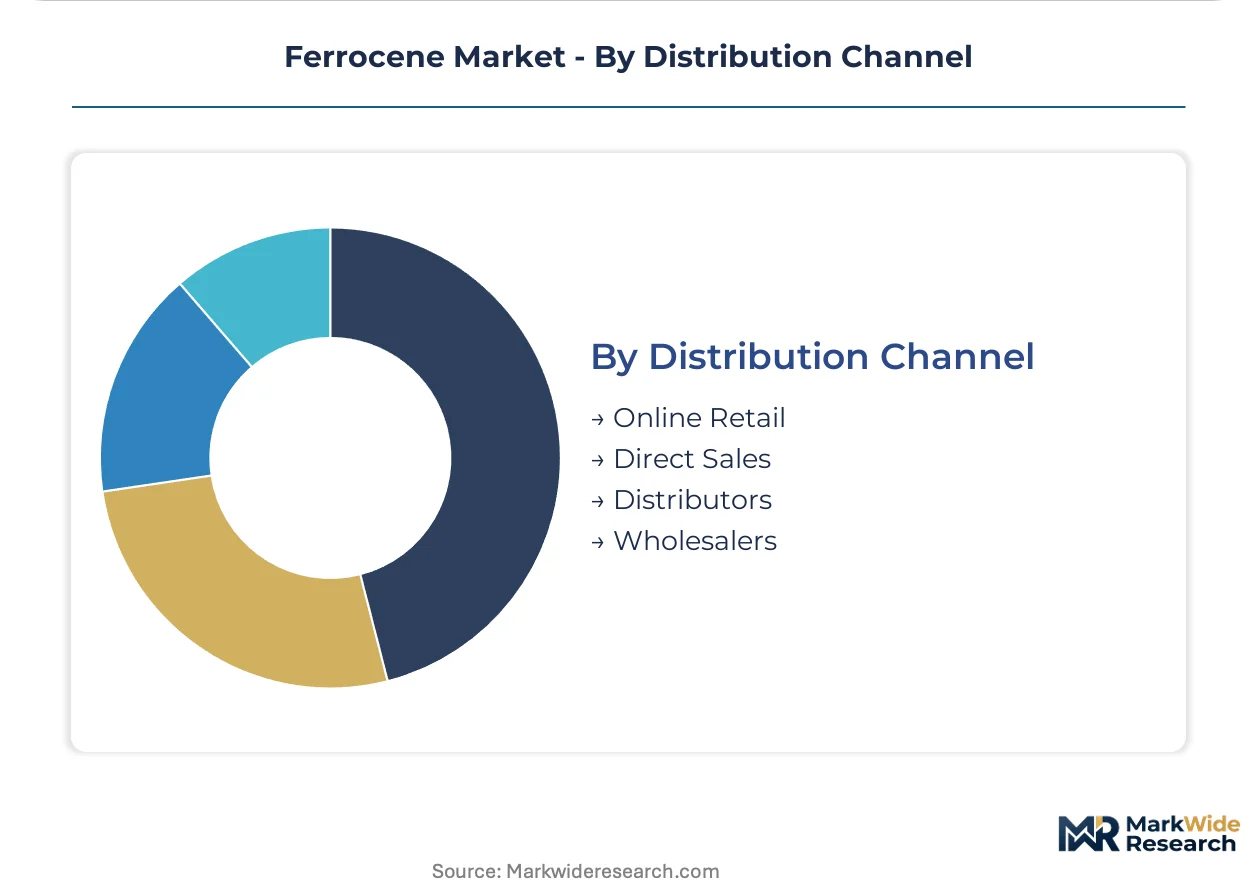
- Direct Sales:Large-volume catalyst and additive formulators negotiate multi-year supply agreements with embedded purity certification and technical audit clauses. Defense contractors and multinational polymer producers dominate this channel.
- Distributors:Regional chemical distributors serve mid-tier pharmaceutical and coatings manufacturers with inventory positioning and regulatory documentation support.
- Online Retail:Research grade and small-batch industrial quantities move through specialized chemical procurement platforms serving academic and laboratory customers.
- Wholesalers:Commodity-grade ferrocene for non-critical industrial applications flows through bulk chemical wholesalers with minimal technical service attachment.
Direct sales holds margin concentration. Distributor relationships are rotating up the share rankings in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: defense contractors in the United States prioritize high-purity derivatives for propellant formulations, while Chinese chemical manufacturers concentrate on industrial-grade volumes for fuel additive export markets.
China
SAMR's tightening GB standards for chemical purity are forcing purification investments across Liaoning and Shandong export corridors. The Yangtze River Delta chemical manufacturing cluster around Shanghai-Ningbo ports anchors global industrial-grade throughput with integrated C5 feedstock access.
United States
Defense procurement of solid rocket propellant additives concentrates demand for certified high-purity ferrocene along the Atlantic seaboard. EPA residual iron content limits under the Clean Air Act framework constrain fuel additive formulation specifications for automotive catalyst applications.
Germany
REACH Annex XIV authorization requirements and SVHC disclosure mandates are filtering non-compliant producers from polymer catalyst supply chains. German chemical distributors in the Rhine-Ruhr industrial region now demand full regulatory documentation prior to ferrocene derivative contract execution.
India
DRDO propellant formulation programs under defense indigenization policies are creating import substitution demand for domestically manufactured ferrocene. The country's national pharmaceutical regulator is aligning active pharmaceutical intermediate filing requirements with FDA and EMA precedents to accelerate contract manufacturer qualification.
Japan
METI industrial policy supports metallocene polymerization system adoption at refineries in the Chubu and Kansai regions. Japanese display manufacturers in Kyushu utilize ultra-high purity ferrocene for niche liquid crystal optoelectronic components with stringent particulate contamination limits.
Ferrocene Market Vendor Landscape
Capability concentration sits with purification specialists commanding pharmaceutical-grade premiums; scale advantage sits with integrated chemical groups capturing industrial-grade volumes. The vendor base organizes around three archetypes: Liaoning-based integrated catalyst manufacturers, Jiangsu province industrial-grade volume producers, and pharmaceutical-focused sublimation specialists. Dominant competitive moves include backward integration into C5 feedstock processing and multi-jurisdiction certification filing to preempt regulatory exclusion.
Among Chinese chemical producers, Tianyuan Group exemplifies the integrated catalyst manufacturing archetype through its Liaoning province operations. Tanyun Chemical occupies a position within the pharmaceutical-grade purification tier, while Yixing Lianyang Chemical represents the industrial-grade volume strategy anchored in regional logistics infrastructure.
| Leading Market Players |
|---|
| The Third Plant of Haicheng Chemical |
| Yixing Lianyang Chemical |
| Yixing Weite |
| Tianyuan Group |
| HAIHUA |
| Binhai Bluesky Chemical |
| Tanyun Chemical |
| Hefei TNJ Chemical Industry Co. Ltd. |
| Donggang Xinbao |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Liaoning Province's pharmaceutical-grade sublimation capacity is compressing spot premiums while tightening contract discipline among defense contractors seeking certified high-purity derivatives. This utilization asymmetry between industrial-grade oversupply and pharmaceutical-grade bottlenecks is reconfiguring procurement leverage across buyer archetypes.
Pricing Analysis
Long-term offtake agreements dominate procurement for defense contractors and multinational polymer producers, embedding purity certification and technical audit clauses that insulate suppliers from cyclopentadiene feedstock volatility. Three-tier pricing structure across pharmaceutical, industrial, and research grades separates sub-ppm certified derivatives from standard 98-99% purity volumes. Cost compression in industrial-grade spot markets is intensifying because iron powder substitution threatens burner application volumes. Mid-tier catalyst formulators exhibit highest price sensitivity, while pharmaceutical intermediates manufacturers accept premium positioning for multi-jurisdiction certification security.
Supply Chain Analysis
Contract manufacturing concentration rests with Liaoning and Shandong purification specialists commanding pharmaceutical-grade premiums, while Jiangsu province volume producers anchor industrial-grade throughput. Raw material dependencies center on crude C5 fraction availability, iron powder quality, and specialized organometallic synthesis reagents. Single-source vulnerability concentrates in aging technical workforces across northeastern China with limited air-sensitive metallocene expertise. Distribution runs through direct sales channels for large-volume catalyst formulators and regional distributors serving mid-tier pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized synthesis expertise for air-sensitive ferrocene production is thinning across aging technical workforces, creating asymmetric capability access that favors incumbents with captive purification assets and isolates new entrants without multi-year certification runway.
For Market Incumbents: Pre-empt regulatory exclusion by accelerating FDA, EMA, and NMPA sequential filings for pharmaceutical-grade derivatives before REACH Annex XIV authorization expansions tighten further. Backward integration into C5 feedstock processing secures margin control against cyclopentadiene volatility, while continuous flow synthesis investments hybridize batch Grignard production with real-time quality control for defense contract capture. For New Entrants and Emerging Players: Build out domestic Indian ferrocene manufacturing capacity to serve DRDO propellant formulation programs under defense indigenization policies, bypassing established Chinese export corridors. India's pharmaceutical intermediate sector offers the most penetrable entry point given alignment of CDSCO filing requirements with FDA and EMA precedents. Position through contract manufacturing partnerships with existing purification specialists rather than greenfield sublimation capacity. For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-grade purification specialists with existing multi-jurisdiction certification and sublimation asset bases that can be scaled for metallocene polymerization co-catalyst demand. Long-term viability hinges on regulatory moat depth rather than commodity volume exposure. Watch for REACH Annex XIV substance restriction list expansions covering specific ferrocene impurity profiles as inflection signal for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C5 Feedstock | Captive cyclopentadiene supply insulates margins from crude fraction volatility at Yangtze River Delta producers. |
| Continuous Flow Synthesis Adoption | Microreactor process intensification enables real-time quality control for pharmaceutical-grade defense contracts. |
| Multi-Jurisdiction Certification Filing | Sequential FDA, EMA, and NMPA submissions preempt regulatory exclusion under tightening SAMR GB standards. |
| Long-term Defense Supply Agreement | Embedded technical audit clauses with Atlantic seaboard contractors secure volume allocation amid procurement consolidation. |
| Organometallic Chemist Workforce Development | Specialized air-sensitive synthesis training addresses capability scarcity concentrating in Liaoning and Shandong provinces. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with plant managers at Liaoning purification facilities, procurement leads at downstream polymer producers, distribution channel partners in the Yangtze River Delta, and technical R&D directors specializing in metallocene synthesis. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed specialty chemical producers, SAMR GB standard documentation, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Calibration against historical purity-grade pricing spreads and defense procurement contract structures anchored projections across the analysis window. Segmentation dimensions modeled include purity tier, end-use application, regional production hub, and customer industry vertical. CAGRs were derived from elasticity-adjusted demand curves incorporating metallocene polymerization system adoption rates and pharmaceutical intermediate filing timelines. Industry-specific forecast inputs captured DRDO propellant indigenization schedules and EPA residual iron content limit enforcement patterns.
Stress conditions across cyclopentadiene feedstock price bands, REACH authorization timeline delays, and pharmaceutical-grade capacity expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization pace and defense procurement continuity. Cross-checking against ECHA SVHC disclosure trends and SAMR enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Silicone Fluid Market