
 Automotive Biofuel Market | 2026-2036
Automotive Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Biofuel Market Outlook
Advanced certification tiers for low-carbon fuel standards is unwinding competitive dynamics across the automotive biofuel supply base. Neste Corporation leverages proprietary NEXBTL refining technology to dominate renewable diesel output in Northern Europe. POET LLC anchors its position through backward integration into corn ethanol production across the US Midwest. Valero Energy Corporation extends its reach by operating integrated biorefineries alongside conventional fuel assets.
Automotive biofuel denotes liquid or gaseous fuels derived from biomass feedstocks, chemically processed to achieve cetane ratings above 51 or octane thresholds compatible with internal combustion engines, serving primarily to displace petroleum-derived gasoline and diesel in transportation applications. Biodiesel and renewable diesel command the largest share of current blending volumes, though renewable diesel is displacing conventional biodiesel in cold-climate markets due to superior cloud-point performance. Waste oils as a feedstock category are attracting capital faster than virgin oilseeds, as processors seek margin protection against agricultural commodity volatility.
The EPA administers Renewable Fuel Standard volume obligations that mandate minimum biofuel blending percentages for US refiners, while the EU Green Deal and F-Gas Regulation collectively tighten carbon intensity thresholds for fuels sold across member states. India's BIS and PLI scheme are establishing domestic ethanol blending mandates that redirect sugarcane processing capacity toward fuel output. Stakeholders must monitor how regulatory credit trading mechanisms evolve, as certificate price volatility increasingly determines project returns more than underlying fuel margins.
Market Dynamics
Renewable diesel is supplanting conventional biodiesel across cold-climate fleets as cloud-point performance becomes the decisive procurement criterion for heavy-duty operators. This feedstock-driven technology rotation is compressing margins for first-generation processors while redirecting capital toward waste-oil refining infrastructure.
Growth Catalysts
- EU Green Deal renewable energy mandates:The directive tightens carbon intensity thresholds for transportation fuels, forcing refiners to blend higher volumes of advanced biofuels or purchase compliance credits.
- India's PLI scheme for ethanol:Production-linked incentives redirect sugarcane processing capacity toward fuel output, creating dedicated offtake for domestic distillers.
- Cellulosic ethanol technology maturation:Enzymatic hydrolysis advances reduce conversion costs for agricultural residue feedstocks, opening non-food biomass pathways.
Market Restraints
- Agricultural commodity volatility:Corn and soybean oil price swings compress processor margins, making waste-oil feedstocks the only viable hedge against input cost spikes.
- Refining capacity concentration:Renewable diesel output clusters in Finland, the Netherlands, and Singapore, creating geographic supply risk for inland European and North American markets.
- F-Gas Regulation compliance friction:The EU framework imposes complex certification requirements on biofuel-derived process gases, delaying project commissioning timelines.
Strategic Opportunities
- Brazil's low-carbon fuel standard expansion:RenovaBio credit mechanisms reward carbon-negative feedstocks, creating first-mover advantage for waste-to-fuel processors.
- Renewable natural gas convergence:Biogas upgrading and bio-LNG liquefaction technologies merge with liquid biofuel distribution networks, unlocking dual-fuel fleet contracts.
- Digital carbon accounting platforms:Blockchain-tracked supply chain verification commands premium pricing from scope-3-conscious corporate fleet operators.
Industry Challenges
- ISCC certification timeline compression:Third-party audit backlogs delay market access for new waste-oil collectors seeking EU renewable fuel qualification.
- Biorefinery capex intensity:Hydrotreating units for renewable diesel require nine-figure capital commitments, restricting participation to balance-sheet-heavy integrated refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Biofuel Market |
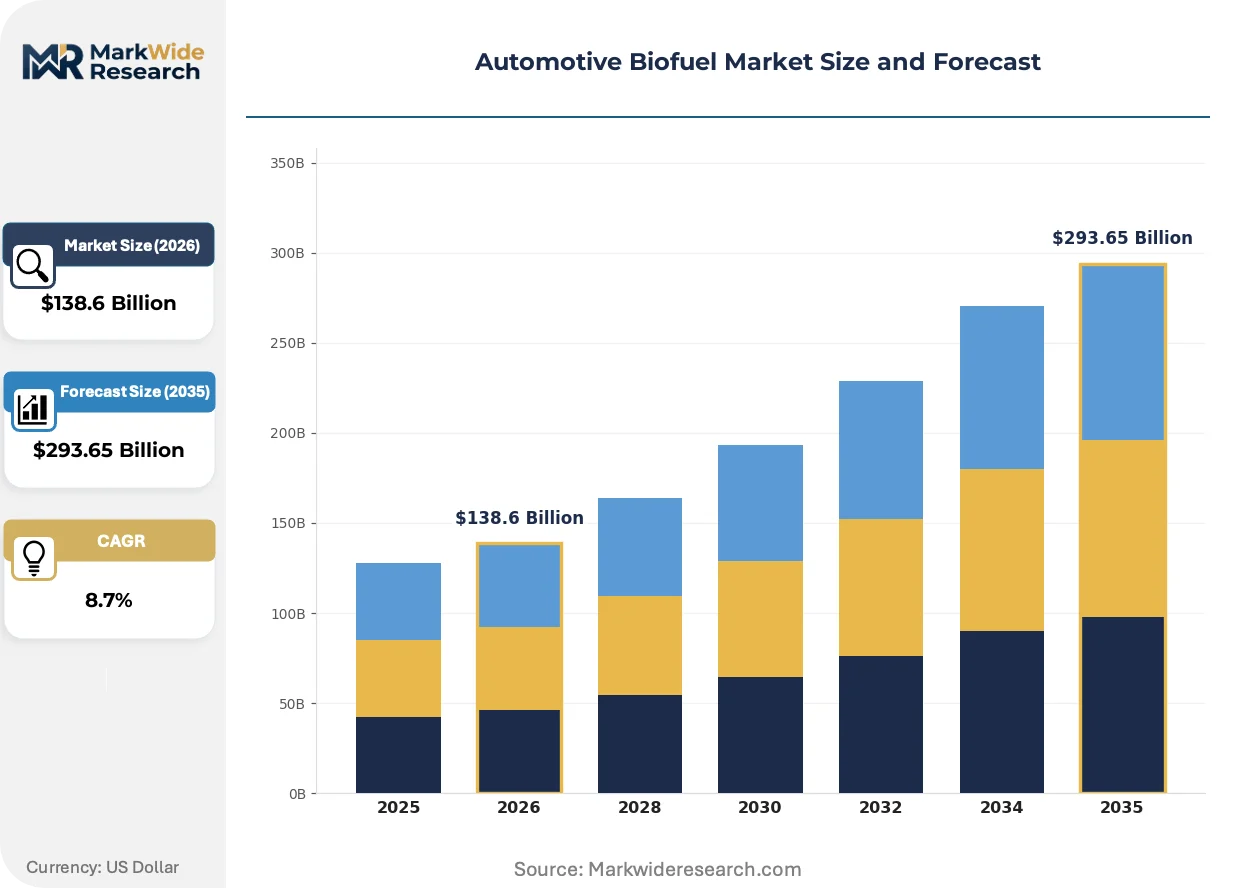
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioethanol, Biodiesel, Renewable Diesel, Biogas Feedstock: Corn, Sugarcane, Soybean, Waste Oils End User: Passenger Vehicles, Light Commercial Vehicles, Heavy Duty Trucks, Motorcycles Distribution Channel: Retail Outlets, Online Platforms, Fleets, Partnerships |
| Companies Covered | Archer Daniels Midland, Neste Corporation, Valero Energy Corporation, Cargill, POET LLC, Renewable Energy Group, Bunge Limited, BP, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Biofuel Market Strategic Shifts
Technology convergence between enzymatic processing and digital traceability is compressing certification timelines while fragmenting the processor base. These shifts reward operators who control both feedstock sourcing and carbon accounting infrastructure.
Hydroprocessed esters and fatty acids (HEFA) refining is supplanting transesterification-based biodiesel production across Nordic and Baltic markets. Cold-climate fleet operators in Finland and Sweden now specify renewable diesel exclusively, forcing southern European biodiesel plants into idleness or costly retrofit. This technology rotation is concentrating margin capture with hydrotreater owners while liquidating first-generation capacity.
The EPA's Renewable Fuel Standard volume obligations now include a nested advanced biofuel category with separate D5 RIN generation. US refiners face escalating compliance costs for conventional renewable identification numbers, redirecting capital toward cellulosic and biomass-based diesel pathways. Merchant refiners without integrated biorefinery assets now trade RIN volatility as a core P&L line item.
Fleet procurement contracts now embed scope-3 emissions clauses that require mass-balance-certified fuel delivery. Heavy-duty truck operators in Germany and California demand quarterly carbon intensity scorecards, displacing spot-market biofuel purchasing. This contractual evolution forces fuel suppliers to invest in in-house lifecycle analysis capabilities or lose multi-year tender participation rights.
Automotive Biofuel Market Segmentation
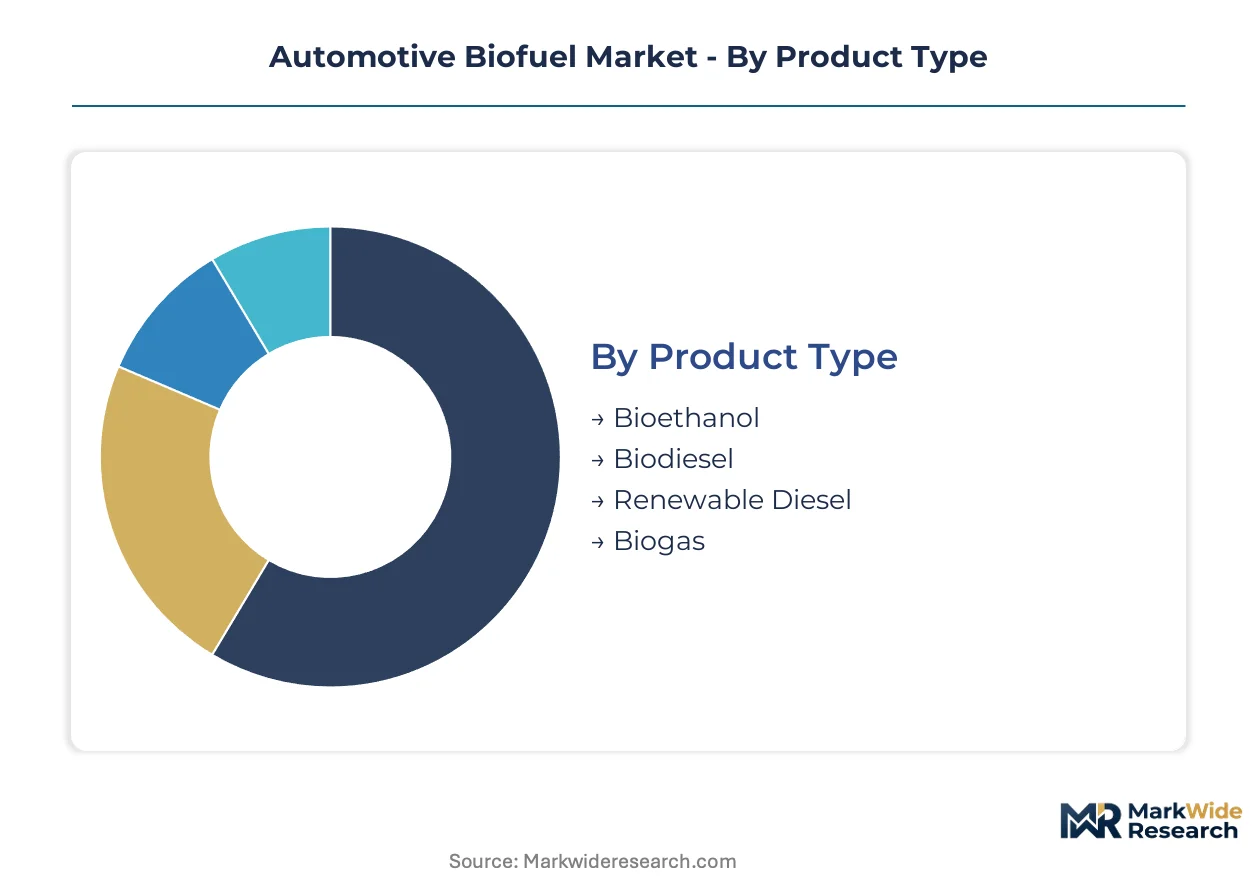
Automotive biofuel segmentation reveals divergent margin pressures across product chemistry and feedstock sourcing. Procurement patterns vary sharply between fleet operators seeking cold-climate performance and refiners optimizing for carbon intensity scoring.
Product Type:
Renewable diesel and biogas face the strongest substitution pressure from electrification in light-duty segments, while heavy transport retains liquid fuel dependence.
- Bioethanol:Fermented starch or sugar feedstocks yield oxygenated gasoline blending components with 113 octane ratings. US Midwest corn ethanol dominates volume, though Brazilian sugarcane ethanol achieves lower carbon intensity scores under California's LCFS. EPA RIN obligations sustain domestic demand despite electric vehicle penetration in passenger segments.
- Renewable Diesel:Hydrotreated vegetable oils and animal fats produce paraffinic diesel meeting ASTM D975 specifications with cloud points below -20°C. Finnish and Singaporean refiners supply Nordic heavy-duty fleets that reject conventional biodiesel for winter operability. Hydrogen consumption per barrel creates feedstock cost sensitivity.
- Biodiesel:Fatty acid methyl esters from transesterification deliver cetane ratings of 46-52 but gel above 0°C in high-oleic formulations. Southern European plants face idleness as cold-climate operators switch to renewable diesel.
- Biogas:Upgraded methane from anaerobic digestion serves compressed natural gas fleets in Sweden and compressed biomethane networks across Germany's heavy logistics corridors.
Bioethanol retains volume leadership; renewable diesel holds the steepest expansion curve.
Feedstock:
Margin compression concentrates among first-generation agricultural processors, while waste-stream collectors capture regulatory premiums.
- Waste Oils:Used cooking oils and animal fats command ISCC-EU certification premiums, insulating processors from soybean price volatility. Neste's Singapore facility and Diamond Green Diesel's Louisiana plant anchor global waste-oil refining capacity.
- Corn:Starch fermentation yields ethanol for E10-E15 blending in US gasoline pools. POET and Green Plains operate dry-mill capacity across Iowa and Nebraska, locked into RFS volume obligations.
- Sugarcane:Brazilian mills redirect juice toward hydrous ethanol when sugar prices weaken, supplying flex-fuel vehicle demand under RenovaBio credit mechanisms.
- Soybean:Oil extraction for biodiesel competes with food and oleochemical demand, exposing crushers to Chicago Board of Trade price swings.
Corn retains volume leadership; waste oils hold the steepest expansion curve.
End User:
Carbon accounting requirements fragment procurement patterns across vehicle weight classes and duty cycles.
- Heavy Duty Trucks:Long-haul operators in Germany and California specify mass-balance-certified renewable diesel for scope-3 reporting compliance. Daimler Truck and Volvo Group fleet contracts embed quarterly carbon intensity scorecards.
- Passenger Vehicles:Flex-fuel vehicle sales concentrate in Brazil and US Midwest states with E15 retail infrastructure. OEM powertrain strategies increasingly marginalize ethanol-optimized engines.
- Light Commercial Vehicles:Urban delivery fleets in London and Amsterdam trial biomethane for dual-fuel van platforms.
- Motorcycles:Two-wheeler ethanol blending in India reaches E20 under BIS mandates, with sugarcane distillers supplying dedicated fuel ethanol.
Heavy duty trucks retain volume leadership; light commercial vehicles hold the steepest expansion curve.
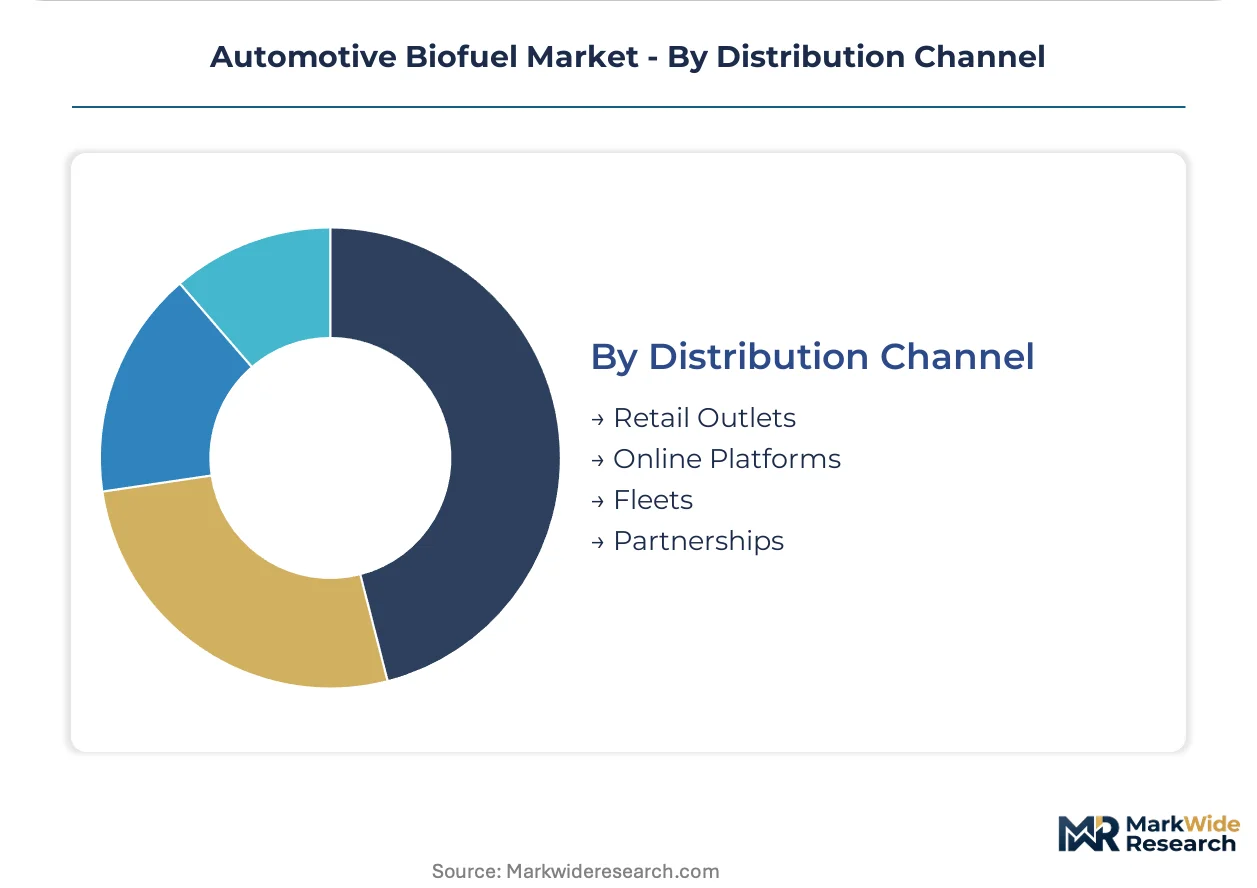
Distribution Channel:
Contract structures diverge between spot-market retail and long-term fleet procurement with embedded carbon verification.
- Fleets:Direct supply agreements with integrated carbon accounting dominate German and California heavy-duty markets. Shell and BP anchor renewable diesel offtake through multi-year tenders with lifecycle analysis requirements.
- Retail Outlets:Blender pumps at US truck stops and Brazilian service stations serve fragmented owner-operator demand with price-sensitive spot purchasing.
- Partnerships:Oil majors partner with agricultural processors for backward integration into feedstock supply, as Valero does with Diamond Green Diesel.
- Online Platforms:Digital carbon credit exchanges emerge for compliance certificate trading, though physical fuel delivery remains infrastructure-bound.
Retail outlets retain volume leadership; fleets hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity clusters in Finland, Singapore, and the US Gulf Coast, creating geographic supply risk for inland European and North American markets. This concentration forces fleet operators to secure long-term offtake agreements rather than rely on spot procurement. Capital flows toward waste-to-fuel infrastructure in Brazil, India, and Germany under national low-carbon fuel standards.
United States
Heavy-duty truck fleets across California and the Midwest expand renewable diesel procurement under EPA Renewable Fuel Standard obligations. The EPA administers nested D5 RIN categories that redirect capital toward cellulosic and biomass-based diesel pathways. POET operates dry-mill ethanol capacity across Iowa and Nebraska, locked into RFS volume commitments.
Brazil
Mills redirect sugarcane juice toward hydrous ethanol when sugar prices weaken, supplying flex-fuel vehicle demand. RenovaBio credit mechanisms reward carbon-negative feedstocks, creating first-mover advantage for waste-to-fuel processors. São Paulo state anchors processing infrastructure for the domestic ethanol blending program.
Germany
Daimler Truck and Volvo Group fleet contracts embed quarterly carbon intensity scorecards for scope-3 reporting compliance. The EU Green Deal and F-Gas Regulation tighten carbon intensity thresholds for transportation fuels sold across member states. Hamburg and the Ruhr region concentrate biorefinery capacity serving Nordic heavy-duty operators.
India
Sugarcane distillers supply dedicated fuel ethanol for two-wheeler blending reaching E20 under BIS mandates. The PLI scheme redirects sugarcane processing capacity toward fuel output, creating dedicated offtake for domestic distillers. Maharashtra and Uttar Pradesh anchor ethanol production infrastructure for the national blending program.
Finland
Neste Corporation leverages proprietary refining technology to dominate renewable diesel output for cold-climate Nordic markets. Finnish refiners supply heavy-duty fleets that reject conventional biodiesel for winter operability. The Porvoo refining cluster anchors European hydrotreated renewable diesel capacity.
Automotive Biofuel Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the automotive biofuel supply base. Hydrotreating expertise concentrates margin capture with specialized refiners while agricultural processors defend position through backward integration into feedstock supply. Three archetypes dominate: integrated oil majors with biorefinery assets, dedicated renewable fuel specialists with proprietary refining technology, and agribusiness conglomerates with captive starch and oilseed supply. Competitive moves center on waste-oil feedstock aggregation and multi-year fleet procurement contracts with embedded carbon accounting.
Among integrated energy conglomerates, BP and Shell anchor renewable diesel offtake through multi-year tenders with lifecycle analysis requirements. Neste Corporation exemplifies the technology-specialist archetype with concentrated hydrotreating capacity in Northern Europe and Singapore. POET LLC occupies a position within the agricultural-processor tier, securing RFS-compliant ethanol supply through Midwest corn sourcing.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Neste Corporation |
| Valero Energy Corporation |
| Cargill |
| POET LLC |
| Renewable Energy Group |
| Bunge Limited |
| BP |
| Shell |
| Others |
Value Chain & Pricing Dynamics
Waste-oil feedstock substitution for virgin oilseeds simultaneously concentrates refining capacity in coastal Singapore and Finland while compressing margins for inland agricultural processors dependent on volatile commodity inputs. This dual restructuring forces fleet operators to secure multi-year offtake agreements rather than rely on spot procurement, embedding carbon intensity premiums into contract structures.
Pricing Analysis
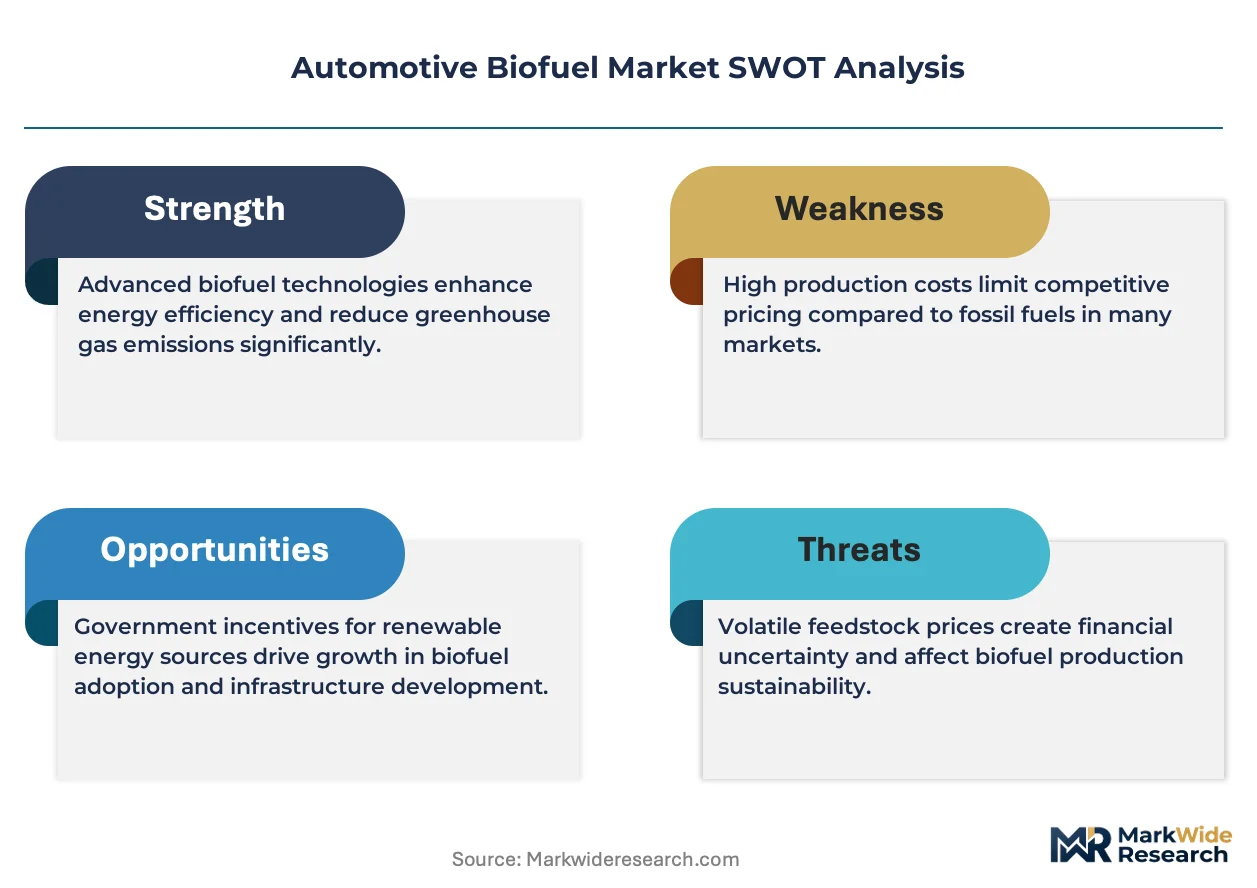
The EU Green Deal and F-Gas Regulation dictate the pricing tier structure across automotive biofuel markets, separating ISCC-EU certified waste-oil products from conventional agricultural feedstocks through carbon intensity scoring. Three-tier pricing stratifies across premium certified waste streams, standard agricultural ethanol, and economy biodiesel from unverified sources. Cost compression in first-generation biodiesel intensifies as renewable diesel captures cold-climate fleet demand, leaving spot-market purchasers most price-sensitive while scope-3-conscious corporate operators absorb premiums for verified supply.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock flows to Singapore's renewable diesel cluster, creating chokepoint exposure for European and North American inland markets. Supply concentrates in Finland, Singapore, and the US Gulf Coast, with hydrogen consumption and waste-oil aggregation determining refinery economics. The chain draws from used cooking oils, animal fats, and agricultural residues, with single-source vulnerability in hydrotreating catalyst supply. Distribution runs through integrated biorefinery networks rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive biofuel incumbents face substitution defense against battery-electric heavy-duty platforms and hydrogen fuel cell corridors. Electrification of urban delivery segments threatens ethanol demand, while long-haul electrification timelines preserve renewable diesel relevance.
For Market Incumbents: Consolidate waste-oil feedstock aggregation capacity in Brazil and India before RenovaBio and PLI scheme incentives attract competing processors. Secure backward integration into used cooking oil collection networks to hedge against soybean price volatility. Prioritize hydrotreater retrofit investments over transesterification capacity maintenance as cloud-point specifications harden in Nordic procurement contracts. For New Entrants and Emerging Players: Anchor in India's E20 ethanol blending infrastructure gap, where sugarcane distillers lack sufficient capacity to meet BIS mandates. Target biomethane upgrading for German urban delivery fleets seeking dual-fuel van platforms. Pursue digital carbon accounting partnerships with fleet operators requiring blockchain-tracked mass-balance certification for scope-3 reporting compliance. For Investors and Strategic Acquirers: The market sits at a technology rotation phase that favors hydrotreating specialists with waste-oil supply contracts over first-generation agricultural processors. Long-term viability hinges on refinery margin capture surviving the electrification window for heavy transport. Watch renewable diesel capacity utilization rates in Singapore and Rotterdam as the inflection signal for feedstock competition intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Waste-Oil Feedstock Aggregation | ISCC-EU certification premiums protect margins against agricultural commodity volatility for processors. |
| Hydrotreater Capacity Expansion | Neste's Singapore facility demonstrates margin capture from cold-climate renewable diesel specifications. |
| Digital Carbon Accounting Platform | Blockchain-tracked supply chains command premium pricing from scope-3-conscious corporate fleet operators. |
| Backward Integration Partnership | Valero's Diamond Green Diesel joint venture secures captive feedstock for US Gulf Coast refining. |
| Multi-Year Fleet Procurement Contract | Shell and BP anchor offtake through tenders embedding lifecycle analysis requirements for German operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA RIN transaction databases, EU ETS fuel quality reports, and customs trade flows for waste-oil feedstocks. The approach combines interviews with biorefinery operations managers, fleet procurement directors at Daimler Truck and Volvo Group, sugarcane mill executives in São Paulo state, and renewable fuel traders at integrated oil majors. Secondary validation draws from ISCC certification registries, California LCFS credit clearing data, and national low-carbon fuel standard implementation documents across Brazil, India, and Germany. Bottom-up capacity modeling triangulates against top-down regulatory obligation calculations.
Segmentation dimensions modeled include fuel chemistry type, feedstock origin, vehicle weight class, and distribution channel structure across the projection horizon. The analytical framework incorporates technology substitution curves for electrification penetration in light versus heavy-duty segments, regulatory credit price volatility scenarios, and carbon intensity scorecard adoption rates among corporate fleet operators. CAGRs derive from capacity buildout pipelines, policy mandate trajectories, and feedstock availability constraints.
Decision-makers should treat outputs as directional under assumptions of sustained low-carbon fuel standard enforcement and heavy-duty electrification timelines; material deviation in battery-economic parity or hydrogen corridor deployment would warrant model refresh. Revision becomes warranted when renewable diesel capacity utilization in Singapore and Rotterdam crosses threshold shifts indicating feedstock competition saturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market