
 Global Automotive Anti Pinch Window Market | 2026-2036
Global Automotive Anti Pinch Window Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Anti Pinch Window Market Intelligence
The United Nations ECE Regulation No. 21, governing interior fittings and passenger protection, is broadening the baseline requirement for anti-pinch systems beyond luxury vehicles. Robert Bosch GmbH leverages its expertise in sensor technology to offer integrated solutions for global automakers. Continental AG competes through its advanced electronic control units and system integration capabilities. DENSO Corporation sustains a strong market position with its focus on manufacturing scale and OEM relationships in Japan and North America.
Automotive anti-pinch window systems are active safety features designed to prevent injury from electrically powered closures. The system utilizes resistive or capacitive sensors to detect an obstruction and immediately reverse the motor's direction. Demand from the SUV vehicle type segment leads the market due to higher feature content and larger window apertures. Within technology segments, capacitive technology is displacing older resistive sensor designs due to superior sensitivity and reliability.
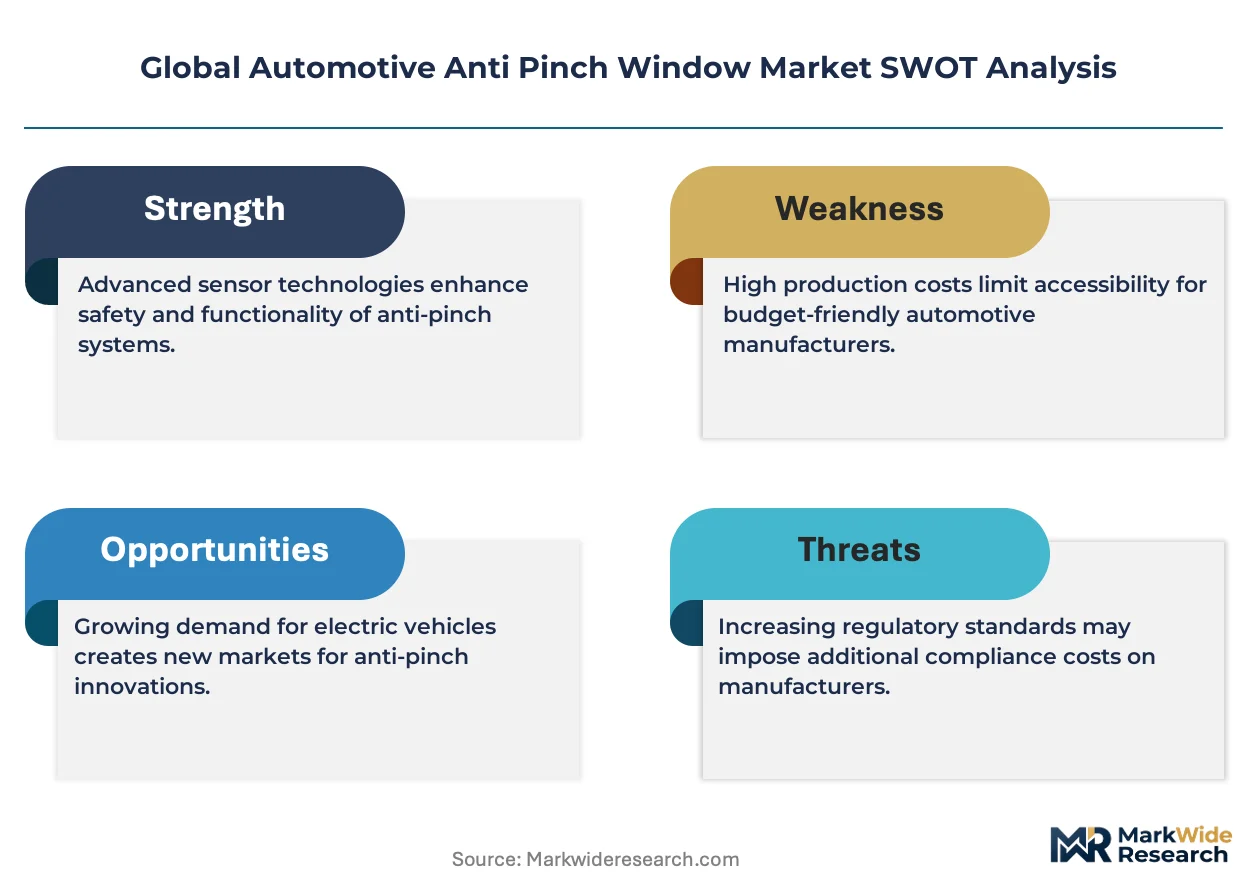
Mandates from bodies like the U.S. NHTSA under its FMVSS standards and China's GB 11552 directly drive OEM adoption. These regulations establish minimum performance criteria for obstruction detection, making anti-pinch a standard safety requirement. Future differentiation for suppliers will depend on integrating these systems with broader vehicle domain controllers and advanced driver-assistance systems.
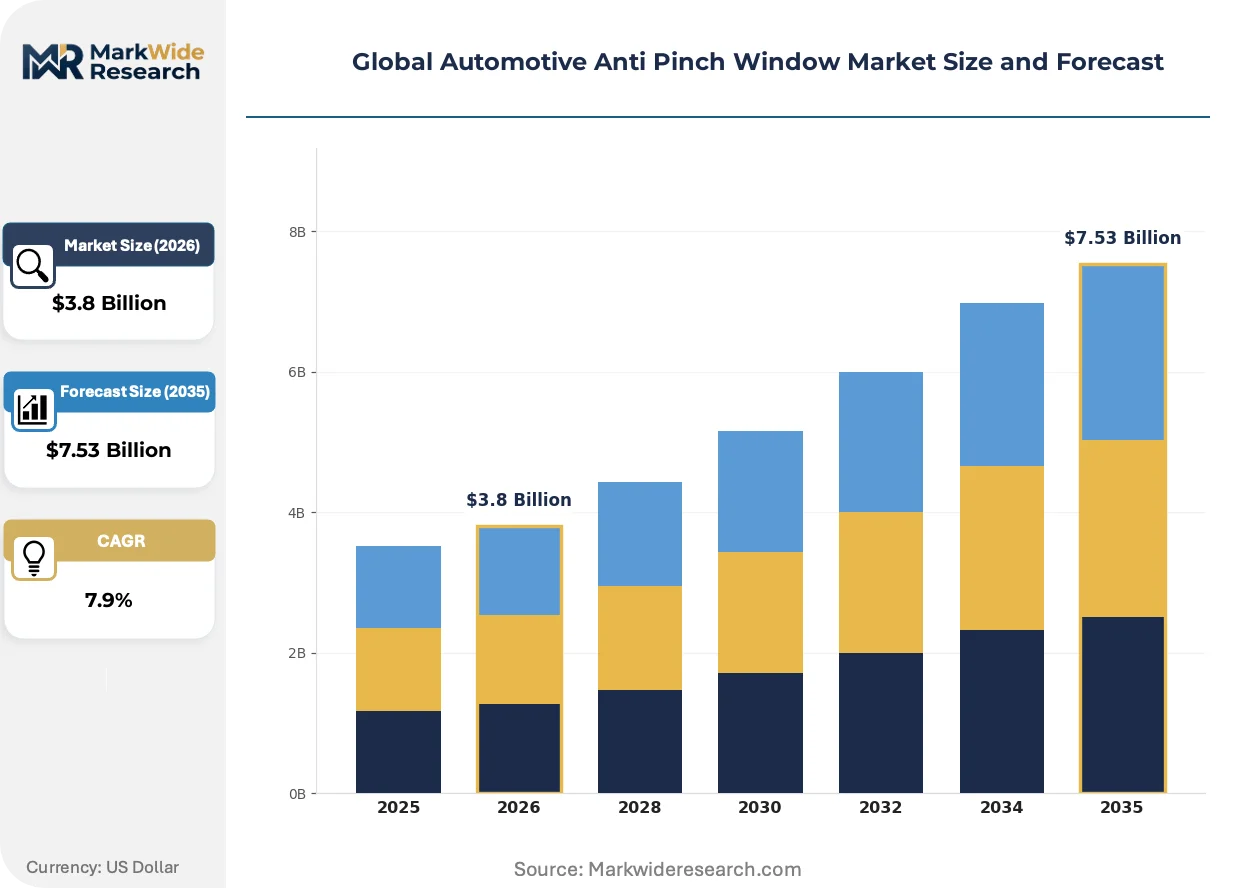
Market Dynamics
The expansion of automotive anti-pinch systems from a luxury add-on to a standard safety feature is the market's central dynamic. This transition is propelled by a global cascade of safety regulations, such as China's GB 11552, which mandate minimum performance standards for all vehicle classes.
Growth Catalysts
- Regulatory Harmonization:The United Nations ECE Regulation No. 21 is creating a baseline safety standard, compelling automakers to install anti-pinch systems in vehicles sold across multiple jurisdictions, not just in premium models.
- Advanced Sensor Technology:The shift to capacitive sensors from older resistive designs improves detection sensitivity and reliability, reducing false positives and enhancing user safety, which encourages OEM adoption.
- SUV Segment Proliferation:Strong consumer preference for SUVs, which typically feature larger window apertures and higher overall feature content, creates a significant volume driver for anti-pinch system integration.
Market Restraints
- Cost Pressure in Economy Segments:The additional bill-of-materials and integration cost for anti-pinch systems poses a significant barrier in the highly price-sensitive economy and sub-compact vehicle segments.
- Electrical Architecture Complexity:Integrating sensor inputs and motor control with diverse and often proprietary vehicle electrical architectures presents a technical hurdle, increasing development time and validation costs for suppliers.
- Semiconductor Dependencies:The systems rely on specific microcontrollers and sensor components, making the supply chain vulnerable to shortages and price volatility within the broader semiconductor industry.
Strategic Opportunities
- System Integration with ADAS:There is a clear opportunity to integrate anti-pinch sensor data with advanced driver-assistance systems and body domain controllers to enable more sophisticated, context-aware safety protocols.
- Commercial Vehicle Adoption:The light and heavy commercial vehicle segments remain underpenetrated, offering a new frontier for growth as fleet operators and regulators focus more on driver and occupant safety.
- Aftermarket Retrofit Solutions:Developing advanced, easy-to-install aftermarket kits for older vehicles or for models in markets without strict mandates provides an alternative revenue channel beyond direct OEM sales.
Industry Challenges
- Calibration and Environmental Factors:A persistent operational challenge is perfecting sensor calibration to reliably detect obstructions while filtering out environmental noise like rain, ice, or dirt that can cause false reversals.
- Software Validation Complexity:The increasing complexity of the embedded software that governs the system's logic requires extensive testing and validation to ensure failsafe operation under all conditions, straining engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Anti Pinch Window Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Windows, Manual Windows, Sunroofs, Specialty Windows Installation Type: OEM Installation, Aftermarket Installation, Retrofitting, Custom Installation Vehicle Type: Sedans, SUVs, Hatchbacks, Trucks Technology: Resistive Technology, Capacitive Technology, Optical Sensors, Mechanical Sensors |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, AISIN SEIKI Co., Ltd., Brose Fahrzeugteile GmbH & Co. KG, Inteva Products LLC, Johnson Electric, Magna International Inc., NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Anti Pinch Window Market Strategic Shifts & Innovations
The evolution of anti-pinch systems reflects a broader shift within automotive electronics from isolated, single-function safety devices to interconnected components within a vehicle's centralized digital nervous system. This integration is driven by advancements in sensor fidelity and processing power.
Capacitive sensing technology detects obstructions by monitoring changes in a localized electric field around the window frame. Automakers are adopting this technology at an accelerated pace across mid-range vehicle platforms, moving it beyond its initial application in the luxury segment. The core technology is expanding into other powered closures, including sunroofs, sliding doors, and liftgates, to create a holistic vehicle safety envelope.
Mandates from regulatory bodies like the U.S. National Highway Traffic Safety Administration (NHTSA) are solidifying the market's foundation. The Federal Motor Vehicle Safety Standards (FMVSS) establish clear performance criteria for obstruction detection, effectively making anti-pinch a non-negotiable feature for vehicles sold in the United States. This regulatory floor primarily impacts all passenger vehicle segments, forcing universal compliance and removing the feature from the optional-extra list.
Consumer expectations are shifting, with buyers increasingly viewing active safety features as a standard package rather than as individual a la carte options. This change disrupts traditional feature-bundling strategies tied to vehicle trim levels, compelling automakers to standardize systems to achieve high marks from safety rating agencies. This demand-side pressure is most pronounced in Europe and North America, where Euro NCAP and IIHS ratings strongly influence purchasing decisions.
Global Automotive Anti Pinch Window Market Segmentation
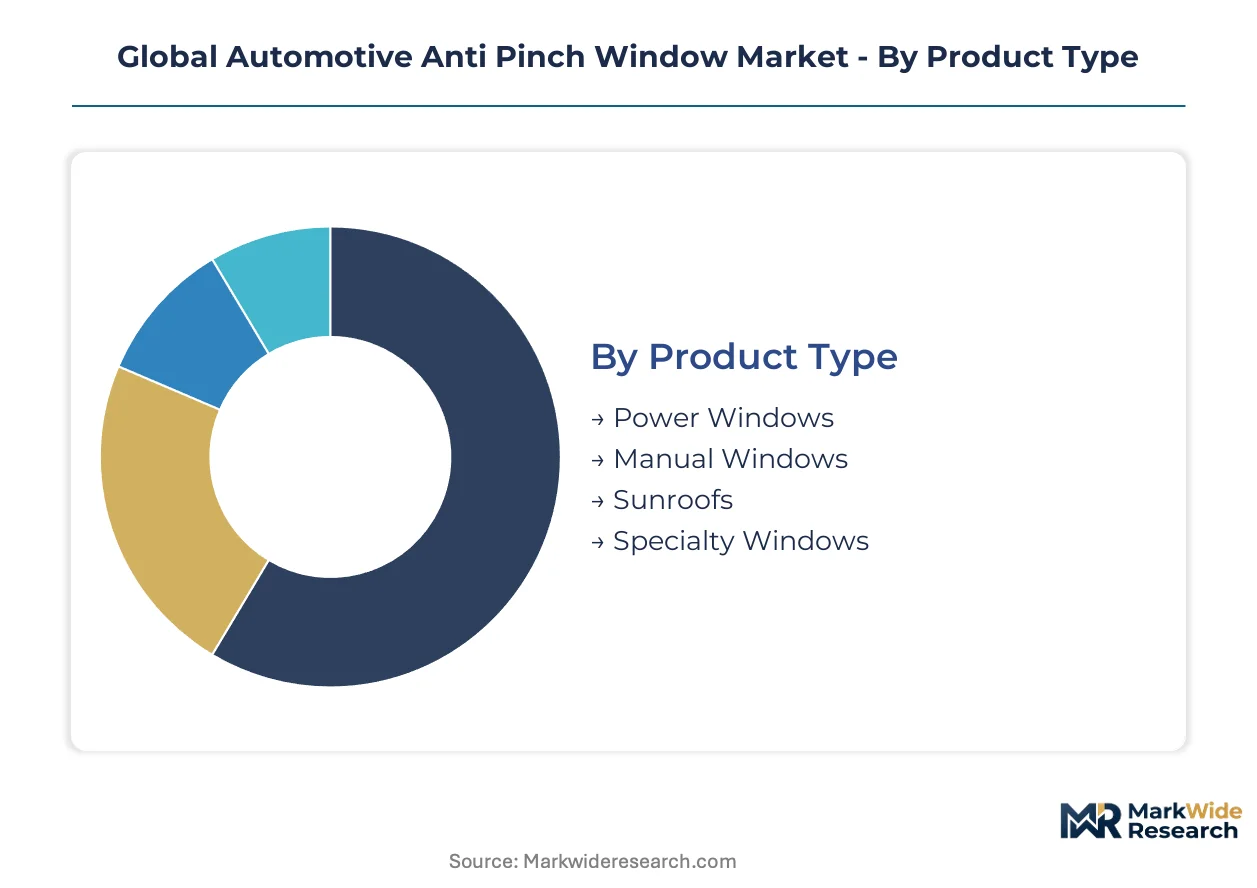
The automotive anti-pinch window market exhibits distinct segmentation across key attributes, influencing product development and market penetration strategies. Understanding these divisions helps stakeholders identify areas of high demand, technological evolution, and regulatory impact, guiding investment and competitive positioning within the global landscape.
Product Type:
The functionality of anti-pinch systems is primarily defined by the specific closure type they protect, each presenting unique engineering challenges and safety requirements.
- Power Windows:These electrically operated windows are the most common application for anti-pinch systems, requiring precise motor control and sensor integration. Demand concentrates in all passenger vehicle segments, driven by universal safety mandates from bodies like the U.S. NHTSA.
- Sunroofs:Large, complex powered glass panels demand sophisticated anti-pinch solutions due to their size and potential for injury. The luxury and premium SUV segments in Europe and China are driving adoption of advanced sunroof safety systems.
- Manual Windows:These mechanically operated windows typically do not feature anti-pinch technology, as the risk of injury from manual operation is significantly lower.
- Specialty Windows:This category includes bespoke window applications in niche vehicles or specific vehicle zones, often requiring custom sensor configurations.
Mature deployment sits with Power Windows. Newer deployment is concentrated in Sunroofs.
Installation Type:
The market's supply chain dynamics are shaped by how anti-pinch systems are integrated into vehicles, spanning initial manufacturing to post-sale modifications.
- OEM Installation:These systems are factory-fitted during vehicle production, ensuring seamless integration and compliance with initial safety standards. This segment represents the largest volume, particularly in regions with stringent regulations like China.
- Aftermarket Installation:Systems installed post-purchase by dealerships or independent workshops cater to vehicles without factory-fitted anti-pinch features. This segment provides flexibility for consumers in markets with less strict mandates.
- Retrofitting:The process of upgrading existing vehicles with anti-pinch systems, often driven by consumer safety concerns or evolving local regulations. This typically involves more complex integration challenges compared to OEM solutions.
- Custom Installation:Tailored solutions for specialized vehicles or unique applications, often involving low-volume production and specific engineering requirements.
OEM integration drives the largest volume, while aftermarket solutions represent the fastest-growing trajectory for consumer choice.
Vehicle Type:
Anti-pinch system features and penetration rates vary significantly across different vehicle categories, reflecting design priorities and consumer expectations.
- SUVs:These vehicles often feature larger window apertures and higher trim levels, leading to a greater demand for advanced anti-pinch systems. The strong consumer preference for SUVs in North America and Europe directly translates to increased system integration.
- Sedans:A high-volume segment globally, sedans represent a significant base for anti-pinch system standardization due to widespread adoption and regulatory pressure. China's domestic vehicle production significantly contributes to sedan anti-pinch demand.
- Hatchbacks:Compact and economy-focused, hatchbacks are increasingly incorporating anti-pinch features as safety mandates expand beyond premium segments.
- Trucks:Light and heavy commercial trucks represent an underpenetrated segment, offering future growth opportunities as fleet safety standards evolve.
SUV and truck segments exhibit the highest feature content, while hatchbacks offer a significant volume base for standardization.
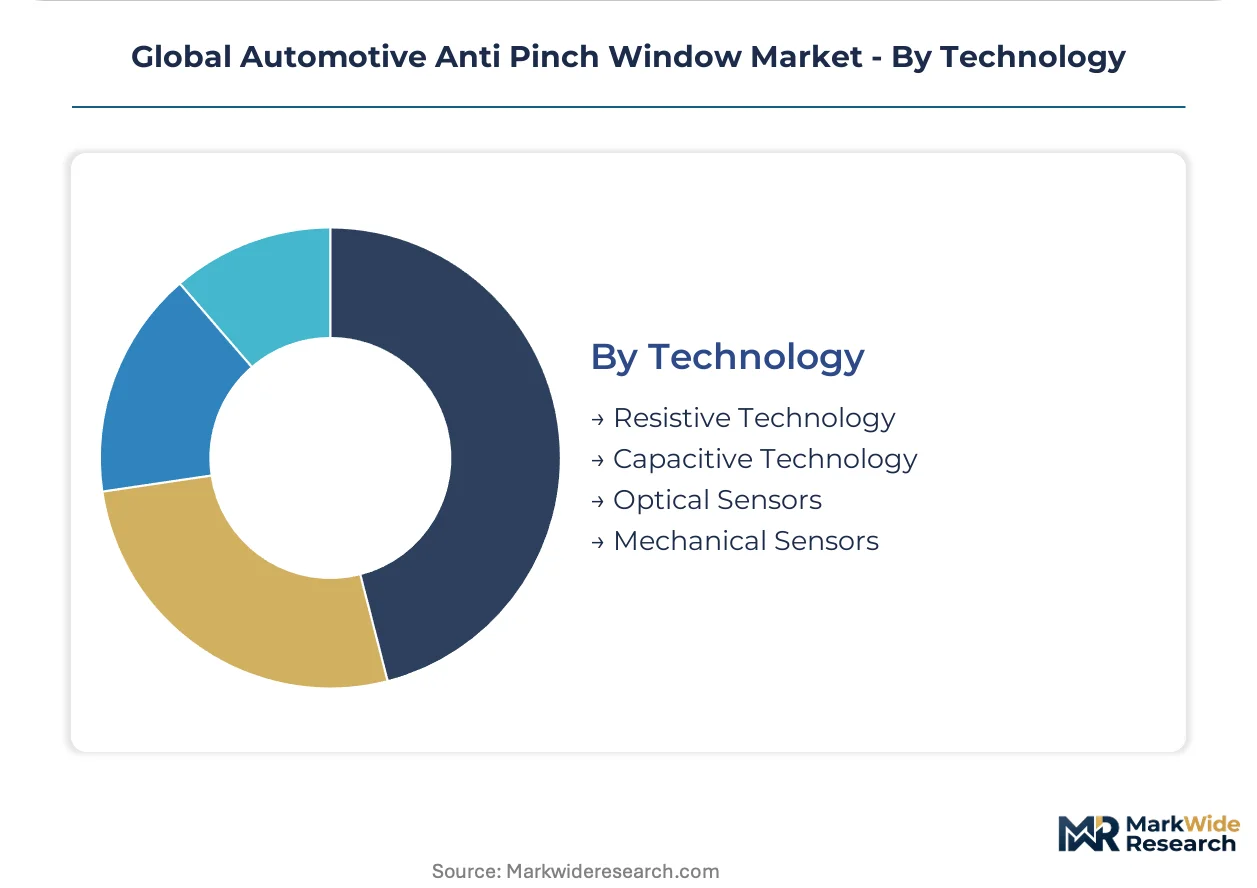
Technology:
The choice of sensor technology directly impacts the responsiveness, reliability, and cost-effectiveness of anti-pinch systems, driving innovation and competitive differentiation.
- Capacitive Technology:This advanced sensor type detects obstructions by monitoring changes in an electric field, offering superior sensitivity and reliability over older designs. Robert Bosch GmbH leverages this technology for its integrated solutions across global automakers.
- Resistive Technology:Older systems use resistive sensors that detect pressure or contact, which can be less sensitive and prone to false positives compared to capacitive solutions. This technology still holds a significant installed base in legacy vehicle platforms.
- Optical Sensors:These sensors use light to detect obstructions, offering precise detection capabilities but often at a higher cost and with potential susceptibility to environmental factors.
- Mechanical Sensors:Basic mechanical switches or pressure-sensitive strips are used in simpler systems, primarily for basic obstruction detection rather than advanced anti-pinch functionality.
Capacitive sensors are rapidly gaining share, displacing older resistive designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for automotive anti-pinch window systems is notable in China, driven by its large domestic vehicle production and tightening safety standards. Global regulatory convergence, such as the United Nations ECE Regulation No. 21, is expanding the baseline requirement for these systems beyond premium vehicle segments. This widespread adoption is influencing market dynamics across major automotive manufacturing regions.
China
China's automotive market exhibits significant demand for anti-pinch systems due to its vast domestic vehicle production and a growing consumer emphasis on safety features. The nation's GB 11552 standard directly mandates minimum performance criteria for obstruction detection. Manufacturing hubs in the Yangtze River Delta actively integrate these systems into high-volume passenger vehicles.
United States
The United States market experiences strong demand from the SUV segment, which typically features larger window apertures and higher feature content. The U.S. NHTSA, through its FMVSS standards, establishes clear performance criteria for anti-pinch systems. Automotive suppliers in Detroit and surrounding Michigan areas focus on integrating advanced capacitive technologies into new vehicle platforms.
Germany
Germany drives demand through its robust premium vehicle segment and stringent safety regulations. The United Nations ECE Regulation No. 21 significantly influences design and implementation across European vehicle models. Major automotive technology centers in Bavaria, home to companies like Robert Bosch GmbH and Continental AG, lead in developing integrated anti-pinch solutions.
Japan
Japan's market is characterized by strong OEM relationships and a focus on manufacturing scale for anti-pinch systems. The country's vehicle safety standards, including JIS, contribute to the baseline adoption of these features. Automotive manufacturing clusters in Aichi Prefecture, including suppliers like DENSO Corporation, are central to system production and innovation.
India
India's rapidly expanding automotive market is seeing increased adoption of anti-pinch systems, propelled by rising consumer safety awareness and evolving regulatory frameworks. The Bureau of Indian Standards (BIS) plays a role in establishing quality and safety norms for automotive components. Major automotive production corridors, such as the Chennai automotive belt, are integrating these systems into economy and mid-range vehicles.
Global Automotive Anti Pinch Window Market Key Industry Players
European producers anchor one tier, emphasizing advanced technology and system integration; Asian specialists hold another, focusing on manufacturing scale and OEM relationships. The market exhibits a tiered structure, with global Tier 1 suppliers dominating the integrated solutions segment. Specialized sensor technology developers and regional OEM-focused suppliers also occupy specific niches. Strategic partnerships for system integration with broader vehicle domain controllers and continuous investment in advanced sensor technology characterize competitive moves.
Within the integrated solutions tier, Robert Bosch GmbH and Continental AG exemplify German engineering expertise. Robert Bosch GmbH, a German-based company, represents comprehensive sensor technology and system integration capabilities. Continental AG, also a German entity, holds a strong position with electronic control units and system integration capabilities. DENSO Corporation, a Japanese-headquartered manufacturer, anchors the market through its manufacturing scale and strong OEM relationships in Asian and North American markets.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| AISIN SEIKI Co., Ltd. |
| Brose Fahrzeugteile GmbH & Co. KG |
| Inteva Products LLC |
| Johnson Electric |
| Magna International Inc. |
| NXP Semiconductors N.V. |
| Others |
Cost & Logistics Intelligence
Vertical integration of sensor technology by Tier 1 suppliers anchors their supply position, granting significant pricing power for advanced anti-pinch systems. This strategy ensures seamless integration into complex vehicle architectures.
Pricing Analysis
Volume-driven pricing dominates the economy and mid-range segments, while premium anti-pinch systems command higher margins. Premium-mid-economy pricing differentiation reflects sensor technology (capacitive vs. resistive) and certification levels (e.g., U.S. NHTSA, UN ECE R21). Pricing softness runs through economy vehicle segments due to additional bill-of-materials and integration costs. Luxury vehicle manufacturers exhibit lower price sensitivity for advanced safety features.
Supply Chain Analysis
Microcontroller supply for anti-pinch systems primarily rests on East Asian semiconductor manufacturers, particularly in Taiwan and South Korea. Key component dependencies include specialized microcontrollers and capacitive sensor elements. The supply chain faces structural risk from semiconductor price volatility and potential shortages. Distribution runs through direct OEM supply channels, with Tier 1 suppliers integrating components into finished modules for automakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive anti-pinch market is consolidating, driven by the increasing complexity of integrating advanced safety systems into diverse vehicle platforms. This pressure forces out smaller players lacking scale or deep OEM integration.
For Market Incumbents: To counter rising software validation complexity, incumbents must deepen integration with broader vehicle domain controllers and ADAS. Invest in advanced capacitive sensor R&D to maintain a technological edge and reduce false positives. Strengthen OEM relationships through comprehensive system-level support. Expanding manufacturing capacity in strategic regions like China can also mitigate supply chain risks. For New Entrants and Emerging Players: Begin with targeting underpenetrated segments like light and heavy commercial vehicles, which present significant growth opportunities. Develop cost-effective, easy-to-install aftermarket retrofit solutions for older vehicle models or regions with less strict mandates. Focus on specialized sensor configurations for niche vehicle zones or unique applications. Partnering with regional distributors can provide a rapid market entry point. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized sensor technology developers or regional OEM-focused suppliers with proprietary intellectual property. This market offers strong long-term viability over the next decade, driven by expanding safety mandates. Identify targets demonstrating robust software validation capabilities. A key signal to watch is the acquisition of smaller, innovative sensor firms by established Tier 1 automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Integration | Enables seamless anti-pinch system control within advanced vehicle architectures, enhancing overall safety features. |
| Capacitive Sensor R&D Investment | Improves detection sensitivity and reliability, reducing false positives for automotive anti-pinch systems. |
| Commercial Vehicle Market Entry | Unlocks new revenue streams by addressing underpenetrated light and heavy commercial vehicle segments globally. |
| Aftermarket Solution Development | Provides alternative revenue channels and expands market reach for anti-pinch systems in older vehicles. |
| Global Regulatory Compliance Expansion | Ensures anti-pinch system market access and adoption across diverse international automotive safety standards. |
Research Approach
Multi-period observation of vehicle production volumes, regulatory adoption rates, and technology penetration anchored the trend analysis, supplemented by interviews. Primary research involved discussions with automotive OEM engineers, Tier 1 supplier product managers, regulatory affairs specialists, and aftermarket distributors. Secondary validation drew from U.S. NHTSA reports, UN ECE regulations, China GB standards, and industry association publications. This approach utilized both bottom-up market sizing and top-down validation.
Segment-weighting across vehicle type, technology, product type, installation type, and regional regulatory frameworks formed the core analytical framework. Compound Annual Growth Rates were derived from historical data trends and projected future adoption rates across the analysis window. Key industry-specific forecast inputs included semiconductor availability and the evolving landscape of global safety mandates. The model incorporated anticipated shifts in consumer preferences for active safety features.
Underlying measurement precision varies by segment; OEM installation and SUV vehicle types carry tighter precision than aftermarket solutions. Forecasts reflect assumptions regarding global economic stability, geopolitical trade tensions, and raw material price volatility. Unexpected regulatory delays could also revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Lane Departure Warning System Market