
 Automotive Intelligent Headlight System Market | 2026-2036
Automotive Intelligent Headlight System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intelligent Headlight System Market Outlook
Aftermarket service revenue is fragmenting as OEMs extend software-defined lighting subscriptions and over-the-air update capabilities. Koito Manufacturing leverages its vertical integration into LED chip packaging to sustain margin control across the value chain. Valeo competes through its dominant position in matrix beam actuators, while Forvia Hella anchors European OEM relationships with glare-free adaptive systems.
An automotive intelligent headlight system integrates sensor fusion, real-time control algorithms, and multi-element LED or laser arrays to dynamically adjust beam pattern, intensity, and direction based on traffic conditions, road geometry, and weather. These systems typically operate at color temperatures between 5,500K and 6,000K and achieve response latencies under 10 milliseconds for oncoming vehicle detection. LED headlights occupy the largest installed base due to cost maturity and thermal efficiency, while matrix beam configurations capture expanding margin pools as software-enabled feature differentiation intensifies. Computer vision technology leads sensor integration for object recognition, though lidar fusion is gaining traction in premium segments for predictive beam shaping.
NHTSA Federal Motor Vehicle Safety Standard 108 governs headlight photometric performance in the United States, while ECE R48 and R123 regulations in Europe mandate adaptive driving beam homologation. Euro NCAP assessment protocols now weight active safety illumination scores, directly steering OEM procurement toward intelligent systems. Stakeholders must monitor divergence between U.S. self-certification and European type-approval pathways, as regulatory asymmetry shapes product development roadmaps and market access timelines.
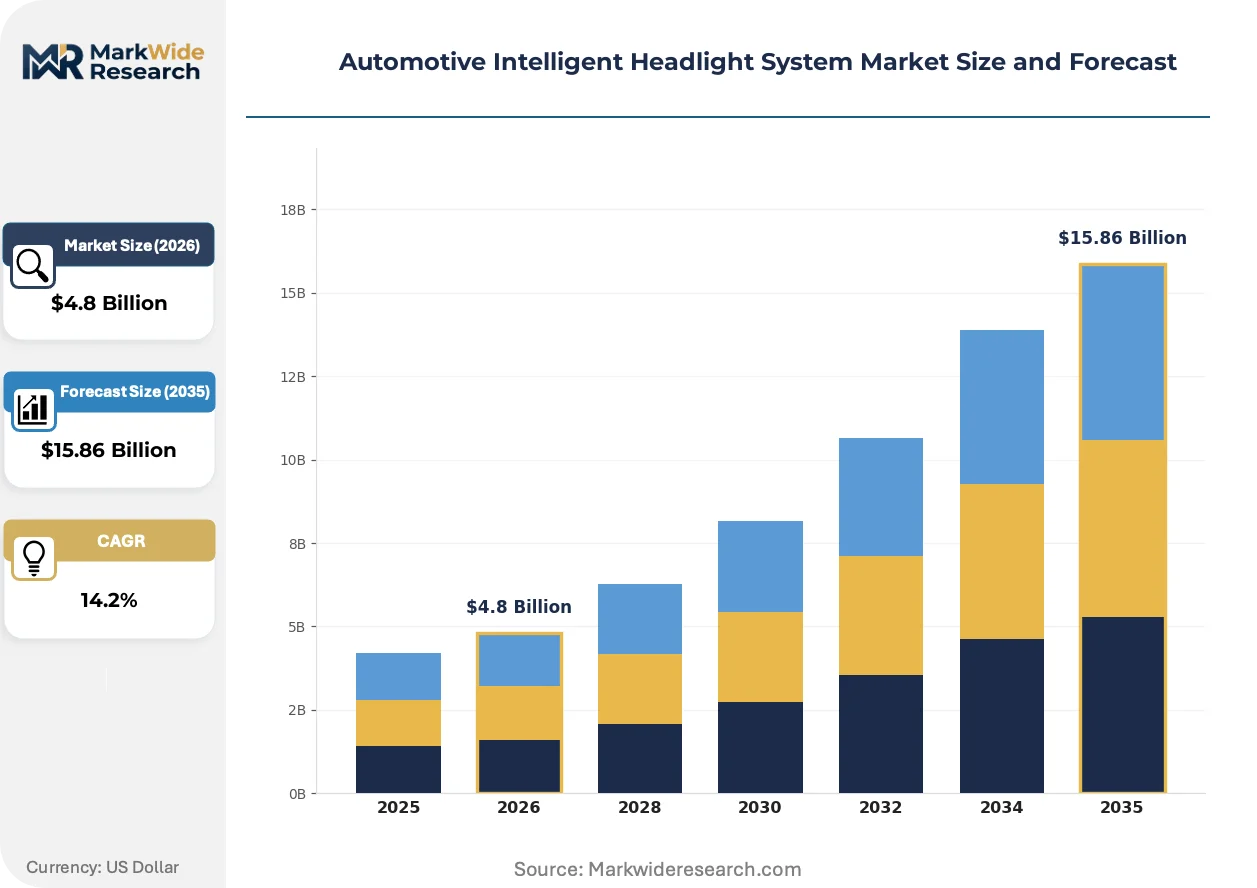
Market Dynamics
Software-defined lighting architectures are compressing hardware replacement cycles while extending OEM monetization through subscription-based feature activation. NHTSA's pending adaptive beam legalization and Euro NCAP's weighted illumination scoring create dual regulatory momentum that favors integrated sensor-fusion platforms over discrete component sourcing.
Growth Catalysts
- Euro NCAP Protocol Weighting:Active safety illumination scores now directly influence five-star ratings, forcing European OEM procurement toward matrix beam systems with predictive glare suppression.
- Sensor Fusion Convergence:Camera-lidar integration enables predictive beam shaping that anticipates curves and elevation changes before driver input reaches steering systems.
- German Production Clustering:Stuttgart and Munich anchor premium vehicle assembly lines where intelligent headlight content penetration exceeds mass-market platforms by structural design.
Market Restraints
- LED Driver IC Concentration:Taiwan and South Korea foundries control advanced automotive LED driver fabrication, exposing supply continuity to geopolitical friction and capacity allocation.
- Homologation Asymmetry:NHTSA self-certification permits market entry without pre-approval testing, yet European type-approval under ECE R48 imposes 18-24 month validation timelines that fragment product roadmaps.
- Thermal Management Cost:Laser array systems require active cooling subsystems using gallium nitride substrates whose pricing volatility tracks rare earth processing capacity in China.
Strategic Opportunities
- India Premiumization:Luxury vehicle assembly expansion in Pune and Chennai creates localized demand for adaptive beam systems previously limited to fully-imported nameplates.
- Over-the-Air Monetization:Software-defined headlight feature subscriptions enable recurring revenue from hardware already installed, transforming capital expenditure into operational expenditure for fleet operators.
- China Dual Carbon Alignment:MIIT energy-efficiency mandates for automotive electronics favor LED and laser architectures over halogen legacy systems in domestic brand lineups.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time control algorithm development requires automotive-functional-safety certification (ISO 26262) that outstrips qualified firmware engineer supply in European and Japanese labor markets.
- Legacy Platform Integration:CAN bus bandwidth limitations in vehicles older than seven years prevent retrofit of intelligent headlight systems without full electrical architecture replacement.
- Patent Thicket Navigation:Matrix beam actuator mechanics and adaptive glare-free algorithms carry dense overlapping IP portfolios from German, Japanese, and Korean assignees, complicating clean-room development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intelligent Headlight System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Headlights, Matrix Beam, Laser Headlights, LED Headlights Technology: Computer Vision, Lidar, Radar, Control Algorithms End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Feature: Automatic Leveling, Glare-Free Light, Cornering Function, Dynamic Light Distribution |
| Companies Covered | Stanley Electric, Hyundai Mobis, Koito Manufacturing, Osram, ZKW Group, Valeo, Marelli, Varroc, Forvia Hella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intelligent Headlight System Market Strategic Shifts
Digital micromirror device projection is replacing mechanical shutter systems for pixel-level beam control, while solid-state lidar cost curves enable predictive illumination that extends beyond camera line-of-sight limitations.
Micro-LED array technology achieves 25,000 individually addressable pixels per headlight module, enabling street-level symbol projection and pedestrian warning graphics. German luxury OEMs are adopting these systems for 2026 model year launches. Discrete LED matrix configurations are rendering obsolete mechanical high-beam assist shutters that physically block portions of the light field.
ECE R123 adaptive driving beam homologation requirements are tightening photometric test protocols for oncoming vehicle detection zones. European type-approval bodies now mandate 100-meter minimum recognition distance under wet-road conditions. Premium segment suppliers are responding with fused camera-radar sensor stacks that extend detection range beyond pure vision systems.
Fleet procurement departments are unbundling headlight system specification from vehicle platform contracts, creating direct supplier relationships that bypass traditional tier-one integrators. Rental and ride-hail operators in California and Texas are specifying intelligent lighting as separate line items in multi-year vehicle supply agreements, compressing decision cycles from platform-development timelines to annual procurement reviews.
Automotive Intelligent Headlight System Market Segmentation
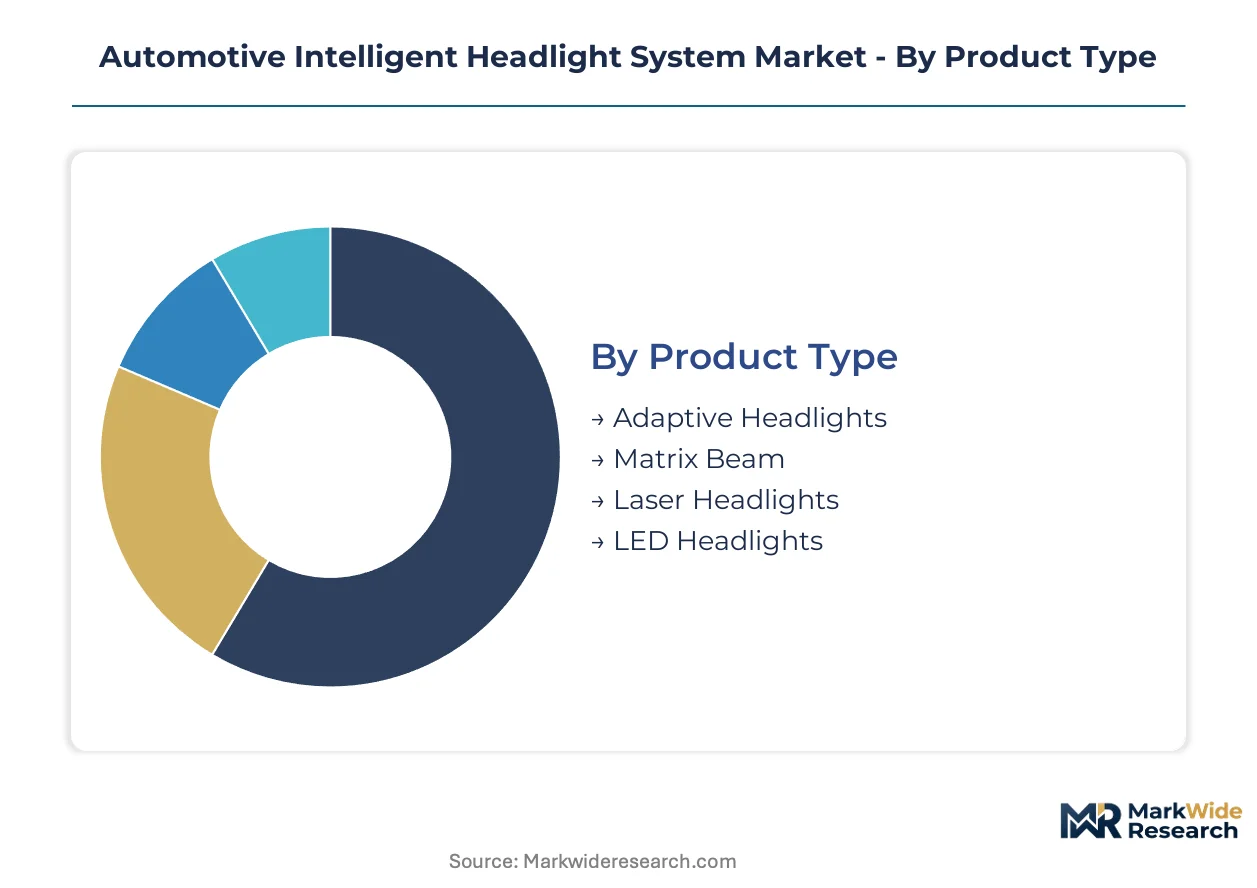
Intelligent headlight procurement varies sharply by product architecture and integration depth. OEMs specify systems differently for premium nameplates versus volume platforms, while technology choices determine sensor fusion complexity and software validation burden.
Product Type:
Cost tier differentiation separates legacy LED retrofits from software-enabled matrix and laser architectures commanding substantial system-level premiums.
- Adaptive Headlights:Motorized swiveling modules adjust beam direction based on steering angle and vehicle speed through electromechanical actuators. German luxury OEMs in Stuttgart and Munich specify these as standard equipment across executive sedans, driven by Euro NCAP illumination scoring requirements.
- Matrix Beam:Multi-element LED arrays enable pixel-level dimming of specific zones without mechanical shutters. Demand concentrates in European premium segments where ECE R123 homologation mandates predictive glare suppression for five-star safety ratings.
- Laser Headlights:Blue laser diodes excite phosphor converters to achieve extended high-beam range exceeding 600 meters. BMW and Audi flagship platforms specify these for autobahn-capable illumination.
- LED Headlights:Solid-state emitters operating at 5,500K-6,000K color temperature dominate mass-market installations through thermal efficiency and packaging flexibility.
LED Headlights command the established base. The steepest expansion runs through Matrix Beam.
Technology:
Application specificity determines sensor modality selection, with vision-centric platforms competing against fused perception stacks for predictive beam shaping.
- Computer Vision:Camera-based object recognition algorithms process traffic scene geometry in real-time for adaptive beam adjustment. Mercedes-Benz S-Class and BMW 7-Series integrate multi-camera arrays for 250-meter forward detection under NHTSA and ECE protocols.
- Lidar:Time-of-flight ranging extends detection beyond camera line-of-sight limitations for predictive curve illumination. Audi and Porsche deploy solid-state lidar in flagship EV architectures where sensor fusion justifies cost premiums.
- Radar:Frequency-modulated continuous-wave sensors provide all-weather object detection complementing optical systems. Continental and Bosch supply 77GHz modules for adaptive driving beam activation.
- Control Algorithms:Real-time decision engines executing ISO 26262-certified functional safety protocols manage multi-sensor fusion latency under 10 milliseconds.
Computer Vision anchors current installations. Lidar is climbing the fastest as solid-state cost curves compress.
End User:
Customer type fragmentation reflects divergent procurement authority across vehicle lifecycle stages and supply chain tiers.
- OEMs:Brand-holding manufacturers specify intelligent headlight content as platform-level design decisions. Volkswagen Group, BMW, and Mercedes-Benz maintain direct supplier relationships with Koito, Valeo, and Forvia Hella for matrix beam integration.
- Tier-1 Suppliers:System integrators manage electromechanical assembly, thermal management, and software validation for OEM customers. Magna and Marelli compete for modular headlight contracts bundling LED drivers with adaptive actuators.
- Vehicle Assemblers:Contract manufacturing partners execute platform builds where lighting specifications derive from OEM engineering directives rather than independent procurement.
- Aftermarket Providers:Independent distributors and installation networks serve vehicle owners outside warranty periods, though software-defined lighting architectures constrain retrofit compatibility.
OEMs retain specification authority. Tier-1 Suppliers are gaining share fastest through modular system integration.
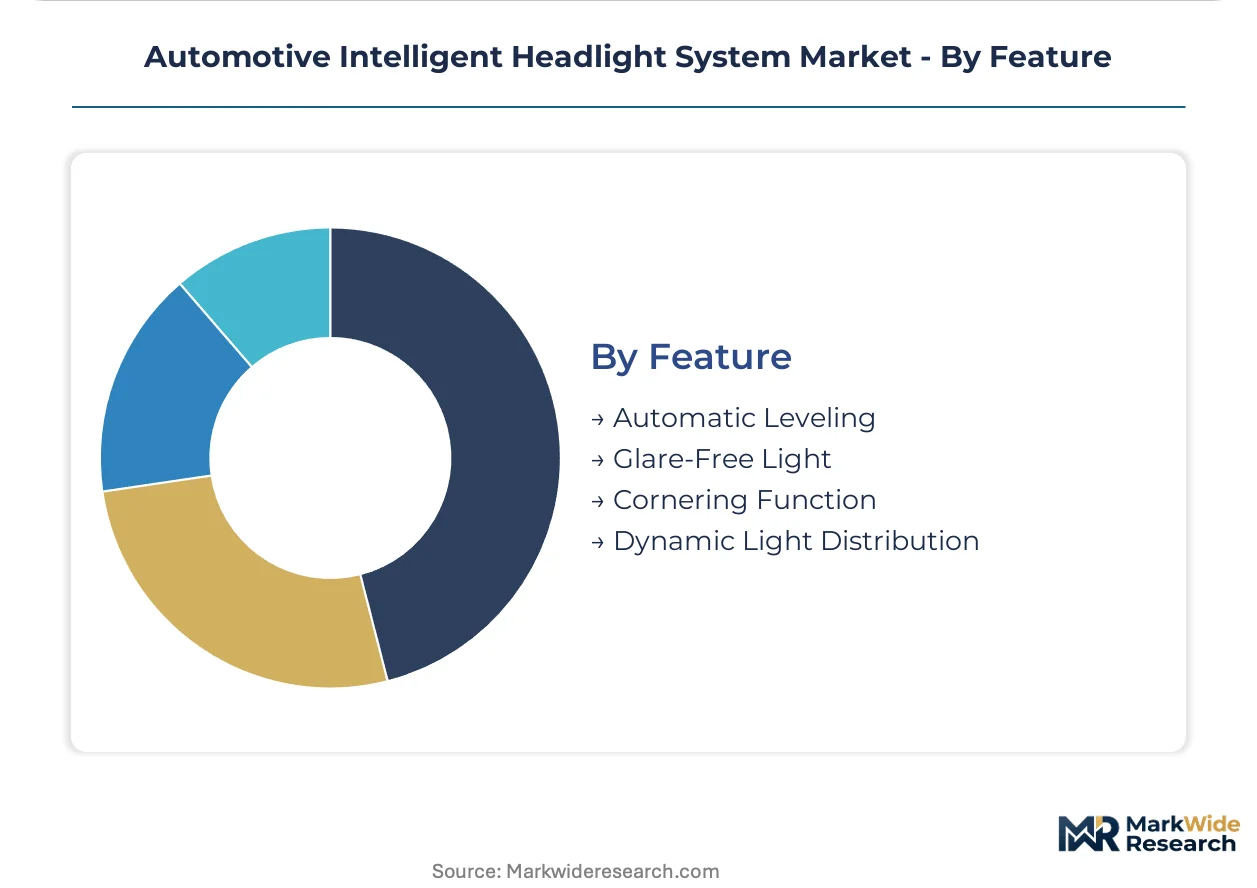
Feature:
Maturity gradients separate established mechanical functions from software-enabled capabilities requiring sensor fusion and over-the-air update infrastructure.
- Glare-Free Light:Predictive masking of oncoming vehicle zones without driver intervention represents the highest-value adaptive beam functionality. Euro NCAP protocols weight this capability heavily in active safety scoring.
- Dynamic Light Distribution:Continuous beam width and intensity adjustment based on traffic density, road type, and weather conditions. Highway versus urban mode switching responds to navigation system inputs.
- Cornering Function:Static or dynamic supplemental illumination of road curvature through dedicated lens elements or beam steering. Entry-level adaptive systems deploy this as primary differentiation.
- Automatic Leveling:Load-compensating vertical adjustment maintains legal beam height during acceleration, braking, and cargo variation. Regulatory mandates in ECE R48 and FMVSS 108 require this as baseline functionality.
Automatic Leveling commands the established base. Glare-Free Light is gaining share fastest through regulatory scoring weight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys intelligent headlight systems as standard equipment across premium nameplates, while the United States treats adaptive beam technology as a compliance-driven upgrade limited by NHTSA regulatory lag. Japan concentrates procurement through keiretsu supplier networks that bundle lighting with broader electronics packages.
Germany
Mercedes-Benz and BMW specify matrix beam systems as baseline equipment for executive sedans and SUVs. ECE R123 homologation mandates predictive glare suppression for type approval. Stuttgart and Munich production clusters anchor European intelligent lighting procurement, with Tier-1 suppliers maintaining captive engineering centers in Baden-Württemberg.
United States
Domestic OEMs limit adaptive beam deployment to luxury nameplates pending NHTSA final rulemaking on glare-free systems. FMVSS 108 self-certification permits faster market entry than European type-approval pathways. Michigan and Ohio assembly plants source intelligent headlights through traditional Tier-1 integrators rather than direct supplier relationships.
Japan
Toyota and Honda bundle intelligent lighting within broader electronics packages through keiretsu supplier networks. METI energy-efficiency guidelines favor LED architectures over legacy halogen systems. Aichi Prefecture production clusters concentrate procurement authority with platform engineering teams rather than standalone lighting specification.
China
Domestic brands accelerate intelligent headlight adoption to meet MIIT energy-efficiency mandates for automotive electronics. MIIT dual carbon alignment policies disadvantage halogen legacy systems in domestic lineup planning. Shanghai and Guangzhou production bases source matrix beam systems from joint-venture suppliers with technology transfer requirements.
South Korea
Hyundai and Kia integrate intelligent lighting as differentiation features in Genesis luxury nameplates and high-trim domestic market vehicles. MFDS automotive electronics guidelines shape validation protocols for LED driver systems. Gyeonggi Province assembly clusters concentrate procurement with captive supplier affiliates.
Automotive Intelligent Headlight System Market Competitive Environment
Capability concentration sits with specialized lighting engineers; scale advantage sits with diversified automotive electronics conglomerates. The vendor base separates into three tiers: integrated headlamp system suppliers with full-stack sensor fusion competence, component specialists dominating LED driver ICs and thermal management subsystems, and modular assemblers competing on cost-engineered platforms. Consolidation pressure runs through backward integration into LED chip packaging and forward integration into software-defined feature monetization.
Among Japanese lighting specialists, Stanley Electric and Koito Manufacturing exemplify the integrated system tier with captive control over optical design and electromechanical assembly. European-headquartered suppliers Valeo and Forvia Hella occupy positions bridging Tier-1 integration depth with OEM direct relationship management. Korean-affiliated Hyundai Mobis represents the diversified electronics conglomerate archetype, leveraging vehicle platform bundling to secure lighting content within broader cockpit electronics packages.
| Leading Market Players |
|---|
| Stanley Electric |
| Hyundai Mobis |
| Koito Manufacturing |
| Osram |
| ZKW Group |
| Valeo |
| Marelli |
| Varroc |
| Forvia Hella |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korea foundries controlling LED driver IC fabrication anchor margin distribution downstream, concentrating pricing power with semiconductor suppliers while OEMs and Tier 1 integrators compete on system-level feature differentiation and software monetization.
Pricing Analysis
Long-term offtake agreements dominate procurement between German and Japanese OEMs and their captive lighting suppliers, insulating premium matrix beam systems from spot-market volatility while aftermarket channels operate on transactional spot purchasing with compressed margins. Price differentiation rests on ISO 26262 functional safety certification tier and software-enabled feature activation depth. Cost compression in mass-market LED retrofits is intensifying because Chinese domestic brands are scaling local supply chains. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement frameworks, while luxury OEMs remain least sensitive given safety-rating compliance requirements.
Supply Chain Analysis
Extended payment terms from German OEMs to Tier 1 integrators cascade through to LED chip packaging subcontractors, creating working capital pressure that favors vertically integrated suppliers with captive financing facilities. Manufacturing concentrates in Germany, Japan, and China, with raw material dependencies spanning gallium nitride substrates, rare earth phosphors, and automotive-grade silicon wafers. Single-source vulnerability in advanced LED driver fabrication exposes continuity to geopolitical friction. Distribution runs through OEM captive channels for original equipment, with independent aftermarket networks handling legacy system replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive intelligent headlight systems represent a high-growth disruption as NHTSA adaptive beam legalization converges with Euro NCAP weighted illumination scoring, creating dual regulatory momentum that favors integrated sensor-fusion platforms over discrete component sourcing.
For Market Incumbents: Entrench position through backward integration into LED chip packaging and captive software-defined lighting subscription infrastructure. Koito Manufacturing's vertical control over optical design and electromechanical assembly demonstrates the defensive value of upstream integration. Threat from solid-state lidar cost compression demands accelerated R&D in predictive beam algorithms to maintain feature differentiation.
For New Entrants and Emerging Players: Mid-market vehicle platforms in India and Southeast Asia represent the most penetrable entry point, as luxury segment procurement remains locked behind keiretsu and captive supplier relationships. Aftermarket software compatibility layers for legacy CAN bus architectures offer a secondary white-space target. Go-to-market execution should emphasize direct fleet procurement relationships that bypass traditional Tier 1 integrators.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized lighting engineers with ISO 26262-certified control algorithm development capabilities and established OEM direct relationships. Long-term viability over a multi-year horizon hinges on software monetization infrastructure and over-the-air update deployment. The signal to watch is NHTSA final rulemaking on adaptive beam glare-free systems, which would unlock substantial US market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Lighting Investment | Enables recurring subscription revenue from hardware already installed in Mercedes-Benz and BMW flagship platforms. |
| Sensor Fusion Platform Integration | Camera-lidar-radar stacks from Valeo and Forvia Hella extend detection range beyond pure vision limitations for Euro NCAP compliance. |
| LED Driver Backward Integration | Koito Manufacturing's captive chip packaging insulates margin control against Taiwan foundry concentration risk. |
| Geographic Manufacturing Footprint | Localized assembly in Pune and Chennai captures India premiumization without import duty exposure. |
| Regulatory Homologation Partnership | Direct engagement with KBA and NHTSA accelerates type-approval timelines for matrix beam systems. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution network managers, and automotive lighting R&D directors, then refined through secondary validation spanning vehicle production databases, IHS Markit registration data, NHTSA FMVSS 108 filings, and ECE R123 homologation records. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory mandate timelines and OEM platform launch schedules.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, sensor fusion technology, vehicle class tier, and regional production cluster. CAGRs were derived from installed base evolution and content-per-vehicle trajectories. Forecast inputs incorporated Euro NCAP protocol weighting changes and MIIT energy-efficiency mandate enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor foundry capacity allocation, or rare earth processing output would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization timelines and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market