
 Electric Vehicle (EV) Electronic Components Market | 2026-2036
Electric Vehicle (EV) Electronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Electronic Components Market Insights
Silicon carbide (SiC) power semiconductor migration is reconfiguring thermal management architectures across drivetrain electronics. Infineon Technologies leverages its Dresden fab capacity to anchor European SiC wafer supply. NXP Semiconductors specializes in battery management ICs that dominate voltage sensing precision. Bosch sustains vertical integration from semiconductor design through module assembly.
Electric vehicle electronic components comprise power semiconductors, battery management systems, onboard chargers, DC-DC converters, and motor control units engineered to operate at 400-800V with switching frequencies above 20 kHz, serving the primary purpose of efficient energy conversion and thermal regulation between storage systems and traction motors. Power inverters command the largest margin pool due to SiC content premiums, while solid-state battery interfaces represent the fastest-growing technology segment as cell chemistry transitions accelerate. OEMs constitute the most concentrated end-user channel, though aftermarket providers are expanding refurbishment capabilities for out-of-warranty battery management systems.
The US NHTSA and EPA enforce crashworthiness and emissions compliance that directly shape inverter housing standards and electromagnetic compatibility testing protocols. Europe's REACH and RoHS frameworks restrict hazardous substances in solder joints and capacitor dielectrics, compelling material substitutions across the supply base. China's GB standards and MIIT NEV catalog rules mandate domestic certification for every electronic control unit installed in vehicles sold nationally. Stakeholders must monitor how impending EU Battery Regulation digital passport requirements will force component-level traceability investments.
Market Dynamics
Silicon carbide power semiconductor adoption is collapsing thermal management system complexity while simultaneously inflating wafer supply constraints across the automotive electronics supply base. This material transition reconfigures inverter architectures, battery interface designs, and cooling subsystem requirements simultaneously.
Growth Catalysts
- China MIIT NEV Integration Mandates:Domestic certification requirements for every electronic control unit accelerate localized production investments and captive supply chain development within the country's vehicle manufacturing corridor.
- Fleet Electrification Logistics:Commercial vehicle operators across Germany and the United States are specifying 800V architectures that demand upgraded power semiconductor specifications and onboard charging capabilities.
- Silicon Carbide Wafer Capacity Expansion:European fab investments in Dresden and Villach anchor regional supply security for automotive-grade substrates, reducing import dependency for drivetrain manufacturers.
Market Restraints
- Silicon Carbide Substrate Cost Volatility:150mm wafer supply concentration among limited qualified vendors creates input price instability for inverter manufacturers scaling production.
- EU Battery Regulation Traceability Requirements:Impending digital passport mandates force component-level serialization investments that inflate compliance overhead for battery management system suppliers.
- IGBT Technology Persistence:Mature insulated-gate bipolar transistor platforms retain cost advantages in 400V economy vehicle segments, delaying full SiC conversion timelines.
Strategic Opportunities
- India Automotive Electronics Localization:PLI scheme incentives for advanced chemistry cell manufacturing create demand for domestic battery management system and power electronics assembly capacity.
- Solid-State Battery Interface Development:Next-generation cell chemistry transitions require redesigned voltage sensing architectures and thermal runaway detection protocols.
- Aftermarket Refurbishment Channels:Out-of-warranty battery management system remanufacturing represents an emerging revenue stream independent of OEM production cycles.
Industry Challenges
- Power Electronics Engineering Talent Scarcity:Shortages of specialists proficient in wide-bandgap semiconductor design and high-frequency magnetics constrain product development velocity.
- Multi-Standard Certification Complexity:Simultaneous compliance with US NHTSA crashworthiness, EPA electromagnetic compatibility, and China GB standards extends validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Electronic Components Market |
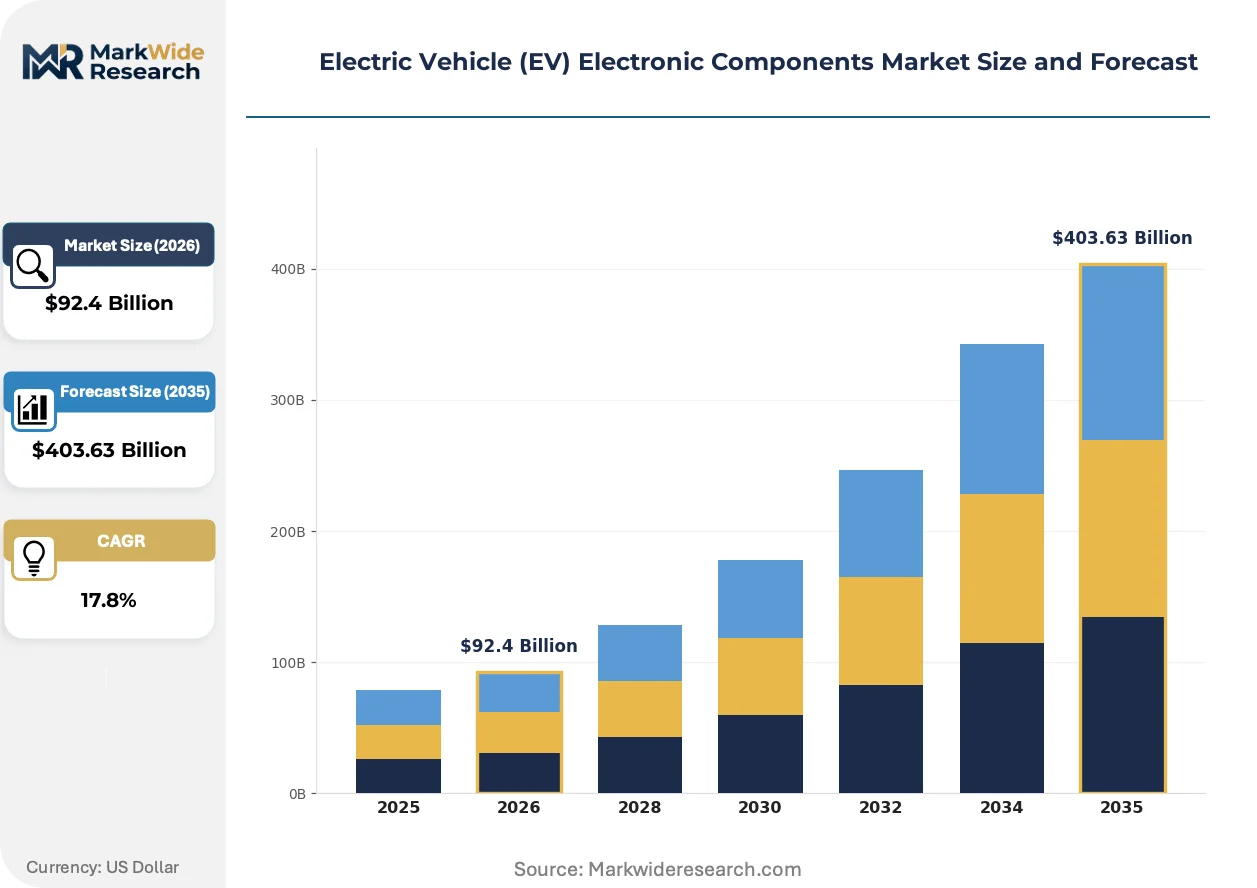
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $403.63 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Power Inverters, Electric Motors, Charging Stations Technology: Li-ion, Solid-State, Fast Charging, Wireless Charging End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses |
| Companies Covered | Infineon Technologies, NXP Semiconductors, Renesas Electronics, Texas Instruments, STMicroelectronics, Bosch, ON Semiconductor, ROHM Semiconductor, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Electronic Components Market Trends and Innovations
Three simultaneous forces are restructuring how electronic components are specified, procured, and integrated into vehicle platforms. Material science breakthroughs, regulatory traceability mandates, and procurement model evolution each create distinct competitive pressures.
Silicon carbide MOSFET technology is collapsing the boundary between power conversion and thermal management subsystems. OEM drivetrain engineers now specify unified cooling loops that service both inverters and battery packs. This integration eliminates redundant heat exchangers and pumps while demanding higher-grade substrate materials.
Europe's REACH substance restrictions and impending Battery Regulation digital passport requirements are forcing material substitutions across capacitor dielectrics and solder compositions. Component suppliers must requalify entire product families under compressed timelines. Germany's automotive corridor faces the steepest compliance burden given its concentration of high-voltage platform production.
Buyer concentration among OEM platform engineering teams is compressing supplier negotiation cycles and accelerating specification lock-in. Tier-1 electronics manufacturers now face direct sourcing relationships with vehicle manufacturers that previously filtered through module integrators. This disintermediation is most visible in the United States, where Ford and GM have established dedicated power electronics procurement offices bypassing traditional supplier hierarchies.
Electric Vehicle (EV) Electronic Components Market Segmentation
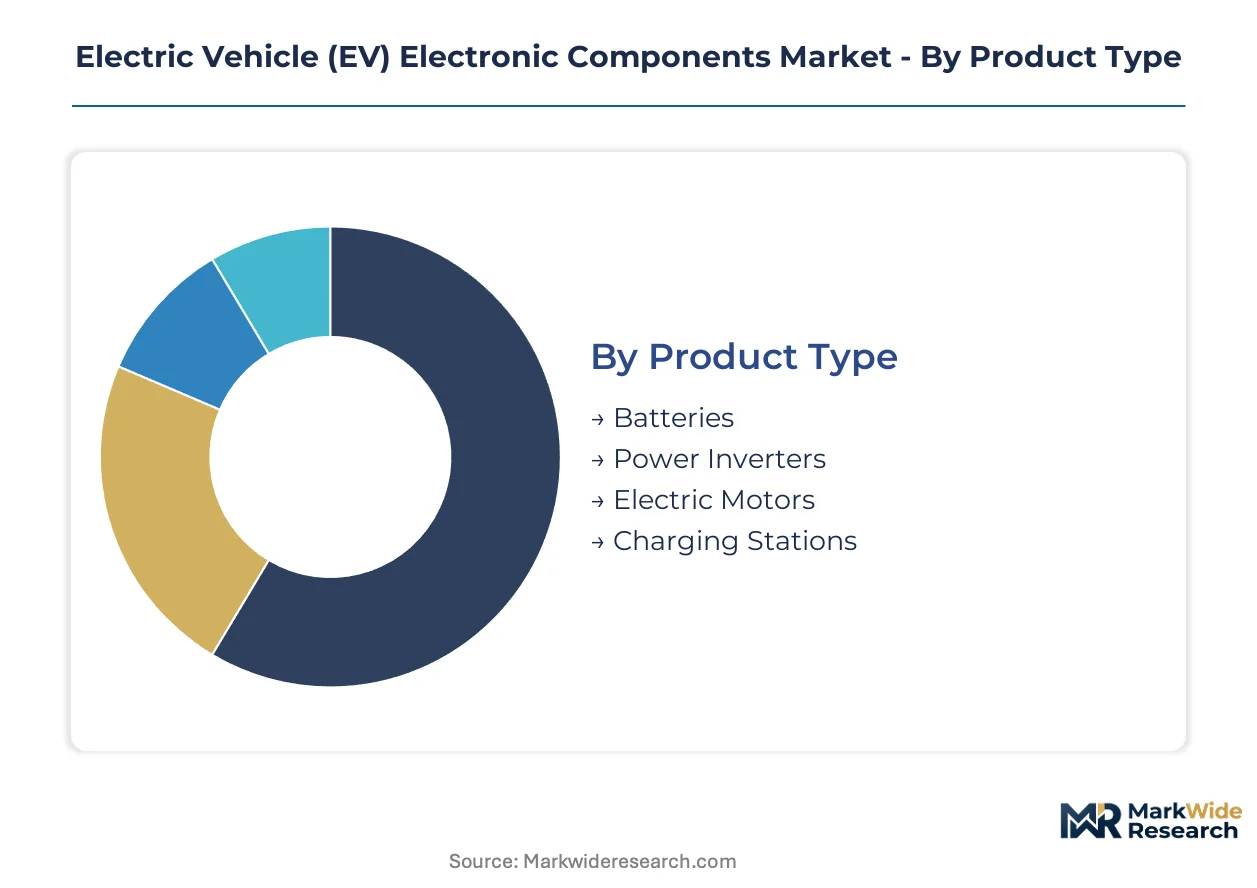
Electronic component specification varies sharply across vehicle platforms, creating distinct service intensity profiles. Battery management systems demand continuous firmware updates and thermal recalibration, while power inverters require less frequent intervention. Component segmentation directly shapes aftermarket revenue potential and warranty reserve calculations.
Product Type:
After-sales service intensity diverges dramatically across product categories, with battery systems generating recurring diagnostic revenue and inverter modules producing one-time replacement cycles.
- Power Inverters:Silicon carbide-based DC-AC conversion modules operating at 400-800V with switching frequencies above 20 kHz. Demand concentrates in Germany's automotive corridor around Stuttgart and Wolfsburg, where OEMs specify unified cooling loops that service both inverters and battery packs simultaneously.
- Batteries:High-voltage energy storage systems with integrated battery management ICs for voltage sensing precision. Fleet operators across the United States and Germany are scaling electrified logistics that demand upgraded cell monitoring architectures and thermal runaway detection protocols.
- Electric Motors:Permanent magnet synchronous and induction motor drive units with power electronics integration.
- Charging Stations:Onboard and offboard power conversion equipment for AC and DC charging interfaces.
By volume, Batteries lead. By growth pace, Power Inverters is ahead.
Technology:
Cost tier stratification separates premium wide-bandgap platforms from mature silicon-based alternatives, with price gaps exceeding 3x at equivalent power ratings.
- Solid-State:Next-generation cell chemistry with ceramic electrolyte interfaces requiring redesigned voltage sensing architectures. China's MIIT mandates on NEV integration and battery traceability tighten compliance thresholds for solid-state interface development investments.
- Fast Charging:High-power DC infrastructure and onboard power electronics enabling 350kW+ transfer rates. European REACH substance restrictions force material substitutions across capacitor dielectrics in fast-charging module assemblies.
- Li-ion:Mature lithium-ion cell technology with established supply chains and certification pathways.
- Wireless Charging:Inductive power transfer systems for automated charging without physical connectors.
By installed base, Li-ion leads. By technology transition velocity, Solid-State is expanding most quickly.
End User:
Procurement concentration varies by customer type, with OEM platform engineering teams compressing negotiation cycles and accelerating specification lock-in.
- OEMs:Vehicle manufacturers establishing direct sourcing relationships for power electronics that previously filtered through module integrators. Ford and GM in the United States have established dedicated procurement offices bypassing traditional supplier hierarchies entirely.
- Fleet Operators:Commercial vehicle buyers specifying 800V architectures across North America and Europe that demand upgraded power semiconductor specifications and onboard charging capabilities at volume scale.
- Tier-1 Suppliers:Module integrators facing disintermediation pressure from direct OEM-component relationships.
- Aftermarket Providers:Independent service channels expanding refurbishment capabilities for out-of-warranty battery management systems.
By contract value, OEMs lead. By margin expansion potential, Aftermarket Providers is climbing the fastest.
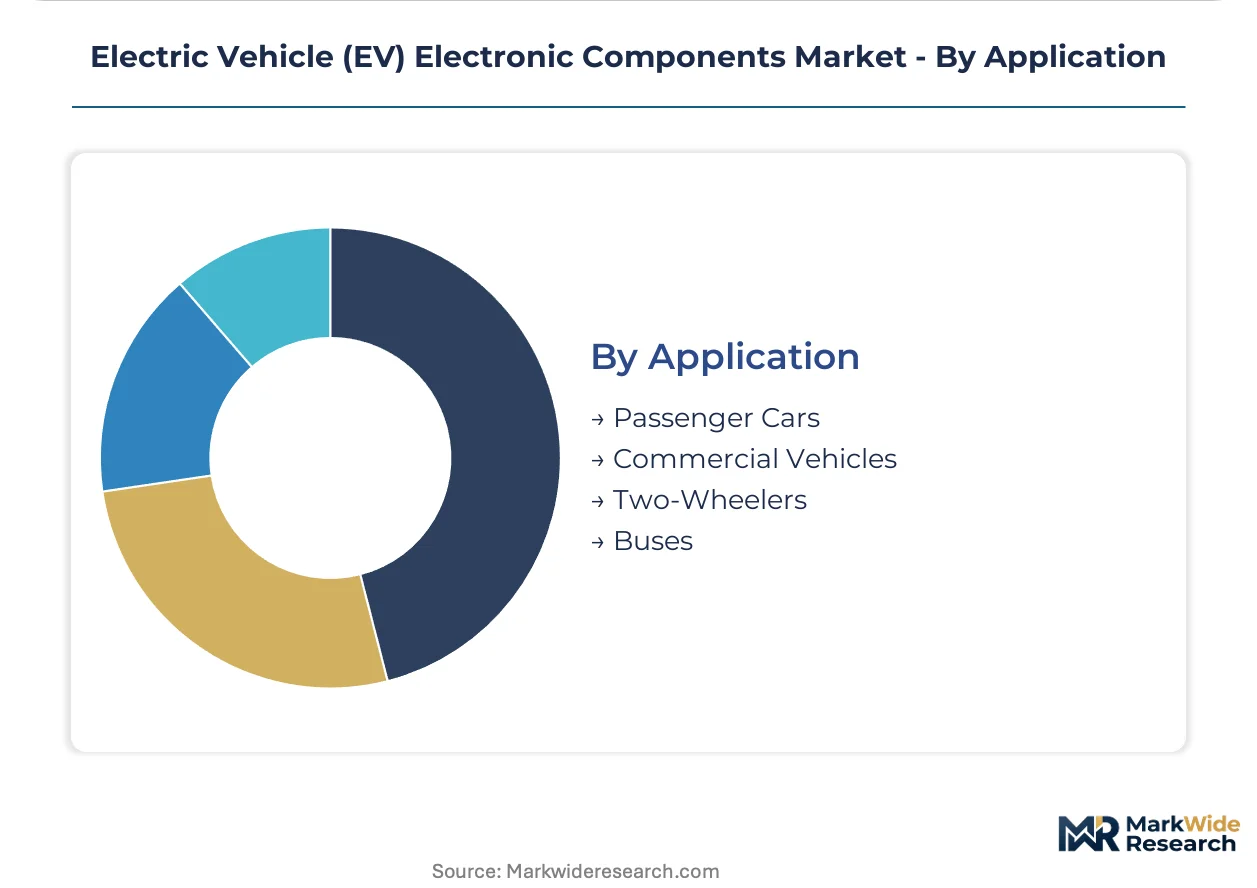
Application:
Platform voltage requirements and thermal management complexity scale with vehicle mass and duty cycle intensity.
- Commercial Vehicles:Heavy-duty trucks and vans operating on 800V platforms with sustained high-load duty cycles. Fleet electrification logistics across Germany and the United States drive specification upgrades for power semiconductors and thermal regulation subsystems.
- Passenger Cars:Light-duty vehicles spanning economy 400V IGBT architectures to premium 800V SiC platforms. Mature insulated-gate bipolar transistor platforms retain cost advantages in economy segments, delaying full silicon carbide conversion timelines.
- Buses:Transit and coach vehicles with high-capacity battery configurations and opportunity charging infrastructure.
- Two-Wheelers:Motorcycles and scooters with compact power electronics and cost-optimized battery management systems.
By unit shipments, Passenger Cars lead. By technology upgrade intensity, Commercial Vehicles is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and fleet operators drive procurement concentration across four major manufacturing geographies, with each market imposing distinct certification regimes on power electronics suppliers.
China
Domestic NEV production scales demand for battery management systems and onboard chargers. MIIT mandates domestic certification for every electronic control unit, compelling localized assembly investments. The Yangtze River Delta manufacturing cluster around Shanghai anchors substrate fabrication and module integration capacity.
Germany
Premium OEM platform engineering teams specify 800V SiC architectures for performance segments. REACH substance restrictions and impending EU Battery Regulation digital passport requirements force material requalification across capacitor dielectrics. Stuttgart and Wolfsburg concentrate inverter design centers and thermal management subsystem integration.
United States
Fleet electrification logistics across commercial vehicle operators drive specification upgrades for power semiconductors. NHTSA crashworthiness and EPA electromagnetic compatibility testing protocols shape inverter housing standards. Michigan and Texas host OEM procurement offices that bypass traditional Tier-1 hierarchies for direct component sourcing.
Japan
Automotive electronics specialists supply precision voltage sensing architectures to hybrid and battery-electric platforms. METI industrial policy supports wide-bandgap semiconductor development through domestic R&D consortia. The Nagoya automotive corridor maintains concentrated module assembly and quality validation facilities.
South Korea
Battery cell manufacturers generate captive demand for battery management ICs and thermal runaway detection systems. Domestic content requirements in NEV procurement favor locally certified electronic control units. The Seoul Capital Area clusters power electronics design houses serving Hyundai-Kia platform engineering teams.
Electric Vehicle (EV) Electronic Components Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages separate volume suppliers from niche technology developers. The market exhibits moderate concentration with identifiable leadership clusters around power semiconductor fabrication and battery management system design. Strategic archetypes include integrated automotive electronics conglomerates, pure-play semiconductor foundries, and module-level system integrators. Competitive moves center on captive wafer capacity expansion and direct OEM procurement relationship establishment.
Among European semiconductor specialists, Infineon Technologies and NXP Semiconductors occupy positions anchoring regional supply security for automotive-grade substrates and precision sensing architectures respectively. Bosch represents the vertically integrated conglomerate archetype with in-house production spanning semiconductor design through module assembly. STMicroelectronics sits within the diversified technology tier serving multiple voltage classes across economy and premium vehicle segments.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| Renesas Electronics |
| Texas Instruments |
| STMicroelectronics |
| Bosch |
| ON Semiconductor |
| ROHM Semiconductor |
| Analog Devices |
| Others |
Pricing and Supply Chain Analysis
Dresden's silicon carbide wafer fabrication cluster anchors European supply security for automotive-grade substrates, translating concentrated 150mm capacity into asymmetric pricing power for qualified vendors serving inverter manufacturers. This geographic chokepoint enables indexation premiums that downstream module assemblers struggle to pass through to OEM procurement offices.
Pricing Analysis
Cost-plus contracts with silicon carbide wafer price indexation dominate long-term supply agreements between substrate vendors and inverter manufacturers. Three-tier pricing structure across premium 800V SiC platforms, standard 400V hybrid architectures, and economy IGBT configurations separates certification-grade automotive from industrial-tier products. Cost compression in economy segments is intensifying because mature silicon platforms retain manufacturing scale advantages. Fleet operators specifying commercial vehicle architectures demonstrate lowest price sensitivity, while aftermarket refurbishment channels face margin pressure from warranty-voiding risks.
Supply Chain Analysis
Contract manufacturing concentration rests with TSMC and GlobalFoundries for automotive-grade microcontroller fabrication, while Foxconn and Jabil hold module assembly capacity for power electronics. Geographic supply concentration centers on Taiwan for leading-edge semiconductor foundry services, Germany for automotive module integration, and China for battery management system PCB fabrication. Raw material dependencies draw from rare earth elements for permanent magnet motors, high-purity silicon carbide substrates for wide-bandgap semiconductors, and lithium carbonate for battery cell interfaces. Single-source vulnerability around qualified 150mm SiC wafer vendors creates supply chain risk. Distribution runs through direct OEM procurement relationships that disintermediate traditional Tier-1 hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Electronic Components Market sits in early-cycle expansion as fleet electrification logistics across North America and Europe accelerate 800V platform penetration beyond passenger car segments into commercial vehicle duty cycles.
For Market Incumbents: Harden captive wafer capacity positions through Dresden and Villach fab investments to defend against emerging foundry entrants targeting automotive qualification timelines. Deepen backward integration into silicon carbide substrate supply as Chinese MIIT domestic certification requirements tighten import dependency risks. Reinforce direct OEM procurement relationships bypassing module integrators to secure specification lock-in before platform engineering cycles finalize. For New Entrants and Emerging Players: Establish a beachhead in aftermarket battery management system refurbishment channels where out-of-warranty service demand outpaces OEM production cycle dependencies. Target India's PLI scheme incentives for advanced chemistry cell manufacturing to capture localized power electronics assembly demand before incumbent capacity commitments solidify. Lead with solid-state battery interface development expertise as next-generation cell chemistry transitions create specification white space. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery management system suppliers with firmware update dependencies and thermal recalibration service contracts. Long-term viability favors vertically integrated specialists with in-house semiconductor design through module assembly capabilities. Battery traceability technology providers represent priority acquisition archetypes as EU Battery Regulation digital passport mandates force component-level serialization investments. Watch silicon carbide wafer yield improvement rates as the inflection signal for substrate cost trajectory and inverter margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Capacity Expansion | Dresden and Villach fab investments anchor European supply security against import dependency. |
| Battery Management System Firmware-as-a-Service | Continuous thermal recalibration contracts convert one-time hardware sales into recurring revenue streams. |
| Direct OEM Procurement Relationship Establishment | Ford and GM dedicated power electronics offices bypass traditional Tier-1 supplier hierarchies entirely. |
| Solid-State Battery Interface Development | Redesigned voltage sensing architectures capture specification premiums from next-generation cell chemistry transitions. |
| India PLI Scheme Localization Investment | Domestic assembly capacity qualifies for advanced chemistry cell manufacturing incentives under national industrial policy. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 electronics procurement directors, semiconductor foundry account managers, and aftermarket service channel operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings of listed semiconductor vendors, and MIIT NEV catalog certification records. Bottom-up component shipment estimates and top-down OEM platform content analysis were triangulated to reconcile volume figures.
Calibration against historical silicon carbide adoption curves and battery management system penetration rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, voltage platform tier, content per vehicle, and regional production cluster. CAGRs were derived from fitted adoption curves rather than linear extrapolation. Industry-specific forecast inputs incorporated MIIT domestic certification timeline assumptions and EU Battery Regulation digital passport implementation phasing.
Stress conditions across silicon carbide wafer yield improvement rates, fleet electrification logistics adoption velocity, and China GB standards enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of 150mm substrate spot pricing, OEM platform engineering specification lock-in announcements, and solid-state battery pilot production timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Digital Audio Processor Market
Electronic Components
Europe PCB Market
Electronic Components
Power Resistor Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Switch Diode Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
USB Charger Market
Electronic Components
Electronic Wipe Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Safety Relay Market
Electronic Components
Europe Radiation-Hardened Electronics Market