
 Sack Fillers Market | 2026-2036
Sack Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Sack Fillers Market Analytics
Automated servo-driven weighing systems is reconfiguring how sack fillers achieve precision at high throughput rates. Haver & Boecker Company leverages its German engineering heritage to dominate heavy-duty mechanical filler production for construction and chemicals. GEA Group AG sustains technology leadership in hygienic electronic fillers for dairy and food applications. Flexicon Corporation specializes in pneumatic conveying integration that extends its reach into specialty powder handling for agricultural clients.
Sack fillers are industrial packaging machines designed to dispense measured quantities of dry bulk materials into woven paper, plastic, or composite sacks, typically achieving accuracies within 0.1-0.5% of target weight depending on filler technology. These systems serve essential functions across commodity processing, enabling automated bagging of cement, flour, fertilizers, and polymer pellets at rates from 100 to 2,000 sacks per hour. Electronic fillers command premium positioning due to their load-cell precision and data-logging capabilities that support traceability requirements in food and pharmaceutical adjacent applications. Pneumatic fillers are gaining share in dusty environments where contained transfer reduces worker exposure and material loss. Gravity fillers retain cost advantages for free-flowing granules in agricultural and construction verticals where margins pressure capital expenditure decisions.
CE marking requirements under EU machinery directives shape design standards for safety interlocks and dust containment systems sold across Europe. FDA material contact regulations for food-grade equipment influence stainless steel specification and surface finish requirements in North American installations. OSHA combustible dust standards drive demand for explosion-proof electrical enclosures in chemical and food processing facilities. Stakeholders must monitor how evolving sustainability mandates around recyclable packaging materials reshape sack specification and filler compatibility requirements.
Market Dynamics
Automated servo-driven weighing systems is compressing the precision-throughput tradeoff that previously forced food and chemical processors to choose between speed and accuracy. This technological inflection is redrawing capital allocation patterns across filling line investments.
Growth Catalysts
- REACH compliance tightening:European material contact standards for powder-handling equipment are accelerating replacement cycles in Germany, France, and Italy as processors retrofit lines to meet evolving ECHA thresholds.
- Food and beverage throughput targets:Automated filling line expansions by dairy and bakery processors are pulling demand for electronic fillers with load-cell precision and data-logging capabilities.
- Stuttgart-Cologne machinery cluster:Regional supplier concentration around these German industrial centers is shortening lead times and strengthening technical service networks for sack filler deployments.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings directly compress margins on hygienic electronic fillers specified for dairy and pharmaceutical adjacent applications.
- German engineering concentration:Heavy-duty mechanical filler production clusters disproportionately around Haver & Boecker's domestic supply base, creating geographic single-source exposure.
- Gravity filler substitution ceiling:Free-flowing granule applications in agricultural and construction verticals resist upgrade to electronic systems where capital recovery periods exceed five years.
Strategic Opportunities
- OSHA combustible dust enforcement:Chemical and food processing facilities in the US are retrofitting explosion-proof electrical enclosures, opening upgrade windows for compliant pneumatic filler installations.
- Recyclable packaging mandate convergence:EU Green Deal and member state extended producer responsibility schemes are reshaping sack specifications, requiring filler compatibility investments that favor modular system suppliers.
- Pneumatic-conveying integration:Agricultural specialty powder handlers are consolidating material transfer and bagging operations, creating pull for Flexicon-type contained transfer systems that reduce worker exposure.
Industry Challenges
- CE marking compliance timelines:EU machinery directive safety interlock and dust containment certifications require 12-18 month validation cycles that delay revenue recognition on European deployments.
- Legacy gravity filler installed base:Agricultural cooperatives and regional cement distributors face integration complexity when retrofitting automated lines alongside mechanical systems with incompatible control architectures.
- Servo calibration expertise scarcity:Food processors report extended commissioning periods due to limited technician availability for multi-axis weighing system tuning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sack Fillers Market |
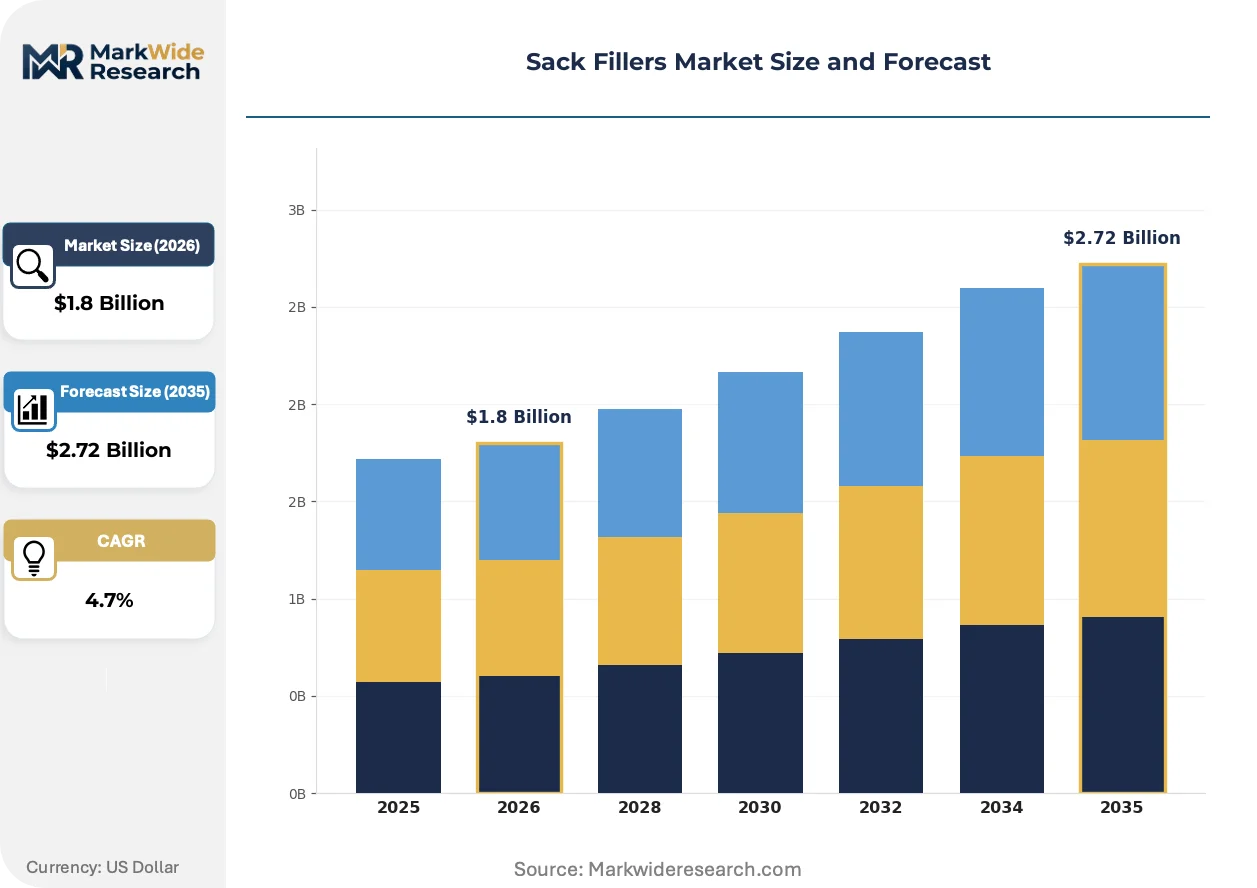
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Fillers, Electronic Fillers, Pneumatic Fillers, Gravity Fillers Industry Vertical: Agriculture, Food & Beverage, Chemicals, Construction Filling Material: Granules, Powder, Liquid, Semi-solid End User: Manufacturers, Distributors, Retailers, Packers |
| Companies Covered | Robert Bosch Packaging Technology GmbH, Haver & Boecker Company, Webster Griffin Ltd., Barry-Wehmiller Companies, Concetti S.p.A, Flexicon Corporation, GEA Group AG, Fres-co System USA Inc., Premier Tech Chronos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sack Fillers Market Evolving Landscape
Digital instrumentation and contained powder transfer architectures are displacing mechanical legacy systems across high-value processing verticals. These shifts are compressing the performance gap between premium electronic and mid-tier pneumatic configurations.
Load-cell-based servo weighing is digitizing quality assurance workflows in dairy and pharmaceutical adjacent applications. Mid-sized food processors are adopting these systems at accelerated paces to satisfy retailer traceability mandates. The technology is digitizing batch record-keeping and enabling real-time deviation flagging that reduces giveaway and recall exposure.
CE marking requirements under EU machinery directives are mandating redundant safety interlocks and enhanced dust containment architectures for all European installations. Industrial consequence includes elevated engineering hours and extended factory acceptance testing protocols. Dairy and infant nutrition processors in Germany and the Netherlands are responding by consolidating supplier relationships with vendors holding notified body pre-certifications.
After-sales service unbundling is fragmenting traditional maintenance contract structures in North American food processing. Equipment buyers are separating spare parts procurement from technical support, favoring regional service integrators over OEM captive service networks. This pattern is most visible in California and Wisconsin dairy processing corridors where third-party automation specialists are capturing calibration and preventive maintenance workflows.
Sack Fillers Market Segmentation
Sack filler procurement patterns diverge sharply across equipment categories, with after-sales service intensity varying from minimal on gravity systems to substantial on servo-driven electronic lines. Understanding these segment-specific service obligations and replacement cycle dynamics enables more precise vendor selection and total cost of ownership modeling.
Product Type:
After-sales service intensity escalates from gravity systems requiring minimal intervention to electronic fillers demanding ongoing calibration support and software maintenance contracts.
- Mechanical Fillers:Heavy-duty cam-and-linkage mechanisms handle abrasive construction materials and mineral aggregates at sustained throughput rates. German cement processors around the Cologne machinery cluster specify these systems for 20-year operational lifespans with scheduled rebuild intervals. Demand concentrates in European construction verticals where REACH material contact compliance drives periodic equipment replacement.
- Electronic Fillers:Load-cell-based servo weighing achieves 0.1% accuracy targets through multi-axis digital control architectures. Dairy processors in the Netherlands and infant nutrition facilities in Germany require these systems for FDA-aligned traceability and batch documentation. The segment commands premium positioning due to commissioning complexity and ongoing calibration service dependencies.
- Pneumatic Fillers:Contained powder transfer systems reduce worker exposure in dusty chemical and agricultural environments.
- Gravity Fillers:Simple hopper-fed designs serve free-flowing agricultural granules where capital constraints limit technology upgrades.
Mechanical fillers hold the largest share; momentum sits with electronic fillers.
Industry Vertical:
Cost tier stratification separates capital-intensive chemical installations from margin-sensitive agricultural deployments, with service contract structures adapting accordingly.
- Food & Beverage:Hygienic stainless steel construction and FDA material contact compliance define specifications for dairy, bakery, and infant nutrition processors. German and Dutch facilities prioritize electronic fillers with data-logging capabilities to satisfy retailer traceability mandates and EFSA safety documentation requirements. The vertical generates the most intensive after-sales service demand due to regulatory audit schedules.
- Chemicals:OSHA combustible dust standards and EPA emissions controls shape equipment selection for specialty powder and pellet handling. US Gulf Coast chemical processors are retrofitting explosion-proof electrical enclosures, creating upgrade windows for pneumatic filler installations with integrated dust containment.
- Agriculture:Fertilizer and feed grain bagging operates on compressed margins favoring gravity and mechanical systems.
- Construction:Cement and mineral aggregate filling prioritizes mechanical durability over precision in European and Middle Eastern markets.
Food & Beverage holds the largest share; chemicals are expanding most quickly.
Filling Material:
Volume throughput requirements and containment challenges create distinct equipment specifications across material states.
- Powder:Fine particulate handling demands pneumatic containment or sealed mechanical systems to manage dust exposure and material loss. European chemical and food processors face tightening ECHA thresholds under REACH, accelerating replacement of open-transfer equipment. The segment drives the highest service contract attachment rates due to wear component replacement schedules.
- Granules:Free-flowing pellets and crystals suit gravity and simple mechanical fillers in agricultural and construction applications where accuracy requirements remain modest.
- Liquid:Viscosity-variable pumping systems serve specialty chemical and food additive niches with sealed filling requirements.
- Semi-solid:Paste and slurry handling requires specialized auger or piston mechanisms in limited food processing and chemical applications.
Powder holds the largest share; granules show the steepest expansion trajectory.
End User:
Customer type determines procurement authority structures and service relationship preferences, from integrated manufacturer engineering teams to independent packer price sensitivity.
- Manufacturers:Integrated processors in dairy, chemicals, and construction materials deploy capital budgets for automated filling line expansions with multi-year service agreements. German food manufacturers around Stuttgart concentrate demand for electronic fillers with OEM-captive maintenance contracts.
- Distributors:Regional agricultural and cement supply intermediaries prioritize equipment reliability and local service response over technology sophistication.
- Retailers:Private-label food and agricultural product bagging operations specify mid-tier pneumatic systems with third-party service integrator support.
- Packers:Independent contract packaging services favor flexible equipment configurations accommodating multiple product formats.
Manufacturers hold the largest share; packers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering exports anchor transatlantic sack filler procurement, with Stuttgart-Cologne machinery clusters supplying automated lines to US dairy processors and Brazilian agricultural cooperatives seeking REACH-aligned equipment upgrades.
Germany
Stuttgart-Cologne machinery clusters concentrate demand for heavy-duty mechanical fillers serving cement and chemical processors. ECHA REACH compliance timelines are accelerating replacement cycles as manufacturers retrofit lines to meet evolving material contact thresholds. Bavarian dairy processors specify electronic fillers with data-logging capabilities for EFSA-aligned traceability documentation.
United States
OSHA combustible dust enforcement is driving retrofit demand for explosion-proof electrical enclosures across Gulf Coast chemical facilities. FDA material contact regulations shape stainless steel specifications for dairy and infant nutrition processors in Wisconsin and California. Third-party automation specialists in these corridors are capturing calibration and preventive maintenance workflows from traditional OEM service networks.
China
Construction material processors in the Yangtze River Delta and Pearl River Delta are expanding automated bagging capacity for cement and mineral aggregates. GB standards for machinery safety and MIIT industrial automation directives influence equipment specification for domestic and export-bound production lines. Zhengzhou-based fabricators serve agricultural cooperatives seeking gravity filler upgrades for fertilizer and feed grain operations.
Brazil
Agricultural cooperatives in São Paulo and Paraná prioritize equipment reliability for fertilizer and feed grain bagging on compressed margins. ANVISA pharmaceutical and food-grade equipment regulations influence specification patterns for processors serving export markets. Regional cement distributors face integration complexity when retrofitting automated lines alongside legacy mechanical systems.
India
FSSAI food safety mandates and BIS machinery standards are reshaping procurement criteria for dairy and spice processors in Maharashtra and Gujarat. PLI scheme incentives for food processing infrastructure are pulling demand for electronic fillers with traceability capabilities. Ahmedabad-based packers are consolidating material transfer and bagging operations to reduce worker exposure in dusty environments.
Sack Fillers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands. The vendor base clusters around German engineering heritage, North American pneumatic integration expertise, and Italian mechanical fabrication traditions. Three archetypes dominate: precision electronics specialists, heavy-duty mechanical producers, and contained-transfer system integrators. Competitive moves concentrate on modular system architecture development and regional service network expansion.
Among German-based engineering groups, Haver & Boecker Company and GEA Group AG exemplify divergent specialization vectors—one anchoring heavy-duty mechanical production, the other occupying hygienic electronic filler positioning. Flexicon Corporation represents the North American pneumatic-conveying integration archetype. Robert Bosch Packaging Technology GmbH sits within the diversified industrial automation tier, while Barry-Wehmiller Companies exemplifies the multi-brand consolidation model through its packaging machinery portfolio architecture.
| Leading Market Players |
|---|
| Robert Bosch Packaging Technology GmbH |
| Haver & Boecker Company |
| Webster Griffin Ltd. |
| Barry-Wehmiller Companies |
| Concetti S.p.A |
| Flexicon Corporation |
| GEA Group AG |
| Fres-co System USA Inc. |
| Premier Tech Chronos |
| Others |
Value Network & Pricing Analysis
Stuttgart-Cologne machinery clusters concentrate German engineering capacity for electronic and mechanical sack fillers, translating regional supplier density into pricing leverage for precision equipment tiers. This geographic concentration shapes how downstream food processors and chemical facilities negotiate capital expenditure allocations across automated filling line investments.
Pricing Analysis
Electronic servo-driven fillers command 40-60% premiums over gravity-fed mechanical systems due to multi-axis load-cell precision and data-logging architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant stainless steel configurations from REACH-aligned European specifications and basic agricultural-grade units. Cost compression in mid-tier pneumatic systems is intensifying because agricultural cooperatives delay upgrades beyond five-year capital recovery thresholds. Distributors and independent packers exhibit the highest price sensitivity, while integrated dairy and pharmaceutical-adjacent manufacturers prioritize traceability capabilities over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German engineering groups anchor procurement relationships with Brazilian agricultural cooperatives and Indian spice processors. Component sourcing concentrates in Germany, Italy, and China, with servo motors and load cells drawing from precision manufacturing clusters around Stuttgart and Milan. Single-source vulnerability persists for Grade 304 and 316 stainless steel specifications subject to commodity volatility. Distribution runs through OEM-captive service networks in Europe and third-party automation integrators in North American dairy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible intermediate bulk container systems and bulk bag unloaders threaten traditional sack filler incumbents in powder-handling applications, forcing established vendors to defend installed base relationships through service bundling and modular retrofit architectures.
For Market Incumbents: Build switching-cost moats through captive calibration service contracts and software-locked spare parts ecosystems. Haver & Boecker and GEA Group should deepen backward integration into servo drive manufacturing to insulate margins from component volatility. Defensive priority centers on pre-empting Flexicon-type pneumatic integration moves into agricultural specialty powder verticals. For New Entrants and Emerging Players: Brazilian fertilizer cooperatives and Indian FSSAI-compliant dairy processors represent the most penetrable white-space geographies for mid-tier electronic filler deployment. Zhengzhou-based fabricators and Ahmedabad packer consolidations offer channel partnership angles. Go-to-market traction requires ANVISA-aligned certification pathways for export-facing Brazilian processors. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because REACH and OSHA enforcement windows concentrate upgrade demand across 2026-2035. Target acquisition profile centers on regional service integrators with notified body pre-certifications. The signal to watch is ECHA threshold tightening velocity for European material contact compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Architecture Development | Enables gravity-to-electronic upgrades without full line replacement, reducing capital barriers for agricultural processors. |
| Notified Body Pre-Certification Investment | Compresses CE marking validation cycles from 18 months to 9 months for dairy installations in Germany and the Netherlands. |
| Pneumatic-Conveying Integration Partnership | Extends equipment reach into specialty powder handling where OSHA combustible dust standards drive contained transfer demand. |
| Regional Service Network Expansion | Captures aftermarket calibration workflows from OEM-captive networks in Wisconsin and California dairy corridors. |
| Recyclable Packaging Compatibility R&D | Aligns filler specifications with EU Green Deal extended producer responsibility schemes reshaping sack material requirements. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at dairy and chemical processing facilities, aftermarket service heads at OEM networks, and procurement leads at agricultural cooperatives, then refined through secondary validation. Primary fieldwork encompassed maintenance directors, OEM procurement teams, and technical R&D directors across German, US, and Brazilian installations. Secondary sources included EU machinery directive filings, ECHA REACH substance database updates, SEC 10-K disclosures from listed packaging machinery groups, and customs trade data for stainless steel component flows. Bottom-up equipment shipment tallies were triangulated against top-down capital expenditure surveys from food processing trade associations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning filler technology type, industry vertical, filling material state, and end-user procurement authority. CAGRs were derived from installed base replacement cycle analysis and greenfield capacity addition trajectories. Industry-specific forecast inputs incorporated ECHA compliance timeline acceleration and OSHA combustible dust enforcement intensity variations across US regional jurisdictions.
Practitioners should monitor ECHA threshold revisions, stainless steel commodity volatility, and servo technician availability constraints for early signals of forecast deviation. Forecasts reflect assumptions around regulatory enforcement continuity and capital expenditure recovery period stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market