
 Wall Oven Market | 2026-2036
Wall Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Oven Market Intelligence
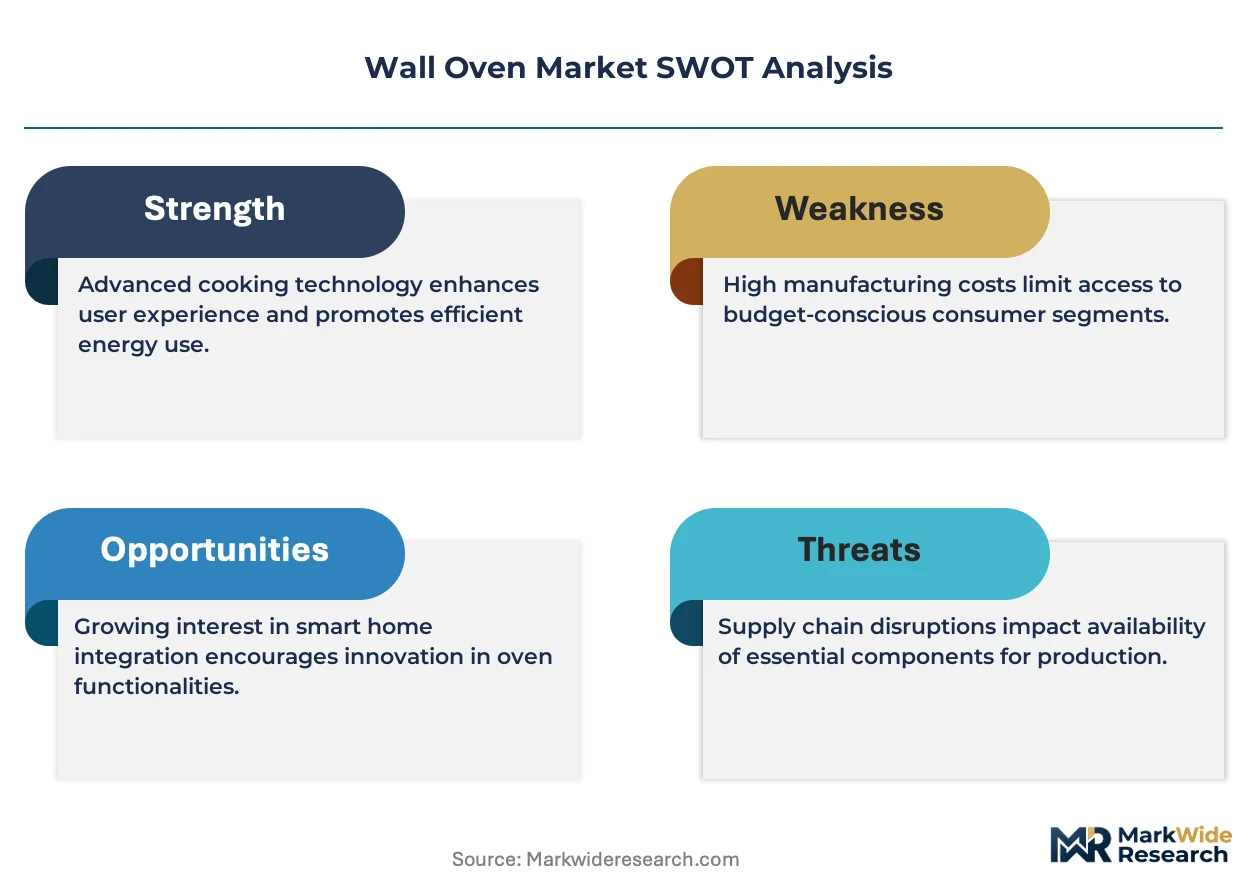
The consolidation of procurement by large-scale residential developers is realigning competitive dynamics in the wall oven market. This shift favors manufacturers with extensive supply chain capabilities and established business-to-business relationships. Bosch leverages its premium brand positioning to secure specifications in high-end multi-family projects. Meanwhile, Whirlpool competes on its vast distribution network and ability to fulfill high-volume orders for single-family home builders.
A wall oven is a cooking appliance designed for installation within a cabinet or wall, distinct from a freestanding range. Electric models, which typically require a dedicated 240-volt circuit, offer precise temperature control and represent the largest product type segment. The primary purpose is to provide integrated baking and roasting functions that blend seamlessly with kitchen design. While electric ovens form the market's core, models featuring smart connectivity and convection technology represent a high-growth category, driven by demand from residential kitchens.
Product design and market access are shaped by energy efficiency and safety regulations. In the United States, the Department of Energy's ENERGY STAR program sets voluntary efficiency standards, while the EU's Ecodesign Directive mandates minimum performance levels for appliances sold in Europe. Compliance with electrical safety certifications like the CE marking is essential for all manufacturers. Future product development will balance the integration of power-intensive smart features against increasingly stringent energy consumption mandates from regulators.
Market Dynamics
The primary dynamic shaping the wall oven market is the tension between integrating power-intensive smart features and adhering to stricter energy consumption mandates. This forces manufacturers to innovate in thermal efficiency and software optimization to satisfy both consumer desires and regulatory bodies.
Growth Catalysts
- Premium Residential Renovation:Kitchen modernization cycles in high-income urban households, particularly in the United States and Germany, prioritize integrated appliances. This demand favors wall ovens for their seamless, built-in aesthetic and advanced cooking functions that align with high-end cabinetry.
- Smart Home Ecosystems:The proliferation of home automation platforms acts as a significant pull for connected wall ovens. Consumers seek appliances that integrate with voice assistants and mobile applications for remote monitoring and control, creating a new basis for product differentiation.
- Convection Technology Adoption:The mainstreaming of convection and combination steam-convection cooking provides a clear performance upgrade over traditional thermal ovens. This technology's ability to cook faster and more evenly drives replacement sales and justifies premium pricing points for consumers.
Market Restraints
- High Upfront and Installation Cost:The total cost of ownership, including the unit price and specialized electrical work for a 240-volt circuit, remains a significant barrier. This expense positions wall ovens as a premium product, limiting penetration in budget-conscious residential construction and renovation projects.
- Space and Cabinetry Constraints:Unlike freestanding ranges, wall ovens require dedicated, correctly sized cabinet cutouts. This lack of interchangeability and the need for custom cabinetry can deter consumers during kitchen remodels, especially in older homes with non-standard dimensions.
- Substitution from Freestanding Ranges:High-performance freestanding ranges that incorporate dual ovens, air frying, and smart features offer a compelling, all-in-one alternative. These substitutes provide similar functionality without the cost and complexity of custom installation, posing a direct threat.
Strategic Opportunities
- Compact and Combination Models:There is an opportunity for smaller-footprint ovens designed for accessory dwelling units, micro-apartments, and secondary kitchens. Combination steam or microwave-convection models that consolidate functions address space constraints in dense urban housing markets.
- Software and Content Services:Manufacturers can develop subscription-based services offering guided cooking programs, curated recipes from professional chefs, and diagnostic support. This creates a recurring revenue stream beyond the initial hardware sale and deepens customer engagement.
- Channel Expansion to Kitchen Designers:Cultivating direct relationships with interior designers and kitchen design firms presents a key opportunity. These professionals heavily influence appliance selection in the premium residential segment and can be powerful brand advocates for specific manufacturers.
Industry Challenges
- Electronic Component Volatility:The reliance on microprocessors, sensors, and high-resolution displays creates vulnerability to semiconductor supply chain disruptions. Shortages or price spikes in these critical components can delay production schedules and erode profit margins for manufacturers of smart ovens.
- Software Obsolescence and Support:Ensuring long-term support, including security patches and feature updates, for connected appliances is a significant operational challenge. Failure to maintain software risks damaging brand reputation and creating cybersecurity vulnerabilities for consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Oven Market |
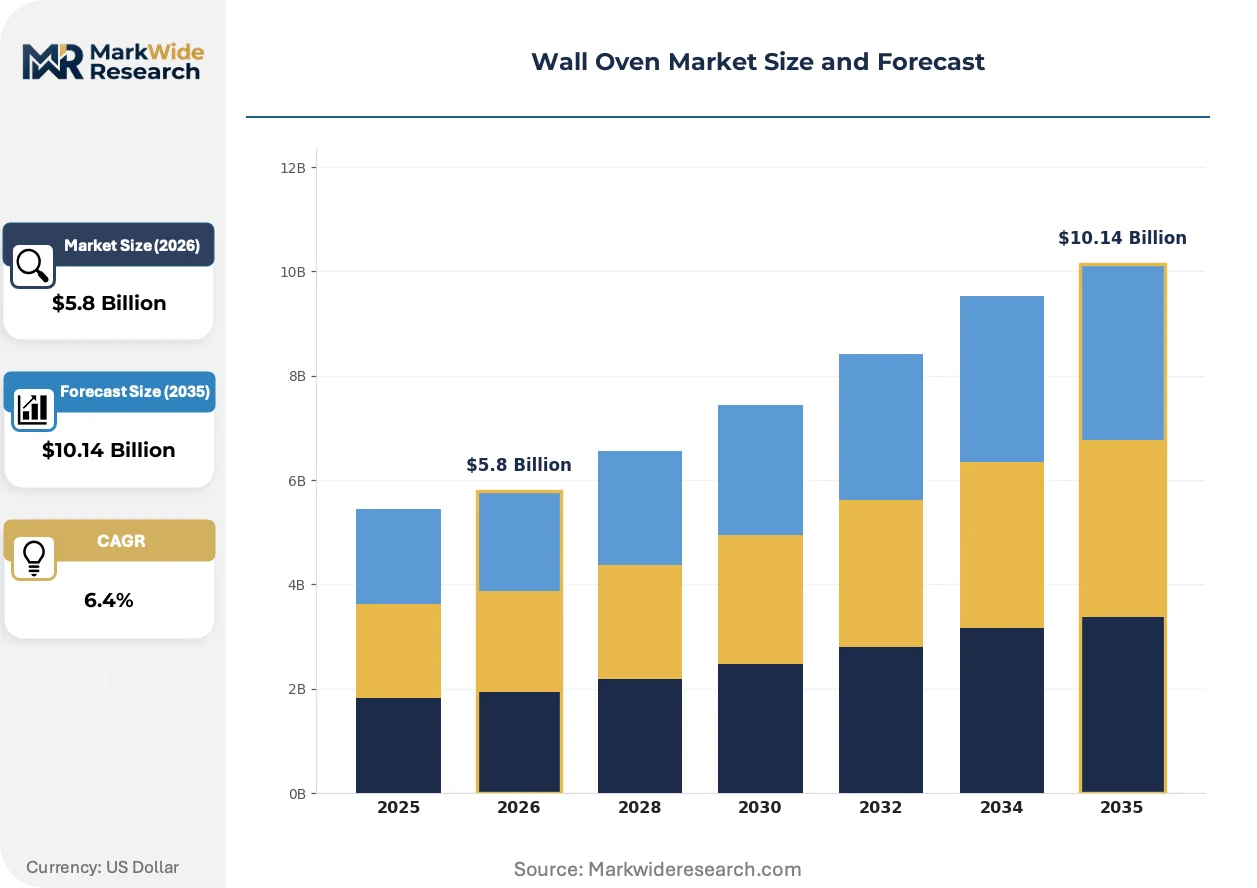
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Microwave, Convection, Steam Technology: Touch Control, Dial Control, Smart Connectivity, Self-Cleaning, Digital Display Application: Residential Kitchens, Foodservice Establishments, Catering Services, Commercial Kitchens, Boutique Bakeries End User: Homeowners, Restaurants, Hotels, Cafes, Corporate Dining Facilities |
| Companies Covered | Bosch, LG, Thermador, Electrolux, Whirlpool, Miele, GE Appliances, Gaggenau, Wolf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Oven Market Strategic Shifts & Innovations
Product evolution is defined by the integration of software-driven cooking assistance and multi-functionality. The wall oven is transforming from a static hardware piece into a dynamic, connected hub that simplifies the cooking process and consolidates the functions of multiple countertop appliances.
AI-powered cooking assistance, which utilizes internal cameras and sensors, is a defining technological evolution. This system automates temperature, time, and cooking mode adjustments based on food recognition. The feature is being adopted primarily by consumers in the premium market segment who value convenience and consistent results. This intelligent functionality is absorbing the need for manual recipe interpretation and constant monitoring, positioning the oven as a more autonomous kitchen partner.
The EU's "right to repair" framework, an element of the Ecodesign Directive, is a pivotal regulatory shift. It mandates that manufacturers make spare parts and repair documentation available for an extended period. This directly impacts product engineering, forcing a move towards more modular and easily serviceable designs for complex electronic components. The premium smart oven category is most affected, as intricate systems must now be architected for disassembly and component replacement by independent technicians.
A distinct behavioral shift is visible in customer evaluation criteria, moving beyond hardware specifications to the total user experience. The quality of the digital interface, the intuitiveness of the mobile app, and the richness of the connected ecosystem are becoming primary purchase drivers. This pattern disrupts traditional retail channels focused on performance metrics, favoring brands that demonstrate superior software design and ecosystem integration. This is most prominent in North American and European urban markets where smart home adoption is high.
Wall Oven Market Segmentation
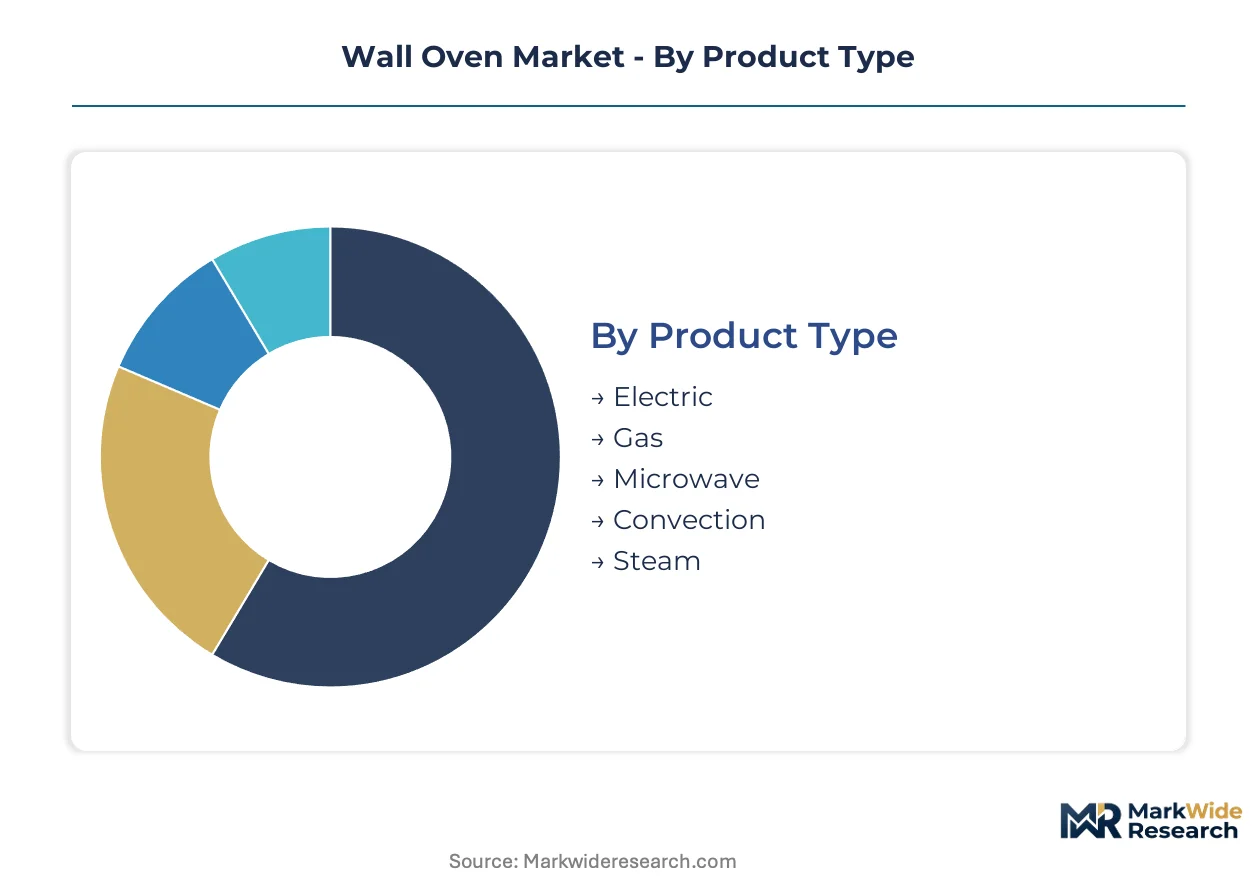
The segmentation analysis of the wall oven market provides a granular view of product evolution and demand drivers. Understanding these distinct categories helps manufacturers align product development with specific consumer preferences and installation requirements. This detailed breakdown illuminates strategic opportunities across various market niches.
Product Type:
The upgrade and replacement cycles significantly influence the product type segmentation, as consumers often seek enhanced features over their previous appliances.
- Electric:These models rely on resistive heating elements and typically require a dedicated 240-volt circuit for operation. Their precise temperature control makes them a staple in residential kitchens, driving replacement cycles as homeowners upgrade to more efficient and feature-rich units.
- Convection:Incorporating a fan and exhaust system to circulate hot air, these ovens provide faster and more even cooking. Demand concentrates in high-end residential renovations in urban markets where culinary performance and efficiency are prized.
- Gas:These wall ovens utilize natural gas or propane for heat generation, favored in regions with established gas infrastructure for their moist heat cooking characteristics.
- Microwave:Compact units designed for rapid reheating and defrosting, often integrated into combination wall oven configurations for space efficiency.
- Steam:These appliances inject steam during the cooking process, valued for preserving food moisture and nutrients, appealing to health-conscious consumers.
Volume placements concentrate in Electric models; the faster expansion belongs to Convection technology.
Technology:
Customer type preferences significantly shape the technology landscape, with different user groups prioritizing distinct operational and connectivity features.
- Smart Connectivity:These ovens integrate with home automation platforms, allowing remote control via mobile apps and voice assistants. Homeowners in tech-forward urban areas prioritize these features for convenience and ecosystem integration.
- Self-Cleaning:This technology utilizes high temperatures to incinerate food residues, simplifying maintenance for consumers. Its appeal is strong among busy households seeking convenience and reduced manual effort in kitchen upkeep.
- Touch Control:Modern interfaces offering sleek aesthetics and intuitive operation, often found in premium appliance designs.
- Dial Control:Traditional mechanical or electronic knobs provide tactile feedback, appealing to users who prefer a familiar and straightforward interface.
- Digital Display:Provides clear readouts of temperature, time, and cooking modes, enhancing user experience across various product tiers.
The foundational segment is Digital Display, while Smart Connectivity drives innovation.
Application:
The volume of demand varies considerably across different application segments, reflecting diverse operational needs and installation environments.
- Residential Kitchens:This segment encompasses wall oven installations in private homes and apartments, driven by new construction and renovation projects. Consumers seek appliances that blend seamlessly with kitchen design and offer advanced cooking capabilities for daily use.
- Foodservice Establishments:This category includes restaurants, cafes, and institutional kitchens requiring robust, high-capacity ovens for continuous operation. Durability and consistent performance are critical for these professional environments.
- Catering Services:Mobile and specialized ovens designed for off-site food preparation and event-based cooking, emphasizing portability and rapid heating.
- Commercial Kitchens:Large-scale operations demanding industrial-grade appliances capable of handling high volumes and diverse cooking tasks.
- Boutique Bakeries:Specialty ovens tailored for precise temperature and humidity control, crucial for artisanal bread and pastry production.
The largest demand originates from Residential Kitchens, with specialized needs met by Foodservice Establishments.
End User:
Margin opportunities are influenced by the specific needs and purchasing power of various end-user groups, from individual consumers to large institutional buyers.
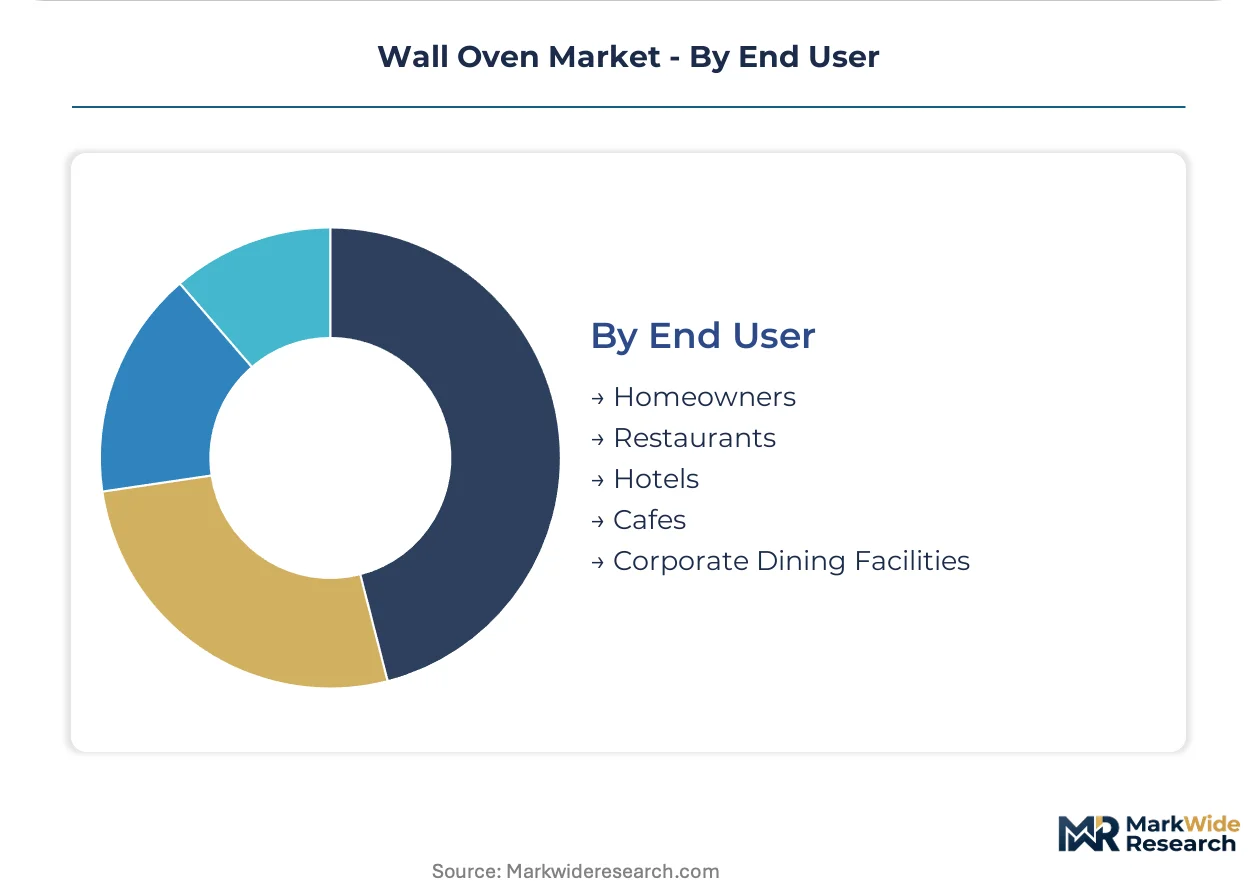
- Homeowners:Individual consumers purchasing wall ovens for personal residential use, often prioritizing aesthetic integration, smart features, and energy efficiency. Their purchasing decisions are heavily influenced by kitchen design trends and lifestyle demands.
- Restaurants:Professional culinary businesses requiring high-performance, durable ovens capable of continuous operation and precise cooking. Investment decisions are driven by operational efficiency, reliability, and menu requirements.
- Hotels:Establishments utilizing ovens for guest dining, banqueting, and room service, focusing on capacity and consistent quality.
- Cafes:Smaller food service outlets employing ovens for baking pastries, heating prepared foods, and light meal preparation, valuing speed and compact design.
- Corporate Dining Facilities:Institutional settings providing meals for employees, requiring robust ovens for large-scale food production and varied menu offerings.
The primary consumer base is Homeowners, while the institutional market includes Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wall ovens concentrates in developed urban markets where kitchen modernization cycles are frequent. Consumers in these regions prioritize integrated appliances and smart home ecosystems for convenience and aesthetic appeal. This focus drives product innovation and market penetration.
United States
The United States market sees strong demand from premium residential renovation projects and smart home ecosystem integration. Department of Energy's ENERGY STAR program influences efficiency standards for new appliance models. Major urban centers like the New York City metropolitan area drive volume for high-end, integrated kitchen solutions.
Germany
Germany exhibits robust demand from high-income urban households prioritizing seamless kitchen design and advanced cooking functions. The EU's Ecodesign Directive mandates minimum performance levels for appliances sold. Urban centers such as Munich and Berlin show significant adoption for integrated smart ovens.
United Kingdom
United Kingdom consumers increasingly seek wall ovens for kitchen modernization and space optimization in dense urban areas. Compliance with CE marking is essential for all electrical appliances entering the market. London's luxury apartment developments represent a key cluster for premium wall oven installations.
France
French consumers prioritize integrated appliances in new construction and increasingly adopt convection technology for efficient cooking. The EU's "right to repair" framework impacts product engineering for modular design. Major metropolitan regions like Paris and Lyon demonstrate consistent demand for feature-rich models.
Canada
Canadian homeowners drive demand through home renovation cycles and desire for smart connectivity in new builds. Health Canada oversees product safety and electrical standards for kitchen appliances. Urban housing markets in Toronto and Vancouver show sustained interest in premium wall oven solutions.
Wall Oven Market Key Industry Players
North American producers anchor one tier; European specialists hold another, creating a diverse competitive landscape. The wall oven market exhibits a tiered structure, with established appliance manufacturers competing against niche premium brands. Scale manufacturers focus on vast distribution networks and high-volume orders. Premium players differentiate through advanced features and design aesthetics. Three strategic archetypes define the market: integrated appliance conglomerates, luxury segment specialists, and mass-market volume providers. Portfolio diversification and strategic partnerships are dominant competitive moves.
On the premium-tier vector, Bosch, a German-based manufacturer, represents high-end brand positioning, securing specifications in multi-family projects and luxury kitchen renovations. Whirlpool, a US-based corporation, exemplifies a mass-market volume provider, leveraging its extensive distribution network and ability to fulfill high-volume orders for diverse residential construction. Miele, another German-based company, sits within the luxury segment, known for its advanced cooking functionalities and design, appealing to discerning homeowners seeking sophisticated kitchen solutions and superior user experience. These companies anchor distinct competitive approaches.
| Leading Market Players |
|---|
| Bosch |
| LG |
| Thermador |
| Electrolux |
| Whirlpool |
| Miele |
| GE Appliances |
| Gaggenau |
| Wolf |
| Others |
Cost & Logistics Intelligence
Large-scale residential developers' consolidated procurement drives contract-based pricing models, impacting manufacturer margins. This concentration of buying power influences the competitive landscape for wall oven suppliers.
Pricing Analysis
Volume-driven segments prioritize per-unit transactional pricing, while premium offerings leverage value-based models. Brand premium and after-sales service differentiate pricing, especially in high-end urban markets. Pricing pressure stems from intense competition in the mass-market segment, particularly from freestanding range alternatives. Homeowners are less price-sensitive for smart, integrated features, but budget-conscious builders are highly sensitive to unit costs.
Supply Chain Analysis
Dual-sourcing requirements for critical electronic components are becoming standard practice for major wall oven manufacturers. Geographic supply concentrates in China and Southeast Asia for microprocessors, while European and US facilities produce specialized heating elements. Single-source vulnerability for smart connectivity modules presents a structural risk. Distribution runs through established appliance retailers and direct-to-builder channels for multi-family projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wall oven market is experiencing a vertical-integration race, with manufacturers pursuing in-house software development to control the user experience and connected ecosystem.
For Market Incumbents: Anticipate increased regulatory scrutiny on energy consumption mandates, particularly in the EU and United States. Consolidate supply chains for electronic components and invest in modular product designs to counter software obsolescence. Focus R&D on thermal efficiency improvements and AI-powered cooking assistance as a key lever.
For New Entrants and Emerging Players: Enter via niche segments like compact, combination models designed for micro-apartments or accessory dwelling units. Target dense urban housing markets in North America and Europe, where space optimization is critical. A go-to-market angle involves partnering directly with interior designers and custom cabinet makers to secure early specifications.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in the European market with strong R&D capabilities in smart home technology. Long-term viability hinges on companies that can balance power-intensive features with stringent energy efficiency regulations. The signal to watch is the adoption rate of subscription-based cooking services.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Combination Steam Oven) | Addresses space constraints and health-conscious consumer demand in urban centers. |
| Platform Integration (Smart Home Ecosystems) | Enhances user experience and remote control for tech-forward homeowners in Germany. |
| Strategic Partnership (Kitchen Design Firms) | Secures early product specifications and brand advocacy in premium residential renovations. |
| Manufacturing Scale-Up (Convection Component Production) | Reduces reliance on external suppliers for high-growth technology. |
| Software Development (AI-Powered Cooking Assistance) | Differentiates products through enhanced convenience and automated cooking functions. |
Research Approach
Academic journals, industry reports, and government publications formed the secondary backbone, supplemented by primary interviews. We engaged with product development executives, kitchen appliance retailers, smart home platform engineers, and residential developers. This approach facilitated bottom-up and top-down triangulation of market data.
Historical trendline analysis informed the projection of future market trajectories across the analysis window. We modeled segmentation dimensions including product type, technology, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from a multi-variant regression analysis. Key forecast inputs included housing starts data and smart home penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant supply chain disruptions or rapid regulatory shifts. These forecasts reflect assumptions regarding technological advancements and consumer purchasing power. Deviation in semiconductor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Sanitary Towel Machine Market
Appliances
Japan Massage Equipment Market
Appliances
Triple Barrel Waver Market
Appliances
UAE Dishwasher Market
Appliances
Toaster Ovens Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Lightwave Microwave Oven Market
Appliances
Middle East Water Heater Market
Appliances
Electrical Appliances Plastics Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Microwave Oven Market
Appliances
Smart Washing Machine Market