
 Saudi Arabia Electric Water Heater Market | 2026-2036
Saudi Arabia Electric Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Electric Water Heater Market Analytics
Commercial buyers is bifurcating away from price-sensitive residential segments toward specification-driven hospitality and healthcare procurement. A.O. Smith anchors its position through tank-in-tank engineering for high-occupancy buildings. Ariston Thermo Group leverages Italian design heritage to differentiate in premium villa developments. Saudi Ceramics competes on local manufacturing scale and distribution depth across provincial cities.
An electric water heater converts electrical energy into thermal energy via immersed resistance elements or heat pump compressors to raise and store potable water temperature, typically operating at pressures up to 8 bar and efficiencies governed by insulation thickness and heating element wattage. Storage units dominate installed base owing to lower upfront cost and compatibility with Saudi grid capacity, while heat pump variants capture fastest growth among sustainability-focused commercial projects. Wall-mounted configurations occupy the majority of residential demand, though floor-standing models retain margin pools in industrial and above-100-liter commercial segments.
SASO mandates minimum energy performance standards and labeling requirements that filter non-compliant imports at port of entry. The Saudi Building Code, enforced by municipal authorities in Riyadh, Jeddah, and Dammam, specifies temperature safety limits and installation clearances that shape product dimensioning. SFDA oversight of materials in contact with potable water adds a compliance layer for tank lining and element sheathing. Stakeholders must monitor how upcoming efficiency tier revisions and building decarbonization directives alter procurement specifications and supplier qualification thresholds.
Market Dynamics
SASO energy-efficiency mandates are compressing demand toward certified units while hospitality construction accelerates procurement of specification-driven systems across Riyadh and Jeddah municipal markets.
Growth Catalysts
- Hospitality Construction Pipeline:Hotel development across the Kingdom is pulling commercial-grade electric water heater procurement toward higher-capacity, tank-in-tank configurations designed for continuous occupancy cycles.
- SASO Minimum Energy Performance Standards:Port-of-entry filtering of non-compliant imports is clearing shelf space for certified manufacturers and accelerating replacement cycles in existing building stock.
- Heat Pump Technology Maturation:Sustainability-focused commercial projects are specifying heat pump variants for new construction, displacing resistance-element systems in premium developments.
Market Restraints
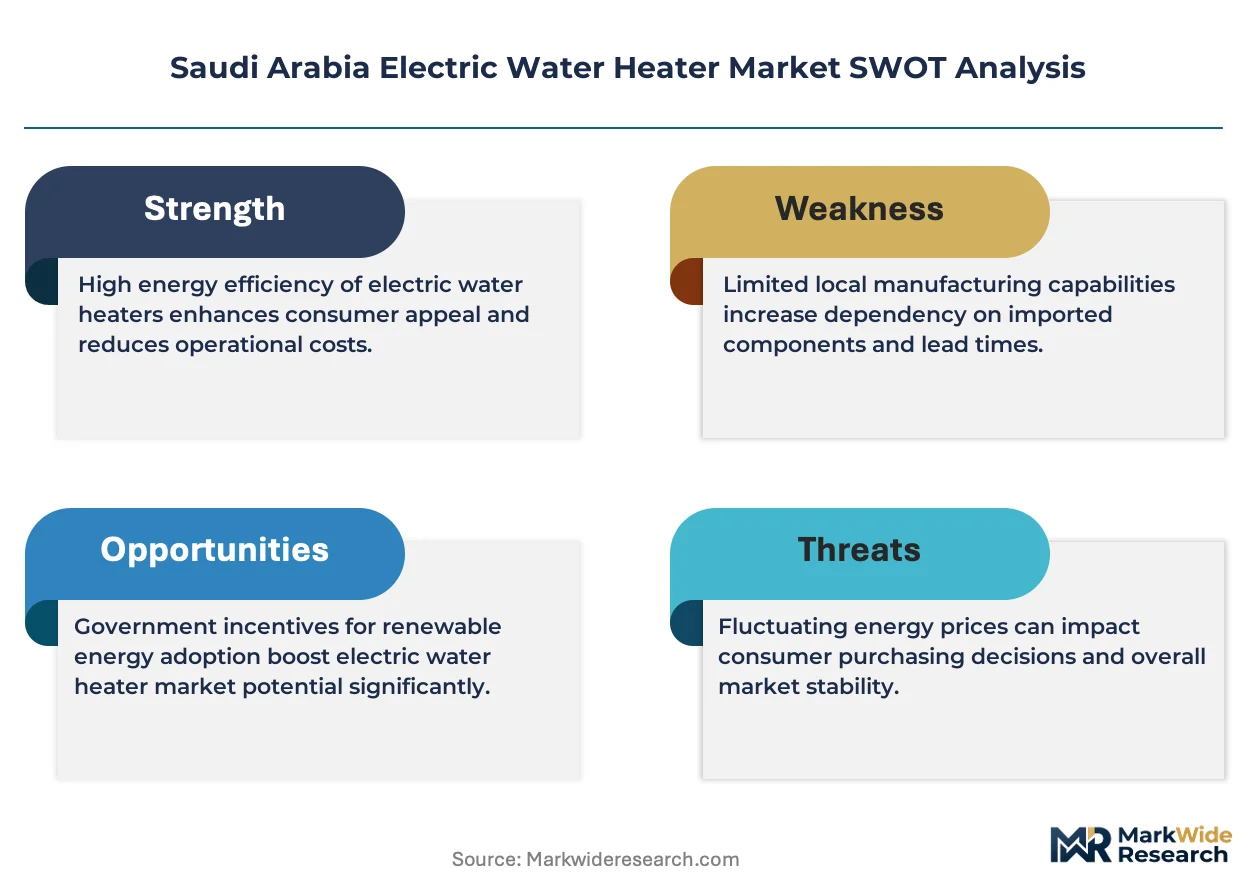
- Copper and Steel Input Volatility:Tank fabrication depends on copper heating elements and galvanized steel shells, exposing manufacturers to commodity price swings that compress margin pools on economy-tier units.
- Grid Capacity Constraints:Resistance-element systems above 100 liters strain residential distribution infrastructure in older Riyadh districts, limiting penetration of high-capacity residential models.
- Gas Water Heater Substitution:LPG and natural gas alternatives retain cost advantages in off-grid provincial settlements, constraining electric share in peripheral markets.
Strategic Opportunities
- Smart Controls Integration:IoT-enabled temperature management and predictive maintenance modules are opening specification premiums in hospitality and healthcare verticals seeking operational visibility.
- Provincial City Distribution Gaps:Secondary markets in Tabuk, Hail, and Abha exhibit underdeveloped dealer networks, creating first-mover advantages for local manufacturing scale players.
- Saudi Building Code Decarbonization Directives:Upcoming efficiency tier revisions will mandate heat pump readiness in new commercial construction, positioning early compliance as a qualification barrier.
Industry Challenges
- SFDA Potable Water Material Certification:Tank lining and element sheathing materials require extended testing timelines, delaying product launches and compressing competitive response windows.
- Heat Pump Installation Skill Scarcity:Refrigerant handling and compressor diagnostics demand technician training programs that outpace current vocational pipeline output.
- Legacy Resistance-Element Retrofit Complexity:Existing building electrical infrastructure often requires panel upgrades to accommodate heat pump amperage draws, lengthening sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Electric Water Heater Market |
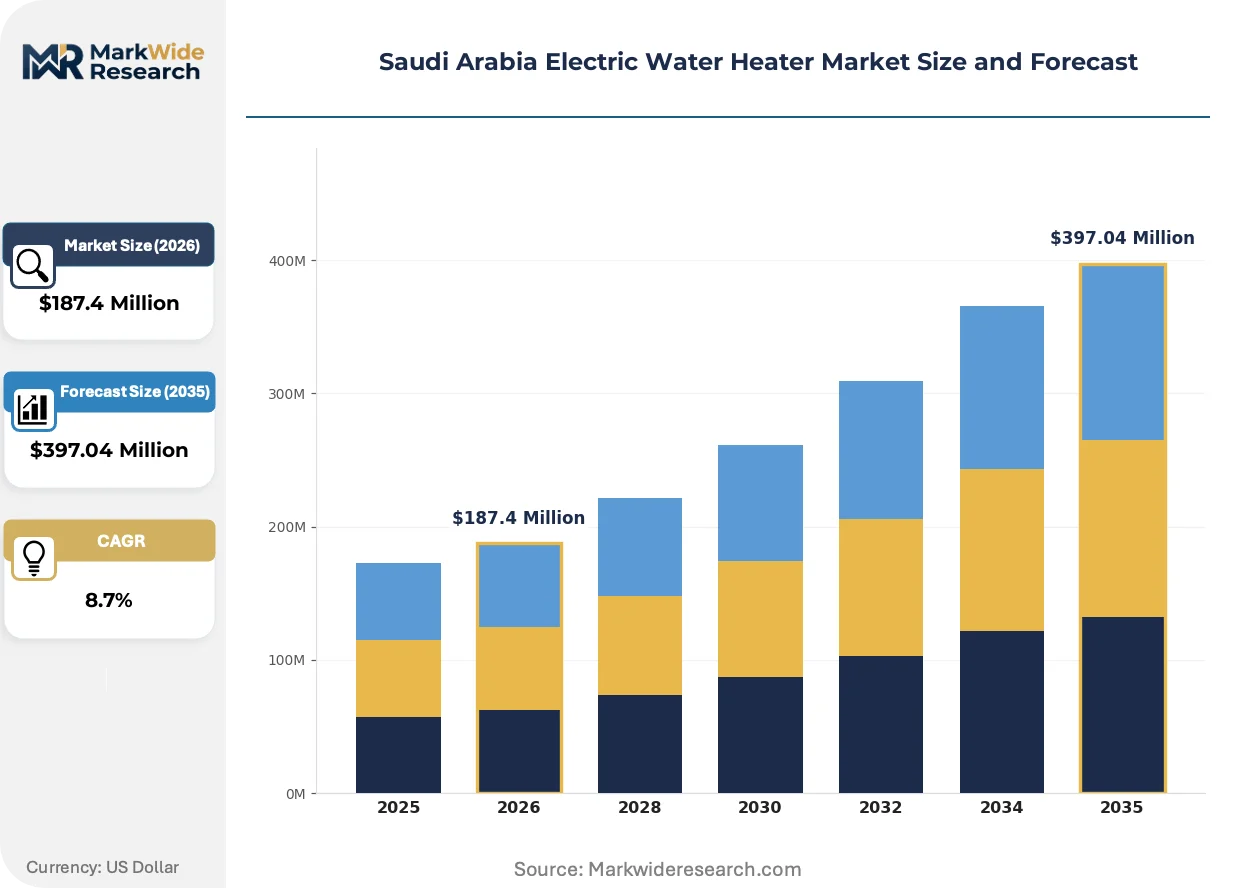
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instantaneous, Storage, Heat Pump, Solar End User: Residential, Commercial, Industrial, Hospitality Capacity: 10-30 Liters, 30-50 Liters, 50-100 Liters, Above 100 Liters Installation Type: Wall-Mounted, Floor-Standing, Portable, Built-In |
| Companies Covered | Bosch Thermotechnology, Haier, A.O. Smith, Saudi Ceramics, Whirlpool Corporation, Ariston Thermo Group, Rinnai Corporation, Legrand, Rheem Manufacturing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Electric Water Heater Market Evolving Landscape
Active thermal management technologies and connected control architectures are redefining product specifications across residential and commercial procurement channels.
Tank-in-tank engineering is miniaturizing footprint requirements while maintaining recovery rates for high-occupancy buildings. Hospitality developers in Jeddah's coastal corridor are specifying these compact systems to maximize mechanical room density. The technology is miniaturizing installation clearances mandated by municipal building codes, enabling higher-capacity units in constrained urban footprints.
SASO labeling requirements and Saudi Building Code temperature safety mandates are forcing redesign of thermostat architectures and relief valve configurations. Manufacturers must now integrate dual-redundancy temperature cutoffs to satisfy enforced installation clearances in Riyadh, Jeddah, and Dammam jurisdictions. Commercial specification sheets increasingly cite compliance certification as a disqualifying threshold rather than a preference.
Facility managers in healthcare and hospitality verticals are unbundling after-sales service from equipment procurement, contracting directly with certified maintenance networks for predictive monitoring. Traditional dealer-installer channels are losing attach revenue to independent service operators offering outcome-based uptime guarantees. This disintermediation is most visible in Riyadh's hospital construction cluster, where procurement teams separate capital equipment from multi-year service agreements.
Saudi Arabia Electric Water Heater Market Segmentation
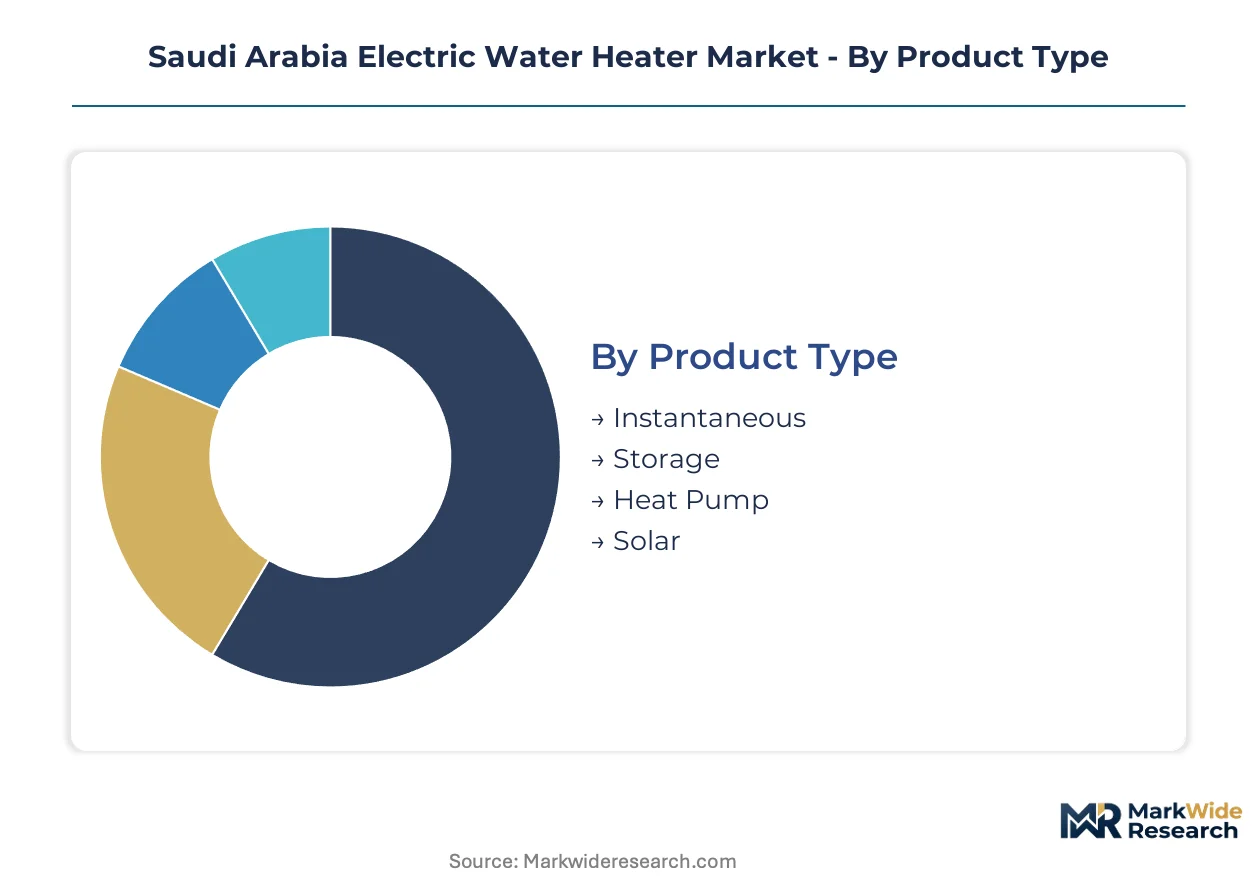
Procurement patterns across Saudi Arabia diverge sharply between price-conscious residential replacement cycles and specification-driven commercial developments. SASO certification tiers and Saudi Building Code enforcement create natural segmentation boundaries that filter supplier participation by compliance capability.
Product Type:
Domestic manufacturing concentrates on resistance-element systems for the mass market, while heat pump and solar-integrated units rely primarily on imported technology partnerships.
- Instantaneous:Tankless configurations deploy high-wattage elements for on-demand heating without storage losses. Riyadh apartment retrofits favor these units where mechanical space is constrained by older building footprints.
- Storage:Insulated tank systems with immersed resistance elements dominate installed base across Kingdom residential stock. Jeddah coastal humidity accelerates tank lining degradation, shortening replacement cycles versus inland provinces.
- Heat Pump:Compressor-based systems extract ambient thermal energy at three-to-four times resistance-element efficiency. Premium commercial projects in Riyadh's King Abdullah Financial District specify these for operational cost visibility.
- Solar:Electric-boosted solar thermal hybrids integrate photovoltaic or evacuated-tube preheating with backup element activation. NEOM and Red Sea Project developments trial these configurations for sustainability credentials.
Storage units command the established base. The steepest expansion runs through heat pump variants.
End User:
Cost tier separation defines procurement behavior, with hospitality and healthcare buyers operating on specification-driven capital budgets distinct from residential price sensitivity.
- Residential:Individual household procurement focuses on 30-100 liter wall-mounted units with lowest installed cost. SASO labeling compliance has become a minimum threshold after non-certified import filtering.
- Commercial:Office and retail facilities prioritize recovery rate and footprint efficiency over first cost. Riyadh and Jeddah municipal building codes mandate specific safety clearances that shape product selection.
- Industrial:Process hot water applications demand floor-standing configurations above 100 liters with corrosion-resistant linings. Eastern Province petrochemical adjacencies drive specification for heavy-duty element sheathing.
- Hospitality:Hotel developers specify tank-in-tank or modular systems for continuous occupancy duty cycles. Jeddah's coastal hotel construction pipeline pulls procurement toward high-recovery commercial grades.
Residential volume anchors manufacturer throughput. Hospitality procurement is climbing fastest as construction accelerates.
Capacity:
Volume concentration sits in mid-range segments compatible with standard Saudi residential electrical infrastructure, while grid constraints limit penetration of largest units.
- 10-30 Liters:Compact point-of-use units serve kitchen and single-fixture applications. Riyadh apartment stock with legacy 20-amp circuits restricts adoption of larger alternatives.
- 30-50 Liters:Standard family-sized configurations balance recovery time against panel load limits. Provincial city distribution networks move highest unit volumes in this bracket.
- 50-100 Liters:Extended-family and small commercial applications require dedicated circuits and upgraded panels. Jeddah villa developments increasingly specify this threshold for guest accommodation.
- Above 100 Liters:Industrial and commercial hospitality systems demand three-phase supply or heat pump technology. Grid capacity constraints in older Riyadh districts constrain residential penetration.
The 30-50 liter segment maintains volume leadership. Above-100-liter systems are gaining share fastest in commercial construction.
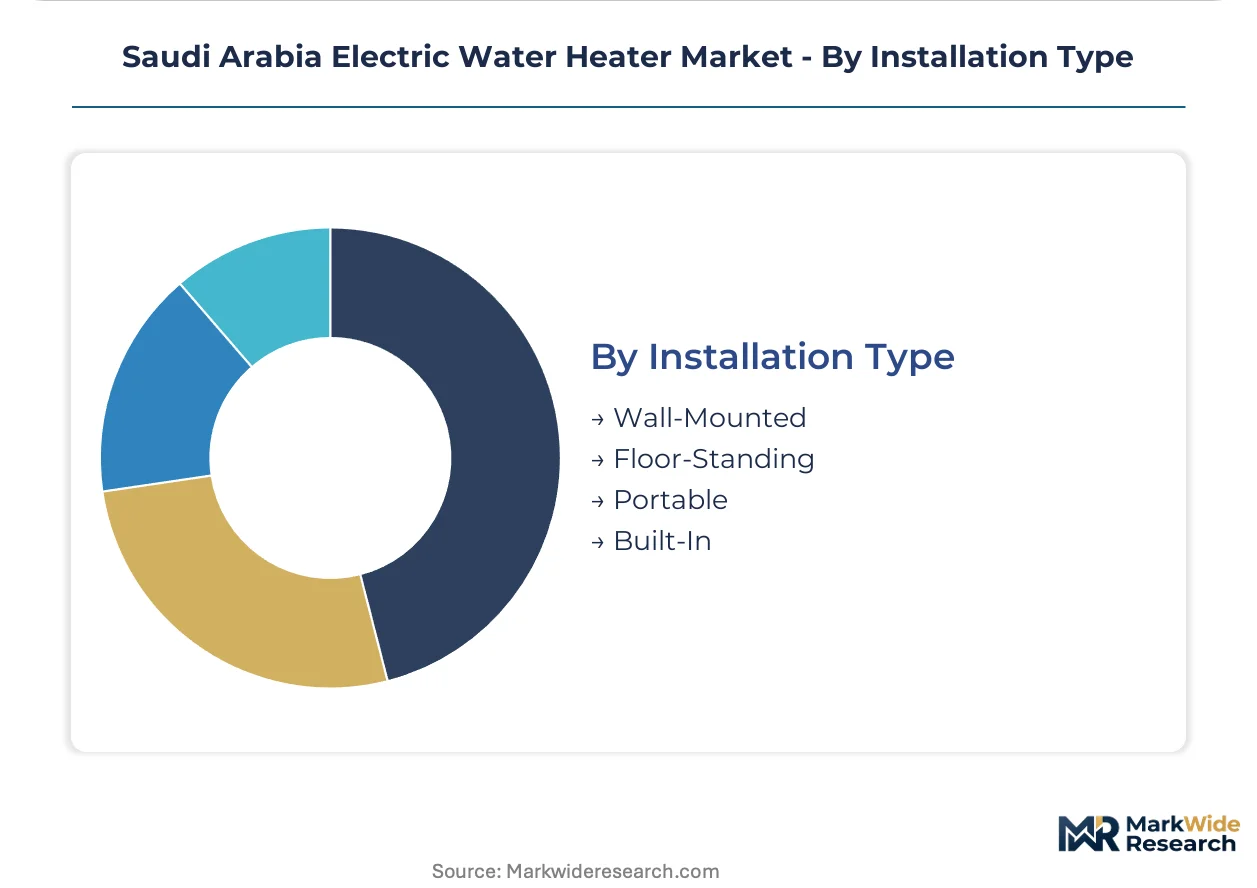
Installation Type:
Margin structure separates wall-mounted commodity units from specialized floor-standing and built-in configurations requiring custom fabrication.
- Wall-Mounted:Bracket-suspended tanks up to 100 liters dominate residential specification for space efficiency. Municipal building codes in Riyadh, Jeddah, and Dammam mandate seismic restraint hardware.
- Floor-Standing:Vertical cylinder configurations serve commercial and industrial above-100-liter requirements. Hospitality mechanical rooms in Jeddah's coastal corridor maximize density with these units.
- Portable:Plug-in temporary units address construction site and seasonal demand without permanent installation. Tabuk and Hail provincial markets exhibit sporadic demand from mobile workforce housing.
- Built-In:Cabinet-integrated or concealed systems align with premium villa aesthetic requirements. Saudi Ceramics and import partners serve this niche through custom fabrication channels.
Wall-mounted configurations hold the volume base. Built-in systems are expanding most quickly in premium residential developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply the bulk of resistance-element systems entering Saudi ports, while European heat pump technology partners serve premium commercial specifications in Riyadh and Jeddah.
Riyadh
Hotel construction in the King Abdullah Financial District drives specification of tank-in-tank systems for continuous occupancy cycles. SASO enforcement at dry port entry filters non-certified imports, clearing shelf space for compliant manufacturers. The municipal building code mandates seismic restraint hardware and dual-redundancy temperature cutoffs that shape product dimensioning.
Jeddah
Coastal humidity accelerates tank lining degradation, shortening replacement cycles versus inland provinces. The hospitality pipeline along the Red Sea coast pulls procurement toward high-recovery commercial grades with corrosion-resistant specifications. Municipal authorities enforce temperature safety limits and installation clearances that favor compact floor-standing configurations in constrained mechanical rooms.
Eastern Province
Petrochemical adjacencies drive specification for heavy-duty element sheathing in process hot water applications. SFDA oversight of materials in contact with potable water adds compliance layers for tank lining certification. Dammam municipal markets concentrate industrial procurement above 100 liters requiring three-phase supply infrastructure.
Western Region
NEOM and Red Sea Project developments trial solar-integrated electric-boosted configurations for sustainability credentials. Grid capacity constraints in older districts limit penetration of high-capacity residential models above 50 liters. Provincial distribution networks in Tabuk and Hail exhibit underdeveloped dealer infrastructure, creating first-mover opportunities for local manufacturing scale players.
Saudi Arabia Electric Water Heater Market Competitive Landscape
Player mix skews toward diversified appliance conglomerates with water heating divisions alongside specialized thermal equipment fabricators. Market structure consolidates around three tiers: multinational OEMs with tank-in-tank engineering capabilities, regional manufacturers leveraging local assembly scale, and import-dependent distributors serving price-sensitive replacement cycles. Strategic moves center on SASO certification pre-positioning and hospitality sector specification capture.
Among the multinational OEM tier, A.O. Smith and Ariston Thermo Group exemplify engineering-led positioning for high-occupancy commercial specifications. Saudi Ceramics occupies a position within the regional manufacturing tier, leveraging distribution depth across provincial cities. Bosch Thermotechnology and Haier represent diversified conglomerate approaches with water heating as a vertical within broader appliance portfolios.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Haier |
| A.O. Smith |
| Saudi Ceramics |
| Whirlpool Corporation |
| Ariston Thermo Group |
| Rinnai Corporation |
| Legrand |
| Rheem Manufacturing Company |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Jeddah port entry points compress working capital for distributors while concentrating pricing power with SASO-certified manufacturers who cleared compliance bottlenecks ahead of port filtering. This lead-time structure rewards pre-certified suppliers with shelf-space premiums and penalizes import-dependent distributors facing extended customs holds.
Pricing Analysis
Resistance-element systems trade at prior-generation price points while heat pump variants command next-generation premiums of forty-to-sixty percent above baseline. Three-tier pricing structure across premium, standard, and economy levels separates hospitality specification grades from residential replacement units, with SASO certification tier and recovery rate performance as the primary differentiation drivers. Cost compression in economy-tier units stems from copper and steel input volatility, while pricing pressure runs through standard segments as Chinese manufacturers push volume through Riyadh and Jeddah municipal markets. Residential buyers exhibit highest price sensitivity, prioritizing lowest installed cost for 30-50 liter wall-mounted units, whereas hospitality procurement teams prioritize operational cost visibility over first cost.
Supply Chain Analysis
China anchors resistance-element manufacturing and supplies the bulk of components entering Saudi ports, while Italy and Germany feed heat pump compressor technology for premium commercial specifications. Tank fabrication draws from copper heating elements, galvanized steel shells, and specialized tank linings certified for SFDA potable water contact. Single-source vulnerability concentrates in compressor technology for heat pump variants, where European suppliers control core intellectual property. Distribution runs through municipal dealer networks in Riyadh, Jeddah, and Dammam, with secondary provincial markets exhibiting underdeveloped infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against gas water heater alternatives that retain cost advantages in off-grid provincial settlements. LPG and natural gas systems threaten electric share in peripheral markets where grid infrastructure remains underdeveloped.
For Market Incumbents: Compound certification advantages by accelerating heat pump product line SASO pre-qualification ahead of efficiency tier revisions. Deepen backward integration into tank lining production to compress SFDA testing timelines and accelerate competitive response windows. Anchor channel control through direct service network partnerships that capture disintermediated hospitality maintenance contracts.
For New Entrants and Emerging Players: Anchor in provincial distribution gaps across Tabuk, Hail, and Abha where dealer infrastructure remains underdeveloped and local manufacturing scale players hold first-mover advantages. Target the 30-50 liter residential replacement segment with SASO-certified economy-tier units priced below incumbent landed costs. Pursue direct-to-developer contracting in NEOM and Red Sea Project developments where sustainability credentials open specification doors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SASO enforcement and Saudi Building Code decarbonization directives are erecting compliance barriers that favor pre-certified manufacturing scale. Acquisition targets should display heat pump technology partnerships and established provincial distribution networks. The signal to watch is municipal adoption of heat pump readiness mandates in commercial construction codes.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Positioning | Port-of-entry filtering clears shelf space for compliant manufacturers ahead of efficiency tier revisions. |
| Heat Pump Technology Partnership | European compressor suppliers control core IP for next-generation efficiency specifications in Riyadh commercial developments. |
| Provincial Distribution Expansion | Secondary markets in Tabuk and Hail exhibit underdeveloped dealer networks creating first-mover advantages. |
| Direct Service Network Integration | Hospitality procurement teams separate capital equipment from multi-year maintenance agreements in Riyadh hospital clusters. |
| Backward Integration into Tank Lining | SFDA material certification timelines compress competitive response windows for new product launches. |
Research Methodology
Operator-level perspectives from hotel procurement directors, municipal building code enforcement officers, SFDA compliance consultants, and electrical contractor networks anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with distribution channel managers and aftermarket service operators across Riyadh, Jeddah, and Dammam. Secondary validation drew from SASO technical regulation filings, Saudi Building Code amendments, customs import data at King Abdulaziz Port, and municipal construction permit databases. Bottom-up unit shipment estimates triangulated against top-down construction pipeline valuations across hospitality and healthcare verticals.
Sensitivity analysis tested forecast outputs against variable assumptions for copper price trajectories, grid infrastructure expansion timelines, and SASO efficiency tier implementation schedules across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, capacity tier, and installation configuration dimensions alongside geographic regulatory cluster differentiation. CAGRs were derived from fitted trend analysis of replacement cycle frequencies and new-installation pull-through from construction completions. Industry-specific inputs included hospitality occupancy rate assumptions and heat pump coefficient-of-performance improvement curves.
Material uncertainties — commodity price volatility, municipal code enforcement variance, and heat pump technician training pipeline output — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding SASO implementation consistency and construction pipeline completion rates. Recalibration cycles align with material shifts in efficiency regulation enforcement and hospitality sector capital expenditure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Digital Showers Market
Appliances
Microwave Oven Market
Appliances
Minibar Refrigerators Market
Appliances
Wall Oven Market
Appliances
Small Appliances Market
Appliances
Smart Massage Appliances Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Automatic Dishwasher Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Window Air Conditioners Market
Appliances
Dishwasher Market
Appliances
Commercial Microwave Ovens Market
Appliances
Laundry Kiosk Market
Appliances
Qatar Dishwashers Market
Appliances
Portable Mini Fridge Market
Appliances
North America Compact Dishwasher Market