
 Colombia Laundry Appliances Market | 2026-2036
Colombia Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Laundry Appliances Market Outlook
Aftermarket service revenue is reshaping profit pools as manufacturers pivot from one-time hardware margins to recurring maintenance and extended warranty income. Samsung leverages its national service network to capture recurring revenue streams across Colombian urban centers. Whirlpool Corporation sustains brand loyalty through authorized technician training programs tied to its direct sales channel. Industrias Haceb SA anchors its competitive stance with localized production that reduces import dependency and shortens delivery lead times.
Colombia laundry appliances encompass electromechanical systems designed for textile cleaning and drying, typically operating at 110V/60Hz with drum capacities ranging from 6 kg to 22 kg and energy efficiency ratings certified under national labeling schemes. These units serve residential households, commercial laundromats, and institutional facilities requiring hygienic fabric processing. Washing machines occupy the dominant revenue position due to universal household penetration, while smart appliances represent the fastest-expanding technology segment as Wi-Fi connectivity and load-sensing algorithms gain traction among Bogotá's tech-adopter demographic. Energy-efficient models command premium positioning aligned with UPME certification tiers, whereas conventional machines retain volume leadership in price-sensitive secondary cities.
Colombia's Superintendencia de Industria y Comercio enforces consumer protection standards affecting warranty terms and repair accessibility, while the Unidad de Planeación Minero Energética mandates energy efficiency labeling that directly shapes product development priorities. The Instituto Colombiano de Normas Técnicas y Certificación sets electrical safety benchmarks that determine market access for imported equipment. Stakeholders must monitor regulatory alignment between national efficiency mandates and evolving smart-grid integration requirements as distributed energy resources expand across Colombian utilities.
Market Dynamics
Colombia's mandatory UPME energy labeling regime is compressing product lifecycles and forcing manufacturers to abandon conventional motor architectures for inverter-driven systems ahead of consumer willingness to pay premiums.
Growth Catalysts
- UPME Tier Certification:The Unidad de Planeación Minero Energética's efficiency labeling tiers create visible differentiation at retail, pulling Bogotá apartment dwellers toward certified front-loading units.
- Andean Household Formation:Elevated electrification rates in Colombia's Andean region—particularly Antioquia and Cundinamarca departments—generate replacement demand for compact washing equipment.
- Inverter-Motor Technology:Variable-frequency drive systems reduce water and electricity consumption by 30-40% versus universal motors, aligning with Colombian utility rebate programs.
Market Restraints
- Import Dependency for Electronic Components:Power modules and control boards concentrate in East Asian supply chains, exposing Colombian assemblers to currency volatility and extended lead times.
- Coastal Electrification Gaps:Lower grid penetration in Chocó and La Guajira departments limits addressable market expansion despite latent household demand.
- Conventional Machine Price Anchoring:Legacy top-loading units with universal motors retain volume leadership in secondary cities, compressing margin realization for efficiency-compliant models.
Strategic Opportunities
- Amazonian Basin Penetration:Off-grid solar-compatible laundry systems represent untapped white space in Leticia and Puerto Nariño municipalities.
- Smart-Grid Integration:Wi-Fi-enabled load-sensing appliances can participate in demand-response programs as Colombian utilities deploy distributed energy resources.
- Institutional Channel Expansion:Hospital and hospitality procurement in Cali and Barranquilla favors hygienic-cycle certification, creating premium positioning for heat-pump dryer combinations.
Industry Challenges
- Authorized Technician Scarcity:Inverter-motor diagnostics and sealed-drum repair require specialized training that outpaces Colombia's vocational pipeline expansion.
- ICONTEC Certification Timelines:Electrical safety testing at the Instituto Colombiano de Normas Técnicas y Certificación creates six-to-nine month delays for new product introductions.
- Legacy Inventory Stranding:Conventional machine stockpiles in distributor warehouses face accelerated obsolescence as UPME labeling thresholds tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Laundry Appliances Market |
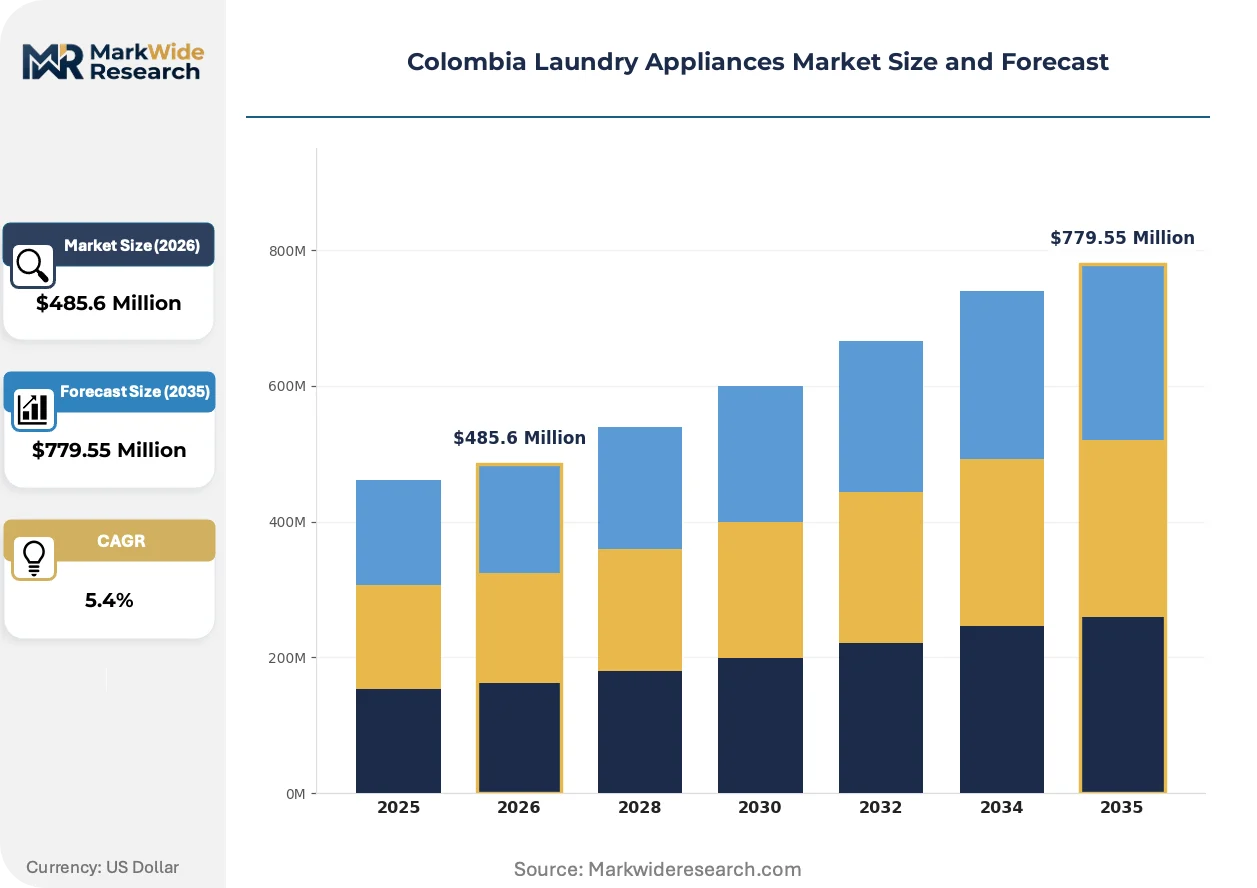
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $779.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Laundry Centers End User: Residential, Commercial, Institutional, Hospitality Technology: Smart Appliances, Energy-Efficient Models, Conventional Machines, Compact Solutions Distribution Channel: Online Retail, Offline Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Samsung, Whirlpool Corporation, Industrias Haceb SA, Panasonic Corporation, BSH Hausgerate GmbH, Mabe Colombia, Electrolux, Arcelik AS, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Laundry Appliances Market Strategic Shifts
Hardware-software convergence is redefining competitive advantage in Colombian laundry equipment, with connectivity features and predictive maintenance capabilities displacing pure mechanical reliability as the primary purchase determinant.
Inverter-motor technology is migrating from premium positioning to mid-tier SKUs as Samsung and Whirlpool localize production. Bogotá's tech-adopter demographic—concentrated in Chapinero and El Poblado districts—now expects load-sensing algorithms and cycle optimization via smartphone interfaces. The technology is migrating from early-adopter niches toward mass-market penetration, compressing replacement cycles for machines lacking smart functionality.
The Unidad de Planeación Miner Energética's 2024 labeling revision tightened minimum efficiency thresholds for drum capacities above 12 kg. Commercial laundromat operators in Medellín face mandatory equipment turnover by 2027, accelerating capital deployment toward heat-pump dryers and ozone-based sanitization systems. The regulation most affects institutional buyers, who are consolidating procurement through leasing arrangements to distribute compliance costs.
Urban Colombian households are compressing replacement cycles from twelve-year averages toward seven-to-eight year intervals. Financing penetration through retailer credit programs—particularly Alkosto and Falabella channels—enables earlier upgrades despite stagnant real wage growth. This behavioral shift concentrates in Bogotá and Medellín metropolitan zones, where apartment density and space constraints favor compact, stackable configurations over traditional top-loading formats.
Colombia Laundry Appliances Market Segmentation
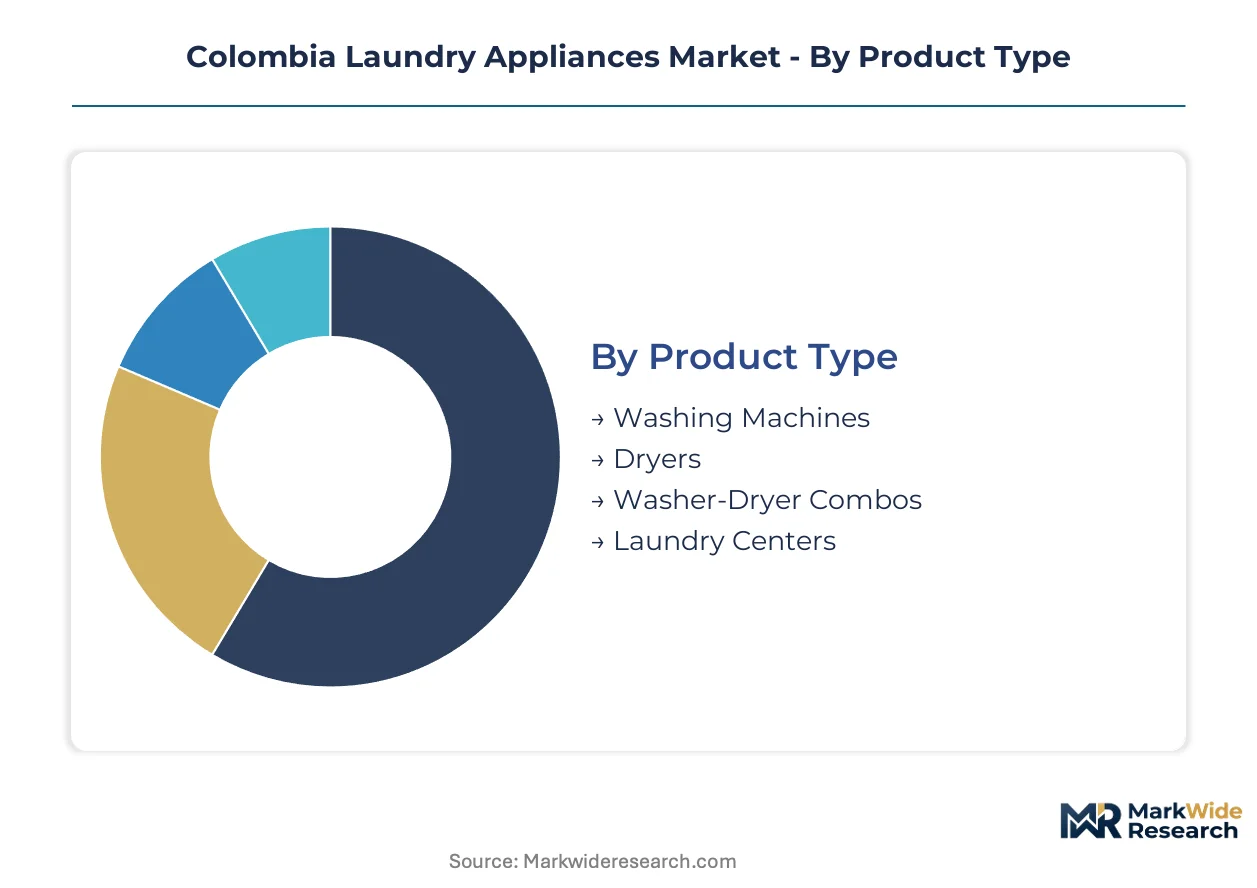
Segmentation reveals divergent replacement rhythms across Colombian laundry equipment, with technology tiers cycling every seven years while conventional units stretch toward twelve-year lifespans. Understanding these temporal patterns enables inventory positioning and margin capture across Bogotá's apartment corridors and Medellín's commercial corridors.
Product Type:
Washing machines turn over fastest in urban Colombian households, while laundry centers and combos lag in replacement velocity due to higher capital commitment and installation complexity.
- Washing Machines:Electromechanical units with drum capacities from 6 kg to 22 kg dominate residential penetration across Colombia's Andean region. Bogotá apartment dwellers in Chapinero and El Poblado districts drive replacement demand for compact front-loading configurations as space constraints intensify.
- Dryers:Vented and heat-pump systems process textile drying at 110V/60Hz, with heat-pump variants gaining traction among UPME-conscious consumers. Medellín's commercial laundromat operators favor heat-pump combinations for reduced utility consumption under municipal rebate programs.
- Washer-Dryer Combos:Integrated single-unit systems serve space-constrained urban households where separate appliances prove impractical.
- Laundry Centers:Stacked vertical configurations address multi-family housing and institutional procurement in Cali and Barranquilla hospitality corridors.
Washing machines anchor the volume base while heat-pump dryers gain share at the steepest rate.
End User:
Cost tier differentiation separates premium institutional procurement from price-sensitive residential channels, with financing penetration enabling earlier upgrades in metropolitan zones.
- Residential:Individual households across Colombia's electrified Andean departments constitute the primary demand pool. Financing programs through Alkosto and Falabella channels compress replacement cycles from twelve-year averages toward seven-to-eight year intervals despite stagnant wage growth.
- Commercial:Laundromat operators and textile service providers in Medellín face mandatory equipment turnover by 2027 under tightened UPME labeling thresholds. Leasing arrangements distribute compliance costs across capital-constrained operators.
- Institutional:Hospital and healthcare procurement prioritizes hygienic-cycle certification for infection control.
- Hospitality:Hotel and lodging operators in Cartagena and Santa Marta coastal zones favor durable configurations with rapid cycle throughput.
Residential demand anchors the volume base while commercial replacement mandates drive the steepest near-term expansion trajectory.
Technology:
Application context determines technology adoption velocity, with grid-connected urban households accessing smart features unavailable to off-grid Amazonian settlements.
- Smart Appliances:Wi-Fi-enabled units with load-sensing algorithms and smartphone cycle optimization serve Bogotá's tech-adopter demographic. Chapinero and El Poblado districts expect predictive maintenance capabilities and utility demand-response participation as Colombian distributed energy resources expand.
- Energy-Efficient Models:Inverter-motor systems with variable-frequency drives reduce water and electricity consumption versus universal motor architectures. UPME certification tiers create visible retail differentiation pulling consumers toward certified front-loading units.
- Conventional Machines:Legacy top-loading units with universal motors retain volume leadership in price-sensitive secondary cities.
- Compact Solutions:Reduced-drum configurations address space constraints in dense urban apartment stock.
Conventional machines anchor the volume base while smart appliances climb the fastest as connectivity features displace pure mechanical reliability in purchase decisions.
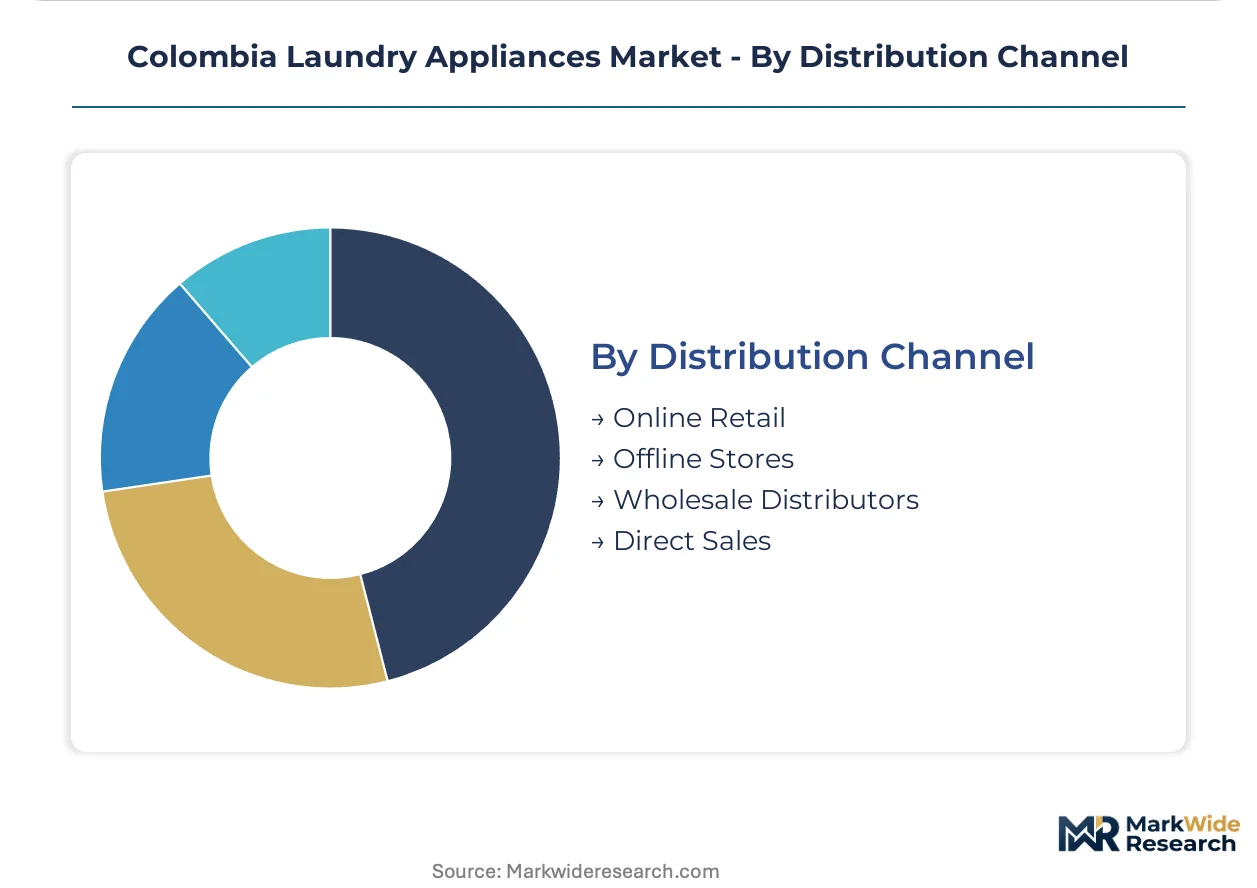
Distribution Channel:
Customer type fragmentation separates credit-enabled retail purchasers from bulk institutional procurement, with service attachment rates varying dramatically by channel.
- Online Retail:Digital platforms enable specification comparison and financing pre-approval for metropolitan consumers. Delivery logistics concentrate in Bogotá and Medellín metropolitan zones with established last-mile infrastructure.
- Offline Stores:Physical retail through Alkosto and Falabella channels provides tactile evaluation and immediate credit decisioning. Authorized technician availability varies by municipality, affecting post-sale service attachment.
- Wholesale Distributors:Bulk procurement channels serve commercial and institutional buyers with volume pricing and extended payment terms.
- Direct Sales:Manufacturer-controlled channels enable warranty bundling and maintenance contract attachment at point of sale.
Offline stores anchor the volume base while online retail expands most quickly as digital financing penetration deepens in urban Colombian households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Colombian sub-regions, with Andean metropolitan buyers absorbing inverter-motor premiums while Caribbean and Pacific coastal markets resist efficiency upgrades above conventional price anchors.
Andean Region
Antioquia and Cundinamarca departments generate the steepest replacement velocity as Bogotá and Medellín apartment formation outpaces national averages. The Unidad de Planeación Minero Energética's tiered labeling pulls consumers toward certified front-loading configurations in Chapinero and El Poblado districts. Heat-pump dryer penetration concentrates in Medellín's commercial laundromat corridors under municipal utility rebate programs.
Caribbean Region
Cartagena and Barranquilla hospitality operators favor rapid-cycle throughput over energy efficiency, delaying inverter-motor adoption. The Instituto Colombiano de Normas Técnicas y Certificación's electrical safety testing creates six-to-nine month delays for new product introductions in coastal distribution channels. Legacy top-loading inventory dominates warehouse stockpiles in Santa Marta procurement zones.
Pacific Region
Chocó department's electrification gaps constrain addressable market expansion despite latent household demand for basic washing equipment. Off-grid settlements in Nuquí and Bahía Solano municipalities remain unreachable by conventional 110V distribution infrastructure. Solar-compatible laundry systems represent untapped white space for specialized equipment suppliers.
Amazonian Region
Leticia and Puerto Nariño municipalities operate beyond national grid coverage, excluding standard appliance penetration. Battery-inverter washing configurations with DC-native architectures could unlock isolated settlements dependent on distributed generation. The region currently contributes negligible revenue to national manufacturer sales.
Orinoquía Region
Villavicencio and Yopal urban centers exhibit intermediate price sensitivity between Andean premium absorption and coastal resistance. Agricultural household income volatility compresses financing penetration for mid-tier SKUs. Regional distributors maintain mixed inventory balancing conventional volume leadership against efficiency-compliant margin compression.
Colombia Laundry Appliances Market Competitive Environment
Multinational electronics conglomerates and regional manufacturing specialists split the market along technology-tier lines, with inverter-motor certification separating premium positioning from conventional volume play. The vendor base concentrates among three strategic archetypes: global brand licensors with national service networks, localized assemblers with import-substitution cost structures, and regional specialists with channel-specific financing arrangements. Dominant competitive moves include authorized technician training programs tied to direct sales channels and backward integration into motor and control module sourcing.
Within the multinational tier, Samsung and Whirlpool Corporation exemplify service-network differentiation strategies, while Industrias Haceb SA anchors the localized production archetype with captive assembly reducing import dependency. These three companies occupy positions spanning premium connectivity-enabled configurations through mid-tier efficiency-certified SKUs, with each representing distinct approaches to UPME compliance timing and technician certification depth.
| Leading Market Players |
|---|
| Samsung |
| Whirlpool Corporation |
| Industrias Haceb SA |
| Panasonic Corporation |
| BSH Hausgerate GmbH |
| Mabe Colombia |
| Electrolux |
| Arcelik AS |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Import dependency for power modules and control boards determines both pricing tier spreads and supply chain shape in Colombian laundry equipment, compressing margins for efficiency-compliant models while extending lead times for inverter-motor SKUs.
Pricing Analysis
Extended warranty and maintenance contract tiers drive lifetime value capture for authorized service networks. Three-tier pricing structure across premium smart-connected, standard inverter-certified, and economy conventional levels separates Bogotá apartment buyers from coastal price-sensitive households. Pricing pressure stems from UPME labeling thresholds forcing premature obsolescence of legacy universal-motor inventory. Commercial laundromat operators in Medellín exhibit lowest price sensitivity due to municipal rebate absorption, while secondary city residential buyers anchor to conventional machine price points.
Supply Chain Analysis
Supplier-financing arrangements through East Asian component vendors extend payment terms for Colombian assemblers facing peso volatility. Manufacturing concentration in China, South Korea, and Vietnam feeds power electronics and sealed-drum assemblies to regional plants. Raw material dependencies span copper windings, rare-earth magnets, and ABS polymer housings. Single-source vulnerability for variable-frequency drive modules threatens production continuity. Distribution runs through authorized retail channels in Bogotá and Medellín with direct-sales service attachment for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
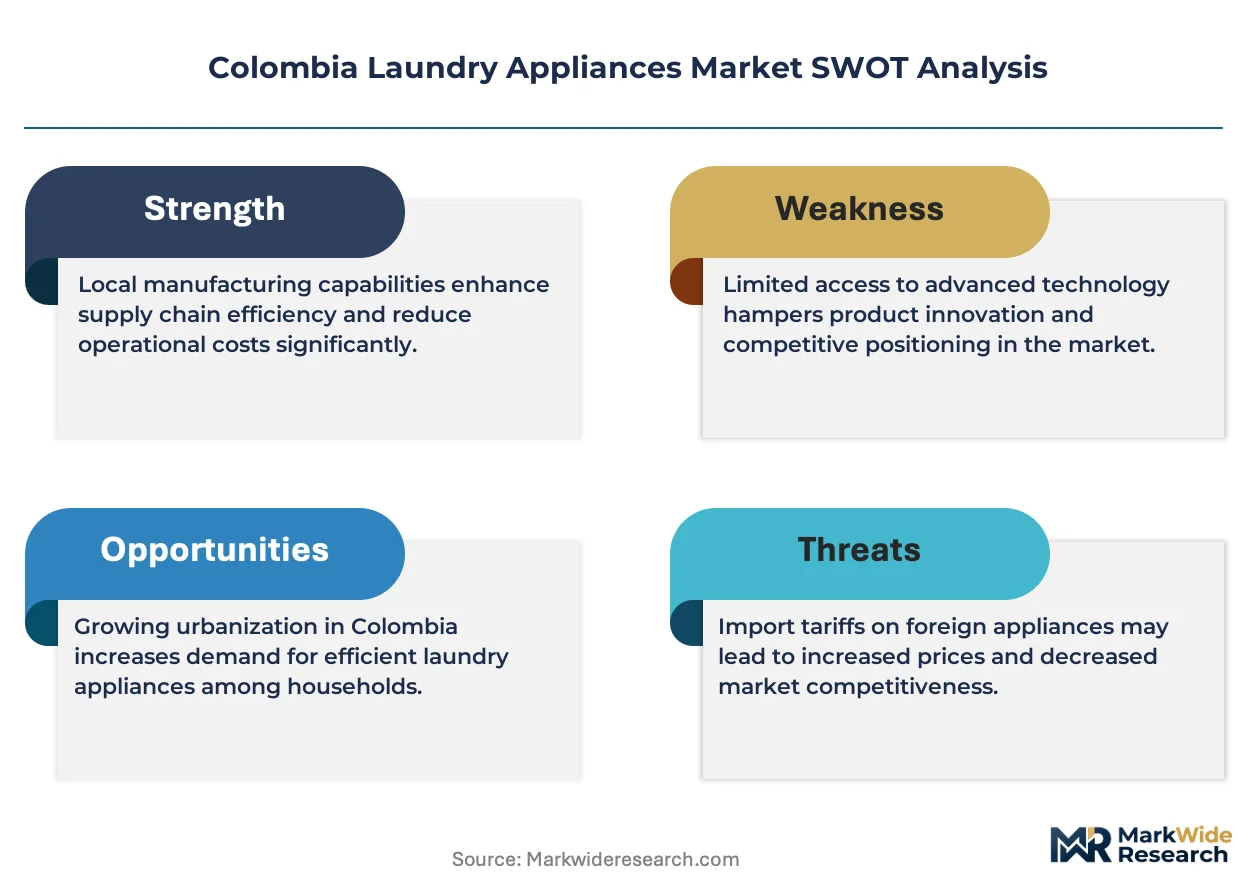
Colombia's laundry equipment market operates as a defensive-moat story where regulatory certification entrenchment and authorized technician network effects protect incumbent positions against price-only competition.
For Market Incumbents: Pre-empt inverter-motor certification gaps by accelerating ICONTEC electrical safety testing timelines before 2024 UPME labeling revisions tighten. Deepen backward integration into motor winding and control module sourcing to reduce East Asian import exposure. Defensive consolidation should target regional distributors with stranded conventional inventory to capture replacement cycle compression in Andean metropolitan zones. For New Entrants and Emerging Players: Pursue off-grid solar-compatible laundry configurations in Amazonian municipalities beyond national grid coverage. Target battery-inverter washing systems with DC-native architectures for Leticia and Puerto Nariño settlements. Direct-to-institutional sales through leasing arrangements for hospital and hospitality procurement in Cali and Barranquilla bypasses established retail channel barriers. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically-integrated assemblers with captive production and national service networks. Long-term viability over the next decade hinges on UPME compliance timing and technician certification depth. Acquisition targets should demonstrate localized assembly capacity and authorized training program scale. The signal to watch is municipal utility rebate program expansion driving heat-pump dryer penetration in commercial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter-Motor Localization | Reduces import dependency and shortens delivery lead times for UPME-certified SKUs. |
| Authorized Technician Network Expansion | Captures recurring aftermarket revenue through predictive maintenance and sealed-drum repair capabilities. |
| Smart-Grid Integration Partnership | Positions Wi-Fi-enabled units for Colombian utility demand-response programs as distributed energy resources expand. |
| Institutional Leasing Program Launch | Distributes capital expenditure burden for commercial laundromat operators facing mandatory equipment turnover. |
| Solar-Compatible Product Development | Unlocks Amazonian basin penetration where grid infrastructure remains absent. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews encompassed appliance manufacturing executives, authorized service network managers, retail category buyers at Alkosto and Falabella channels, and commercial laundromat operators in Medellín and Bogotá. Secondary sources included UPME energy labeling registries, ICONTEC electrical safety certification records, Colombian customs import data, and utility rebate program disclosures. Bottom-up unit shipment estimates triangulated against top-down household formation and replacement cycle models.
Forecast inputs span product type segmentation, technology tier migration curves, end-user channel mix, and regional electrification penetration across Colombian departments. The analytical framework projects volume and value trajectories across the modeling period through CAGR derivation from replacement cycle compression and efficiency regulation compliance timing. Industry-specific inputs incorporate UPME labeling threshold revisions and municipal utility rebate program expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in peso exchange rates, household credit availability, or Andean region electrification investment would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and supply chain continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Portable Washing Machines Market
Appliances
Large Cooking Appliance Market
Appliances
Garments Steamer Market
Appliances
Personal Care Appliances Market
Appliances
Microwave Market
Appliances
India Washing Machine Market
Appliances
Dishwasher Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Cooler Connected to the Mains Market
Appliances
Clothing Iron Market
Appliances
Egypt Microwave Ovens Market
Appliances
Qatar Microwave Ovens Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Electric Dryers Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Japan Laundry Appliances Market