
 Shock Test Machines Market | 2026-2036
Shock Test Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Test Machines Market Analytics
CE marking under the EU Machinery Directive is recalibrating the cost-of-entry calculus for European shock test equipment suppliers. MTS Systems Corporation leverages its servo-hydraulic platform dominance to anchor premium positioning in aerospace validation. Lansmont Corporation specializes in transportation shock simulation, occupying a defensible niche in packaged goods testing. Brüel & Kjær differentiates through integrated vibration-shock systems, extending its acoustic expertise into multi-physics environments.
Shock test machines apply controlled mechanical impulses—typically 50 to 50,000 g peak acceleration—to evaluate structural integrity, solder joint reliability, and component survivability under impact conditions. Electromechanical systems now lead unit shipments for electronics applications below 5,000 g, while hydraulic platforms retain dominance in military and aerospace segments requiring sustained high-energy pulses. Servo-controlled architectures represent the fastest-expanding technology category as manufacturers demand programmable waveform fidelity for electric vehicle battery abuse testing.
FAA airworthiness directives, MIL-STD-810H military environmental test standards, and EU CE marking requirements collectively shape product roadmaps and procurement specifications across defense and commercial aviation. China's GB standards and NMPA medical device regulations add parallel compliance layers for suppliers serving domestic electronics and healthcare equipment markets. Stakeholders must monitor evolving battery safety mandates from NHTSA and China's MIIT, as these will dictate next-generation shock pulse profiles and data acquisition requirements for energy storage validation.
Market Dynamics
Servo-controlled electromechanical architectures are compressing test cycle times for electric vehicle battery validation, forcing incumbent hydraulic platform suppliers to recalibrate their aerospace and defense positioning.
Growth Catalysts
- MIL-STD-810H Revision:Updated military environmental test standards mandate programmable shock pulse profiles for defense electronics qualification, expanding procurement volumes from US defense contractors.
- EV Battery Abuse Testing:NHTSA and China's MIIT battery safety mandates require controlled mechanical impact validation for lithium-ion cell architectures, driving test lab capacity expansion.
- CE Marking Intensification:EU Machinery Directive mechanical safety requirements are recalibrating equipment specifications for European suppliers, creating replacement demand for legacy pneumatic systems.
Market Restraints
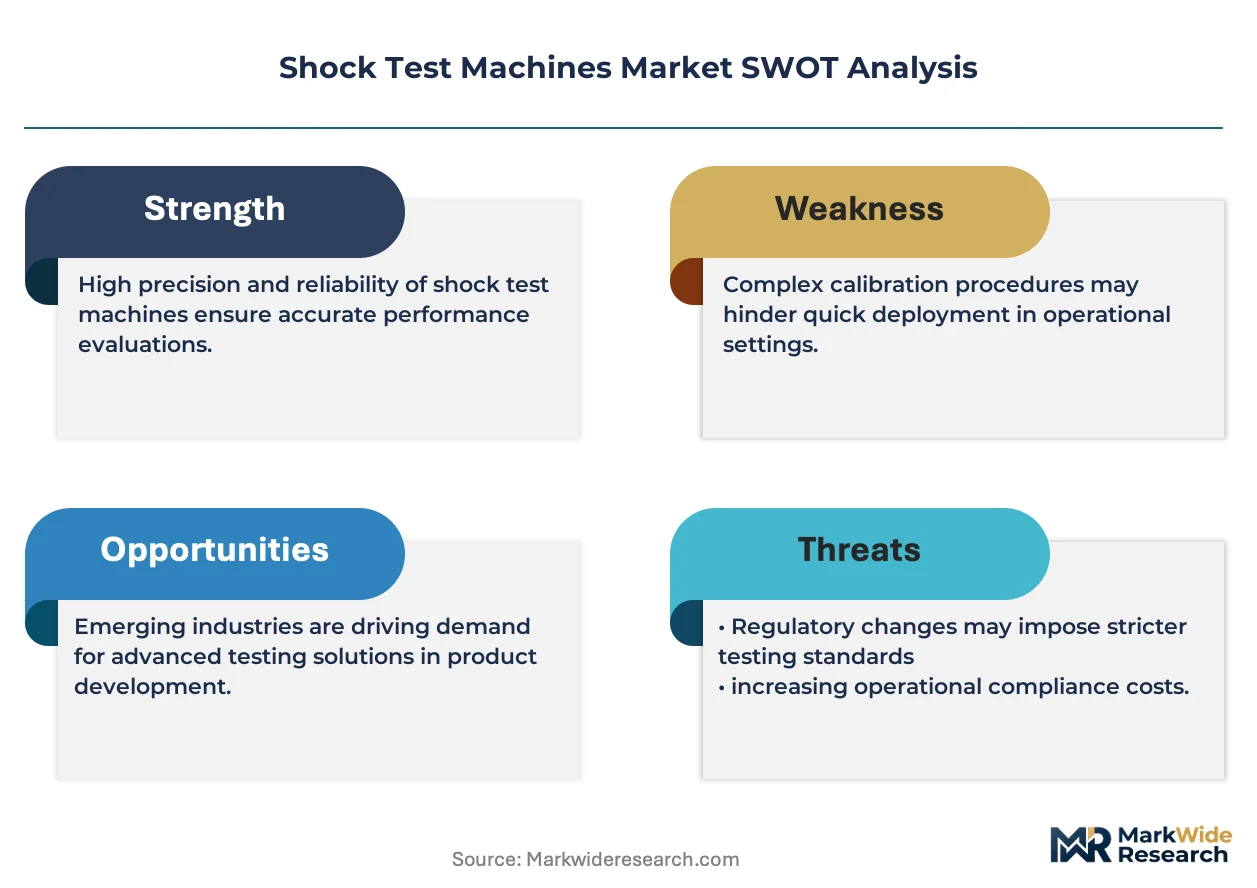
- High-Precision Sensor Costs:Piezoelectric accelerometers and laser Doppler vibrometers for accurate g-force measurement face supply concentration from German and Japanese component specialists, inflating bill-of-material costs.
- Technical Ceiling in Energy Density:Electromechanical systems face fundamental limitations above 5,000 g peak acceleration, preserving hydraulic platform dominance in military segments despite maintenance overhead.
- Regulatory Fragmentation:Parallel compliance requirements from FAA airworthiness directives, EU CE marking, and China's GB standards force redundant certification investments for multinational suppliers.
Strategic Opportunities
- Medical Device Validation:China's NMPA regulations for implantable electronics and portable diagnostic equipment create untapped demand for mid-range shock test capacity in domestic manufacturing clusters.
- Integrated Vibration-Shock Systems:Convergence of multi-axis vibration platforms with programmable shock modules enables single-setup qualification for aerospace avionics, reducing test lab footprint requirements.
- Cloud-Connected Data Acquisition:Remote monitoring architectures allow test service providers to offer waveform validation as a subscription service, opening new channel economics for smaller electronics manufacturers.
Industry Challenges
- Embedded Firmware Expertise Gap:Servo-controlled architectures require motion control programmers capable of real-time waveform synthesis, a skill set concentrated among automotive and robotics talent pools.
- Calibration Certificate Backlogs:ISO 17025-accredited calibration laboratories face queue times exceeding eight weeks for high-g accelerometer verification, compressing equipment uptime for commercial test houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Test Machines Market |
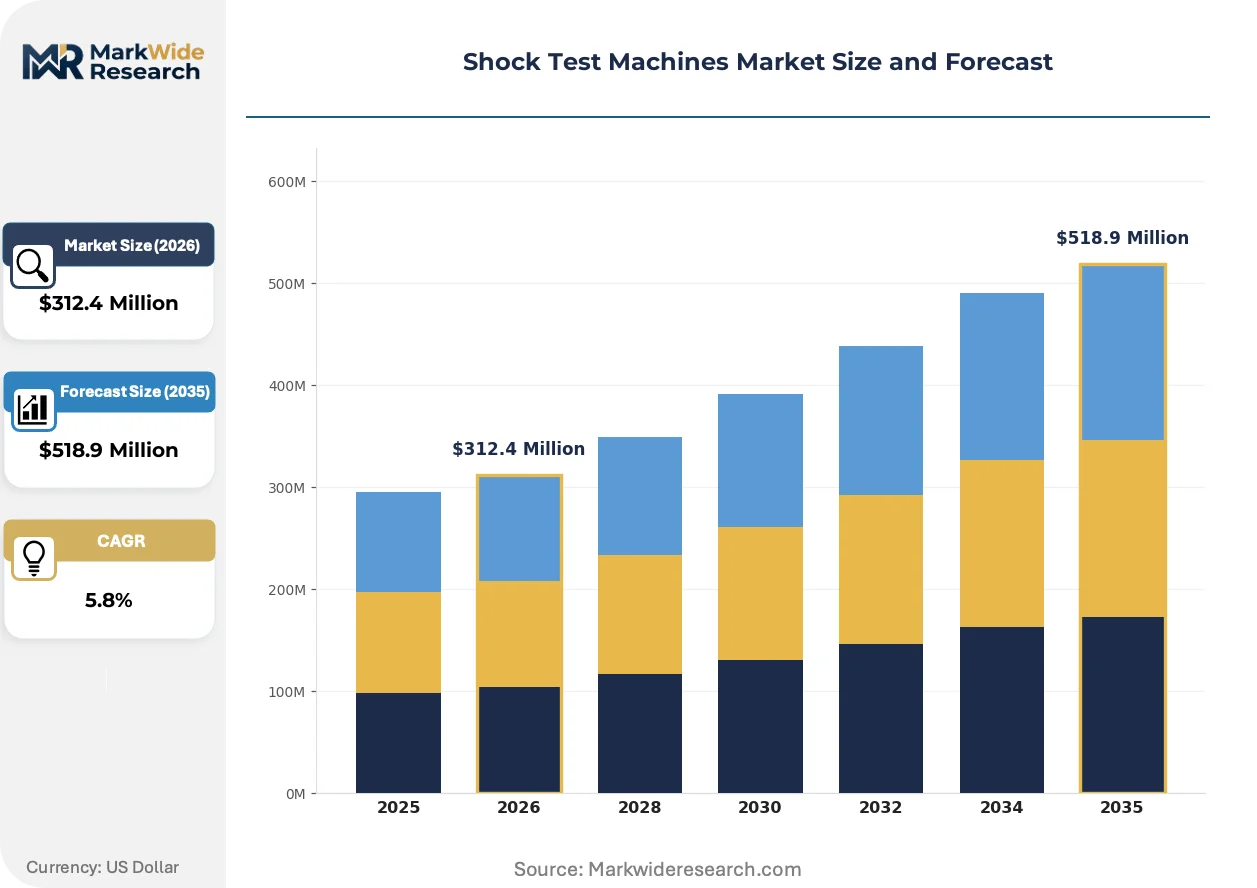
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Servo Controlled Application: Aerospace, Automotive, Electronics, Military End User: Manufacturers, Research Institutions, Quality Control Labs, Government Agencies Technology: Dynamic, Static, Shock Simulators, Impact Testing |
| Companies Covered | MTS Systems Corporation, Instron, Lansmont Corporation, LAB Equipment Inc, Thermotron Industries, Kistler Group, Dongling Technologies, Brüel & Kjær, Team Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Test Machines Market Evolving Landscape
Programmable waveform fidelity is displacing fixed-pulse legacy systems across transportation and energy storage validation, while regulatory bodies on three continents simultaneously tighten mechanical safety documentation requirements.
Digital twin simulation is integrating with physical shock test platforms to reduce prototype iteration cycles for electric vehicle battery pack designs. Automotive OEMs in Germany and China are adopting hybrid virtual-physical validation workflows that compress development timelines by enabling pre-test failure mode prediction. This convergence is integrating finite element analysis outputs directly into servo-hydraulic control loops, collapsing the traditional separation between simulation and physical testing phases.
EU CE marking under the Machinery Directive is mandating documented risk assessments for mechanical test equipment sold into European manufacturing facilities. Industrial consequence includes mandatory third-party conformity assessment for systems above specified energy thresholds, adding certification layers for US and Asian exporters. German automotive suppliers and French aerospace subcontractors are most affected, responding by embedding safety-rated programmable logic controllers and redundant emergency stop architectures into new platform designs.
Test service outsourcing is consolidating procurement among tier-one electronics manufacturers who previously maintained captive shock test capabilities. Contract validation laboratories in the United States and China are displacing in-house equipment ownership through fixed-price per-test contracting, transferring capital burden to specialized service providers. This pattern is most visible in consumer electronics supply chains, where Taiwanese and South Korean contract manufacturers now specify third-party shock certification as a supplier qualification requirement.
Shock Test Machines Market Segmentation
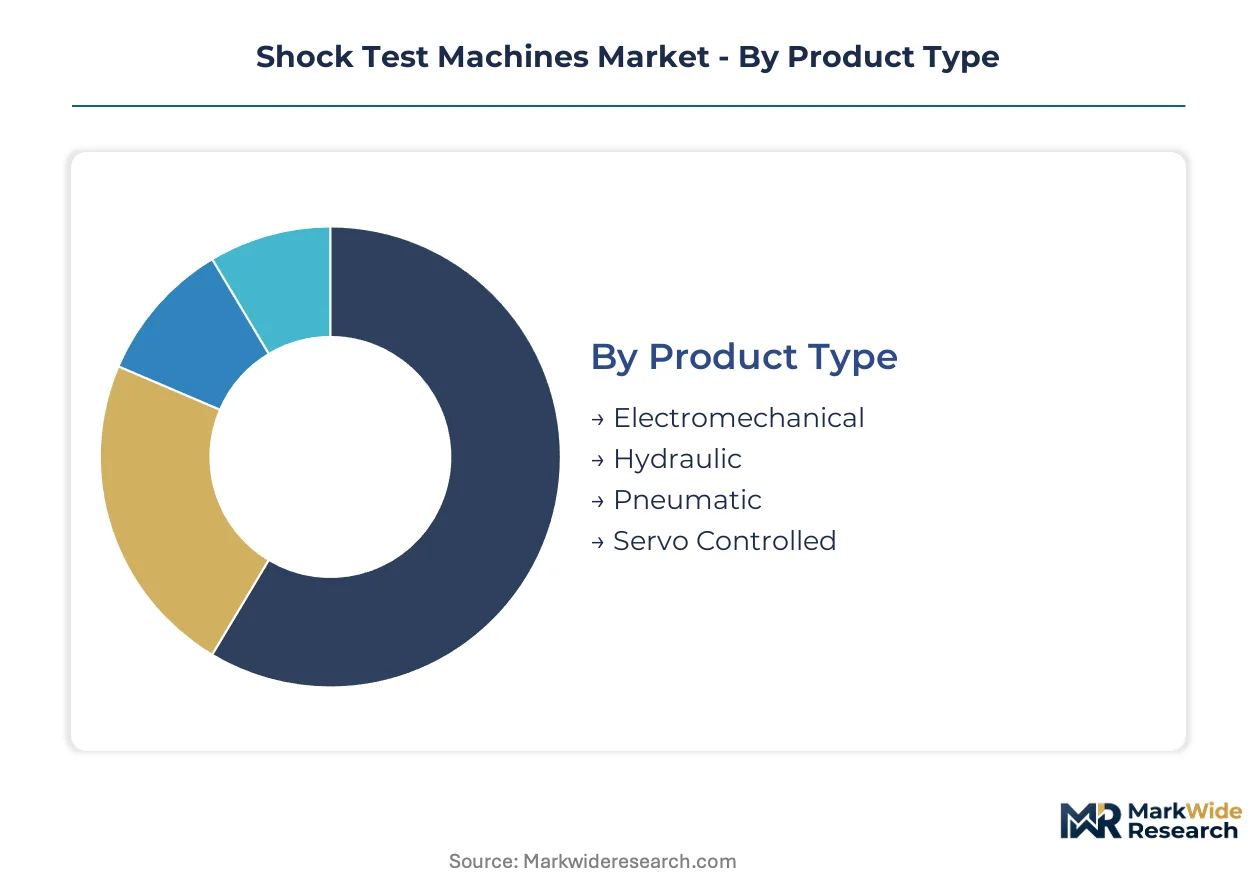
Shock test machine procurement varies sharply by buyer technical requirements and compliance burden. Electromechanical systems serve high-volume electronics manufacturers seeking programmable precision, while hydraulic platforms dominate defense contractors facing MIL-STD-810H energy density mandates. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology roadmaps capture investment.
Product Type:
Cost tier separates buyers most cleanly in this category, with capital intensity and maintenance burden driving divergent procurement patterns.
- Electromechanical:Linear motor and ball-screw architectures generate precisely controlled acceleration profiles up to 5,000 g. Electronics manufacturers in Germany and China favor these systems for consumer device and EV battery validation where waveform programmability outweighs peak energy requirements.
- Hydraulic:Servo-valve controlled fluid power delivers sustained high-energy pulses exceeding 20,000 g for military airframe and aerospace component testing. US defense contractors and French aerospace suppliers accept higher maintenance overhead to meet MIL-STD-810H shock severity specifications.
- Pneumatic:Compressed gas systems offer lower capital entry points for basic transportation shock simulation. Packaged goods manufacturers employ these for ISTA certification with limited waveform complexity needs.
- Servo Controlled:Closed-loop motion control architectures enable real-time pulse shaping for battery abuse testing protocols. NHTSA and China's MIIT safety mandates are accelerating adoption among automotive validation labs.
Electromechanical systems lead volumes today; servo-controlled architectures are gaining share fastest.
Application:
Regulatory stringency and failure consequence severity shape demand concentration across end-use sectors.
- Aerospace:FAA airworthiness directives and EASA certification requirements mandate shock qualification for avionics, flight control systems, and structural components. German and French suppliers face EU Machinery Directive documentation burdens for equipment sold into European manufacturing facilities.
- Automotive:Electric vehicle battery pack validation now dominates capital allocation, with NHTSA mechanical abuse testing and China's MIIT safety standards requiring controlled impact simulation. OEMs in Germany and China are expanding test lab capacity fastest.
- Electronics:Consumer device and semiconductor packaging testing concentrates in Taiwan and South Korean contract manufacturing clusters. ISTA and JEDEC standards govern solder joint reliability and component survivability validation.
- Military:MIL-STD-810H revision compliance drives procurement from US defense primes and their supply chains. Sustained high-g pulse requirements preserve hydraulic platform dominance despite longer test cycle times.
Electronics applications dominate unit shipments; automotive battery testing commands the steepest expansion trajectory.
End User:
Volume scale and technical sophistication divide procurement patterns across customer types.
- Manufacturers:Captive test capabilities at automotive OEMs and aerospace primes are contracting as outsourcing economics improve. German automotive suppliers now specify third-party certification for tier-two component vendors.
- Research Institutions:University and national laboratory demand concentrates on programmable architectures supporting fundamental materials research. China's domestic research funding is expanding test equipment procurement for GB standards development.
- Quality Control Labs:Commercial validation service providers in the United States and China are displacing in-house equipment ownership through fixed-price per-test contracting. Consumer electronics supply chains drive this consolidation pattern.
- Government Agencies:Defense and space agency procurement follows federal acquisition regulations with extended qualification timelines. US military environmental test standards mandate specific pulse profile capabilities.
Quality control labs lead volume growth today; government agency procurement is concentrating on servo-controlled platforms fastest.
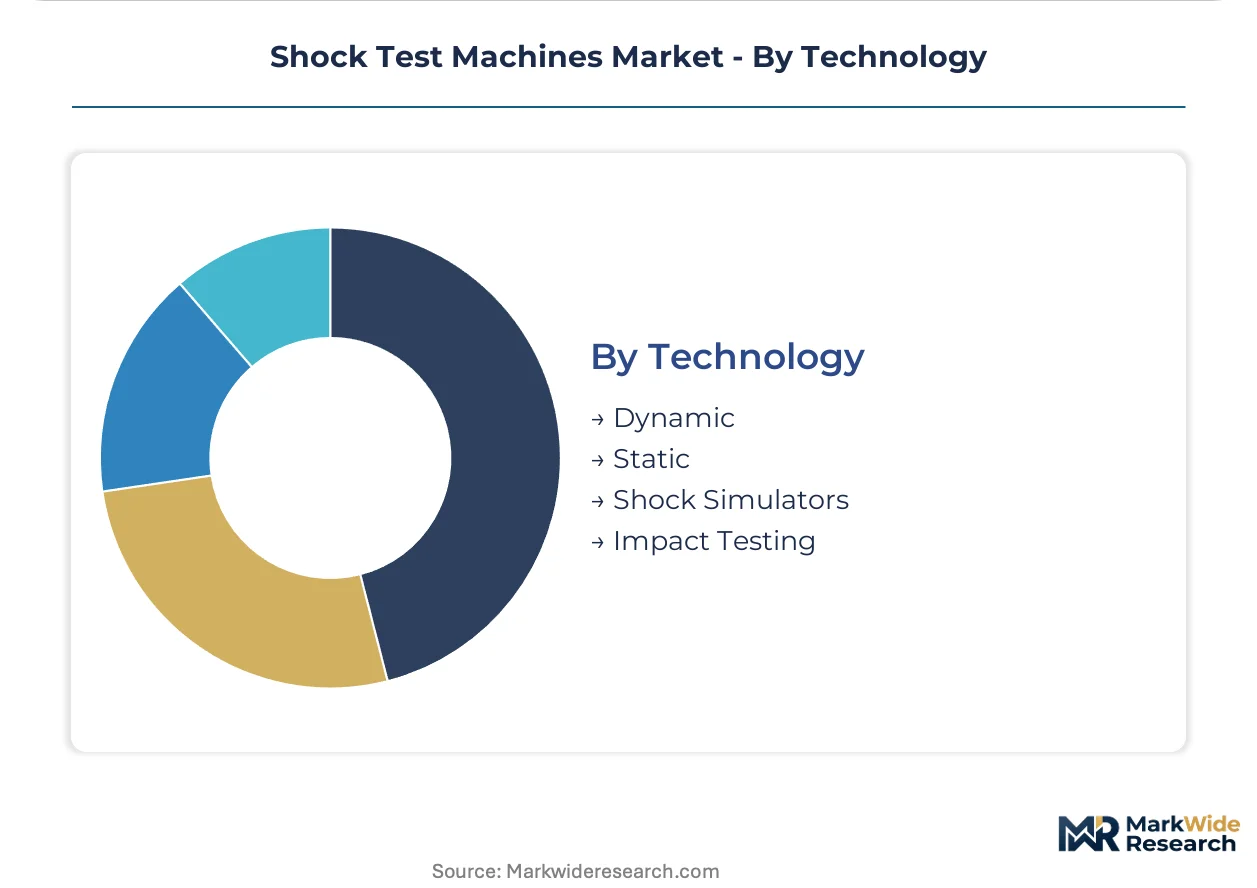
Technology:
Maturity and integration complexity separate legacy approaches from emerging system architectures.
- Dynamic:Time-varying force application with real-time feedback control enables complex waveform synthesis. Aerospace and automotive battery testing requirements are accelerating displacement of fixed-pulse legacy systems.
- Static:Single-impulse drop testers and fixed-height impact systems serve basic transportation packaging validation. Cost-sensitive manufacturers in emerging markets retain these for ISTA certification compliance.
- Shock Simulators:Reproduces field-measured shock environments through programmable excitation. Defense electronics qualification increasingly requires traceability to measured operational environments.
- Impact Testing:High-velocity projectile and pendulum systems evaluate material fracture and structural failure modes. Metals and composites suppliers employ these for fundamental characterization outside regulatory compliance workflows.
Dynamic systems lead commercial investment today; shock simulators are climbing the fastest as traceability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The shock test machines industry traces its commercial origins to post-war aerospace development in the United States and Germany, where military environmental test standards first codified controlled mechanical impulse validation as a procurement requirement.
United States
Defense electronics qualification and FAA airworthiness certification drive sustained demand from aerospace primes and their supply chains. MIL-STD-810H revisions mandate programmable shock pulse profiles for military hardware acceptance. Test service providers in California and Texas are expanding commercial validation capacity to serve outsourced battery abuse testing contracts from automotive OEMs.
Germany
Automotive battery validation and industrial machinery safety compliance concentrate procurement among domestic OEMs and tier-one suppliers. EU CE marking under the Machinery Directive imposes third-party conformity assessment for high-energy test systems. Industrial clusters in Bavaria and Baden-Württemberg host expanding validation laboratories serving electric vehicle development programs.
China
Domestic electric vehicle production and NMPA medical device regulations are accelerating test equipment procurement across manufacturing hubs. MIIT battery safety mandates require controlled mechanical impact validation for lithium-ion cell architectures. Validation facilities in the Yangtze River Delta and Pearl River Delta are adding servo-controlled capacity to meet NHTSA-equivalent abuse testing protocols.
Japan
Semiconductor packaging reliability and automotive electronics validation sustain demand from precision manufacturing supply chains. METI industrial standards and JIS certification requirements govern equipment specifications for domestic test houses. Industrial corridors in Kanto and Kansai maintain captive shock test capabilities for consumer electronics and automotive component development.
France
Aerospace subcontractor networks and defense electronics supply chains generate concentrated demand for high-energy hydraulic platforms. EASA certification alignment with FAA directives shapes procurement specifications for avionics validation. The Île-de-France and Occitanie regions host test service providers expanding capacity to serve pan-European battery qualification contracts.
Shock Test Machines Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than scale-consolidated generalists. Incumbent hydraulic platform suppliers face margin compression as servo-controlled electromechanical architectures capture battery testing growth. Three archetypes dominate: aerospace validation specialists with servo-hydraulic legacies, transportation-focused simulation providers, and integrated vibration-shock system integrators. Competitive dynamics center on waveform programmability investments and calibration service network expansion.
Among North American platform suppliers, MTS Systems Corporation and Lansmont Corporation occupy distinct positioning archetypes, while Brüel & Kjær represents European multi-physics integration expertise. These three exemplify divergent strategic vectors: MTS anchors premium aerospace and defense positioning through servo-hydraulic dominance, Lansmont concentrates transportation shock simulation for packaged goods compliance, and Brüel & Kjær extends acoustic measurement heritage into integrated vibration-shock environments. Chinese participants including Dongling Technologies compete on electromechanical system cost structures for mid-range electronics validation. The vendor map reflects geographic clustering around regulatory compliance centers rather than manufacturing cost arbitrage.
| Leading Market Players |
|---|
| MTS Systems Corporation |
| Instron |
| Lansmont Corporation |
| LAB Equipment Inc |
| Thermotron Industries |
| Kistler Group |
| Dongling Technologies |
| Brüel & Kjær |
| Team Corporation |
| Others |
Value Network & Pricing Analysis
EU CE marking under the Machinery Directive gates qualified supply access for European test equipment vendors, forcing premium-tier pricing for systems embedding safety-rated programmable logic controllers and redundant emergency stop architectures. German automotive suppliers and French aerospace subcontractors absorb these certification costs, while Asian exporters face margin compression from third-party conformity assessment requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates servo-hydraulic aerospace platforms from electromechanical electronics systems and basic pneumatic transportation testers. Certification grade under MIL-STD-810H and waveform programmability drive price differentiation, with battery abuse testing protocols commanding premium positioning. Cost compression in mid-range electromechanical tiers intensifies from Chinese manufacturer competition. Packaged goods manufacturers exhibit highest price sensitivity; defense contractors demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Freight cost volatility for precision motion components from Germany and Japan inflates landed costs for North American and Asian system integrators. Piezoelectric accelerometers and laser Doppler vibrometers draw from German and Japanese component specialists, while servo valves and hydraulic power units rest on US and European fluid power manufacturers. Single-source vulnerability concentrates in high-g sensor verification where ISO 17025-accredited calibration laboratories face eight-week queue times. Distribution runs through direct OEM sales for aerospace and defense, with commercial test houses procuring through specialized industrial equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shock test machines market compounds steadily as electric vehicle battery validation mandates expand test lab capacity across automotive manufacturing clusters. Regulatory convergence on mechanical safety documentation sustains replacement demand regardless of macroeconomic cyclicality.
For Market Incumbents: To counter servo-controlled electromechanical displacement in battery testing, anchor aerospace and defense positioning through MIL-STD-810H waveform fidelity investments while expanding calibration service networks to capture recurring revenue from commercial test houses. For New Entrants and Emerging Players: Contract validation laboratories represent the most penetrable channel partner type for cloud-connected data acquisition architectures, enabling subscription-based waveform validation services for smaller electronics manufacturers lacking captive test capabilities. For Investors and Strategic Acquirers: Roll-up economics work for regional test service providers because outsourced procurement consolidation among tier-one electronics manufacturers transfers capital burden from equipment ownership to specialized validation houses. The five-to-ten-year viability window favors platforms with NHTSA and MIIT battery safety certification capabilities. Monitor NMPA medical device regulation expansion as inflection indicator for mid-range shock capacity demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Controlled Platform Development | Real-time waveform synthesis captures NHTSA battery abuse testing mandates from automotive OEMs. |
| Calibration Service Network Expansion | ISO 17025-accredited verification capacity addresses eight-week queue times compressing commercial test house uptime. |
| Cloud-Connected Data Acquisition Launch | Remote monitoring architectures enable subscription revenue from smaller electronics manufacturers. |
| Integrated Vibration-Shock System Integration | Single-setup qualification reduces test lab footprint requirements for aerospace avionics validation. |
| Medical Device Certification Investment | China NMPA implantable electronics regulations create untapped demand in domestic manufacturing clusters. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and France, with primary inputs from each market combining interviews with test lab operations directors, OEM validation engineers, defense contractor procurement leads, and industrial equipment distributors. Secondary validation draws from FAA airworthiness directives, MIL-STD-810H revision documentation, EU Machinery Directive conformity assessment records, and MIIT battery safety standard filings. Bottom-up equipment shipment analysis triangulates against top-down test lab capacity expansion tracking.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include product type, application sector, end-user category, and technology architecture, with electric vehicle battery validation content per test protocol as industry-specific intensity driver. CAGRs derive from equipment replacement cycles, regulatory mandate implementation timelines, and capacity expansion announcements from automotive and aerospace manufacturing clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA and MIIT battery safety mandate evolution, MIL-STD revision schedules, and CE marking enforcement intensity. A model refresh is warranted upon material change in electric vehicle production volume trajectories or automotive OEM outsourcing policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Battery Testing Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Mechanical Testing Equipment Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Digital Height Gauges Market