
 Coaxial Profile Projectors Market | 2026-2036
Coaxial Profile Projectors Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Profile Projectors Market Insights
Aftermarket service revenue for calibration and recertification is fragmenting across regional service networks and OEM-certified partners. Mitutoyo sustains extensive metrology service infrastructure across Asia-Pacific manufacturing corridors. Zeiss differentiates through integrated software-hardware ecosystems that lock in recurring calibration contracts. Dr. Heinrich Schneider Messtechnik GmbH specializes in high-precision optical benches for German automotive and medical device suppliers.
Coaxial profile projectors employ telecentric optical paths with coaxial illumination to eliminate parallax error during two-dimensional dimensional measurement of precision-machined components, achieving resolution thresholds below one micron. Digital profile projectors are capturing margin pools from aging optical units as shops demand automated edge detection and SPC-ready data output. Video profile projectors lead in electronics producer environments where non-contact measurement of fragile PCBs and connector housings dominates throughput requirements. Measurement software segments are deepening as vendors bundle AI-assisted feature recognition to reduce operator-dependent variation.
ISO 17025 laboratory accreditation requirements and AS9100 aerospace quality mandates shape procurement specifications for calibration-traceable systems in Germany and Japan. The US FDA's 21 CFR Part 820 quality system regulation and China's GB/T standards for geometric dimensioning drive verification protocol rigor in medical device and general manufacturing applications. Stakeholders must weigh captive metrology investment against third-party inspection outsourcing as tolerance specifications tighten across semiconductor and medical implant supply chains.
Market Dynamics
Telecentric optical systems with coaxial illumination are compressing tolerance verification cycles in precision manufacturing, forcing metrology departments to consolidate around certified platforms that satisfy ISO 10360 traceability mandates.
Growth Catalysts
- ISO 10360 Certification Mandates:German automotive suppliers and Japanese electronics producers now require certified optical measurement platforms for micron-level dimensional verification, eliminating uncertified legacy equipment from approved vendor lists.
- Semiconductor Packaging Complexity:Advanced flip-chip and wafer-level packaging geometries in Taiwan and South Korea demand non-contact two-dimensional measurement systems capable of sub-micron resolution without probe-induced damage.
- AS9100 Aerospace Traceability:Tier-one avionics suppliers in France and the United States face mandatory calibration documentation for every dimensional verification step, driving replacement of manual optical comparators with digital profile projectors.
Market Restraints
- Telecentric Lens Supply Concentration:High-precision telecentric objective manufacturing concentrates among Japanese and German optical specialists, creating single-source vulnerability for projector OEMs.
- Certified Reference Artifact Costs:ISO 17025-compliant calibration artifacts for optical comparators command premium pricing, elevating total cost of ownership beyond budget-constrained machine shops.
- Coordinate Measuring Machine Substitution:Entry-level touch-probe CMMs with vision modules capture simple 2D measurement tasks at comparable accuracy, pressuring optical projector unit economics.
Strategic Opportunities
- Indian Medical Device Manufacturing:CDSCO quality system regulations and expanding orthopedic implant production in Gujarat and Karnataka create demand for traceable optical measurement systems.
- AI-Assisted Edge Detection Convergence:Machine vision algorithms integrated with telecentric optics enable automated feature recognition, reducing operator-dependent variation in high-mix production environments.
- Third-Party Metrology Services:Contract inspection laboratories in Vietnam and Mexico offer calibration-traceable measurement without captive capital investment, opening channel partnerships for equipment vendors.
Industry Challenges
- Dimensional Metrology Technician Scarcity:Shops struggle to recruit operators capable of interpreting telecentric optical paths and validating measurement uncertainty per ISO 14253-1.
- Legacy Comparator Integration Complexity:Digital retrofit kits for aging optical benches require mechanical realignment and software bridge development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Profile Projectors Market |
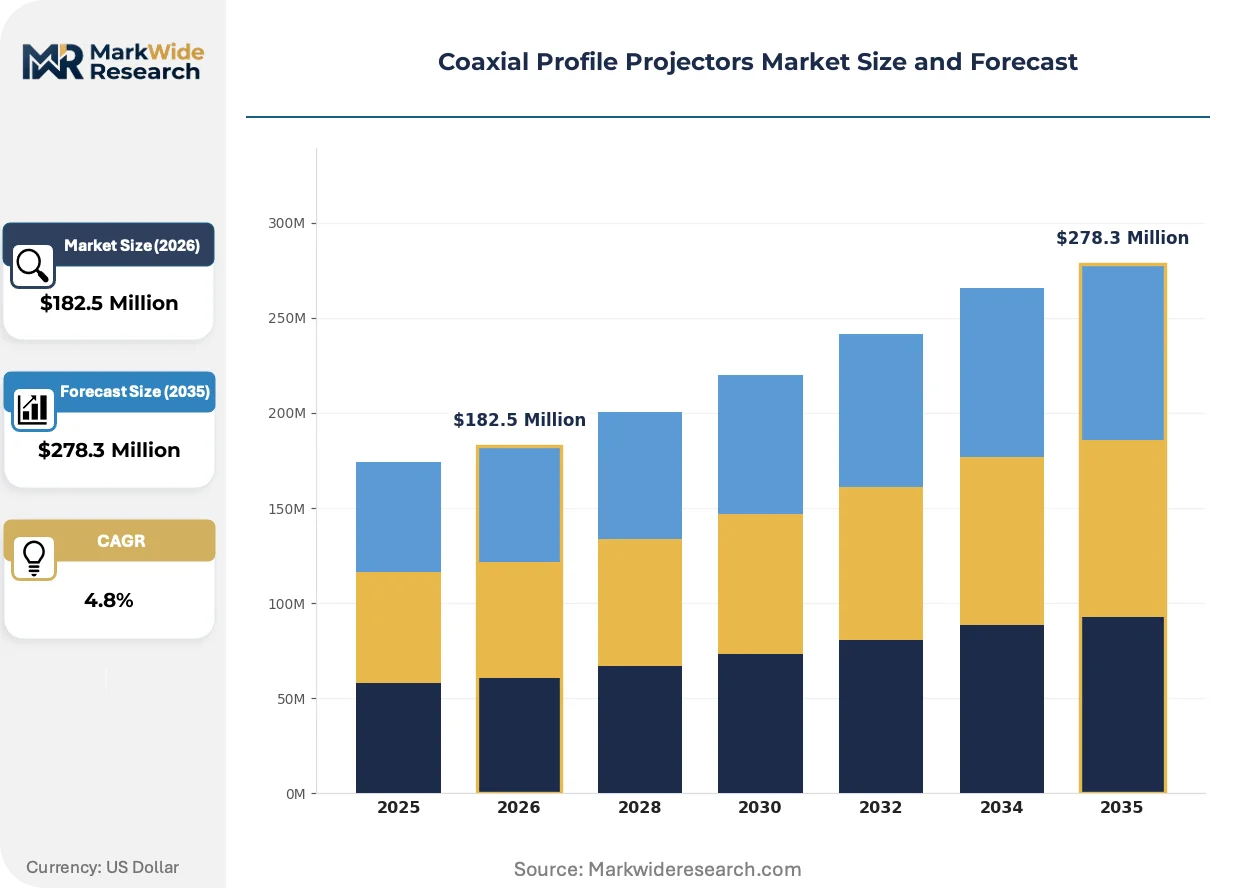
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $278.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Profile Projector, Digital Profile Projector, Video Profile Projector, Hybrid Profile Projector Technology: Image Processing, Edge Detection, Measurement Software, High-Resolution Optics, Digital Imaging Application: Precision Inspection, Quality Control, Dimensional Measurement, Tool Manufacturing, Assembly Verification End User: Machine Shops, Aerospace Component Manufacturers, Electronics Producers, Precision Engineering Firms |
| Companies Covered | Sipcon, Ayonis, Baty, DELTRONIC, Dr. Heinrich Schneider Messtechnik GmbH, Dynascan, INNOVATEST Europe BV, Mitutoyo, Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Profile Projectors Market Trends and Innovations
Digital capture architectures are displacing purely optical observation in precision measurement, compressing the gap between raw image acquisition and statistical process control integration.
Telecentric optical systems with coaxial LED illumination is digitizing edge detection workflows that previously required operator interpretation through ground-glass screens. Electronics contract manufacturers in Shenzhen and Seoul adopt these systems at replacement-cycle pace, eliminating parallax error in connector housing measurement. The technology is digitizing quality documentation, enabling direct SPC data feeds without manual transcription bottlenecks.
EU MDR and REACH substance restrictions are tightening material traceability requirements for medical device measurement equipment sold in Germany and France. Manufacturers must now document optical component composition and coating chemistry through the supply chain. German dental implant and surgical instrument producers face the steepest compliance burden, driving preference for vendors with pre-validated regulatory packages.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into discrete calibration, software, and hardware subscription components. Electronics producers in Japan and South Korea now procure measurement capacity as operational expenditure rather than capital investment. This shift is most visible among mid-tier semiconductor packaging houses seeking to preserve balance sheet flexibility during capacity expansion cycles.
Coaxial Profile Projectors Market Segmentation
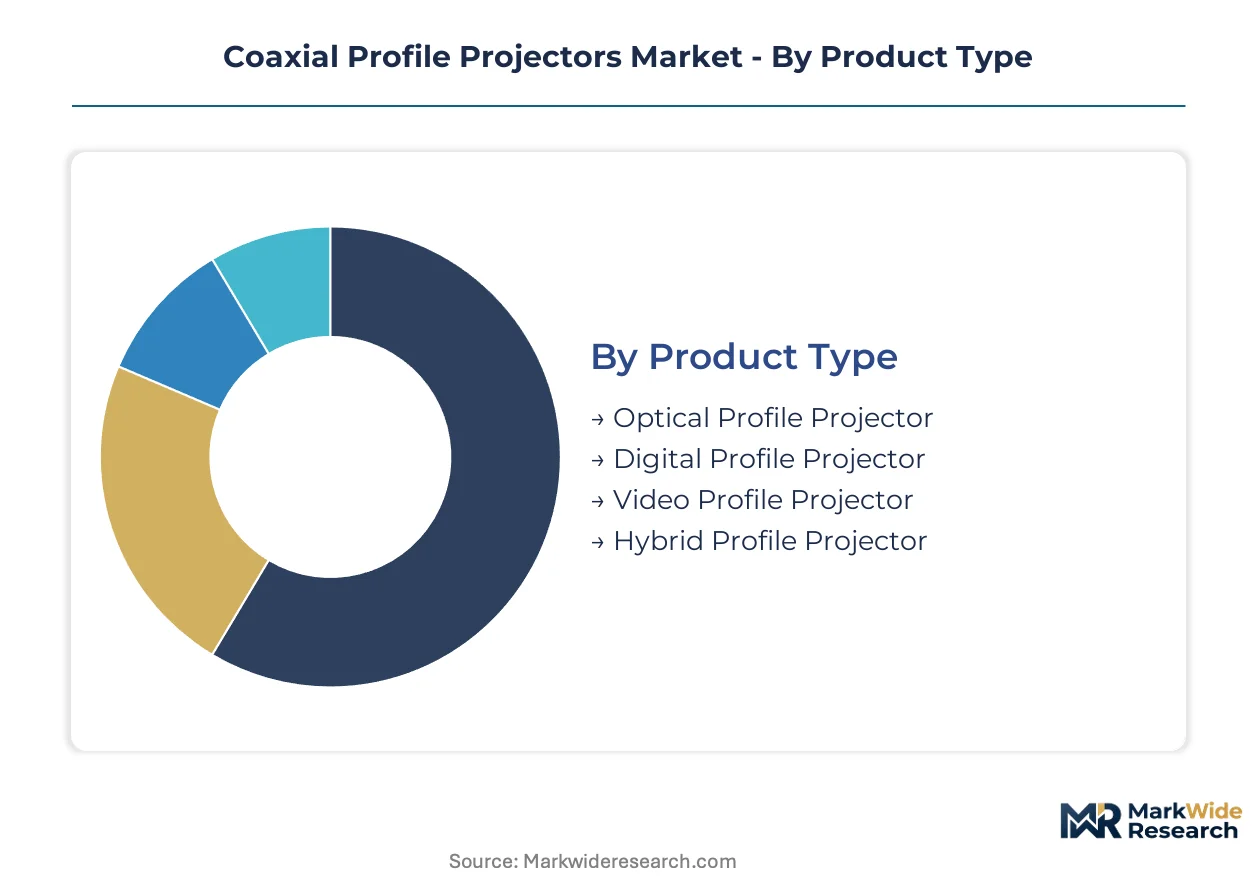
Coaxial profile projector procurement patterns diverge sharply across product architectures, underlying technologies, and end-use environments. Understanding these fault lines reveals where margin pools concentrate and which specifications drive replacement cycles in precision manufacturing corridors.
Product Type:
Optical benches span a functional spectrum from purely analog observation to fully digitized measurement workflows, with each architecture commanding distinct price positions and service attachment rates.
- Optical Profile Projector:Ground-glass screen observation systems with manual micrometer stages serve legacy machine shops performing low-volume inspection. German automotive suppliers are retiring these units fastest as ISO 10360 mandates eliminate uncertified equipment from approved vendor lists.
- Digital Profile Projector:Telecentric optics with CMOS capture and automated edge detection dominate electronics contract manufacturers in Taiwan and South Korea. These systems feed SPC databases directly, eliminating manual transcription bottlenecks in high-throughput PCB and connector housing verification.
- Video Profile Projector:High-frame-rate imaging with multi-point edge detection algorithms addresses fragile semiconductor packaging geometries where probe contact risks damage. Japanese precision engineering firms deploy these for wafer-level and flip-chip dimensional validation.
- Hybrid Profile Projector:Dual-mode architectures combining optical observation with digital capture serve mixed-legacy environments in Indian medical device manufacturing, where CDSCO quality regulations drive traceable measurement adoption without full fleet replacement.
The dominant share belongs to Digital Profile Projector, while Video Profile Projector is closing the gap fastest.
Technology:
Core technology investments determine resolution thresholds, operator skill requirements, and software recurring revenue potential across installed bases.
- Image Processing:Real-time distortion correction and sub-pixel interpolation algorithms compress measurement cycle times. Electronics producers in Shenzhen prioritize these capabilities for connector housing throughput.
- Edge Detection:Gradient-based and machine-vision algorithms reduce operator-dependent variation in feature recognition. French aerospace suppliers under AS9100 mandates favor automated edge detection for calibration-traceable documentation.
- Measurement Software:SPC integration, geometric dimensioning modules, and AI-assisted feature recognition generate recurring license revenue. Bundled software-hardware ecosystems lock in calibration contract renewals.
- High-Resolution Optics:Telecentric objective assemblies with sub-micron resolution concentrate supply among Japanese and German optical specialists, creating single-source vulnerability for projector OEMs.
- Digital Imaging:CMOS and CCD sensor architectures with coaxial LED illumination digitize quality documentation for medical device producers facing EU MDR material traceability requirements.
Measurement Software commands the highest attachment revenue per unit, though Edge Detection is expanding most quickly as AI-assisted algorithms penetrate mid-tier manufacturing.
Application:
Measurement tasks range from incoming material verification to final assembly sign-off, with each application imposing distinct throughput and documentation requirements.
- Precision Inspection:Sub-micron dimensional verification of machined components, medical implants, and semiconductor packages. German automotive suppliers deploy telecentric systems for micron-level tolerance verification in powertrain component production.
- Quality Control:Statistical process control integration with automated pass-fail sorting dominates electronics contract manufacturing in Seoul and Shenzhen, where direct data feeds replace manual logbooks.
- Dimensional Measurement:First-article inspection and lot sampling for geometric dimensioning compliance. Japanese precision engineering firms concentrate demand here for ISO 14253-1 uncertainty validation.
- Tool Manufacturing:Cutting tool edge geometry verification and wear assessment. Machine shops in the United States leverage optical comparators for non-contact tool qualification without probe-induced damage.
- Assembly Verification:Final fit-check and clearance measurement in aerospace and medical device assembly. French avionics suppliers under AS9100 mandates require calibration-traceable documentation at this stage.
Quality Control holds the largest installed base, while Precision Inspection is gaining share fastest as tolerance specifications tighten across semiconductor and medical implant supply chains.
End User:
Customer archetypes span captive metrology departments, third-party inspection laboratories, and contract manufacturers with varying capital intensity preferences.
- Machine Shops:Small-batch precision manufacturers with budget constraints and legacy optical comparator fleets. These operators face technician scarcity in interpreting telecentric optical paths and validating measurement uncertainty.
- Aerospace Component Manufacturers:Tier-one and tier-two suppliers in France and the United States subject to AS9100 and FAA traceability mandates. These firms replace manual comparators with digital profile projectors to satisfy calibration documentation requirements.
- Electronics Producers:Semiconductor packaging houses and PCB contract manufacturers in Taiwan, South Korea, and Japan. Non-contact measurement of fragile components dominates throughput requirements, with service unbundling shifting procurement toward operational expenditure models.
- Precision Engineering Firms:German and Japanese specialists in micron-level dimensional verification for automotive and medical device supply chains. These firms drive adoption of certified optical measurement platforms under ISO 10360 and ISO 17025 requirements.
Electronics Producers represent the deepest installed base, though Precision Engineering Firms are expanding equipment spend fastest as certification mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine shops in the United States exhibit the sharpest price elasticity, deferring replacement of aging optical comparators amid technician scarcity and budget constraints. German precision engineering firms show the least sensitivity, absorbing premium pricing for ISO 10360-certified platforms to maintain automotive supplier qualifications. Electronics producers in East Asia occupy a middle position, trading capital expenditure for operational expenditure through service-unbundled procurement.
Germany
Automotive powertrain suppliers in Bavaria and Baden-Württemberg drive replacement of manual optical comparators with digital profile projectors. KBA enforcement of ISO 10360 traceability mandates eliminates uncertified equipment from approved vendor lists. Stuttgart and Munich manufacturing corridors concentrate demand for telecentric systems capable of sub-micron tolerance verification in crankshaft and transmission component production.
Japan
Semiconductor packaging houses in the Kanto region around Tokyo deploy video profile projectors for wafer-level dimensional validation without probe-induced damage. METI industrial standards and JIS certification requirements shape procurement specifications for calibration-traceable measurement platforms. Osaka-based precision engineering firms specialize in micron-level verification for medical device and automotive supply chains.
United States
Aerospace tier-one suppliers in Seattle and Wichita replace legacy optical benches under FAA and AS9100 calibration documentation mandates. Small-batch machine shops in the Midwest defer upgrades due to ISO 17025-compliant artifact costs and operator training gaps. California electronics contract manufacturers favor non-contact measurement systems for fragile PCB and connector housing inspection.
South Korea
Advanced flip-chip and memory packaging facilities in Seoul Capital Area and Busan-Ulsan corridor demand high-frame-rate imaging for sub-micron resolution. MFDS quality system regulations for medical device exporters drive traceable optical measurement adoption. Yongin and Suwon manufacturing clusters prioritize automated edge detection algorithms for high-throughput SPC integration.
India
Orthopedic implant producers in Gujarat and Karnataka expand optical measurement capacity under CDSCO quality system regulations. Budget-constrained machine shops in Maharashtra and Tamil Nadu favor hybrid profile projectors enabling digital retrofit without full fleet replacement. Pune and Chennai industrial corridors concentrate demand for traceable dimensional verification in surgical instrument and dental component manufacturing.
Coaxial Profile Projectors Market Competitive Landscape
Capability concentration sits with German and Japanese optical specialists mastering telecentric lens assemblies; scale advantage sits with Asia-Pacific metrology conglomerates operating extensive service infrastructures. The vendor base stratifies across three tiers: premium-tier integrated software-hardware ecosystems, mid-tier modular platform suppliers, and value-tier optical bench fabricators. Dominant competitive moves include strategic partnerships with third-party inspection laboratories and geographic expansion into Vietnamese and Mexican contract manufacturing corridors.
Within the precision-tier segment, Dr. Heinrich Schneider Messtechnik GmbH represents German optical bench specialization for automotive and medical device supply chains. Mitutoyo and Zeiss exemplify divergent scale strategies—Mitutoyo through Asia-Pacific service infrastructure density, Zeiss through integrated software-hardware ecosystems locking in recurring calibration contracts. Sipcon and Ayonis occupy positions among mid-tier modular platform suppliers addressing budget-constrained machine shops seeking ISO 10360 compliance without premium-tier investment.
| Leading Market Players |
|---|
| Sipcon |
| Ayonis |
| Baty |
| DELTRONIC |
| Dr. Heinrich Schneider Messtechnik GmbH |
| Dynascan |
| INNOVATEST Europe BV |
| Mitutoyo |
| Zeiss |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in legacy optical comparator manufacturing across the United States Midwest is compressing spot pricing for analog systems while elevating premiums for ISO 10360-certified digital platforms in Germany and Japan. This utilization divergence forces suppliers to bifurcate service strategies: discounting maintenance contracts for aging installed bases while locking in recurring calibration revenue for certified telecentric systems.
Pricing Analysis
Calibration and recertification service contracts drive lifetime value capture, with bundled software-hardware ecosystems commanding premium positioning over modular alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Zeiss and Mitutoyo integrated platforms from mid-tier modular suppliers and value-tier optical bench fabricators. Cost compression in economy-tier analog systems is intensifying because machine shops defer replacement cycles amid technician scarcity. Electronics producers in Taiwan and South Korea show least price sensitivity, absorbing operational-expenditure models; Midwestern US machine shops exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Japan and Germany dominates supply chain risk planning for telecentric objective assemblies. High-precision lens manufacturing concentrates in Japan and Germany, with CMOS sensor sourcing drawing from South Korean and Taiwanese fabrication facilities. Single-source vulnerability permeates telecentric objective supply, as Japanese and German optical specialists control sub-micron resolution assemblies. Distribution runs through OEM-direct channels for premium-tier systems and regional metrology distributors for mid-tier modular platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
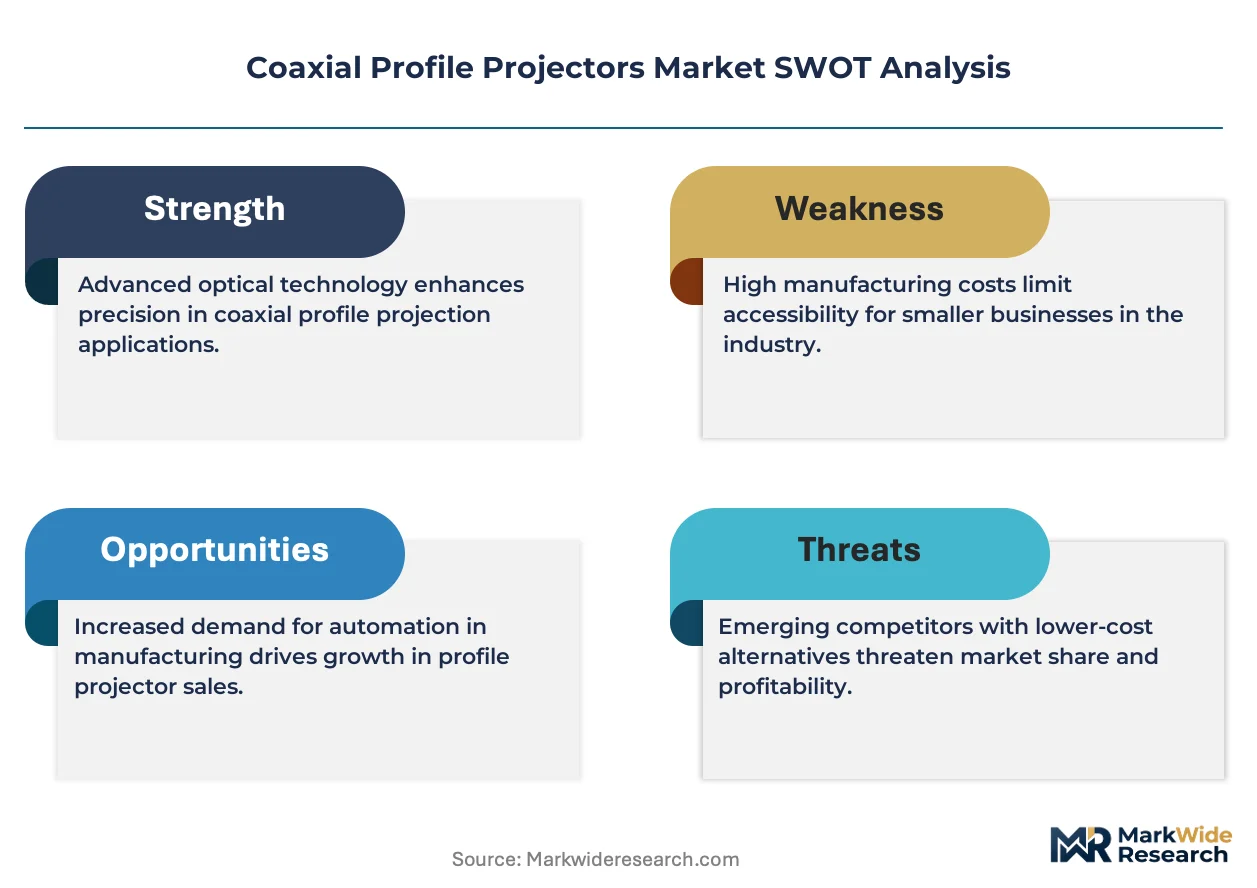
Buyer power is shifting toward electronics contract manufacturers in East Asia as procurement consolidates around service-unbundled operational expenditure models, fragmenting traditional equipment-plus-maintenance contracts.
For Market Incumbents: Pre-empt entry-level CMM substitution by embedding AI-assisted edge detection as standard rather than premium-tier features. Lock in calibration contract renewals through ISO 17025 laboratory accreditation investments that third-party inspection laboratories cannot replicate. Threat: Coordinate measuring machines with vision modules capture simple 2D measurement tasks. Lever: Certification investment in multi-site ISO 10360 compliance. For New Entrants and Emerging Players: Indian medical device manufacturing corridors in Gujarat and Karnataka offer white-space penetration before CDSCO quality system regulations fully mature. Target hybrid profile projector architectures enabling digital retrofit without full fleet replacement for budget-constrained machine shops in Maharashtra and Tamil Nadu. Go-to-market angle: channel partnerships with third-party metrology services in Vietnamese contract manufacturing corridors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated software-hardware ecosystem vendors with captive calibration infrastructure. Long-term viability favors acquisition targets with validated regulatory packages for EU MDR compliance and established service density in Asia-Pacific manufacturing corridors. Signal to watch: OEM consolidation around subscription-based measurement capacity procurement.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Edge Detection Integration | Reduces operator-dependent variation for AS9100-mandated aerospace suppliers. |
| ISO 17025 Laboratory Accreditation Expansion | Locks in calibration contract renewals against third-party inspection competition. |
| Service Unbundling and Subscription Models | Aligns procurement with operational expenditure preferences of semiconductor packaging houses. |
| Geographic Expansion into Vietnamese Metrology Corridors | Captures contract inspection laboratory partnerships before incumbent service density establishes. |
| Hybrid Platform Architecture Development | Addresses CDSCO compliance requirements in Indian medical device manufacturing without full fleet replacement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with metrology equipment procurement managers, precision engineering firm operations directors, and third-party inspection laboratory technical leads; and secondary validation through SEC filings of listed metrology conglomerates, ISO 17025 accreditation databases, and customs records of optical component trade flows. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, application, and end user dimensions.
Forecast inputs considered telecentric lens supply constraints, ISO 10360 certification mandate adoption curves, and semiconductor packaging complexity trajectories across the projection horizon. Segmentation dimensions modeled include product architecture, core technology investment, measurement task category, and customer capital intensity preference. CAGRs were derived from replacement cycle analysis and regulatory compliance deadline clustering.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vision-module CMM vendors or unbundled third-party metrology services would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Telecom Testing Equipment Market
Test and Measurement
Gauss Meter Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Production Testing Market
Test and Measurement
Tube Tester Market
Test and Measurement
Wireless Network Test Equipment Market