
 Grafting Robot Market | 2026-2036
Grafting Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Grafting Robot Market Insights
Carbon-fiber composite end-effectors is rebalancing cost-performance trade-offs for high-speed grafting arms. Visser Horti Systems leverages its Dutch greenhouse automation heritage to dominate European nursery installations. ISO Group anchors its position through precision servo-mechanisms engineered for tropical crop compatibility. Yamaha Motor Co., Ltd. extends its industrial robotics expertise into compact grafting cells for Asian protected-horticulture markets.
A grafting robot is an automated electro-mechanical system that joins scion and rootstock plant tissues through programmable cutting, alignment, and binding operations, typically achieving 1,200–2,500 grafts per hour with sub-millimeter vascular cambium matching accuracy. Its primary purpose is to eliminate manual labor dependency while standardizing union quality in commercial propagation. Automated Systems command the dominant installed base due to throughput requirements at large vegetable seedling facilities, while AI Integration represents the fastest-expanding technology layer as nurseries deploy real-time graft-quality feedback loops. Commercial Nurseries generate the deepest margin pools because volume contracts justify capital-intensive robotic lines.
Japan's METI promotes agricultural robot diffusion through subsidy frameworks that lower capital barriers for domestic growers. South Korea's MFDS and Rural Development Administration enforce phytosanitary standards that grafting equipment must satisfy for certified propagation facility status. Stakeholders must weigh regulatory compliance investments against automation payback periods as labor-scarcity thresholds vary across protected-horticulture zones.
Market Dynamics
Carbon-fiber composite end-effectors are compressing cost-performance thresholds for high-speed grafting arms, forcing equipment makers to recalibrate mechanical durability against precision servo costs. This materials transition sits at the center of competitive positioning across nursery automation supply chains.
Growth Catalysts
- Japan's METI subsidy frameworks:These programs lower capital barriers for domestic growers adopting robotic propagation systems, accelerating diffusion across protected-horticulture clusters.
- Machine vision integration:Real-time graft-quality feedback loops reduce error rates in vegetable crop operations, pulling demand from large-scale seedling facilities.
- South Korean greenhouse complexes:Concentrated protected agriculture investment creates dense installed-base opportunities for compact grafting cell deployments.
Market Restraints
- Precision servo cost volatility:Tropical-crop-compatible servo-mechanisms carry premium component sourcing exposure, compressing margin structures for mid-tier equipment vendors.
- Phytosanitary certification friction:South Korea's MFDS and Rural Development Administration enforce facility-status requirements that extend sales-to-revenue cycles for propagation equipment.
- Manual grafting substitution persistence:Seasonal labor availability in Mediterranean nursery zones delays automation payback calculations for smaller propagation operations.
Strategic Opportunities
- Spanish commercial nursery expansion:Automated grafting capacity buildouts to offset seasonal labor shortages create greenfield installation demand.
- AI-layer convergence with machine vision:Real-time quality feedback integration opens premium pricing for intelligent grafting systems beyond baseline automated units.
- Dutch greenhouse automation heritage leverage:Established European nursery automation ecosystems provide channel infrastructure for next-generation grafting line deployments.
Industry Challenges
- Vascular cambium matching calibration:Sub-millimeter alignment precision requires specialized technician training that outpaces available skilled labor pools in emerging horticulture markets.
- Legacy propagation facility retrofit complexity:Integration of robotic grafting cells with existing seedling handling infrastructure demands customized mechanical interfacing that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grafting Robot Market |
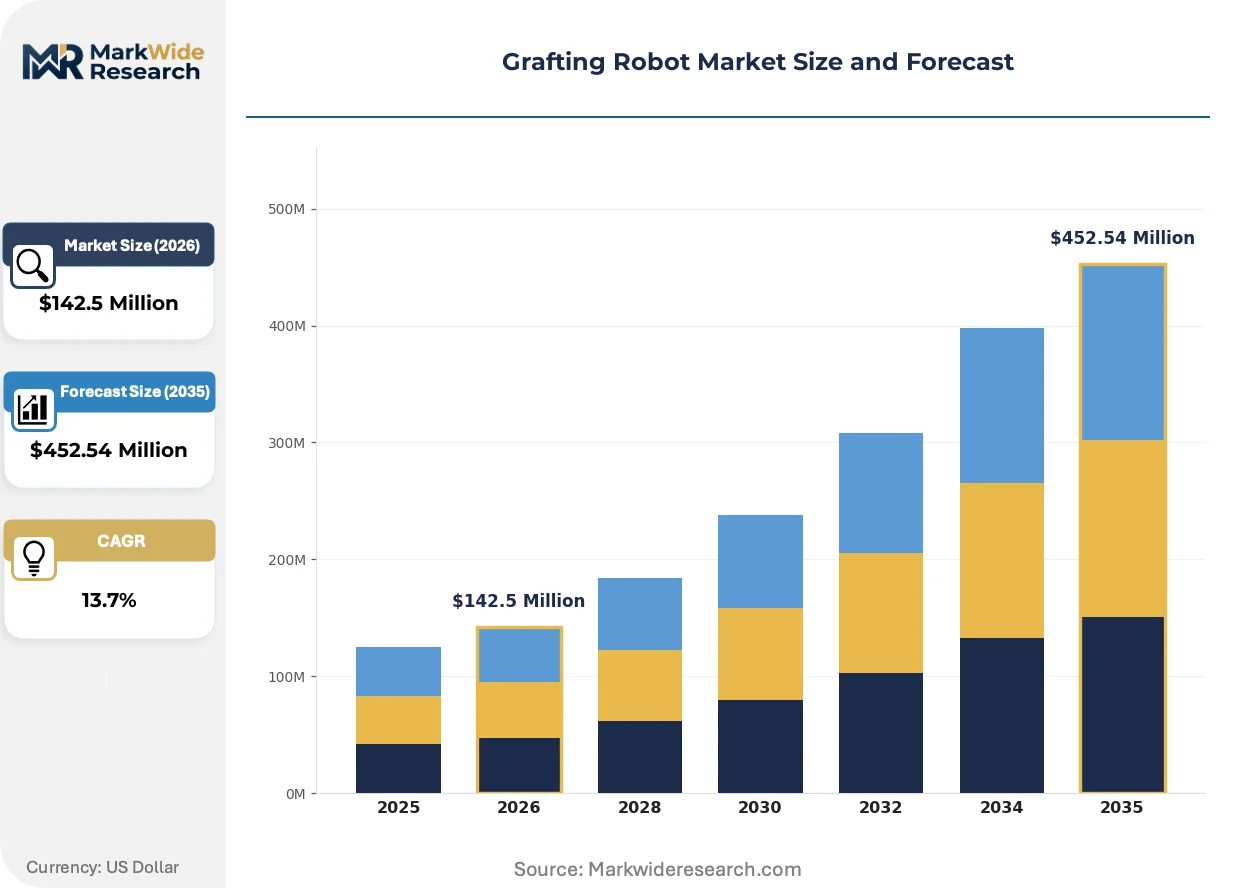
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Collaborative Robots, High-Precision Tools, Manual Assist Devices Technology: AI Integration, Image Recognition, Machine Learning, Motion Control End User: Commercial Nurseries, Research Institutions, Agricultural Production Farms, Hobbyist Growers Application: Vegetable Crops, Fruit Trees, Ornamental Plants, Specialty Botanicals |
| Companies Covered | Visser Horti Systems, ISO Group, Iseki & Co., Ltd., FFRobotics, Conic System, Yamaha Motor Co., Ltd., Daedong Industrial Co., Ltd., Urbinati, Wagner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grafting Robot Market Trends and Innovations
Electrification of mechanical end-effector materials is compressing the traditional trade-off between grafting speed and precision durability. Three parallel developments are reshaping how propagation automation equipment is specified, procured, and deployed across commercial nursery operations.
Carbon-fiber composite grafting arms are electrifying the cost-performance frontier for high-speed propagation equipment. Japanese strawberry propagation facilities and South Korean greenhouse complexes are adopting these lightweight end-effectors at accelerating rates. The technology is electrifying competitive positioning by enabling sub-millimeter accuracy at throughput levels previously requiring steel-frame mechanical systems.
Japan's METI agricultural robot diffusion frameworks are creating subsidy-driven procurement acceleration across domestic protected-horticulture zones. These programs reduce effective capital barriers for grafting automation investments, shifting equipment specification criteria toward total-cost-of-ownership metrics. Commercial nurseries in Japan's major propagation clusters are responding by front-loading robotic line deployments ahead of subsidy phase-out schedules.
Strawberry propagation facilities are consolidating vendor relationships around integrated automation suppliers rather than point-solution grafting equipment. This concentration is displacing standalone grafting robot procurement in favor of bundled propagation line contracts spanning cutting, grafting, and post-union handling. The pattern is most visible in East Asian protected agriculture clusters where greenhouse operators prioritize single-source automation accountability.
Grafting Robot Market Segmentation
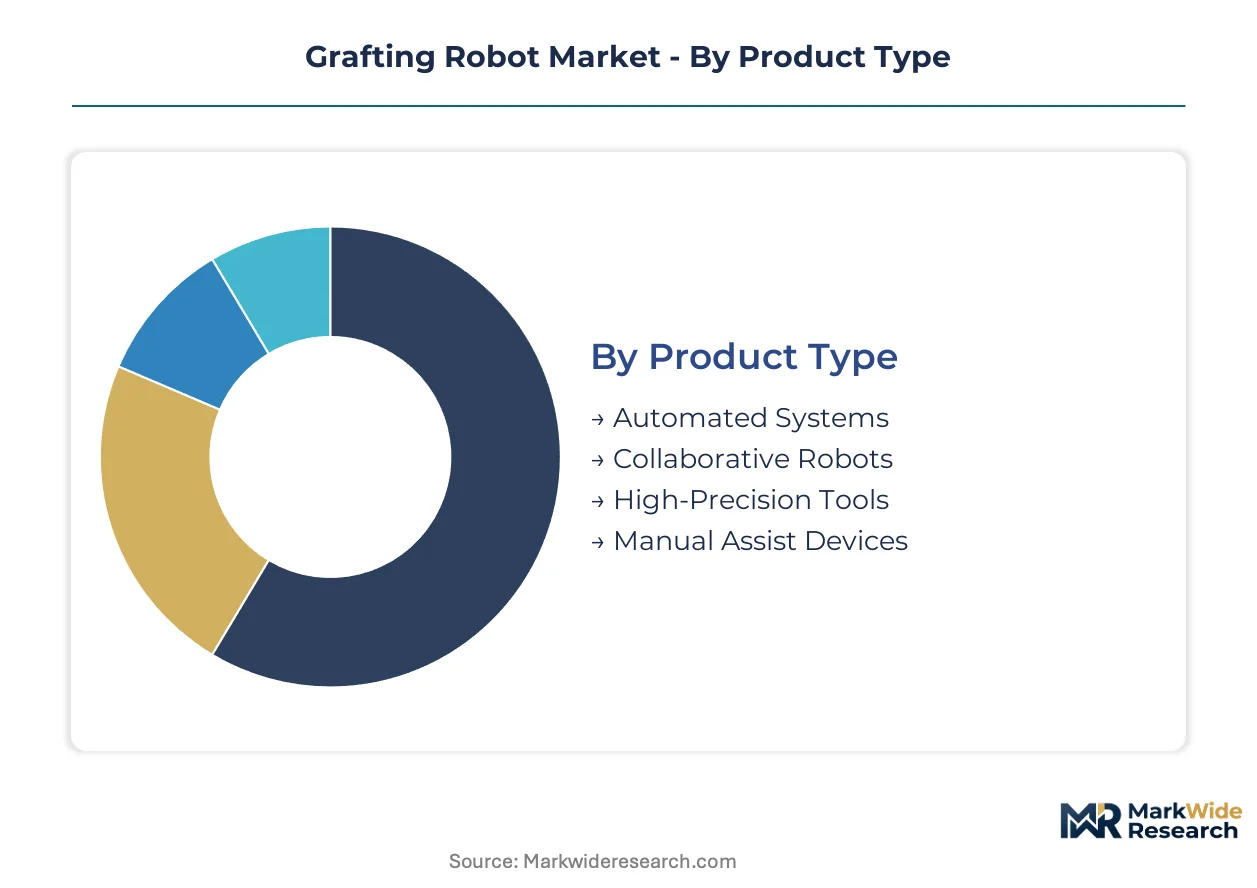
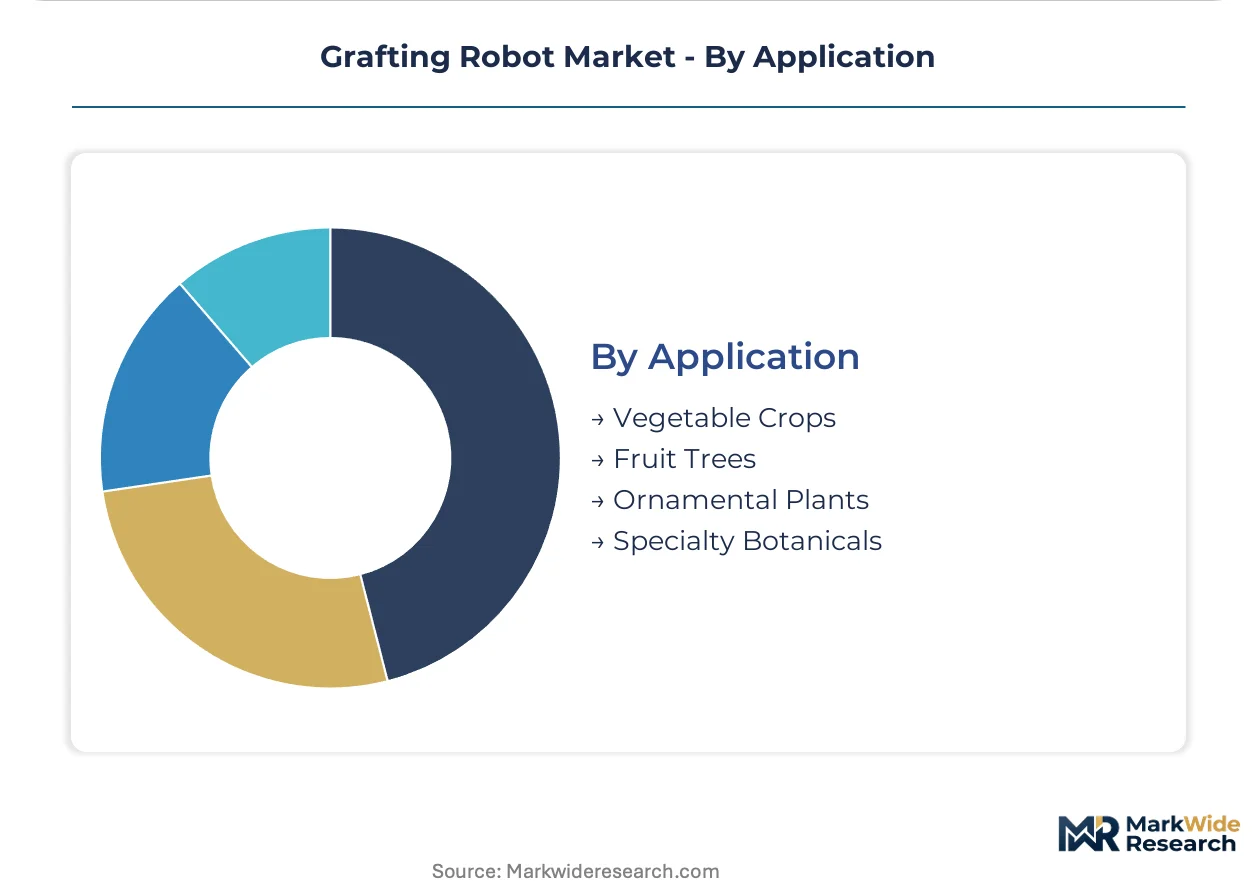
Grafting robot segmentation reveals distinct procurement patterns across propagation facilities. Equipment buyers prioritize throughput requirements, labor substitution economics, and crop-specific precision demands when selecting automation tiers.
Product Type:
Capital intensity and operational scale drive equipment selection across nursery automation procurement cycles.
- Automated Systems:These electro-mechanical lines execute cutting, alignment, and binding through programmable servo-mechanisms, achieving 1,200–2,500 grafts per hour. Commercial nurseries in the Netherlands and Spain deploy these systems to offset seasonal labor shortages at vegetable seedling facilities. Automated Systems lead on scale; Collaborative Robots lead on momentum.
- Collaborative Robots:Compact grafting cells integrate human-robot workflow sharing with force-limiting safety architectures. South Korean greenhouse complexes and Japanese strawberry propagation facilities are adopting these units for flexible batch sizes in protected-horticulture environments.
- High-Precision Tools:Semi-automated devices target vascular cambium matching accuracy below 0.5 millimeters for high-value ornamental propagation.
- Manual Assist Devices:Ergonomic cutting guides and alignment jigs reduce technician fatigue in smaller Mediterranean nursery operations with intermittent automation payback calculations.
Automated Systems dominate installed base economics; Collaborative Robots are expanding most quickly through East Asian subsidy frameworks.
Technology:
Layer sophistication determines pricing stratification and competitive differentiation across equipment vendor portfolios.
- AI Integration:Real-time graft-quality feedback loops analyze union formation and predict healing outcomes through neural network pattern recognition. Japanese METI subsidy programs accelerate procurement of AI-enabled propagation lines ahead of phase-out schedules. AI Integration leads on margin capture; Image Recognition leads on deployment velocity.
- Image Recognition:Machine vision systems reduce error rates in vegetable crop operations by automating scion-rootstock alignment verification. Commercial nurseries specify these systems for standardized union quality in high-volume contracts.
- Machine Learning:Predictive maintenance algorithms optimize servo-mechanism calibration cycles for tropical crop compatibility.
- Motion Control:Precision trajectory planning enables sub-millimeter repeatability in high-speed grafting arm operations.
AI Integration commands premium pricing; Image Recognition shows steepest expansion trajectory through quality-standard enforcement.
End User:
Facility scale and contract structure determine automation investment thresholds across propagation value chains.
- Commercial Nurseries:Large-scale seedling facilities generate the deepest margin pools through volume contracts justifying capital-intensive robotic lines. Dutch greenhouse automation ecosystems provide channel infrastructure for next-generation grafting deployments. Commercial Nurseries lead on revenue concentration; Agricultural Production Farms lead on emerging demand.
- Research Institutions:University breeding programs and government agricultural stations specify precision tools for genotype evaluation and union physiology studies.
- Agricultural Production Farms:Integrated operations are consolidating propagation automation with post-union handling for captive supply security.
- Hobbyist Growers:Manual assist devices address price-sensitive demand in small-scale ornamental and specialty botanical propagation.
Commercial Nurseries anchor equipment vendor margins; Agricultural Production Farms show fastest adoption acceleration through backward integration strategies.
Application:
Crop biology and union healing requirements dictate mechanical specification and throughput design parameters.
- Vegetable Crops:Solanaceous and cucurbit seedlings demand high-speed processing with standardized stem diameters. South Korean MFDS phytosanitary certification requirements shape equipment specifications for certified propagation facility status. Vegetable Crops lead on unit volume; Specialty Botanicals lead on precision premium.
- Fruit Trees:Woody propagation requires enhanced cutting force and cambium exposure techniques for delayed union formation.
- Ornamental Plants:High-value floriculture and nursery stock operations prioritize aesthetic union quality over raw throughput metrics.
- Specialty Botanicals:Rare and medicinal plant propagation demands customized end-effector geometries for irregular stem morphologies.
Vegetable Crops dominate procurement scale; Specialty Botanicals capture highest per-unit equipment margins through customization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian protected agriculture clusters anchor grafting robot deployment velocity. Commercial nurseries across Japan, South Korea, and China are consolidating automation investments through subsidy frameworks and phytosanitary certification requirements.
Japan
Strawberry propagation facilities drive compact grafting cell adoption. METI subsidy frameworks lower capital barriers for domestic growers. Kanto and Kansai greenhouse complexes are front-loading robotic line deployments ahead of phase-out schedules.
South Korea
Greenhouse complexes concentrate demand for high-throughput vegetable seedling operations. MFDS and Rural Development Administration enforce phytosanitary standards for certified propagation facility status. Gyeonggi-do and South Chungcheong protected agriculture zones are expanding automated grafting capacity.
Netherlands
Commercial vegetable nurseries offset seasonal labor shortages through robotic propagation lines. Dutch greenhouse automation heritage provides channel infrastructure for next-generation deployments. Westland and Aalsmeer horticulture clusters are scaling automated grafting installations.
Spain
Mediterranean nursery operations face persistent manual grafting substitution due to intermittent seasonal labor. Almería and Murcia protected agriculture zones are building out automated capacity to reduce dependency on migrant agricultural workers.
United States
Large-scale vegetable seedling facilities in California and Florida evaluate capital-intensive robotic lines for solanaceous crop propagation. USDA research stations support union physiology studies that inform equipment specification criteria. Salinas Valley and Central Florida greenhouse clusters are piloting machine vision-integrated grafting systems.
Grafting Robot Market Competitive Landscape
Technology licensing dominates the current landscape as equipment vendors secure regional distribution partnerships. The vendor base stratifies across three tiers: integrated automation suppliers bundling propagation lines, precision servo-mechanism specialists, and compact grafting cell fabricators. Strategic archetypes include Dutch greenhouse automation heritage players, Japanese industrial robotics extenders, and Korean protected-horticulture specialists. Portfolio diversification and geographic expansion represent the dominant competitive moves as vendors chase subsidy-driven procurement windows.
Within the integrated automation tier, Visser Horti Systems and Urbinati represent European nursery automation heritage. Yamaha Motor Co., Ltd. and Iseki & Co., Ltd. exemplify Japanese industrial robotics expertise extending into horticulture applications. ISO Group and Daedong Industrial Co., Ltd. anchor Korean and broader Asian market positions through tropical-crop-compatible equipment specifications.
| Leading Market Players |
|---|
| Visser Horti Systems |
| ISO Group |
| Iseki & Co., Ltd. |
| FFRobotics |
| Conic System |
| Yamaha Motor Co., Ltd. |
| Daedong Industrial Co., Ltd. |
| Urbinati |
| Wagner |
| Others |
Pricing and Supply Chain Analysis
Performance divergence between carbon-fiber composite end-effectors and legacy steel-frame systems splits procurement economics across nursery automation tiers, with lightweight precision components commanding premium positioning while commodity servo-mechanisms face margin compression from tropical-crop engineering requirements. This bifurcation concentrates vendor pricing power among Japanese and Dutch integrated automation suppliers while forcing mid-tier equipment makers toward volume-contract discounting.
Pricing Analysis
Precision servo cost volatility passes through to equipment pricing most acutely for tropical-crop-compatible mechanisms, compressing margins for vendors without backward integration into component sourcing. Three-tier pricing structure across premium AI-integrated systems, standard automated lines, and economy manual-assist devices reflects certification grade differentiation under South Korea's MFDS phytosanitary standards. Pricing pressure stems from carbon-fiber material cost escalation and Japanese METI subsidy phase-out schedules. Commercial nurseries in the Netherlands show lowest price sensitivity due to volume contract structures, while Mediterranean manual-grafting operations exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Japan, and South Korea anchor hub-and-spoke fulfillment patterns for grafting robot components, with Dutch greenhouse automation heritage players maintaining dense European warehouse networks. Precision servo-mechanisms draw from Japanese and German component specialists, while carbon-fiber end-effector fabrication concentrates in South Korean and Chinese materials processing facilities. Single-source vulnerability persists for tropical-crop-compatible servo calibration modules. Distribution runs through authorized dealer networks serving protected-horticulture clusters, with direct OEM relationships dominating large commercial nursery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grafting robot procurement has shifted toward AI-integrated propagation lines with real-time quality feedback, elevating specification requirements beyond baseline automated systems. This quality migration favors vendors with machine vision R&D depth and subsidy-framework navigation capabilities.
For Market Incumbents: Lock in channel control through exclusive distribution agreements with Dutch and Spanish commercial nursery networks before emerging Korean specialists scale European presence. Invest in backward integration into carbon-fiber end-effector fabrication to offset precision servo cost volatility. Prioritize METI subsidy compliance certification to capture front-loaded Japanese procurement ahead of framework phase-outs. For New Entrants and Emerging Players: Compact collaborative robot architectures with force-limiting safety systems offer the most penetrable white-space for new market entry, particularly in South Korean greenhouse complexes seeking flexible batch-size automation. Target Spanish Mediterranean nursery zones where seasonal labor shortages are accelerating automation payback calculations. Pursue technology licensing partnerships with established greenhouse automation heritage players rather than standalone product launches. For Investors and Strategic Acquirers: Asymmetric upside sits with precision servo-mechanism specialists possessing tropical-crop compatibility engineering. Long-term viability over the projection horizon hinges on AI-layer convergence capabilities rather than mechanical hardware scale. Monitor Japanese strawberry propagation facility procurement patterns as the inflection indicator for subsidy-driven demand acceleration versus market-normalized replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Layer Integration | Real-time graft-quality feedback commands premium pricing above baseline automated systems. |
| Backward Integration | In-house carbon-fiber end-effector production insulates margins from materials cost volatility. |
| Subsidy Framework Navigation | Early METI certification capture accelerates procurement ahead of phase-out schedules. |
| Regional Distribution Expansion | Dutch and Spanish warehouse networks reduce deployment timelines for commercial nursery contracts. |
| Collaborative Robot Development | Force-limiting safety architectures open protected-horticulture segments with flexible batch requirements. |
Research Methodology
Coverage spans East Asian protected agriculture clusters, European greenhouse automation ecosystems, and North American vegetable seedling facilities, with primary inputs from each region triangulated against secondary validation. Interviews with nursery automation procurement managers, precision servo engineering directors, protected-horticulture facility operators, and METI subsidy program administrators combined with customs trade data, agricultural machinery registration databases, greenhouse operator capex disclosures, and phytosanitary certification records. Bottom-up equipment shipment tracking and top-down nursery automation investment flow analysis were cross-referenced for triangulation.
Granularity-level modeling applied product type segmentation at the system-configuration level, technology layering at the AI-integration depth level, end-user analysis at the facility-scale contract-structure level, and application specification at the crop-biology compatibility level. CAGRs were derived from installed-base growth trajectories and replacement-cycle acceleration patterns. Forecast inputs incorporated carbon-fiber materials cost curves, Japanese subsidy framework phase-out schedules, and South Korean MFDS certification timeline assumptions.
The model holds under sustained labor-scarcity conditions in protected horticulture; deviation in seasonal migrant labor availability or precision servo supply normalization would shift automation payback calculations. Forecasts reflect documented assumptions regarding subsidy continuity and materials cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Top Robotics Market