
 Global Artificial Intelligence (AI) in Construction Market | 2026-2036
Global Artificial Intelligence (AI) in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) in Construction Market Foresight
Asset-light SaaS subscription models and pay-per-project financing are narrowing the competitive field for smaller contractors seeking AI tools. Autodesk leverages its design software heritage to anchor cloud-based construction intelligence. Procore Technologies sustains platform stickiness through deep integration with subcontractor payment workflows. Dusty Robotics competes by specializing in field robotics for drywall layout automation.
Artificial Intelligence in Construction encompasses machine learning algorithms, computer vision systems, and predictive analytics platforms that process jobsite sensor data, BIM outputs, and scheduling inputs to optimize labor deployment, safety compliance, and material logistics. Computer vision and predictive analytics lead current deployment as contractors prioritize real-time hazard detection and delay forecasting. Machine learning applications in cost estimation tools represent the fastest-expanding margin pool as volatility in material pricing drives demand for dynamic forecasting.
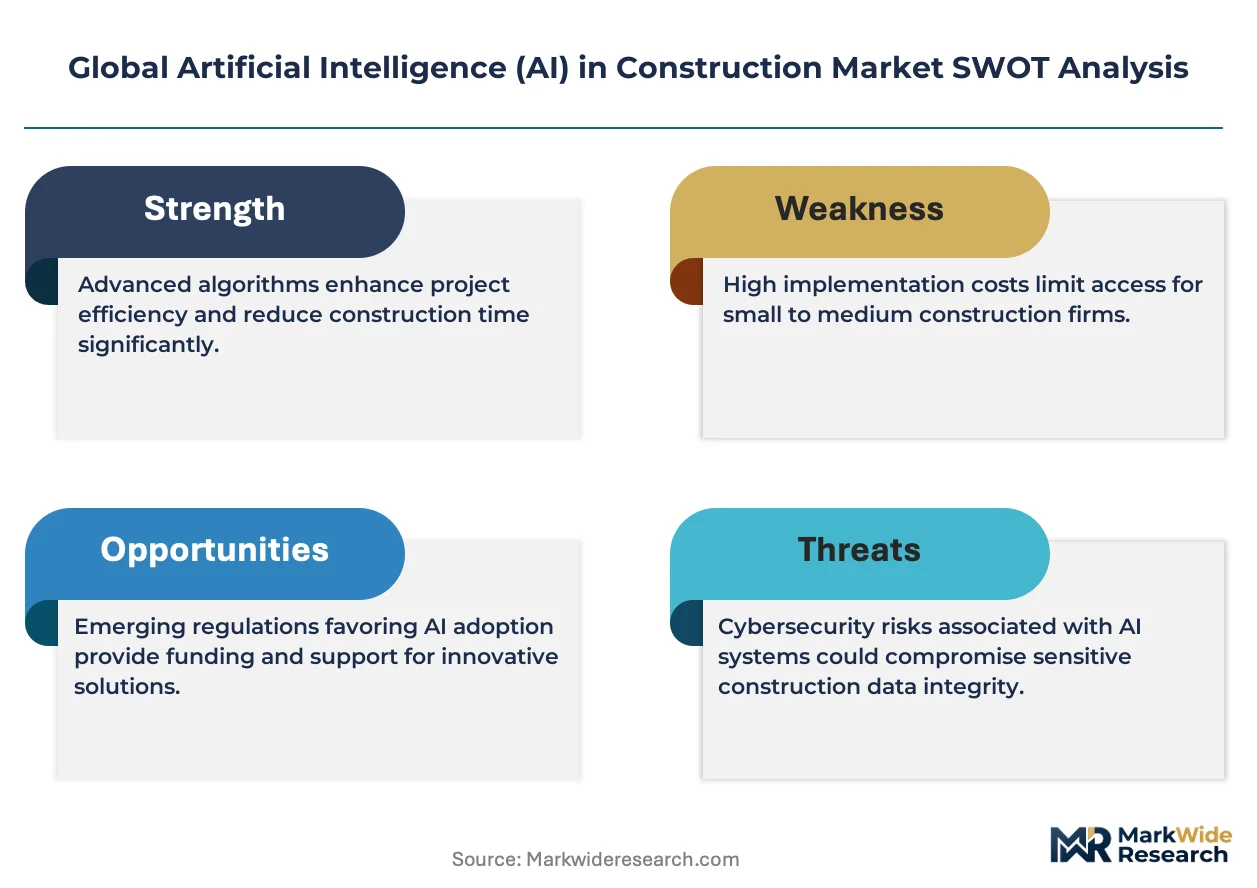
The EU AI Act, OSHA workplace safety directives in the United States, and Singapore's Building and Construction Authority codes collectively shape product certification requirements and data governance standards for construction AI vendors. Compliance with these frameworks determines market access and liability coverage eligibility. Stakeholders must monitor evolving liability allocations between software providers and contractors as autonomous equipment deployment expands.
Market Dynamics
The EU AI Act's risk-classification framework for construction algorithms is forcing vendors to restructure product architectures before 2025 enforcement deadlines, compressing development timelines and redirecting R&D budgets toward compliance documentation.
Growth Catalysts
- Smart City Mandates:Singapore's Building and Construction Authority codes require BIM-AI integration for public projects above SGD 50 million, creating pull-through demand for predictive scheduling platforms.
- OSHA Workplace Safety Directives:Enhanced enforcement of real-time hazard monitoring in the United States accelerates computer vision deployment for fall detection and equipment proximity alerts.
- Material Price Volatility:Dynamic steel and lumber pricing fluctuations drive contractor demand for machine learning cost estimation tools that update forecasts weekly rather than monthly.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in AI training hardware creates procurement bottlenecks for construction AI startups seeking edge-computing infrastructure.
- Liability Allocation Uncertainty:Ambiguous fault determination between software vendors and contractors under the EU AI Act's high-risk system category delays autonomous equipment deployment.
- Data Interoperability Gaps:Proprietary BIM formats from Autodesk and Bentley Systems fragment training datasets, degrading algorithm accuracy across heterogeneous project environments.
Strategic Opportunities
- German Building Performance Standards:The EU Green Deal's energy efficiency mandates create regulatory tailwinds for AI-driven HVAC optimization and carbon footprint tracking tools.
- Drywall Layout Robotics:Field robotics convergence with BIM-to-field automation addresses skilled labor shortages in interior finishing trades across North American commercial construction.
- Pay-per-Project Financing:Usage-based SaaS models lower adoption barriers for mid-tier contractors in the United Arab Emirates, expanding addressable market beyond enterprise accounts.
Industry Challenges
- Edge Computing Integration:Retrofitting legacy jobsite sensor networks with AI-enabled processing units demands capital expenditure that conflicts with contractor cash-flow cycles.
- Model Certification Timelines:Third-party validation of computer vision safety systems under Singapore's BCA codes extends product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) in Construction Market |
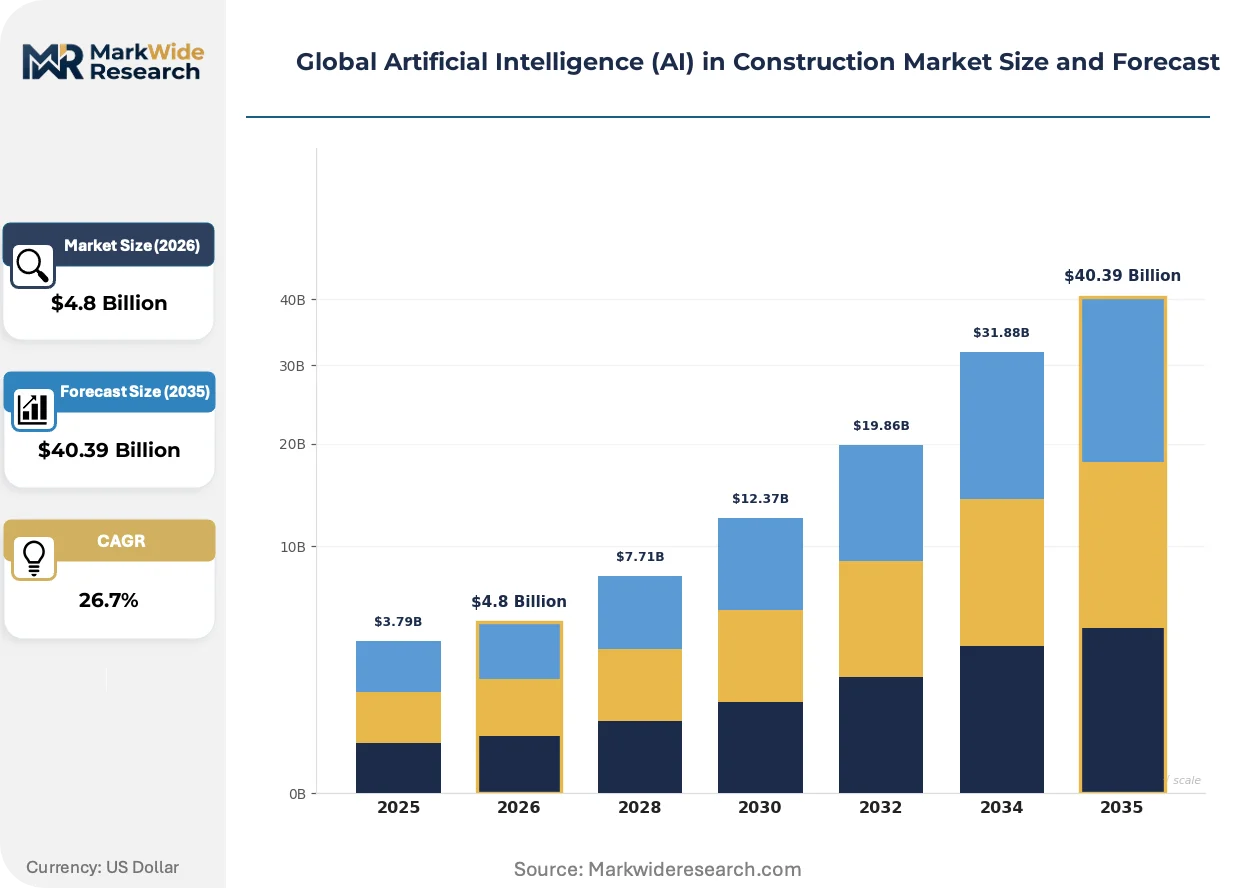
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics, Predictive Analytics, Expert Systems Solution: Project Planning Software, Safety Monitoring Systems, Quality Inspection Tools, Resource Management Platforms, Autonomous Equipment, Cost Estimation Tools Application: Site Monitoring, Risk Assessment, Construction Robotics, Project Scheduling, Inventory Management, Equipment Maintenance End User: General Contractors, Engineering Firms, Project Managers, Building Inspectors, Infrastructure Developers, Construction Consultants |
| Companies Covered | ALICE Technologies, Mastt, Procore Technologies, Buildots, Bentley Systems, Autodesk, Dusty Robotics, Trimble, OpenSpace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) in Construction Market Shifts & Advancements
Generative design algorithms and federated learning architectures are compressing the traditional design-to-construction handoff, enabling real-time iteration that was previously constrained by sequential workflow silos.
Digital twin platforms are collapsing the distinction between design-phase simulation and operational-phase optimization. Large infrastructure operators in Germany now deploy unified models that ingest live sensor feeds from bridges and tunnels, compressing maintenance decision cycles from quarterly reviews to continuous monitoring. This convergence eliminates redundant data translation layers between EPC contractors and asset owners.
The EU AI Act's high-risk system classification for autonomous construction equipment imposes conformity assessment obligations that favor established vendors with dedicated compliance teams. European contractors face 12-18 month certification timelines for computer vision safety systems, diverting procurement budgets toward pre-certified platforms rather than experimental deployments. German and Dutch regulators are coordinating implementation guidance to reduce cross-border friction.
General contractors in Southeast Asia are consolidating vendor relationships around integrated platforms that bundle scheduling, safety, and payment workflows. Singapore-based firms now require AI tool providers to demonstrate subcontractor payment integration before pilot approval, displacing point solutions that lack financial workflow connectivity. This preference consolidation concentrates procurement authority with platform vendors possessing deep ERP integration capabilities.
Global Artificial Intelligence (AI) in Construction Market Segmentation
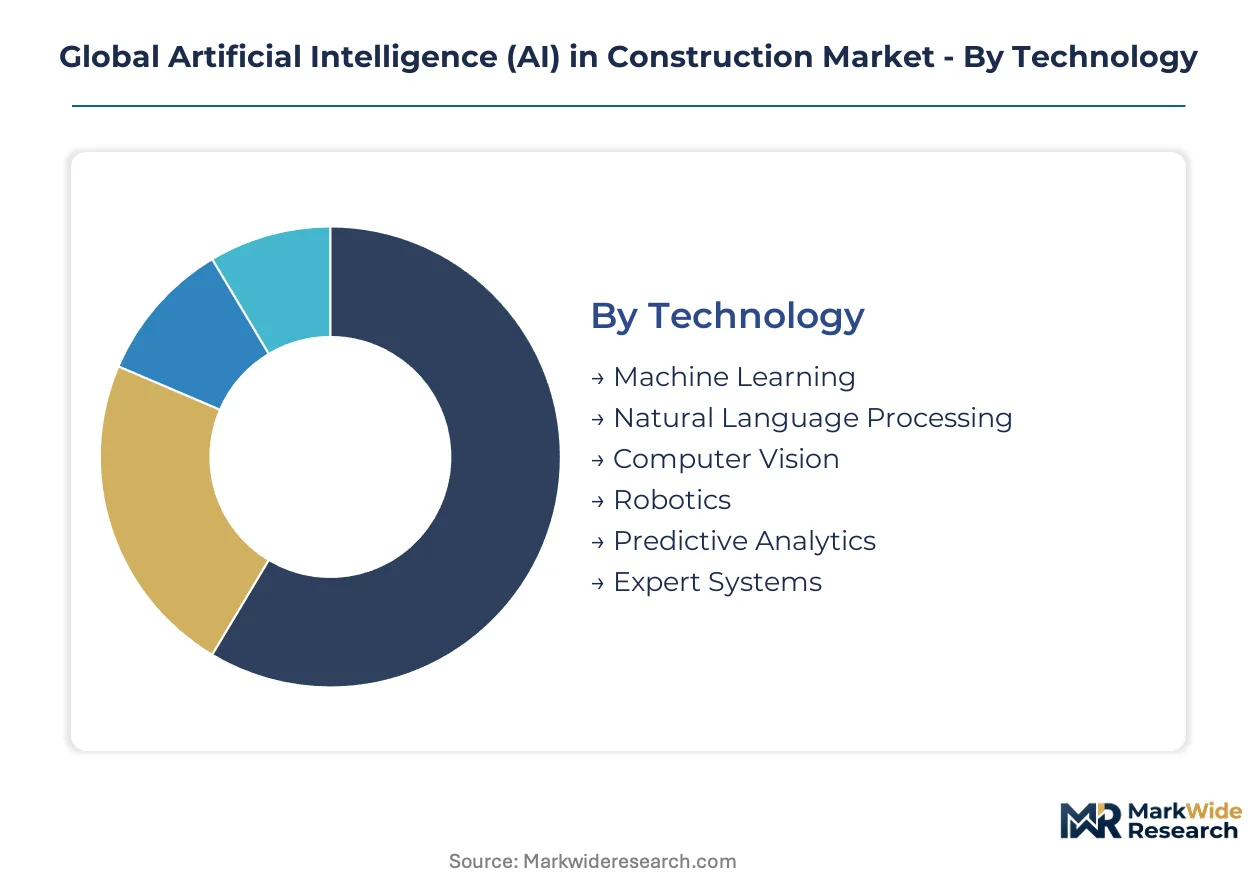
Construction AI segments diverge sharply in deployment velocity. Computer vision safety tools achieve full rollout within 6-12 months, while autonomous equipment faces 18-36 month certification cycles. Understanding these temporal patterns guides vendor resource allocation and contractor procurement sequencing.
Technology:
Machine Learning and Computer Vision turn over fastest as contractors pilot and scale hazard detection algorithms quarterly. Expert Systems and Robotics move slowest due to validation protocols and physical integration requirements.
- Computer Vision:Real-time image processing algorithms analyze jobsite video feeds for PPE compliance, fall risks, and equipment proximity violations. Singapore's BCA mandates this technology for public projects above SGD 50 million, compressing procurement cycles for certified vendors.
- Machine Learning:Pattern recognition systems process historical project data to forecast cost overruns and schedule slippage. Dynamic steel and lumber pricing volatility drives contractor demand for weekly forecast updates rather than monthly static estimates.
- Predictive Analytics:Statistical models aggregate sensor data to anticipate equipment failures before occurrence.
- Natural Language Processing:Text analysis tools extract compliance obligations from regulatory documents and contract clauses.
- Robotics:Physical automation systems execute layout, welding, and material handling tasks with minimal human intervention.
- Expert Systems:Rule-based engines encode veteran engineering knowledge for quality assurance and code compliance verification.
Computer Vision dominates installed base. Machine Learning is where expansion concentrates.
Solution:
Cost Estimation Tools and Safety Monitoring Systems spread fastest through mid-tier contractors using pay-per-project financing. Autonomous Equipment and Resource Management Platforms penetrate slowest due to capital intensity and ERP integration complexity.
- Cost Estimation Tools:ML-powered platforms dynamically adjust material and labor forecasts based on real-time pricing feeds and productivity benchmarks. German contractors prioritize these tools to meet EU Green Deal carbon budgeting requirements for public tenders.
- Safety Monitoring Systems:Integrated hardware-software bundles deploy edge-computing cameras with cloud-based incident dashboards. OSHA enforcement of real-time hazard monitoring in the United States accelerates replacement of manual inspection workflows.
- Project Planning Software:BIM-integrated platforms optimize sequencing and resource allocation across multi-phase developments.
- Quality Inspection Tools:Automated defect detection systems compare as-built conditions against design specifications.
- Resource Management Platforms:Workforce and equipment scheduling systems balance utilization across concurrent projects.
- Autonomous Equipment:Self-operating machinery for excavation, grading, and material transport reduces labor dependency.
Safety Monitoring Systems dominate installed base. Cost Estimation Tools are climbing the fastest.
Application:
Site Monitoring and Project Scheduling achieve broadest adoption through SaaS delivery models. Construction Robotics and Equipment Maintenance expand most slowly due to hardware requirements and specialized technician shortages.
- Site Monitoring:Continuous sensor networks track progress, safety compliance, and environmental conditions across active work zones. UAE infrastructure developers mandate these systems for mega-project oversight, creating reference architectures for regional adoption.
- Project Scheduling:AI-optimized critical path methods adjust timelines dynamically as constraints emerge. Singapore's BIM-AI integration requirements for public projects pull through predictive scheduling platform procurement.
- Risk Assessment:Quantitative models evaluate financial, safety, and schedule risks across project portfolios.
- Construction Robotics:Automated systems execute repetitive physical tasks with precision exceeding manual capabilities.
- Inventory Management:Demand forecasting algorithms optimize just-in-time material delivery to reduce site congestion.
- Equipment Maintenance:Predictive models analyze vibration, temperature, and usage patterns to schedule service interventions.
Site Monitoring dominates installed base. Project Scheduling is gaining share fastest.
End User:
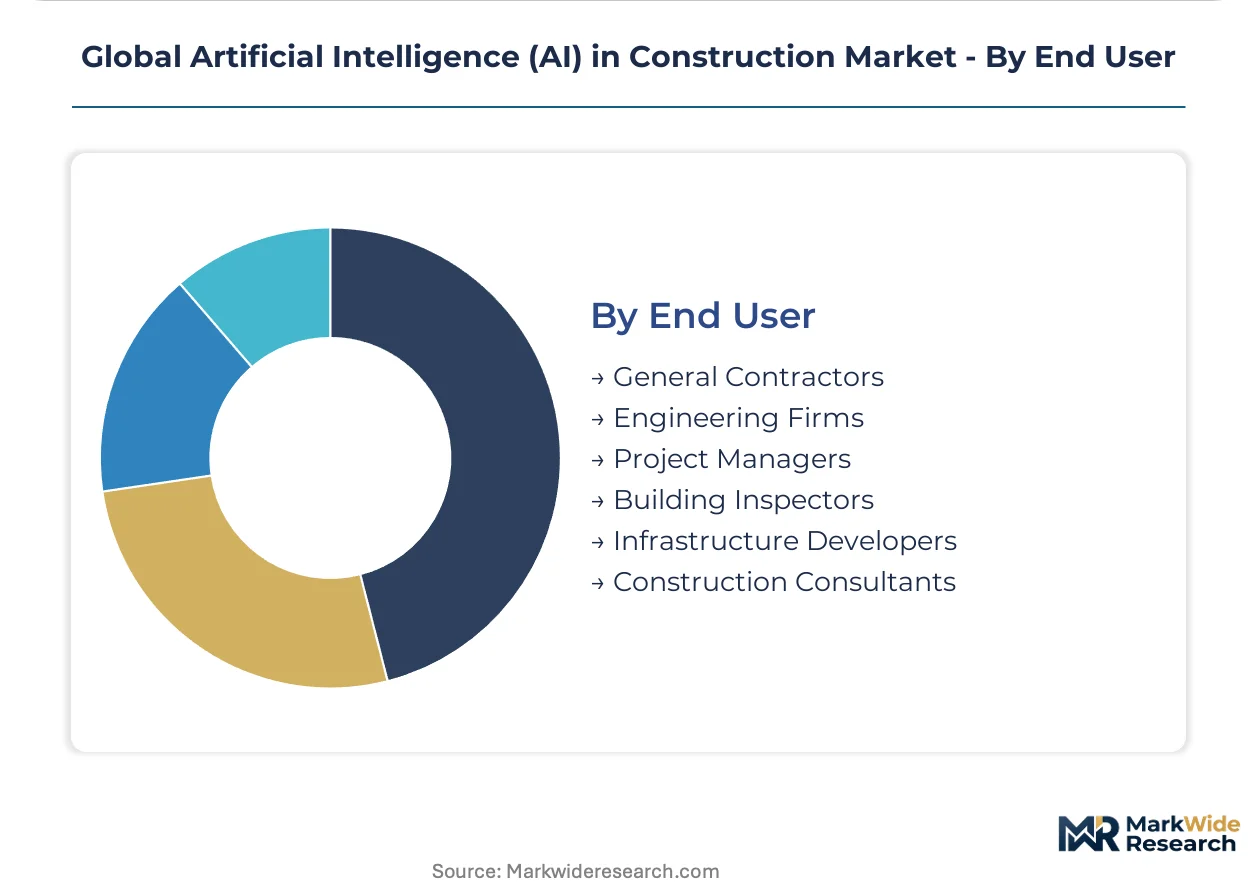
General Contractors and Project Managers adopt AI tools fastest through platform consolidation strategies. Building Inspectors and Construction Consultants move slowest due to fragmented procurement authority and legacy workflow inertia.
- General Contractors:Prime firms deploy integrated AI suites spanning scheduling, safety, and payment workflows. Southeast Asian contractors now require subcontractor payment integration before pilot approval, concentrating procurement with platform vendors possessing deep ERP connectivity.
- Project Managers:Specialist coordinators leverage predictive analytics to mediate between design teams and field operations. German EPC firms deploy unified digital twin models that compress maintenance decision cycles from quarterly reviews to continuous monitoring.
- Engineering Firms:Design-phase specialists apply generative algorithms to optimize structural and MEP system configurations.
- Infrastructure Developers:Long-term asset owners prioritize operational-phase optimization tools for lifecycle cost reduction.
- Building Inspectors:Regulatory compliance officers utilize automated documentation tools to accelerate permit approvals.
- Construction Consultants:Advisory practices deploy benchmarking analytics to validate client project performance claims.
General Contractors dominate installed base. Project Managers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction AI technology flows concentrate in net-importing markets where digitized project delivery commands premium pricing, while software development and algorithm training clusters concentrate in technology-exporting economies with deep engineering talent pools.
United States
Federal infrastructure spending and private commercial development drive deployment of predictive scheduling and computer vision safety systems. OSHA workplace safety directives mandate real-time hazard monitoring, accelerating replacement of manual inspection workflows. California and Texas construction corridors anchor demand concentration, with Bay Area technology clusters supplying adjacent algorithm development capabilities.
Germany
Energy-efficient building retrofits and large-scale infrastructure maintenance create demand for AI-driven HVAC optimization and digital twin platforms. EU Green Deal building performance standards and EU AI Act compliance requirements reshape procurement specifications for construction software. The Rhine-Ruhr and Munich-Stuttgart corridors concentrate both engineering firm demand and industrial software vendor development activity.
Singapore
Smart city infrastructure mandates and public project scale requirements pull through BIM-AI integration platforms. Building and Construction Authority codes require predictive scheduling systems for projects above SGD 50 million, compressing vendor certification timelines. The city-state functions as regional reference architecture for Southeast Asian adoption, with procurement decisions influencing neighboring Malaysia and Indonesia markets.
United Arab Emirates
Mega-project development and sovereign wealth-funded infrastructure expansion sustain demand for site monitoring and project oversight systems. MOHAP and local building codes establish data governance frameworks for construction technology deployment. Dubai and Abu Dhabi development authorities mandate AI-enabled progress tracking for contracts above defined thresholds, creating standardized procurement templates.
China
Urban rail transit expansion and high-speed rail maintenance networks deploy predictive analytics for equipment lifecycle management. MIIT standards and GB construction technology regulations shape domestic vendor certification requirements. Yangtze River Delta and Pearl River Delta metropolitan clusters concentrate both project execution volume and domestic AI construction software development capacity.
Global Artificial Intelligence (AI) in Construction Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors with deep ERP connectivity, while point-solution specialists compete through vertical application depth. Three archetypes dominate: design-heritage software incumbents extending into construction intelligence, construction-native platform vendors anchoring subcontractor financial workflows, and field robotics specialists automating discrete physical tasks. Competitive dynamics center on strategic partnerships with general contractors and portfolio diversification into adjacent construction workflow modules.
Within the design-heritage tier, Autodesk and Bentley Systems occupy positions anchored by proprietary BIM formats that shape data interoperability standards. Procore Technologies exemplifies the construction-native platform archetype, with platform stickiness sustained through payment workflow integration. Dusty Robotics represents the field robotics specialization vector, competing through physical automation of interior finishing tasks. Trimble and OpenSpace sit within the site intelligence and reality capture segment, while ALICE Technologies and Buildots occupy positions in predictive analytics and progress monitoring respectively. Mastt represents emerging vendor activity in project finance integration.
| Leading Market Players |
|---|
| ALICE Technologies |
| Mastt |
| Procore Technologies |
| Buildots |
| Bentley Systems |
| Autodesk |
| Dusty Robotics |
| Trimble |
| OpenSpace |
| Others |
Supply & Pricing Matrix
NVIDIA's dominance in AI training hardware concentrates upstream supply for construction AI vendors, pushing margin pools toward software layer differentiation and compliance documentation services rather than raw compute provisioning. Contractors face procurement bottlenecks for edge-computing infrastructure while SaaS pricing models absorb hardware cost volatility through subscription tiers.
Pricing Analysis
Mid-tier contractors anchor pricing structure through pay-per-project financing that segments the market across certified-premium, standard-API, and basic-telemetry tiers. Price differentiation rests on EU AI Act compliance certification and BIM integration depth, with certified platforms commanding premiums over point solutions. Cost compression in the basic tier intensifies because GPU supply constraints squeeze startup margins. General contractors show least price sensitivity due to platform consolidation strategies, while specialty subcontractors remain most cost-conscious.
Supply Chain Analysis
Foxconn and Wistron hold contract-manufacturing capacity for edge-computing hardware deployed across construction sites, with assembly concentrated in Taiwan, Vietnam, and Mexico. Component sourcing draws from South Korean memory suppliers, Japanese sensor manufacturers, and Chinese PCB fabricators. Single-source vulnerability in NVIDIA GPU allocation creates procurement risk for computer vision safety system vendors. Distribution runs through direct enterprise sales teams and construction technology reseller networks serving regional contractor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of EU AI Act compliance expertise and certified BIM-AI integration engineers constrains vendor expansion velocity, privileging incumbents with dedicated regulatory teams over resource-constrained challengers.
For Market Incumbents: Harden platform stickiness by deepening subcontractor payment workflow integration before emerging ERP-native challengers replicate Procore's financial connectivity. Invest in backward integration into edge-computing hardware design to reduce NVIDIA supply dependency. Prioritize certification investment for computer vision safety systems under Singapore BCA codes to compress 8-14 month validation timelines. For New Entrants and Emerging Players: Build out vertical specialization in drywall layout robotics and interior finishing automation where skilled labor shortages create immediate contractor demand. Target mid-tier UAE contractors through usage-based SaaS models that bypass enterprise procurement complexity. Pursue go-to-market partnerships with regional ERP vendors lacking native AI construction modules. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed construction software platforms seeking portfolio add-ons in predictive analytics and digital twin capabilities. Long-term viability over a 5-10 year horizon depends on EU AI Act compliance infrastructure becoming table stakes rather than differentiator. Monitor certification timeline compression at Singapore BCA and German KBA coordination as inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certification investments unlock procurement budgets at German and Dutch contractors facing 12-18 month validation cycles. |
| Subcontractor Payment Integration | Deep ERP connectivity satisfies Singapore-based general contractor pilot approval requirements displacing point solutions. |
| Edge-Computing Hardware Partnership | Strategic alliances with NVIDIA distributors mitigate GPU allocation bottlenecks constraining computer vision deployment. |
| BIM-Native Platform Development | Proprietary format compatibility with Autodesk and Bentley Systems reduces data interoperability gaps degrading algorithm accuracy. |
| Pay-per-Project Financing Launch | Usage-based models expand addressable market beyond enterprise accounts into mid-tier UAE and Southeast Asian contractors. |
Research Methodology
Initial hypotheses were tested against primary input from construction technology procurement officers, BIM implementation leads, and EPC project directors and refined through secondary validation. Construction AI vendor executives, OSHA compliance consultants, and EU regulatory affairs specialists contributed qualitative perspective. Secondary sources included SEC 10-K filings from listed software vendors, EU AI Act implementation guidance documents, Singapore BCA code amendments, and hyperscaler capex disclosures. Bottom-up project pipeline aggregation and top-down technology spending estimates were triangulated to anchor market sizing.
Demand-supply-balance framing shaped the analytical approach across the analysis window, with segmentation modeled by technology type, solution category, application workflow, and end-user archetype. CAGRs were derived from fitted growth curves calibrated to regulatory mandate timelines and contractor adoption survey data. Forecast inputs incorporated smart city infrastructure budget allocations, material price volatility indices, and GPU supply allocation forecasts.
Sensitivities concentrate around EU AI Act enforcement timeline shifts, NVIDIA supply allocation changes, and Singapore BCA code expansion to private projects. Forecasts reflect assumptions on regulatory coordination between German and Dutch authorities and contractor platform consolidation velocity. Quarterly review of certification backlog durations and mid-tier contractor SaaS conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
US Voice Recognition Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market