
 Semantic Web Market | 2026-2036
Semantic Web Market Size, Share, and Industry Trends Forecast 2026-2036
Semantic Web Market Analysis
Buyer concentration in the Semantic Web space is shifting as enterprise procurement teams fragment across mid-sized manufacturers and public-sector data publishers that previously relied on centralized IT vendors. Syapse sustains clinical-data interoperability contracts with oncology networks that require RDF-based semantic layers. Wikimedia Foundation anchors open-knowledge graph infrastructure that competes with commercial ontology services. Perfect Memory specializes in semantic content-management platforms for media archives seeking automated metadata enrichment.
The Semantic Web comprises machine-readable data architectures built on W3C standards including Resource Description Framework (RDF) triples, Web Ontology Language (OWL) class hierarchies, and SPARQL query protocols that enable automated inference across distributed datasets. Its primary commercial purpose is to replace brittle keyword search with context-aware retrieval that connects entities across siloed databases. Knowledge Graphs applications command the deepest margin pools because enterprise buyers pay premiums for relationship-aware analytics that surface non-obvious connections. Cloud-based deployment is expanding fastest as hyperscalers integrate SPARQL endpoints into managed data services that reduce ontology engineering overhead for customers lacking in-house expertise.
ISO semantic-metadata standards intersect with the EU AI Act's explainability requirements to create compliance-driven demand for auditable knowledge-graph provenance in European deployments. The US FDA's structured-data mandates for pharmaceutical submissions and HIPAA's interoperability provisions shape how healthcare vendors architect semantic data layers for regulated industries. Stakeholders must monitor whether emerging national AI governance frameworks will mandate open linked-data standards or permit proprietary knowledge-graph formats that fragment vendor ecosystems.
Market Dynamics
Enterprise procurement of linked-data infrastructure is fragmenting across mid-sized manufacturers and public-sector data publishers, breaking the historical concentration of centralized IT vendor relationships that dominated early semantic web deployments.
Growth Catalysts
- EU AI Act explainability mandates:The regulation requires auditable knowledge-graph provenance for high-risk AI systems, forcing European enterprises to invest in RDF-based semantic layers that trace data lineage.
- Industrial supply-chain traceability:German automotive and manufacturing consortia are deploying OWL ontologies to track component provenance across tiered supplier networks.
- SPARQL endpoint integration:Cloud hyperscalers are embedding managed semantic query services into data platforms, reducing ontology engineering barriers for buyers lacking in-house expertise.
Market Restraints
- Ontology engineering labor scarcity:The specialized skill set combining formal logic, domain expertise, and W3C standards knowledge commands premium wages that inflate project costs.
- Proprietary knowledge-graph lock-in:Commercial vendors use non-standard extensions that fragment interoperability and raise switching costs for enterprise buyers.
- Legacy data silo fragmentation:Relational database estates resist automated RDF conversion without costly schema reconciliation and quality remediation.
Strategic Opportunities
- Healthcare interoperability acceleration:The US FDA structured-data mandates for pharmaceutical submissions create compliance-driven demand for semantic data layers in life sciences.
- Media archive metadata automation:Broadcasters and streaming platforms seek automated content enrichment using NLP-to-RDF pipelines that reduce manual cataloging overhead.
- Convergence of knowledge graphs with LLMs:Retrieval-augmented generation architectures use SPARQL-accessible ontologies to ground generative outputs in verified enterprise knowledge.
Industry Challenges
- Schema reconciliation complexity:Merging heterogeneous enterprise ontologies requires expensive manual curation that delays production deployments.
- Certification timeline compression:Regulated industries face extended validation cycles for semantic systems that must demonstrate inference accuracy under FDA and EMA scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semantic Web Market |
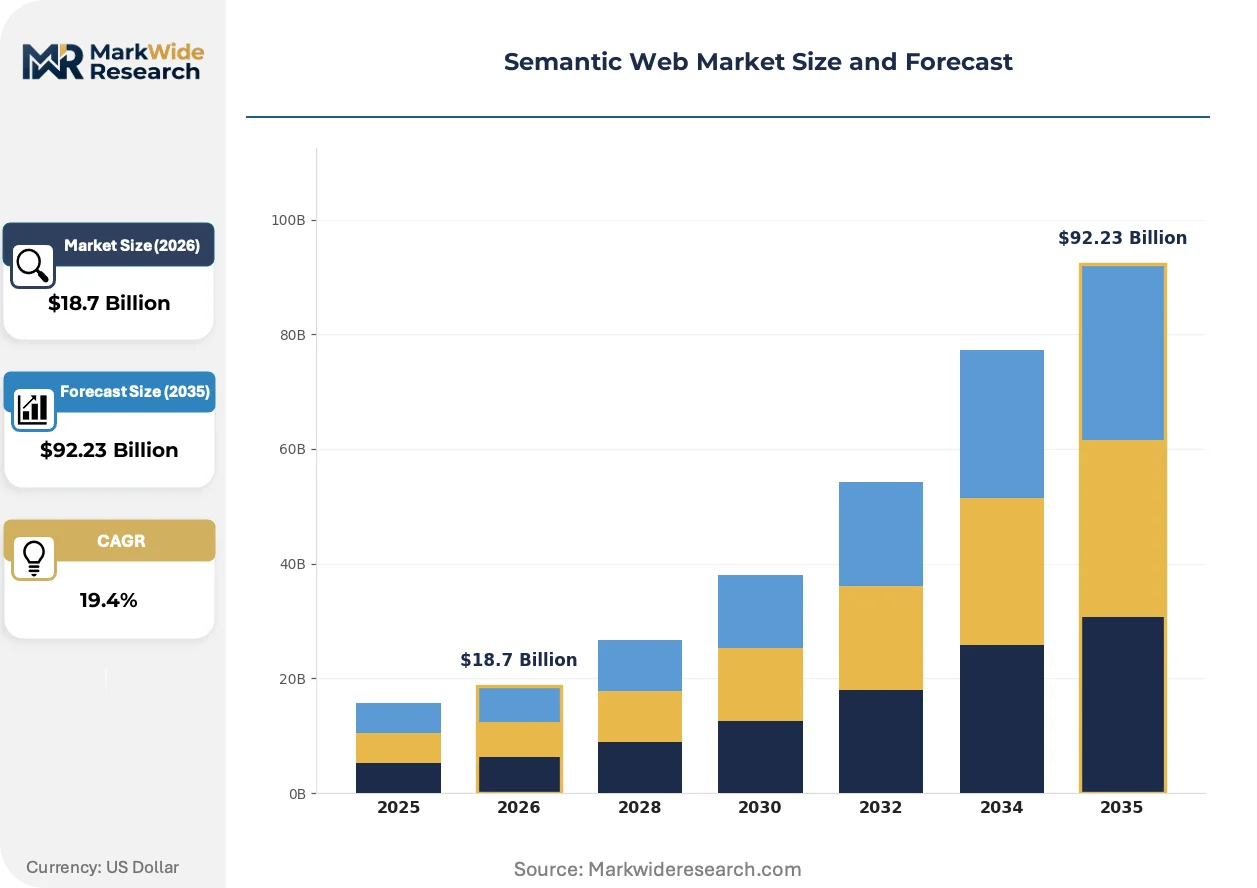
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RDF, OWL, SPARQL, Linked Data Application: Search Engines, Content Management, Data Integration, Knowledge Graphs End User: Enterprises, Startups, Academic Institutions, Government Agencies Deployment: Cloud-based, On-premises, Hybrid, Open Source |
| Companies Covered | Galaksiya Bilişim Teknolojileri, Perfect Memory, OpenRisk Technologies Inc., Syapse, webRunes, Semantic Web Tech Private Limited, SEMKNOX GmbH, Wikimedia Foundation, Redlink GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semantic Web Market Emerging Trajectories
Knowledge graph architectures are undergoing rapid technical evolution as vendors integrate generative AI interfaces, automated ontology learning, and real-time streaming inference to expand addressable use cases beyond static enterprise search.
Graph neural networks are converging with semantic web stacks to enable predictive relationship inference across incomplete datasets. Pharmaceutical discovery teams at research-intensive institutions deploy these hybrid architectures to surface non-obvious molecular connections. The technology is converging with traditional SPARQL-based query systems to compress the gap between statistical pattern detection and symbolic reasoning transparency.
The EU AI Act's risk-classification framework mandates explainable data provenance for automated decision systems operating in European jurisdictions. Industrial manufacturers deploying supply-chain knowledge graphs must now document RDF triple lineage to satisfy conformity assessments. German automotive suppliers are investing in auditable ontology versioning systems to preempt regulatory scrutiny of AI-driven procurement algorithms.
Buyer expectations for self-service semantic tooling are reshaping vendor roadmaps away from professional-services-heavy deployments. Mid-market enterprises in the Netherlands and Nordic countries now demand low-code ontology editors and automated schema mapping that bypass traditional consulting engagements. Healthcare data publishers in the US are piloting subscription-based knowledge-graph APIs that unbundle infrastructure from implementation services.
Semantic Web Market Segmentation
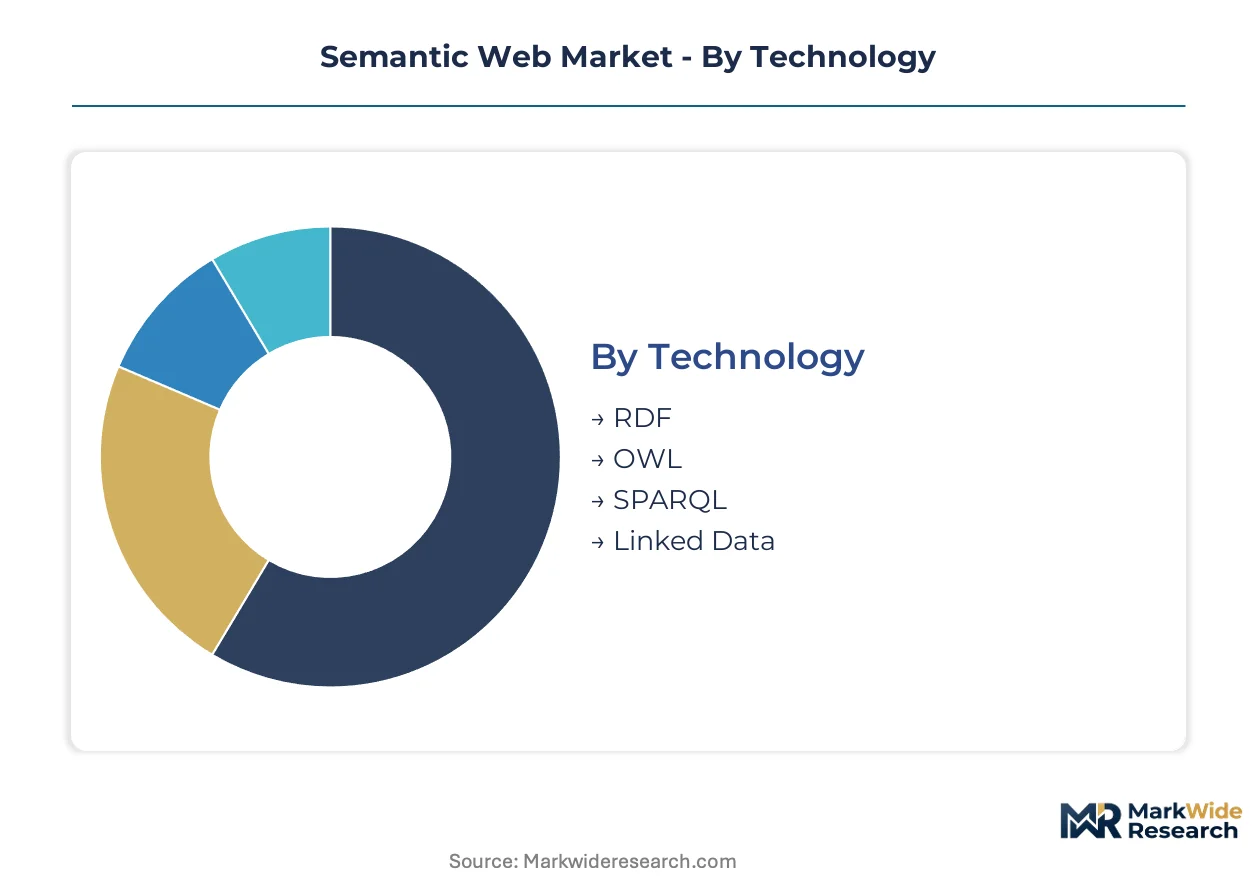
Semantic Web procurement patterns diverge sharply across technology stacks and deployment models. Enterprise buyers prioritize provenance-auditable architectures in regulated sectors while mid-market adopters chase cloud-managed services that mask underlying complexity.
Technology:
Volume deployments favor lightweight RDF implementations. Premium stacks integrate multiple W3C standards with custom inference engines.
- RDF:Resource Description Framework triples form the foundational data model for machine-readable statements about resources. German automotive suppliers deploy RDF-based component traceability to satisfy EU AI Act lineage requirements. Mature deployment sits with RDF. Newer deployment is concentrated in SPARQL.
- OWL:Web Ontology Language enables formal class hierarchies and logical inference across distributed datasets. Pharmaceutical discovery teams at US research institutions leverage OWL for molecular relationship mapping under FDA structured-data mandates.
- SPARQL:The standardized query protocol retrieves and manipulates RDF data through graph-pattern matching. Hyperscalers embed managed SPARQL endpoints to capture mid-market buyers lacking ontology engineering expertise.
- Linked Data:Publishing paradigms connect dereferenceable URIs across organizational boundaries. Wikimedia Foundation infrastructure anchors open-knowledge graphs competing with commercial ontology services.
Standardization pressure from European regulators accelerates migration toward SPARQL-accessible architectures.
Application:
Knowledge-intensive use cases command implementation premiums. Search and content management compete on automation depth.
- Search Engines:Context-aware retrieval replaces brittle keyword matching through entity disambiguation and relationship traversal. Media broadcasters in the Netherlands deploy semantic search to automate archive metadata enrichment.
- Content Management:Automated metadata extraction and ontology-driven tagging reduce manual cataloging overhead. Perfect Memory specializes in semantic content-management platforms for media archives seeking automated enrichment pipelines.
- Data Integration:Schema reconciliation tools bridge relational silos with RDF representations. Legacy database estates resist automated conversion without costly quality remediation.
- Knowledge Graphs:Relationship-aware analytics surface non-obvious connections across enterprise datasets. Syapse sustains clinical-data interoperability contracts with oncology networks requiring RDF-based semantic layers.
Healthcare and life sciences concentrate premium spending. Media and public sector adoption climbs fastest.
End User:
Enterprise procurement fragments across departmental buyers. Academic and government demand anchors open-source sustainability.
- Enterprises:Mid-sized manufacturers and public-sector data publishers fragment procurement across specialized vendors rather than centralized IT relationships. Industrial consortia in Germany deploy semantic standards for supply-chain traceability.
- Startups:Venture-backed firms leverage cloud-managed SPARQL services to bypass ontology engineering labor scarcity. Nordic low-code tooling demand reshapes vendor roadmaps toward self-service interfaces.
- Academic Institutions:Research libraries and digital humanities centers maintain open-knowledge graph infrastructure. Wikimedia Foundation competes with commercial ontology services for institutional partnerships.
- Government Agencies:Public-sector data publishers mandate interoperable standards for transparency and service delivery. EU AI Act explainability requirements drive investment in auditable knowledge-graph provenance.
Enterprise buyers dominate current revenue. Government compliance mandates steepest expansion trajectory.
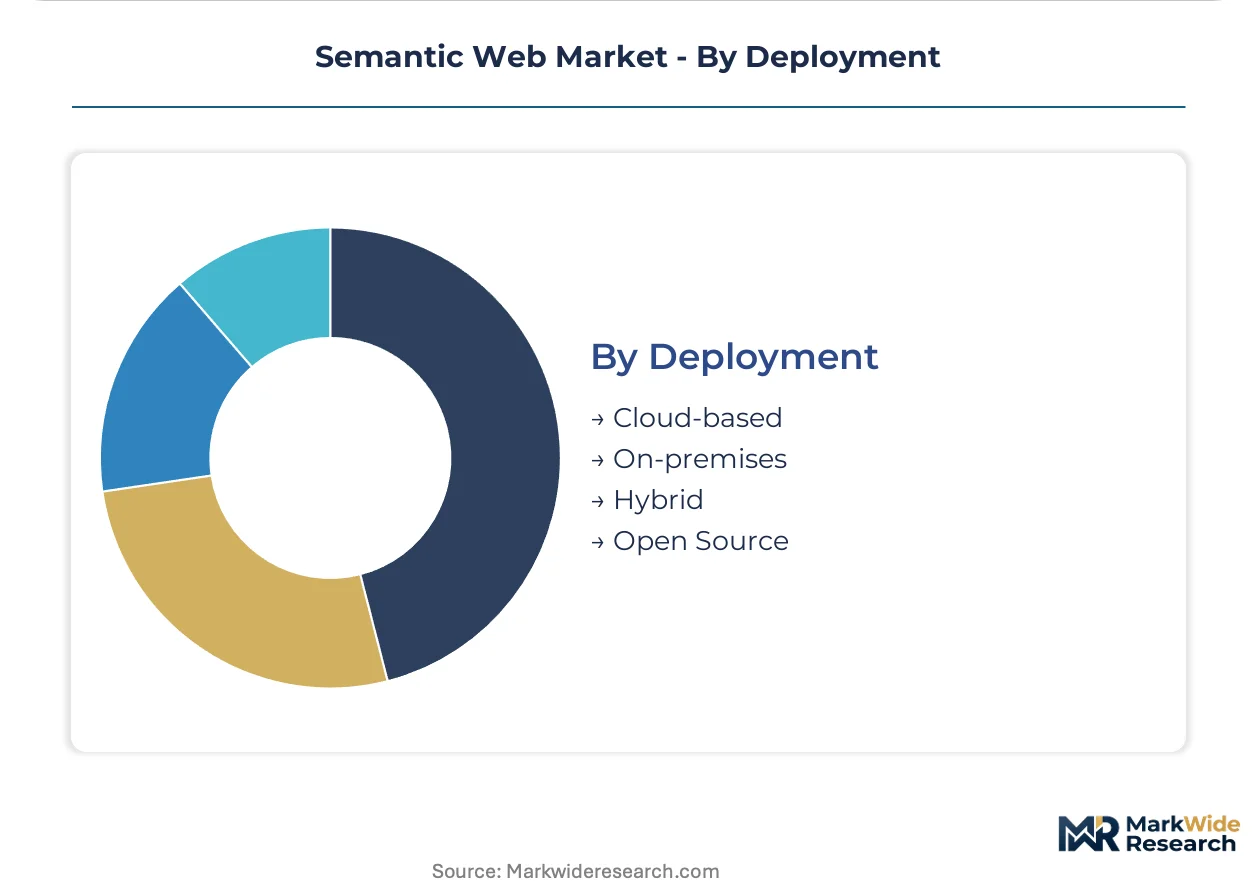
Deployment:
Cloud absorption accelerates as hyperscalers bundle semantic services. On-premises retains regulatory-driven niches.
- Cloud-based:Managed SPARQL endpoints and ontology-as-a-service reduce engineering barriers for buyers lacking in-house expertise. Hyperscaler integration captures mid-market demand in the Netherlands and Nordic countries.
- On-premises:Air-gapped installations satisfy data sovereignty and security requirements in defense and intelligence sectors. Certification timeline compression extends validation cycles for regulated deployments.
- Hybrid:Sensitive data remains on-premises while query federation extends to cloud-hosted knowledge graphs. Financial services firms partition customer records from aggregated analytics.
- Open Source:Community-maintained tools reduce licensing costs for academic and government deployments. Apache Jena and Eclipse RDF4J anchor non-commercial implementation stacks.
Cloud configurations gain share fastest. On-premises deployments defend position in national security and healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial consortia anchor European procurement of RDF-based supply-chain infrastructure. Cloud hyperscalers in the United States and Netherlands capture mid-market demand for managed SPARQL services. Academic institutions in Switzerland and the United Kingdom sustain open-source knowledge graph development.
United States
FDA structured-data mandates drive pharmaceutical investment in semantic data layers for regulatory submissions. HIPAA interoperability provisions shape healthcare vendor architectures for auditable knowledge-graph provenance. Research-intensive institutions in the Greater Boston area deploy OWL ontologies for molecular relationship mapping under federal scrutiny.
Germany
Automotive and manufacturing consortia deploy OWL ontologies to track component provenance across tiered supplier networks. EU AI Act explainability requirements force investment in RDF-based semantic layers that trace data lineage. Industrial clusters in Bavaria and Baden-Württemberg pilot auditable ontology versioning systems for AI-driven procurement algorithms.
Netherlands
Mid-market enterprises demand low-code ontology editors and automated schema mapping that bypass traditional consulting engagements. GDPR interoperability mandates accelerate migration toward SPARQL-accessible architectures. Media broadcasters in the Randstad region deploy semantic search to automate archive metadata enrichment.
United Kingdom
Public-sector data publishers mandate interoperable standards for transparency and service delivery. Research libraries in the London-Southeast corridor maintain open-knowledge graph infrastructure competing with commercial ontology services. Digital humanities centers anchor non-commercial implementation stacks using Apache Jena and Eclipse RDF4J.
Switzerland
Pharmaceutical discovery teams at research-intensive institutions deploy hybrid architectures combining graph neural networks with semantic web stacks. Swissmedic regulatory frameworks shape validation cycles for semantic systems demonstrating inference accuracy. Life sciences clusters in the Basel region invest in relationship-aware analytics surfacing non-obvious molecular connections.
Semantic Web Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-managed SPARQL services and low-code ontology tooling. The vendor base spans specialized semantic content-management platforms, clinical-data interoperability specialists, and open-knowledge graph infrastructure providers. Three archetypes dominate: compliance-focused healthcare vendors, media archive automation specialists, and community-anchored open-source foundations. Competitive moves concentrate on strategic partnerships with hyperscalers and portfolio diversification into generative AI convergence.
Within the healthcare interoperability tier, Syapse represents clinical-data specialists sustaining contracts with oncology networks requiring RDF-based semantic layers. Among media-focused vendors, Perfect Memory exemplifies content-management platforms serving broadcasters seeking automated metadata enrichment. The open-knowledge segment sees Wikimedia Foundation anchoring non-commercial infrastructure that competes with commercial ontology services for institutional partnerships.
| Leading Market Players |
|---|
| Galaksiya Bilişim Teknolojileri |
| Perfect Memory |
| OpenRisk Technologies Inc. |
| Syapse |
| webRunes |
| Semantic Web Tech Private Limited |
| SEMKNOX GmbH |
| Wikimedia Foundation |
| Redlink GmbH |
| Others |
Supply Flow & Price Mechanics
Specialized ontology engineering labor indices cascade through semantic web procurement tiers, compressing margins for project-based deployments while inflating premiums for managed SPARQL services that mask skills scarcity.
Pricing Analysis
Warranty and implementation service bundling separates enterprise-grade knowledge graph deployments from unbundled API-access tiers targeting mid-market buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under EU AI Act scrutiny and customization intensity. Pricing pressure stems from hyperscaler commoditization of baseline SPARQL endpoints, eroding standalone vendor margins. Public-sector data publishers exhibit highest price sensitivity due to budget rigidity, while pharmaceutical sponsors under FDA mandates absorb premium tiers without elasticity.
Supply Chain Analysis
Dual-sourcing requirements for ontology engineering talent compel buyers to qualify multiple implementation partners across Germany, the Netherlands, and the United States. Supply concentration draws from formal logic specialists in Swiss academic clusters, domain-expert consultants in Greater Boston, and cloud-managed service providers in Amsterdam. Single-source vulnerability sits with legacy RDF conversion tooling vendors facing acquisition. Distribution runs through hyperscaler marketplaces and specialized systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors possessing auditable provenance capabilities, as EU AI Act compliance costs extinguish pure-play tooling providers lacking certification infrastructure.
For Market Incumbents: Extend managed SPARQL service portfolios to capture mid-market buyers fleeing high-touch consulting engagements. Deepen vertical integration into automated ontology learning pipelines that reduce labor dependency. Defend against emerging low-code entrants by embedding EU AI Act conformity assessment pre-certification into platform subscriptions. For New Entrants and Emerging Players: Begin with cloud-native SPARQL endpoints targeting Dutch and Nordic mid-market enterprises underserved by legacy vendor professional services. Exploit white-space in media archive metadata automation where broadcasters seek NLP-to-RDF pipelines without implementation overhead. Pursue channel partnerships with hyperscalers to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor clinical-data interoperability specialists in the United States facing FDA validation cost compression. Long-term viability hinges on convergence positioning with generative AI retrieval-augmented generation architectures. Monitor SPARQL endpoint attach rates as the inflection signal separating sustainable platforms from services-dependent vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Hyperscalers | Embedding SPARQL endpoints into AWS and Azure data services captures mid-market buyers lacking ontology expertise. |
| Acquisition of Specialist Ontology Firms | Absorbing OWL engineering teams in Germany addresses labor scarcity constraining project delivery capacity. |
| EU AI Act Pre-Certification Program | Auditable provenance tooling satisfies EMA scrutiny for pharmaceutical knowledge graph deployments. |
| Geographic Expansion into Netherlands | Low-code tooling demand in Randstad media clusters outpaces incumbent professional-services coverage. |
| Strategic Partnership with Wikimedia Foundation | Open-knowledge graph alignment competes for academic and government institutional procurement. |
Methodological Framework
Independent corroboration across ontology engineering directors, healthcare CIOs, and pharmaceutical regulatory affairs leads underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with knowledge graph architects at German automotive suppliers, data publishers at UK research libraries, and integration specialists at Dutch broadcasters. Secondary validation drew from EMA structured-data guidance documents, FDA submission databases, and hyperscaler service catalog disclosures. Bottom-up deployment estimates triangulated against top-down market sizing from W3C standards adoption metrics.
Rate-of-change decomposition across the projection horizon separates volume expansion in cloud-managed services from value capture in regulated healthcare applications. Segmentation dimensions modeled include technology stack complexity, deployment model, end-user sophistication tier, and regional regulatory cluster. CAGR derivation weighted historical ontology engineering project velocity against compliance-mandated acceleration under EU AI Act timelines. Industry-specific inputs incorporated SPARQL endpoint provisioning rates and pharmaceutical sponsor RDF submission volumes.
Underlying measurement precision varies by segment; cloud deployment metrics carry tighter precision than on-premises certification timelines. Forecasts reflect assumptions about hyperscaler bundling strategies and regulatory enforcement intensity. Deviation in EU AI Act conformity assessment timelines or FDA structured-data mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
AI Image Recognition Market