
 Europe Artificial Intelligence Market | 2026-2036
Europe Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Artificial Intelligence Market Intelligence
Mid-sized automotive suppliers are redrawing procurement patterns for AI-enabled quality control and predictive maintenance systems. Helsing GmbH leverages defense-sector partnerships to sustain sovereign AI capabilities for European military applications. Dataiku competes through no-code platform specialization that lowers deployment barriers for manufacturing clients lacking deep data-science benches. Celonis anchors process-mining demand by extending AI-driven workflow optimization across SAP-dominated enterprise environments in Germany and France.
Artificial intelligence in Europe encompasses machine-learning algorithms, neural network architectures, and natural-language processing systems trained on regionally governed datasets with GDPR-mandated privacy constraints. These technologies automate pattern recognition, decision support, and generative content production across industrial and consumer applications. Natural language processing leads solution demand as enterprises deploy multilingual models for regulatory documentation and customer service automation. Cloud-based deployment captures growth momentum as France and the Netherlands expand sovereign cloud infrastructure compliant with EU data-residency rules. AI-as-a-Service offerings concentrate margin pools through recurring revenue structures that reduce upfront capital requirements for healthcare and retail adopters.
The EU AI Act establishes risk-based classification requirements that reshape product development timelines for computer vision and autonomous systems deployed in public spaces. EMA guidance on AI-enabled diagnostic tools tightens clinical-validation standards, while GDPR enforcement by CNIL and other national regulators constrains training-data sourcing strategies. Stakeholders must monitor harmonized standards under development by CEN-CENELEC to determine which compliance pathways will govern market access for robotics and edge-computing solutions.
Market Dynamics
The EU AI Act's risk-based classification system is compressing product development timelines while redirecting R&D budgets toward compliance infrastructure for high-risk applications in public safety and healthcare.
Growth Catalysts
- Automotive autonomy mandates:Germany's KBA and France's ANSM are accelerating validation frameworks for Level 3+ systems, pulling neural-network training demand from Stuttgart and Munich clusters into production-scale deployment.
- GDPR-compliant data infrastructure:Sovereign cloud buildouts in France and the Netherlands are removing legal friction for cross-border model training, enabling healthcare and financial services adopters to pool datasets previously siloed by residency rules.
- EMA diagnostic guidance:Tightened clinical-validation standards for AI-enabled imaging tools are creating procurement pull from radiology departments seeking pre-certified solutions that de-risk technology assessment committees.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in training hardware creates input cost volatility and delivery uncertainty for European model developers lacking direct allocation agreements.
- CEN-CENELEC standardization lag:Absence of harmonized technical specifications for robotics and edge-AI systems forces redundant national certification cycles, extending time-to-revenue for hardware vendors.
- Training-data sourcing constraints:GDPR enforcement by CNIL and other national regulators limits web-scraping and historical dataset reuse, inflating data-acquisition costs for multilingual model development.
Strategic Opportunities
- Defense-sector sovereign AI:NATO procurement frameworks and national military budgets in Germany, France, and Poland are creating protected demand pools for classified-model development outside commercial export controls.
- Process-mining convergence:Integration of AI-driven workflow optimization with existing SAP deployments in German and French enterprises offers white-space expansion for vendors with pre-built connector libraries.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are generating demand for AI-powered emissions-tracking and supply-chain transparency tools among mid-cap manufacturers seeking automated compliance.
Industry Challenges
- MLE talent scarcity:Competition for machine-learning engineers from US-based labs and hyperscalers is compressing retention rates at European AI startups and industrial-software vendors.
- Legacy system integration:Manufacturing clients with decades-old SCADA and MES infrastructure face multi-year retrofit cycles to enable real-time inference at the edge, delaying ROI realization.
- High-risk certification timelines:EU AI Act conformity assessment procedures for biometric identification and critical infrastructure systems extend product launch windows by 12-18 months compared to low-risk categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Artificial Intelligence Market |
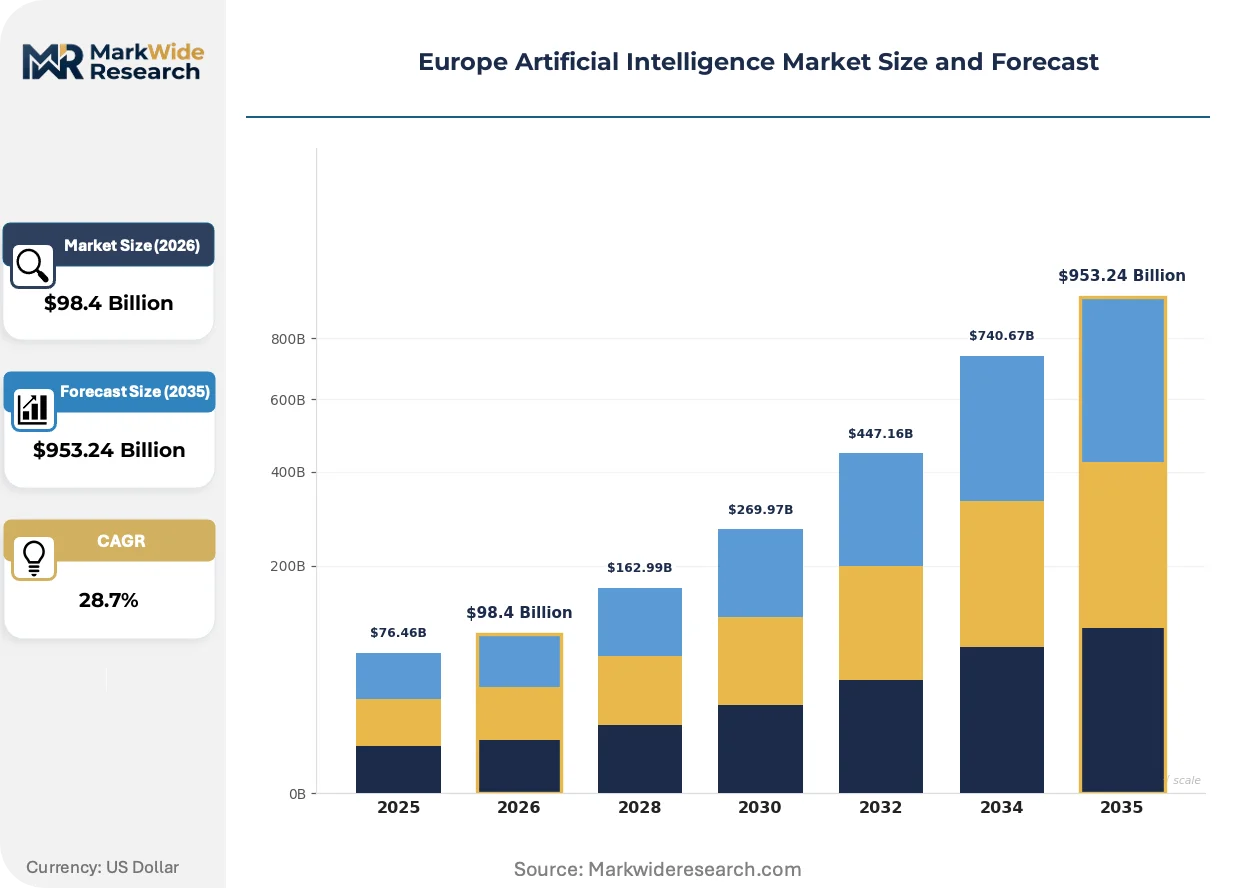
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $953.24 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Natural Language Processing, Machine Learning, Computer Vision, Robotics End User: Healthcare, Retail, Automotive, Manufacturing Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution: AI Platforms, AI-Optimized Hardware, AI Software Tools, AI-as-a-Service |
| Companies Covered | Mistral AI, Aleph Alpha, Helsing GmbH, DeepL, Synthesia, Wayve, Evolution AI, Dataiku, Celonis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Artificial Intelligence Market Strategic Shifts & Innovations
Foundation-model architectures are fragmenting into specialized variants optimized for regulatory constraints, industrial latency requirements, and domain-specific reasoning tasks rather than general-purpose scale.
Small-language-model compression is fragmenting deployment economics for manufacturing quality-control and predictive-maintenance applications. Automotive suppliers in Baden-Württemberg are adopting sub-10B parameter models that run on edge hardware without cloud dependency, reducing inference latency below 50 milliseconds for real-time defect detection. This shift is fragmenting vendor margins between hyperscaler API revenues and on-premise licensing fees.
The EU AI Act's prohibited-practices list and high-risk system obligations are forcing architectural redesigns for computer-vision vendors serving public-space surveillance and recruitment automation. France's CNIL has issued early enforcement guidance on biometric classification systems, pushing developers toward explainability-by-design approaches that document decision pathways for audit trails. German robotics firms are responding by embedding technical documentation modules directly into product firmware.
Mid-sized manufacturers are unbundling AI software procurement from system-integration services, creating direct vendor relationships that bypass traditional IT consultancies. Industrial clients in the Netherlands and Belgium are negotiating seat-based subscriptions for no-code machine-learning platforms rather than project-based SOWs, compressing sales cycles from 18 months to 90 days. This pattern is most visible among food-processing and packaging equipment operators seeking autonomous quality assurance without dedicated data-science hires.
Europe Artificial Intelligence Market Segmentation
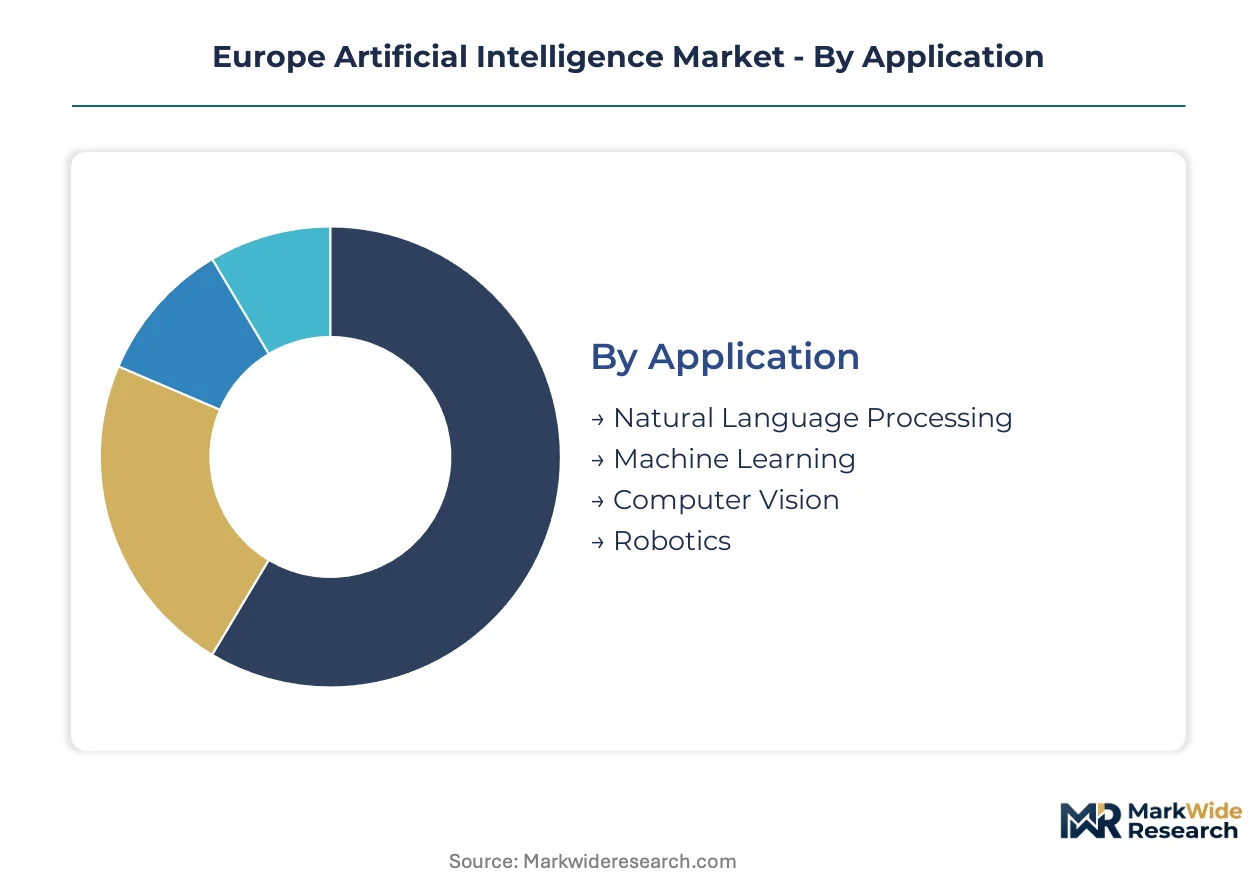
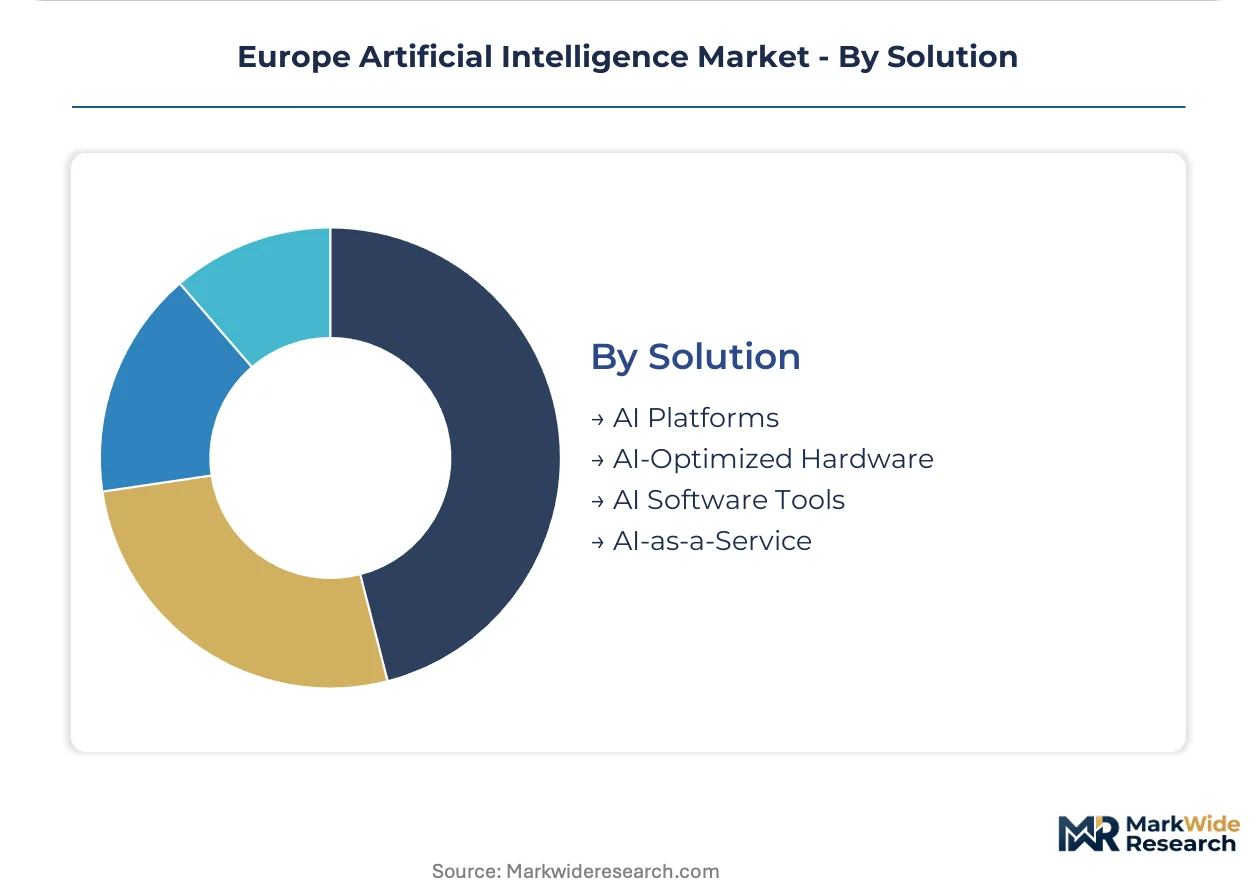
AI market segmentation in Europe reflects divergent compliance burdens and infrastructure maturity across member states. Procurement patterns cluster around GDPR-constrained deployment modes and sector-specific validation requirements under the EU AI Act.
Application:
Natural Language Processing faces intensifying substitution pressure from open-source multilingual models that erode proprietary API margins.
- Natural Language Processing:Multilingual transformer architectures process regulatory documentation and customer service automation across EU official languages. Demand concentrates in Frankfurt and Paris financial services clusters driven by MiFID II compliance documentation requirements. GDPR constraints on training data sourcing inflate development costs for region-specific models.
- Machine Learning:Supervised and unsupervised algorithms power predictive analytics for industrial quality control and demand forecasting. Stuttgart automotive suppliers deploy gradient-boosted frameworks for supply-chain optimization under KBA validation protocols. MLOps tooling shortages extend deployment timelines for mid-sized manufacturers.
- Computer Vision:Convolutional neural networks enable defect detection and biometric classification in manufacturing and security applications.
- Robotics:Sensor fusion and motion-planning algorithms automate warehouse logistics and precision assembly in Bavarian industrial zones.
Natural Language Processing retains volume leadership; Computer Vision holds the steepest expansion curve amid EU AI Act high-risk classification timelines.
End User:
Cost tier differentiation separates validated healthcare deployments from experimental retail implementations.
- Healthcare:Diagnostic imaging and clinical decision-support systems require EMA pre-certification and CE marking under MDR. Procurement concentrates in German university hospitals and French public hospital networks seeking de-risked technology assessment. Tighter clinical-validation standards compress vendor selection pools.
- Automotive:Autonomous driving development and predictive maintenance systems anchor neural-network training demand. Munich and Stuttgart engineering centers validate Level 3+ systems under KBA frameworks. NVIDIA GPU allocation agreements determine development velocity for European OEMs.
- Manufacturing:Predictive maintenance and quality-control automation retrofit decades-old SCADA infrastructure in Baden-Württemberg.
- Retail:Demand forecasting and customer-analytics deployments face GDPR consent-management complexity in Dutch and Belgian markets.
Automotive commands the highest per-deployment value; Manufacturing offers the broadest addressable base across mid-cap suppliers.
Deployment:
Volume concentration shifts toward sovereign cloud infrastructure as France and the Netherlands complete GDPR-compliant data-residency buildouts.
- Cloud-Based:Hyperscaler and sovereign cloud offerings reduce upfront capital requirements through subscription models. French healthcare adopters migrate diagnostic workloads to ANSSI-certified facilities meeting GDPR Article 44 transfer restrictions. Recurring revenue structures attract private-equity backing for platform vendors.
- Edge Computing:Sub-50-millisecond inference requirements drive on-device model compression for real-time manufacturing quality control. Baden-Württemberg automotive suppliers deploy sub-10B parameter models without cloud dependency. Hardware cost premiums constrain adoption outside high-value defect-detection applications.
- On-Premises:Air-gapped installations persist in defense and classified government applications with NATO procurement frameworks.
- Hybrid:Split architectures balance training-scale cloud compute with inference-stage edge localization for latency-sensitive workloads.
Cloud-Based retains volume leadership; Edge Computing gains share fastest amid automotive autonomy latency requirements.
Solution:
Margin pools concentrate in recurring-revenue service models that reduce customer data-science hiring burdens.
- AI-as-a-Service:Subscription APIs for computer vision and natural language processing eliminate infrastructure ownership. Dutch and Belgian food-processing operators negotiate seat-based subscriptions compressing sales cycles to 90 days. Vendor margins fragment between hyperscaler economies of scale and specialized regional providers.
- AI Platforms:No-code and low-code environments enable manufacturing clients without dedicated data-science benches. German mid-caps deploy pre-built connectors for SAP-dominated enterprise environments. Platform stickiness depends on workflow integration depth.
- AI Software Tools:Framework-specific development environments and MLOps tooling address enterprise customization requirements.
- AI-Optimized Hardware:NVIDIA GPU dominance creates supply concentration and input cost volatility for European model developers.
AI-as-a-Service captures the steepest expansion trajectory; AI Platforms retain the deepest enterprise integration moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German AI software exports flow into French automotive and Dutch healthcare procurement channels, creating a north-south trade corridor that concentrates R&D investment in Baden-Württemberg and Bavaria.
Germany
KBA validation frameworks for Level 3+ autonomous systems and industrial predictive maintenance drive neural-network training demand. The EU AI Act's high-risk classification requirements compress development timelines for computer vision vendors. Stuttgart and Munich engineering clusters anchor automotive AI deployment, with suppliers retrofitting SCADA infrastructure for real-time edge inference.
France
ANSSI-certified sovereign cloud buildouts and CNIL enforcement on biometric systems reshape procurement for healthcare and public-sector adopters. EMA guidance on AI-enabled diagnostic tools tightens clinical-validation standards for imaging vendors. Paris and Lyon financial services clusters deploy multilingual NLP models for MiFID II compliance documentation under GDPR Article 44 constraints.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for life sciences and financial services AI deployments. The Medicines and Healthcare products Regulatory Agency issues distinct guidance on software-as-medical-device classifications. London's fintech and health-tech clusters attract venture funding for regulatory-technology platforms that bridge EU and UK conformity requirements.
Netherlands
GDPR-compliant data-residency infrastructure and CSRD disclosure mandates generate demand for emissions-tracking AI among mid-cap manufacturers. Dutch food-processing operators negotiate seat-based subscriptions for no-code quality assurance platforms. Eindhoven's high-tech systems cluster concentrates edge-computing hardware development for sub-50-millisecond manufacturing inference.
Poland
NATO procurement frameworks and national military budgets create protected demand pools for classified-model development outside commercial export controls. The country's central IT security authority aligns certification requirements with EU AI Act risk-based classifications. Warsaw and Krakow emerging tech clusters attract defense-sector AI investment from Western European primes seeking cost-competitive engineering talent.
Europe Artificial Intelligence Market Key Industry Players
Player mix skews toward specialized sovereign-AI developers and no-code platform vendors rather than horizontal hyperscaler competition. Market structure fragments across national defense procurement silos, GDPR-constrained cloud infrastructure, and sector-specific validation requirements. Two strategic archetypes dominate: defense-sector specialists leveraging classified partnerships, and manufacturing-focused platforms with pre-built SAP connectors. Competitive moves concentrate on M&A for MLOps tooling capabilities and strategic partnerships with sovereign cloud providers.
Within the defense-sector specialist tier, Helsing GmbH occupies a position anchored by European military procurement relationships outside commercial export frameworks. Among no-code platform vendors, Dataiku and Celonis exemplify divergent specialization paths—Dataiku represents the low-code deployment archetype for manufacturing clients lacking data-science benches, while Celonis anchors process-mining demand through workflow optimization integration with SAP-dominated enterprise environments in Germany and France.
| Leading Market Players |
|---|
| Mistral AI |
| Aleph Alpha |
| Helsing GmbH |
| DeepL |
| Synthesia |
| Wayve |
| Evolution AI |
| Dataiku |
| Celonis |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity assessment procedures gate both vendor qualification and price stratification simultaneously, compressing development timelines for high-risk biometric and autonomous systems while creating certification-premium tiers that separate pre-validated solutions from experimental deployments. German automotive OEMs and French healthcare networks now demand documented audit trails as a procurement prerequisite, inflating compliance costs that concentrate margin pools among vendors with established KBA and EMA validation pathways.
Pricing Analysis
Next-generation sovereign cloud offerings command 40-60% premiums over hyperscaler alternatives, while prior-generation on-premise licensing faces compression from subscription-model displacement. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth—EMA pre-certified diagnostic tools anchor the premium band, GDPR-compliant but uncertified NLP APIs occupy standard tiers, and open-source model fine-tuning services populate economy levels. Cost compression in the standard tier intensifies because Mistral and Aleph Alpha release competitive multilingual models. Mid-sized manufacturers in the Netherlands and Belgium exhibit highest price sensitivity, negotiating seat-based subscriptions below €500 monthly, while German automotive clusters demonstrate lowest sensitivity when latency guarantees fall below 50 milliseconds.
Supply Chain Analysis
Strategic stockpiling of NVIDIA H100 and upcoming Blackwell accelerators dominates inventory strategy among Stuttgart and Munich AI clusters, with German OEMs securing 12-18 month forward allocations to buffer against GPU supply volatility. Taiwan, South Korea, and the United States concentrate advanced semiconductor manufacturing, while European sovereign cloud buildouts in France and the Netherlands remain dependent on NVIDIA GPU imports. Supply chain risk centers on single-source vulnerability for training hardware, with no qualified European alternative to NVIDIA's CUDA ecosystem. Distribution runs through hyperscaler marketplaces for cloud-based AI services, direct enterprise sales for SAP-integrated platforms, and defense procurement frameworks for classified sovereign AI development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's AI market approaches a platform-economics inflection where SAP connector libraries and sovereign cloud interoperability determine vendor survival, with Celonis and Dataiku exemplifying divergent ecosystem-anchoring strategies that fragment competitive positioning between workflow-optimization depth and no-code accessibility.
For Market Incumbents: Consolidate MLOps tooling capabilities through targeted acquisition to defend against open-source model commoditization eroding proprietary API margins. Deepen SAP integration moats in German and French enterprise environments, embedding technical documentation modules directly into product firmware to preempt CNIL enforcement actions on explainability requirements. For New Entrants and Emerging Players: Differentiate on GDPR-compliant training-data sourcing as a service, addressing the €2-4 per-record cost inflation plaguing multilingual model development. Target Polish defense procurement frameworks and NATO classified-model development pools, where sovereign AI mandates create protected demand outside commercial export controls. Pursue direct seat-based subscription models with Dutch and Belgian food-processing operators, compressing sales cycles through pre-built quality-assurance connectors. For Investors and Strategic Acquirers: The EU AI Act's high-risk system obligations reshape the acquisition landscape toward vendors with pre-validated conformity assessment pathways and established relationships with KBA, EMA, or ANSSI. Long-term viability over the next decade hinges on regulatory moat depth rather than model scale alone. Prioritize targets with embedded firmware documentation and edge-deployment capabilities serving Baden-Württemberg automotive suppliers. Watch CEN-CENELEC harmonized standard publication as the critical inflection signal determining which compliance pathways govern robotics and edge-AI market access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built SAP connectors anchor workflow-optimization demand across German and French enterprises. |
| Acquisition of Specialist Firm | MLOps tooling capabilities compress deployment timelines for mid-sized manufacturers lacking data-science benches. |
| Strategic Partnership | Sovereign cloud alliances with ANSSI-certified providers remove GDPR Article 44 friction for healthcare adopters. |
| Product Launch | Sub-10B parameter edge models address sub-50-millisecond latency requirements in Stuttgart automotive clusters. |
| Geographic Expansion | Poland defense-sector presence captures NATO procurement frameworks outside commercial export controls. |
Research Approach
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners and secondary validation against SEC filings, hyperscaler capex disclosures, ANSSI certification databases, and EMA guidance documents anchors the qualitative findings. Bottom-up triangulation aggregates deployment data across German automotive clusters, French healthcare networks, and Dutch manufacturing operators, while top-down reconciliation against sovereign cloud infrastructure buildouts ensures segmentation consistency.
Sensitivity analysis across deployment model, organization size, vertical integration complexity, and regional adoption pattern informs the analytical framework throughout the projection horizon. Segmentation dimensions modeled include application type, end-user industry, deployment architecture, and solution delivery mode. CAGRs derive from regression analysis of historical adoption curves adjusted for EU AI Act implementation phases and GDPR enforcement intensity by national regulator.
Material uncertainties — GPU supply allocation volatility, CEN-CENELEC standardization delays, and EMA diagnostic guidance revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sovereign cloud completion timelines and defense procurement budget trajectories. Revision becomes warranted when high-risk system certification timelines compress or extend beyond modeled 12-18 month windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Brain Machine Interface Market