
 Latin America Artificial Intelligence Market | 2026-2036
Latin America Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Artificial Intelligence Market Intelligence
Data science talent scarcity across Brazil, Mexico, and Argentina is rotating toward cloud infrastructure and MLOps specializations, tightening supply for on-premises AI deployments. NVIDIA Corporation leverages its CUDA ecosystem to anchor GPU-accelerated training demand among Latin American research institutions. Softtek sustains nearshore delivery advantages for enterprise AI integration across Mexican and Colombian clients. IBM differentiates through Watson governance tooling that addresses emerging compliance requirements in regulated industries.
Artificial intelligence in Latin America encompasses machine learning algorithms, neural network architectures, and natural language processing systems deployed for automated decision-making, predictive inference, and pattern recognition across commercial and public sector operations. These technologies process structured and unstructured data streams through supervised, unsupervised, and reinforcement learning paradigms to optimize operational workflows, risk assessment, and customer interaction protocols. Machine learning dominates current deployment value due to its applicability across banking fraud detection and retail demand forecasting, while natural language processing exhibits the fastest trajectory as Portuguese and Spanish conversational AI matures for customer service automation. Cloud-based deployment captures the expanding margin pool as hyperscale providers extend region-specific data residency guarantees.
Brazil's Lei Geral de Proteção de Dados and Mexico's Federal Law on Protection of Personal Data shape algorithmic transparency mandates and cross-border data transfer restrictions for AI system operators. ANPD enforcement actions in Brazil and INAI guidance in Mexico are tightening consent frameworks for automated profiling in financial services and healthcare. Stakeholders must monitor evolving national AI strategies and data localization requirements as countries draft sector-specific algorithmic accountability rules.
Market Dynamics
Cloud infrastructure migration across Brazil, Mexico, and Argentina is fragmenting deployment architectures, forcing vendors to rebuild delivery models around data residency guarantees and sovereign cloud requirements rather than centralized hyperscale efficiency.
Growth Catalysts
- LGPD enforcement in Brazil:ANPD audit schedules for automated profiling systems are accelerating procurement of explainable AI tooling by financial institutions and healthcare providers seeking compliance certainty.
- Neural network compression:Edge-optimized model architectures are enabling computer vision deployment on legacy agricultural hardware across Argentina's Pampas region without full infrastructure replacement.
- Fintech sandbox expansion:Mexico's central bank regulatory sandbox for algorithmic credit scoring is opening controlled deployment pathways for alternative data scoring models previously blocked by traditional underwriting rules.
Market Restraints
- GPU supply concentration:NVIDIA's CUDA ecosystem dominance creates vendor lock-in risk for Latin American research institutions dependent on single-source accelerated computing infrastructure.
- Cross-border data friction:LGPD and Mexico's Federal Law on Protection of Personal Data impose conflicting cross-border transfer requirements that fragment regional AI service delivery models.
- Specialist talent scarcity:MLOps and cloud infrastructure expertise concentration in São Paulo and Mexico City leaves secondary markets dependent on expensive remote contracting arrangements.
Strategic Opportunities
- Portuguese-Spanish NLP maturity:Conversational AI systems trained on regional linguistic variants present first-mover advantages for customer service automation in underpenetrated Colombian and Chilean banking sectors.
- Algorithmic accountability frameworks:Draft sector-specific rules in Brazil and Mexico will create compliance service opportunities for governance tooling vendors ahead of formal enforcement timelines.
- Precision agriculture convergence:Computer vision crop monitoring systems combined with satellite imagery analytics are opening integrated subscription models for Argentine soybean and Brazilian sugarcane cooperatives.
Industry Challenges
- Legacy system integration complexity:Brazilian healthcare providers face multi-year electronic health record modernization timelines that delay AI diagnostic imaging deployment despite clinical demand.
- Model validation certification timelines:ANVISA and Mexico's national pharmaceutical regulator lack established pathways for algorithmic medical device approval, creating regulatory uncertainty for diagnostic AI vendors.
- Data labeling workforce gaps:High-quality training data preparation for computer vision applications requires specialized annotation labor pools concentrated in urban centers with insufficient regional scaling capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Artificial Intelligence Market |
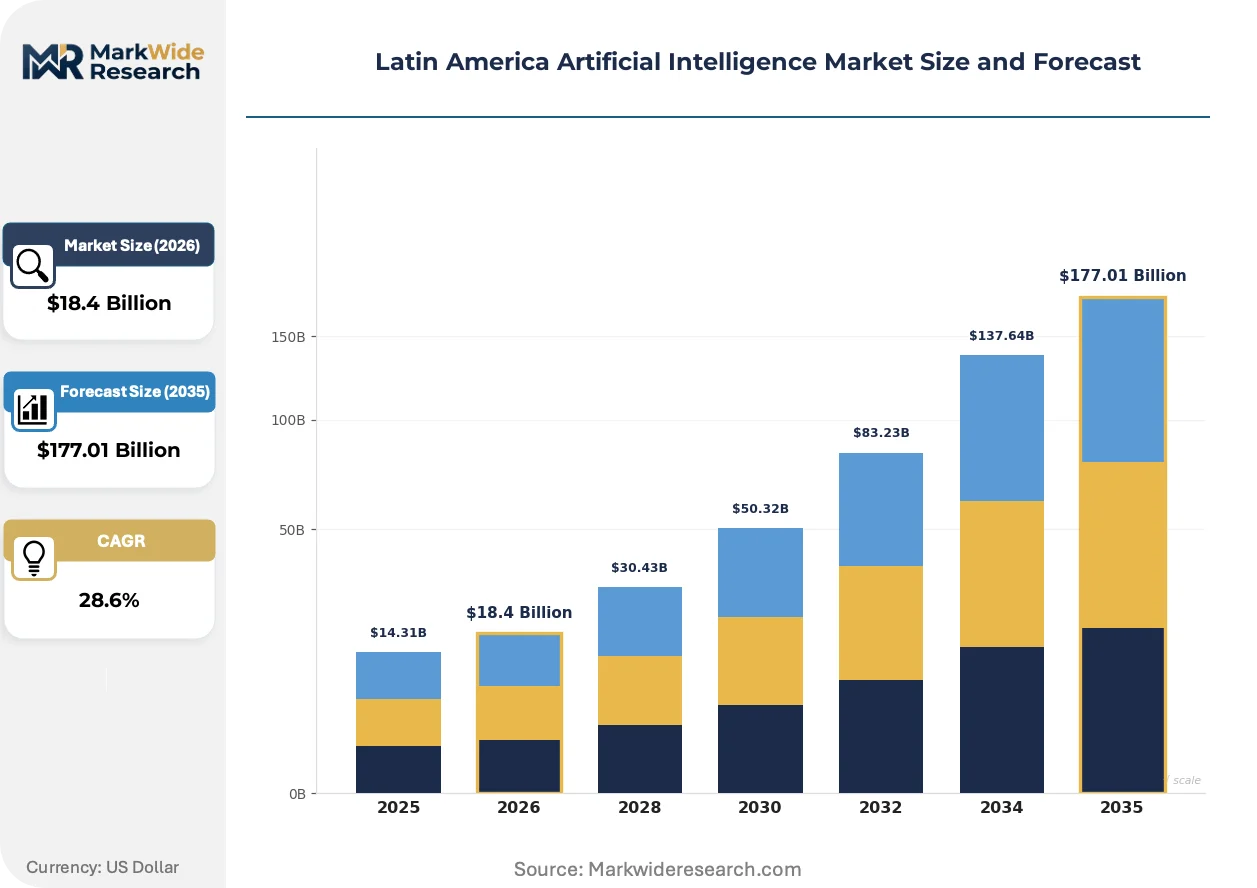
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $177.01 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Robotics, Computer Vision Application: Predictive Analytics, Customer Service Automation, Image Recognition, Fraud Detection End User: Healthcare, Retail, Banking, Manufacturing Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | NVIDIA Corporation, Softtek, IBM, Amazon Web Services, Advanced Micro Devices, Microsoft, Intel Corporation, InvGate, Google LLC, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Artificial Intelligence Market Strategic Shifts & Innovations
Foundation model architectures are reshaping competitive dynamics across Latin American AI deployment, compressing development timelines while raising new governance requirements that favor vendors with established regional compliance infrastructure.
Transformer-based large language models are fragmenting natural language processing deployment patterns across Brazilian financial services and Mexican retail operations. Mid-sized enterprises previously blocked by training cost barriers are adopting API-accessible foundation models for document processing and customer interaction automation. This technology diffusion is compressing margins for custom NLP development shops while expanding addressable market volume for inference-optimized service tiers.
Brazil's ANPD and Mexico's INAI are tightening consent frameworks for automated profiling through successive guidance clarifications that extend LGPD and Federal Law on Protection of Personal Data requirements into algorithmic decision-making contexts. Financial services operators in both countries are responding by embedding explainability modules into credit scoring and fraud detection pipelines ahead of formal audit mandates. Healthcare providers face parallel pressure as patient data processing for diagnostic AI triggers heightened consent documentation requirements.
Subscription-based AI service procurement is displacing perpetual license models across enterprise segments in São Paulo and Mexico City. Mid-market buyers are prioritizing consumption-scaled pricing that aligns software expenditure with actual inference volume rather than upfront capacity planning. Colombian and Chilean markets are exhibiting accelerated adoption of this procurement pattern as cloud-native vendors establish regional sales presence and local system integrators build managed service capabilities around hyperscaler platforms.
Latin America Artificial Intelligence Market Segmentation
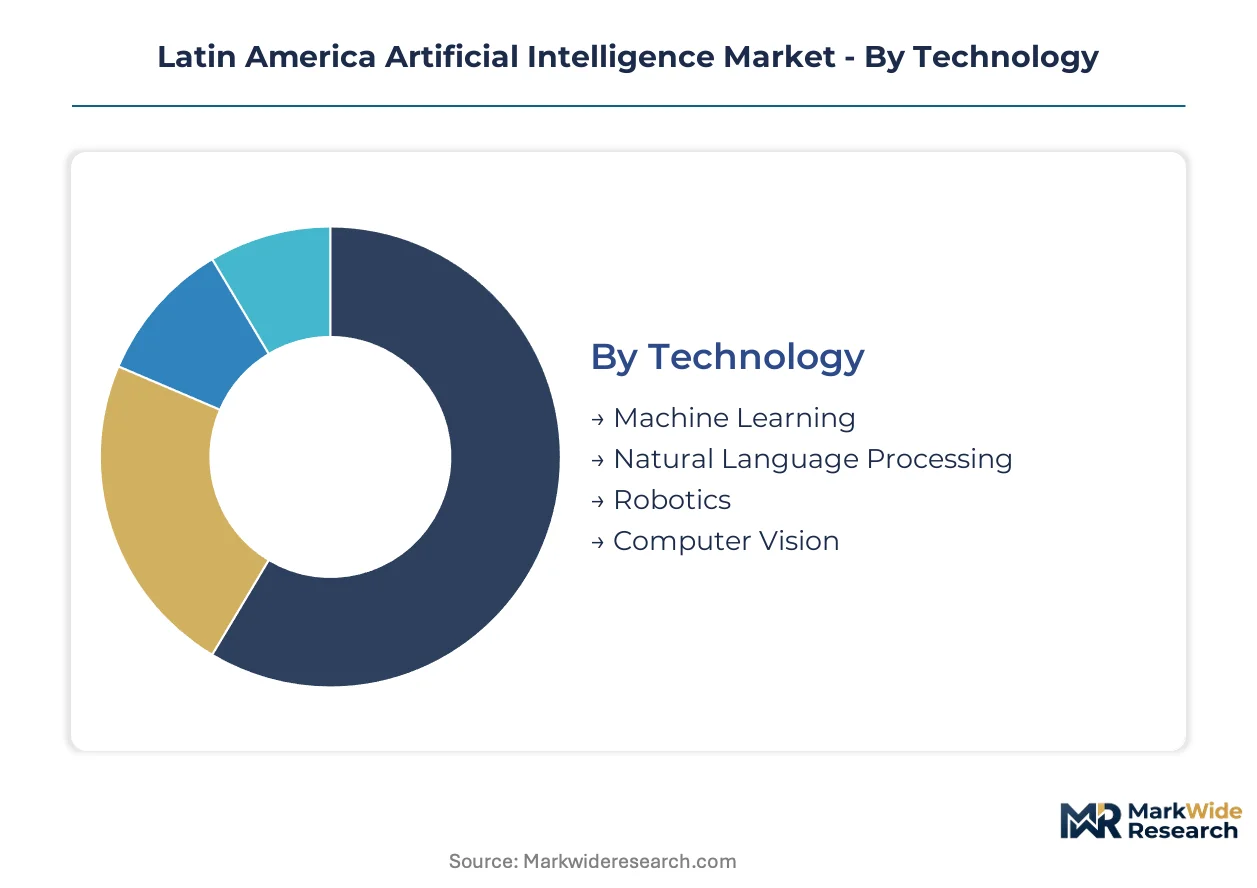
Segmentation reveals how AI demand fragments across technical capabilities, operational use cases, and infrastructure constraints in Latin America. Understanding these divisions exposes where substitution pressures from adjacent technologies reshape competitive boundaries and procurement priorities.
Technology:
Substitution pressure from foundation model APIs threatens custom development in traditional machine learning segments while opening new deployment pathways for previously cost-prohibitive capabilities.
- Machine Learning:Supervised and unsupervised algorithms process structured datasets for pattern recognition and predictive inference. Brazilian banking fraud detection and Mexican retail demand forecasting concentrate procurement volume, though API-accessible foundation models now substitute for custom model builds in mid-market accounts.
- Natural Language Processing:Transformer architectures enable Portuguese and Spanish conversational interfaces, sentiment analysis, and document extraction. Mexican fintech customer service automation and Colombian banking chatbots drive steepest demand expansion as linguistic variant training matures.
- Robotics:Autonomous systems integrate perception, planning, and control for physical task execution. Brazilian manufacturing assembly lines and Argentine agricultural automation represent primary deployment zones.
- Computer Vision:Neural networks classify, detect, and segment visual data streams. Argentine soybean crop monitoring and Brazilian sugarcane cooperative subscriptions anchor agricultural demand.
Machine Learning anchors the volume base while Natural Language Processing gains share at the steepest rate.
Application:
Cost tier differentiation separates enterprise-grade deployments with dedicated infrastructure from API-consumption models that compress margins while expanding addressable market reach.
- Predictive Analytics:Statistical and machine learning models forecast outcomes across operational, financial, and risk domains. Mexican algorithmic credit scoring within central bank sandbox regulations and Brazilian insurance underwriting drive regulatory-sensitive procurement.
- Customer Service Automation:Conversational AI and intelligent routing systems handle inquiry resolution without human intervention. Colombian and Chilean banking sectors present underpenetrated expansion opportunities as Portuguese-Spanish NLP capabilities mature.
- Image Recognition:Classification and detection algorithms process medical, industrial, and satellite imagery. Brazilian diagnostic imaging adoption accelerates despite ANVISA regulatory pathway uncertainty for algorithmic medical devices.
- Fraud Detection:Real-time transaction monitoring identifies anomalous patterns for financial risk mitigation. LGPD audit schedules accelerate explainable AI tooling procurement across Brazilian financial institutions seeking compliance certainty.
Predictive Analytics commands the largest installed base while Customer Service Automation exhibits the most rapid adoption trajectory among mid-market enterprises.
End User:
Maturity gaps between sectors create divergent implementation timelines, with regulated industries facing extended validation requirements that delay deployment despite demonstrated clinical or operational demand.
- Healthcare:Diagnostic imaging, clinical decision support, and operational optimization applications. Brazilian providers accelerate AI adoption for radiology workflows while electronic health record modernization timelines delay full integration.
- Retail:Demand forecasting, inventory optimization, and personalized recommendation engines. Mexican e-commerce platforms and Brazilian omnichannel operators concentrate procurement of customer-facing automation.
- Banking:Credit scoring, fraud detection, and regulatory compliance automation. LGPD and Federal Law on Protection of Personal Data shape algorithmic transparency mandates across Brazilian and Mexican institutions.
- Manufacturing:Predictive maintenance, quality inspection, and supply chain optimization. São Paulo industrial clusters drive initial deployment with secondary markets dependent on remote contracting arrangements.
Banking sustains the deepest technology penetration while Healthcare faces the steepest regulatory validation barriers despite acute clinical demand.
Deployment:
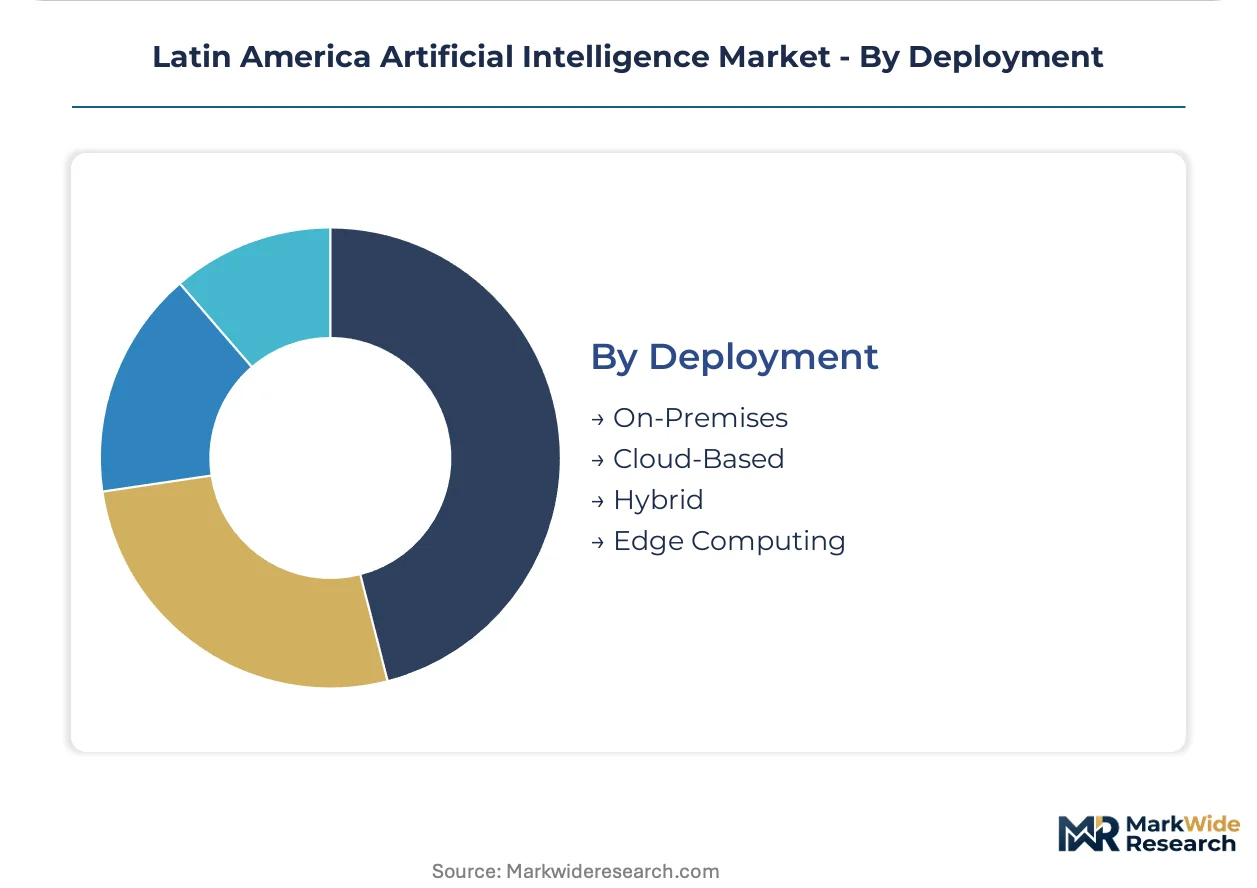
Data residency guarantees and sovereign cloud requirements fragment regional delivery models away from centralized hyperscale efficiency toward distributed architectures with localized compliance controls.
- On-Premises:Dedicated hardware installations within organizational facilities for maximum data control. Brazilian healthcare providers and financial institutions with legacy infrastructure maintain this model despite talent scarcity for MLOps specialization.
- Cloud-Based:Hyperscaler-hosted infrastructure with consumption-scaled pricing and regional data residency options. São Paulo and Mexico City enterprise segments accelerate subscription procurement aligned to actual inference volume.
- Hybrid:Workload distribution across on-premises and cloud environments with orchestrated data flows. Cross-border data friction between LGPD and Mexican transfer requirements complicates regional service delivery for multi-country operators.
- Edge Computing:Model inference on localized devices with limited or intermittent connectivity. Neural network compression enables Argentine Pampas agricultural deployment without full infrastructure replacement.
Cloud-Based deployment captures the expanding margin pool while Edge Computing climbs fastest from minimal base as compression techniques mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANPD enforcement schedules in Brazil are accelerating AI governance procurement across Latin America's largest economy while Mexico's central bank fintech sandbox and Argentina's agricultural automation clusters shape sub-regional demand patterns.
Brazil
Healthcare providers in São Paulo and Rio de Janeiro are deploying diagnostic imaging algorithms for radiology workflow optimization. ANPD audit timelines for automated profiling systems are forcing financial institutions to embed explainable AI modules into credit scoring pipelines. The southeastern industrial corridor around São Paulo anchors manufacturing predictive maintenance adoption despite MLOps talent scarcity.
Mexico
Algorithmic credit scoring demand is unlocking within the central bank's regulatory sandbox for fintech operators previously blocked by traditional underwriting rules. INAI guidance on automated profiling consent frameworks is tightening compliance requirements for customer service automation deployments. Mexico City metro enterprises are accelerating subscription-based cloud AI procurement aligned to inference volume rather than upfront capacity planning.
Argentina
Soybean and sugarcane cooperatives across the Pampas region are subscribing to computer vision crop monitoring systems enabled by neural network compression on legacy agricultural hardware. The national agricultural technology sector concentrates computer vision demand for satellite imagery analytics integration. Buenos Aires-based system integrators are building managed service capabilities around hyperscaler platforms for regional deployment.
Chile
Banking sectors in Santiago present underpenetrated opportunities for Portuguese-Spanish conversational AI as linguistic variant training matures. The financial services regulatory framework is drafting algorithmic accountability rules ahead of formal enforcement timelines. Northern mining clusters are exploring predictive maintenance applications constrained by remote contracting arrangements for specialist talent.
Colombia
Customer service automation in Bogotá banking operations is exhibiting accelerated adoption of API-accessible foundation models for document processing. The national fintech ecosystem is expanding demand for fraud detection algorithms with explainability features. Medellín technology clusters are developing regional NLP capabilities for Spanish conversational interfaces serving Andean markets.
Latin America Artificial Intelligence Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in Latin American AI deployment. Hyperscale cloud providers with regional data residency guarantees capture the expanding margin pool in subscription procurement. GPU-accelerated infrastructure vendors and nearshore system integrators constitute distinct strategic archetypes. Competitive positioning depends on compliance tooling integration and sovereign cloud certification rather than raw computational scale.
Within the infrastructure tier, NVIDIA Corporation anchors GPU-accelerated training demand through its CUDA ecosystem lock-in among research institutions. Softtek occupies a position exemplifying nearshore delivery advantages for enterprise AI integration across Mexican and Colombian clients. IBM sits within the governance tooling segment, differentiating through Watson compliance modules addressing ANPD and INAI audit requirements in regulated industries.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Softtek |
| IBM |
| Amazon Web Services |
| Advanced Micro Devices |
| Microsoft |
| Intel Corporation |
| InvGate |
| Google LLC |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day GPU lead times for Latin American research institutions concentrate pricing power with NVIDIA's CUDA ecosystem while fragmenting procurement budgets across sovereign cloud data residency requirements in Brazil and Mexico. This inventory compression forces buyers into premium subscription tiers for cloud-based inference capacity, reshaping how vendors structure regional service delivery.
Pricing Analysis
São Paulo commands a 15-25% premium over Mexico City for equivalent cloud AI compute capacity due to ANPD data localization mandates and scarcer MLOps talent pools. Three-tier pricing structure across premium sovereign-cloud, standard regional-residency, and economy offshore-processing levels stratifies procurement options. Cost compression in the economy tier is intensifying because hyperscalers are extending consumption-scaled pricing to mid-market accounts previously locked into perpetual licenses. Brazilian financial institutions show least price sensitivity due to LGPD compliance urgency, while Argentine agricultural cooperatives exhibit highest sensitivity given currency volatility and legacy hardware constraints.
Supply Chain Analysis
Port congestion at Santos and Manzanillo elevates inbound logistics costs for GPU hardware destined for Brazilian and Mexican data centers, extending deployment timelines for on-premises AI infrastructure. Supply concentrates in Taiwan for advanced semiconductors, USA for hyperscaler cloud infrastructure, and China for edge-optimized compression chipsets. The regional ecosystem draws from NVIDIA's CUDA-dependent accelerators, AWS and Azure sovereign cloud certifications, and specialized Portuguese-Spanish NLP training data pools. Single-source vulnerability around NVIDIA's ecosystem creates vendor lock-in risk for Latin American institutions. Distribution runs through São Paulo and Mexico City system integrators with secondary market reach into Bogotá and Santiago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model APIs are transforming this market into a platform-economics inflection where interoperability between hyperscaler inference services and sovereign cloud compliance tooling determines competitive survival. NVIDIA's ecosystem dominance and emerging algorithmic accountability frameworks in Brazil and Mexico create distinct consolidation and entry pathways.
For Market Incumbents: Consolidate governance tooling capabilities ahead of ANPD and INAI formal audit mandates, embedding explainability modules into existing Watson or proprietary platforms before compliance deadlines harden. Acquire MLOps talent pools in São Paulo and Mexico City to defend against hyperscaler direct-sales expansion into enterprise accounts. Vertical integration into Portuguese-Spanish NLP training data curation addresses substitution pressure from API-accessible foundation models. For New Entrants and Emerging Players: ANVISA pre-certification fast-tracks for diagnostic imaging algorithms present a regulatory moat against established healthcare IT vendors stalled in legacy EHR integration timelines. Target Colombian and Chilean banking sectors for conversational AI deployment where linguistic variant maturity lags Brazilian and Mexican markets. Partner with Buenos Aires system integrators to leverage nearshore delivery cost advantages for Andean market expansion. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because algorithmic accountability frameworks across Brazil, Mexico, and Chile will sustain premium pricing for governance tooling regardless of foundation model commoditization. Acquire mid-cap specialists with ANPD audit relationships and sovereign cloud certifications rather than raw compute capacity. Watch ANVISA pathway clarifications for algorithmic medical devices as the signal for healthcare AI deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ANPD and INAI data residency mandates lock in premium pricing for certified hyperscaler deployments. |
| Portuguese-Spanish NLP Development | Regional linguistic variant training opens underpenetrated Colombian and Chilean banking automation markets. |
| Edge Compression Technology | Neural network optimization enables Argentine Pampas deployment without full agricultural infrastructure replacement. |
| Explainable AI Tooling Integration | LGPD audit schedules force Brazilian financial institutions into compliance-focused procurement decisions. |
| MLOps Talent Acquisition | São Paulo and Mexico City specialist scarcity creates defensive moat through captive capability pools. |
Research Approach
The analysis maps machine learning deployment patterns, natural language processing adoption curves, and computer vision application clusters across Brazilian, Mexican, and Argentine enterprises, each validated through CTOs at financial institutions, platform engineers at hyperscaler regional offices, and procurement officers at agricultural cooperatives. Primary interviews with ANPD compliance consultants and INAI regulatory specialists combined with secondary validation against AWS and Azure sovereign cloud certification disclosures, ANVISA medical device registration databases, and Brazilian central bank fintech sandbox participant lists. Bottom-up triangulation across technology segments and top-down reconciliation against regional cloud infrastructure capex patterns anchored volume estimates.
Consistency checks against hyperscaler regional revenue disclosures and NVIDIA geographic segment reporting validated projection outputs across the analysis window. The analytical framework modeled deployment mode, organization size tier, vertical regulatory sensitivity, and integration complexity as segmentation dimensions. CAGRs derived from logistic diffusion curves for technology adoption, adjusted for LGPD enforcement timing and central bank sandbox expansion trajectories. Forecast inputs incorporated MLOps talent supply constraints and GPU availability bottlenecks as supply-side dampeners.
Decision-makers should treat outputs as directional under sustained LGPD enforcement intensity and stable central bank regulatory sandbox parameters; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ANVISA algorithmic medical device pathways and Chilean algorithmic accountability draft rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
Legal AI Market