
 Federated Learning Market | 2026-2036
Federated Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Federated Learning Market Analytics
Healthcare is decoupling from finance as the dominant end-use vertical for federated learning adoption. NVIDIA Corporation leverages its GPU infrastructure and CUDA ecosystem to dominate the training layer for distributed neural networks. Google LLC sustains competitive positioning through TensorFlow Federated and its cloud-edge orchestration capabilities. Intel Corporation specializes in hardware-accelerated secure aggregation protocols that reduce communication overhead across heterogeneous device fleets.
Federated learning is a distributed machine learning paradigm where model parameters—not raw data—travel between central servers and edge nodes, with iterative aggregation algorithms converging on a shared global model without data centralization. Its primary commercial purpose is enabling multi-party AI development across privacy boundaries, regulatory jurisdictions, and competitive silos. Cloud-based deployment models are capturing the fastest growth trajectory as hyperscalers bundle federated orchestration into managed ML platforms, while differential privacy technology anchors the highest-margin segment due to cryptographic certification requirements and enterprise liability mitigation. Secure aggregation protocols remain technically immature relative to other technology layers, creating a capability gap that specialist vendors are racing to fill.
The EU AI Act, HIPAA in the United States, and GDPR collectively shape product architecture decisions by mandating audit trails, data minimization, and purpose limitation across distributed training pipelines. Japan's METI has issued non-binding guidance on federated AI governance that Japanese automotive and electronics conglomerates are treating as de facto compliance standards. Stakeholders must monitor whether emerging national AI sovereignty frameworks fragment interoperability standards or create certification arbitrage opportunities across jurisdictions.
Market Dynamics
Healthcare providers are decoupling AI model training from data centralization, with the EU AI Act's risk-based classification system forcing privacy-preserving architectures into procurement specifications.
Growth Catalysts
- EU AI Act compliance mandates:European institutions must implement audit trails and purpose limitation across distributed training pipelines, accelerating federated infrastructure procurement.
- Multi-site clinical collaboration:University hospital networks require cross-institutional AI development without violating HIPAA and GDPR data residency requirements.
- Secure aggregation hardware:Specialized chipsets enabling cryptographic parameter exchange are reducing communication overhead for heterogeneous device fleets.
Market Restraints
- Input cost volatility:GPU cluster pricing fluctuations compress margins for federated orchestration service providers.
- Technical limitation:Byzantine fault tolerance in asynchronous aggregation protocols remains computationally expensive for resource-constrained edge nodes.
- Regulatory friction:Divergent national AI sovereignty frameworks create certification arbitrage risks across jurisdictions.
Strategic Opportunities
- Underpenetrated automotive vertical:German OEMs are building cross-organizational platforms for autonomous driving model training without sharing proprietary sensor data.
- Technology convergence:Differential privacy mechanisms are converging with homomorphic encryption to enable certified aggregation without parameter exposure.
- Regulatory tailwind:Japan's METI federated AI governance guidance is creating de facto standards that Japanese conglomerates are exporting to Southeast Asian operations.
Industry Challenges
- Cryptographic engineering talent scarcity:Secure multi-party computation expertise concentrates in academic institutions rather than commercial vendors.
- Legacy system integration friction:Hospital IT departments face protracted timelines connecting federated nodes to existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Federated Learning Market |
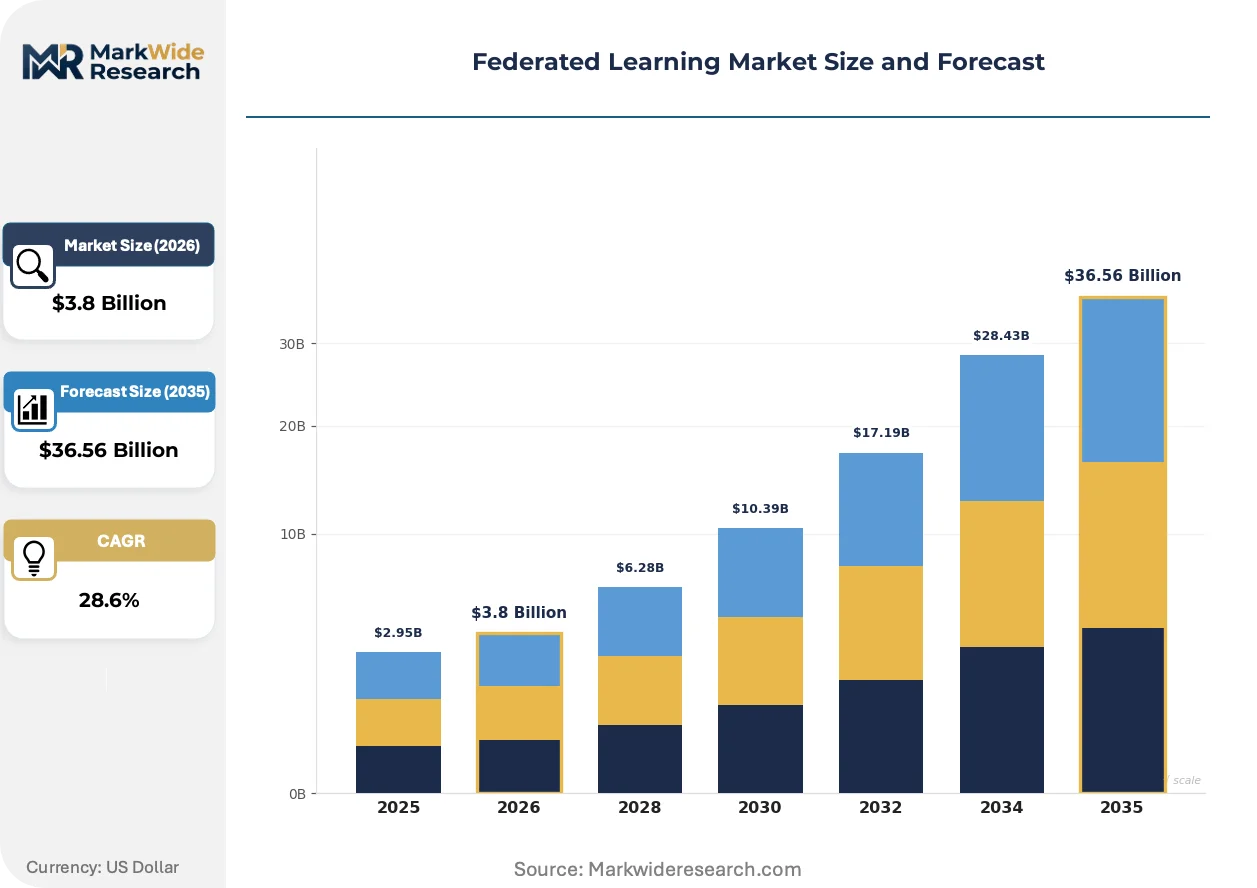
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Finance, Retail, Telecommunications Technology: Blockchain, Multi-Party Computation, Differential Privacy, Secure Aggregation Application: Predictive Modeling, Data Sharing, Anomaly Detection, Privacy Preservation |
| Companies Covered | NVIDIA Corporation, Owkin Inc., Google LLC, Intel Corporation, Flower Labs, Microsoft Corporation, Amazon Web Services Inc., Cloudera Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Federated Learning Market Evolving Landscape
Federated learning architectures are undergoing rapid functional specialization as regulatory pressure and compute economics reshape deployment patterns across end-use verticals.
Homomorphic encryption is converging with secure enclave hardware to enable end-to-end encrypted aggregation without trusted central coordinators. Financial services institutions are piloting this stack for anti-money laundering model training across national subsidiaries. The structural consequence is compressing the attack surface for model inversion attacks while extending training latency tolerances.
GDPR Article 35 data protection impact assessments are mandating federated alternatives to centralized model training for high-risk AI systems. This regulatory pressure is compelling cloud providers to bundle privacy-preserving orchestration into managed ML platforms. Healthcare and public sector procurement in Germany, France, and the Netherlands now specify federated architectures as default for cross-border data processing.
Buyer concentration among hyperscale cloud providers is displacing point-solution vendors from enterprise federated learning procurement. Automotive OEMs and hospital networks are consolidating vendor relationships around full-stack platforms rather than specialized aggregation protocols. This pattern is most visible in Germany, where cross-organizational data collaboration platforms require unified governance tooling.
Federated Learning Market Segmentation
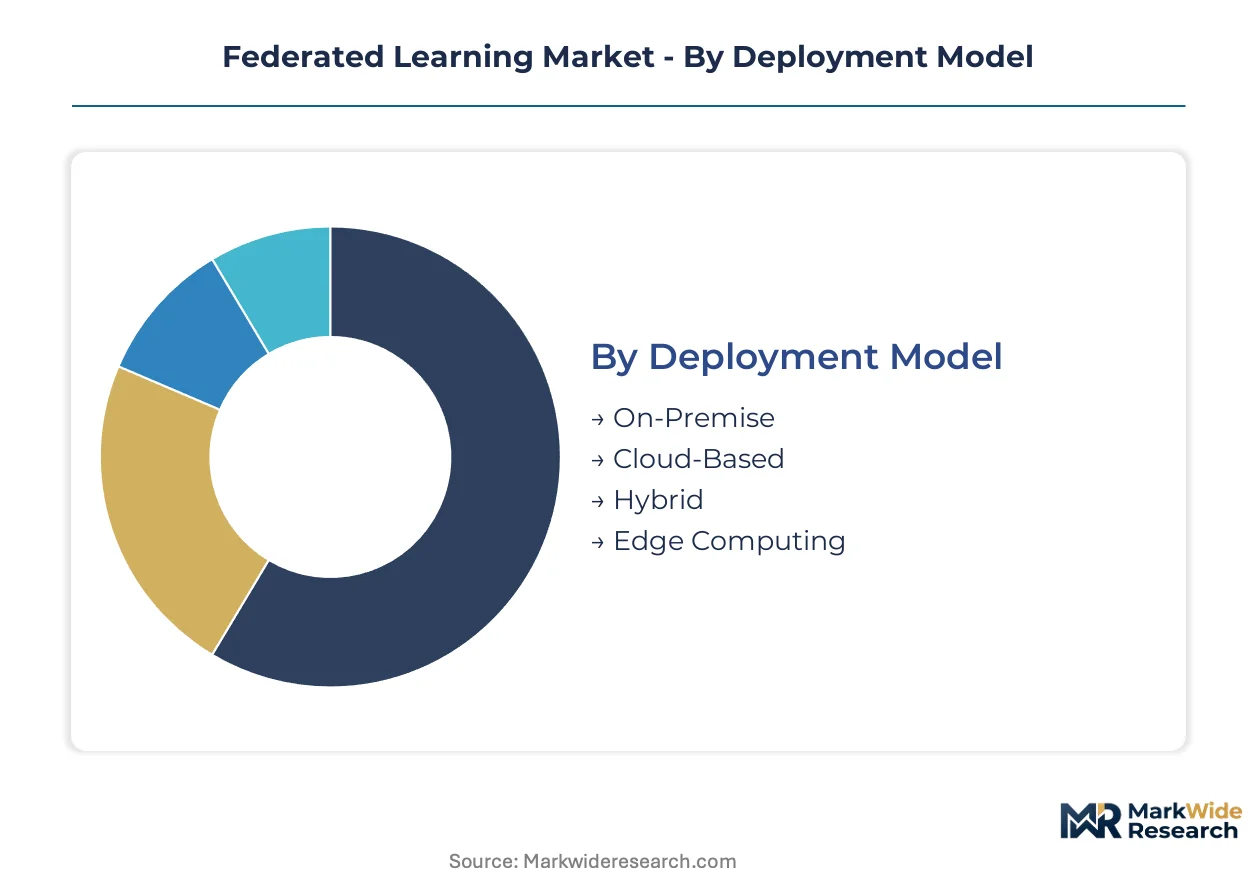
Federated learning architectures fragment across deployment topologies, regulatory exposure levels, and cryptographic sophistication tiers. Segmentation reveals where infrastructure investments concentrate versus where experimental pilots dominate procurement cycles.
Deployment Model:
Volume deployments favor operational control and predictable cost structures. Premium deployments trade capital intensity for elastic scaling and reduced internal security overhead.
- On-Premise:Dedicated hardware stacks within institutional data centers enable complete parameter custody and audit trail sovereignty. German university hospital networks and automotive OEMs favor this model to satisfy EU AI Act documentation requirements and internal compliance protocols.
- Cloud-Based:Hyperscaler-managed orchestration layers abstract node coordination and aggregation protocol maintenance. Healthcare providers in France and the Netherlands are migrating clinical AI training to these platforms to bypass capital expenditure cycles and accelerate multi-site collaboration timelines.
- Hybrid:Sensitive aggregation steps execute on-premise while non-critical coordination functions leverage cloud elasticity. Financial institutions in Japan deploy this architecture for anti-money laundering model training across subsidiaries.
- Edge Computing:Federated nodes operate on distributed IoT hardware with severe bandwidth and power constraints. Automotive sensor networks and remote medical devices represent emerging demand pockets.
Mature deployment sits with On-Premise configurations in regulated European healthcare networks. Newer deployment is concentrated in Cloud-Based platforms as procurement teams prioritize speed-to-collaboration over infrastructure ownership.
End User:
Application complexity and liability exposure create divergent technology requirements across vertical procurement specifications.
- Healthcare:Multi-site clinical AI development without HIPAA and GDPR violations drives the largest infrastructure commitments. University hospital networks require cryptographic certification for every parameter exchange.
- Finance:Cross-border anti-money laundering and fraud detection models train across national subsidiaries without centralizing transaction records. Japanese conglomerates treat METI guidance as binding procurement standards.
- Retail:Customer behavior prediction across franchise networks and supplier ecosystems remains technically feasible but legally underdeveloped. Pilot programs concentrate in German and French retail cooperatives.
- Telecommunications:Network optimization and predictive maintenance across infrastructure operators share limited operational data. European telecom consortiums are testing federated architectures for 5G edge computing coordination.
Procurement maturity clusters in Healthcare where regulatory pressure has hardened into contractual requirements. Retail represents the steepest expansion trajectory as privacy-preserving customer analytics gain commercial urgency.
Technology:
Cryptographic sophistication determines margin structure and vendor certification barriers.
- Secure Aggregation:Protocols enabling parameter averaging without revealing individual node contributions anchor enterprise procurement specifications. Hardware-accelerated implementations are reducing communication overhead for heterogeneous device fleets.
- Differential Privacy:Mathematical noise injection guarantees prevent membership inference attacks with certifiable bounds. Healthcare and finance procurement increasingly mandate third-party cryptographic audit trails.
- Multi-Party Computation:Distributed secret sharing enables computation on encrypted fragments without reconstruction. Academic research concentrates here but commercial deployment lags due to engineering talent scarcity.
- Blockchain:Immutable audit logs for model versioning and contribution tracking appeal to consortium governance structures. Implementation remains peripheral to core training workflows.
Certified deployment concentrates in Differential Privacy where liability mitigation justifies premium pricing. Experimental adoption clusters in Blockchain for cross-organizational governance automation.
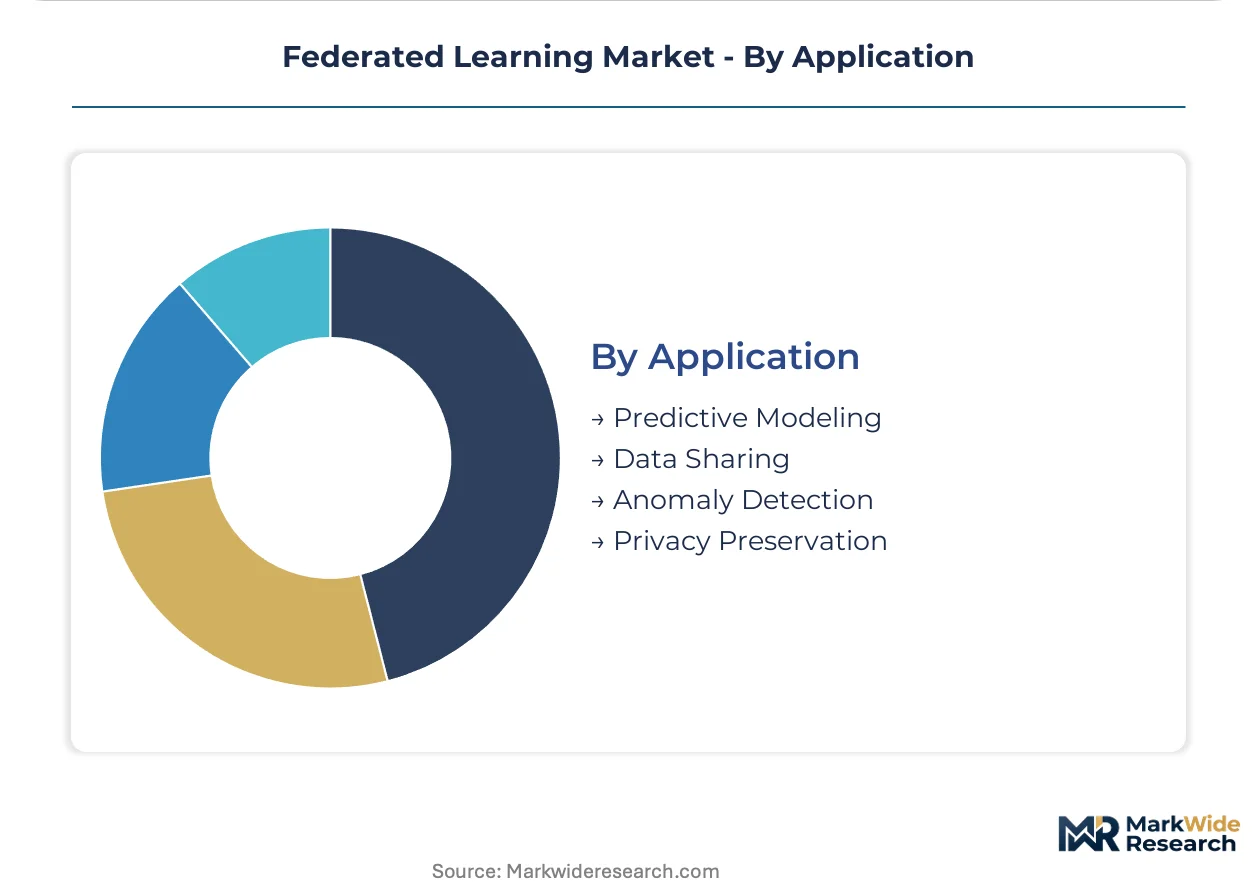
Application:
Functional use cases separate revenue-generating deployments from compliance-driven infrastructure.
- Predictive Modeling:Clinical outcome prediction and autonomous driving scene recognition represent the highest-value training objectives. German automotive OEMs and university hospital networks jointly fund platform development.
- Privacy Preservation:Regulatory compliance and data residency assurance constitute the foundational commercial justification. GDPR Article 35 assessments are mandating federated alternatives for high-risk AI systems.
- Anomaly Detection:Fraud prevention and network intrusion identification leverage distributed pattern recognition without centralizing sensitive event logs. Financial services pilots span Japanese and European institutions.
- Data Sharing:Cross-organizational dataset pooling for research consortia and supply chain optimization remains technically subordinate to model-centric architectures.
Revenue capture concentrates in Predictive Modeling where trained models deploy directly into operational workflows. Infrastructure investment is accelerating fastest in Privacy Preservation as procurement specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of federated learning infrastructure concentrates in US hyperscaler data centers and German industrial cloud facilities, while consumption spreads across healthcare networks in France, automotive clusters in Germany, and financial consortia in Japan.
United States
HIPAA-covered hospital networks and FDA-regulated clinical trial sponsors drive demand for cross-site AI training without data centralization. The Department of Health and Human Services has issued guidance treating federated architectures as acceptable safeguards for multi-institutional research. Boston and San Francisco anchor the densest concentration of health-tech vendors building compliant orchestration platforms.
Germany
University hospital networks and automotive OEMs jointly fund cross-organizational data collaboration platforms for clinical AI and autonomous driving development. The EU AI Act's risk-based classification system forces privacy-preserving architectures into procurement specifications for high-risk systems. Munich and Stuttgart host the primary engineering clusters where secure aggregation protocols receive hardware acceleration.
France
CNIL enforcement of GDPR Article 35 data protection impact assessments mandates federated alternatives to centralized model training for high-risk AI deployments. Public hospital procurement in Paris and Lyon now specifies federated architectures as default for cross-border clinical data processing. The national health data hub has piloted multi-site federated learning for oncology outcome prediction.
Japan
METI's non-binding guidance on federated AI governance has become de facto compliance standards for automotive and electronics conglomerates training models across Southeast Asian subsidiaries. Financial institutions pilot anti-money laundering model training using hybrid architectures. Tokyo and Osaka house the principal engineering centers developing hardware-accelerated secure aggregation for resource-constrained edge nodes.
United Kingdom
NHS Digital's federated data platform enables multi-trust clinical AI development without centralizing patient records from individual hospitals. The Information Commissioner's Office has issued guidance interpreting GDPR purpose limitation requirements for distributed training pipelines. London's health-tech cluster concentrates vendors specializing in differential privacy certification for cross-border research consortia.
Federated Learning Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud infrastructure, while mid-tier specialists concentrate on cryptographic protocol engineering and vertical-specific orchestration layers. The market exhibits tiered concentration around three strategic archetypes: GPU-accelerated training platform providers, privacy-preserving orchestration specialists, and full-stack cloud bundlers. Dominant competitive moves include strategic partnerships between hardware manufacturers and healthcare networks, plus technology licensing agreements that embed secure aggregation into existing electronic health record architectures.
Among US-based technology conglomerates, NVIDIA Corporation, Google LLC, and Microsoft Corporation exemplify the full-stack archetype by combining distributed training software with underlying compute infrastructure. NVIDIA's position represents GPU-centric dominance in the federated training layer, while Google and Microsoft occupy cloud-native orchestration roles. European specialists such as Owkin Inc. and Flower Labs anchor the privacy-first engineering tier, developing open-source frameworks that reduce deployment friction for resource-constrained clinical environments.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Owkin Inc. |
| Google LLC |
| Intel Corporation |
| Flower Labs |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| Cloudera Inc. |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
GPU cluster pricing fluctuations cascade through federated learning infrastructure procurement, compressing margins for orchestration service providers while hyperscalers absorb volatility through captive silicon supply. Cloud-based deployment models trade capital intensity for elastic scaling, creating three-tier pricing separation between premium certified aggregation, standard orchestration, and economy edge-node licensing.
Pricing Analysis
Margin tightening in cloud-based tiers reflects hyperscaler bundling of federated orchestration into managed ML platforms. Pricing stratifies across certified differential privacy implementations, standard secure aggregation protocols, and economy edge-computing licenses. Cost-down pressure accelerates as automotive OEMs and hospital networks consolidate vendor relationships around full-stack platforms rather than point solutions. Healthcare procurement committees exhibit lowest price sensitivity due to liability mitigation requirements, while retail cooperatives demonstrate highest elasticity.
Supply Chain Analysis
Hardware refurbishment flows for GPU clusters and secure enclave chipsets extend equipment lifecycles in German university hospital networks and Japanese financial institutions. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for hyperscaler cloud infrastructure, and Germany for automotive-grade edge computing hardware. Component dependencies include NVIDIA GPU architectures, Intel secure aggregation chipsets, and ARM-based edge processors. Single-source vulnerability in advanced node semiconductor manufacturing poses structural risk. Distribution runs through direct enterprise sales for on-premise deployments and hyperscaler marketplaces for cloud-based orchestration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscaler bundling of federated orchestration into managed ML platforms is forcing point-solution vendors toward acquisition or niche specialization, consolidating competitive dynamics around full-stack platform providers.
For Market Incumbents: Extend cryptographic certification depth to maintain procurement eligibility under EU AI Act documentation requirements and HIPAA audit trail mandates. Capture hospital network consolidation by embedding secure aggregation protocols into existing electronic health record architectures from Epic Systems and Cerner. Counter emerging open-source frameworks from European privacy-first engineering specialists through differentiated hardware acceleration and unified governance tooling. For New Entrants and Emerging Players: Cloud-native orchestration partnerships with regional healthcare IT integrators in France and the Netherlands offer the most penetrable entry vector. Target retail cooperatives in Germany with privacy-preserving customer analytics pilots, a segment where procurement specifications remain technically feasible but legally underdeveloped. Differentiate through differential privacy certification services that third-party auditors can cryptographically validate. For Investors and Strategic Acquirers: METI guidance adoption by Japanese conglomerates exporting federated AI governance standards to Southeast Asian subsidiaries is the leading indicator that regulatory tailwinds will concentrate value in compliance-certified platform vendors. Position acquisitions around mid-tier specialists with cryptographic engineering depth and existing hospital network deployments. Monitor EU AI Act enforcement patterns for early signals of procurement specification hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Accelerated Secure Aggregation | Intel and NVIDIA chipsets reduce communication overhead for heterogeneous device fleets in automotive sensor networks. |
| Cloud-Edge Orchestration Partnership | Google and Microsoft bundle federated training into managed ML platforms displacing point-solution vendors. |
| Differential Privacy Certification | Third-party cryptographic audit trails satisfy GDPR Article 35 assessments for high-risk clinical AI systems. |
| Cross-Organizational Platform Development | German university hospitals and automotive OEMs jointly fund data collaboration infrastructure. |
| Open-Source Framework Expansion | Owkin and Flower Labs reduce deployment friction for resource-constrained clinical environments. |
Research Methodology
Independent corroboration across primary interviews with hospital CIOs, automotive platform engineers, financial services compliance officers, and cloud infrastructure procurement leads underwrites the qualitative findings. Secondary validation draws from SEC filings of hyperscaler technology conglomerates, EU AI Act implementation guidance, METI federated AI governance documentation, and hospital procurement database records. Bottom-up segmentation modeling triangulates against top-down market sizing from infrastructure deployment announcements.
Rate-of-change decomposition across the analysis window isolates volume expansion from price-mix effects in cloud-based versus on-premise deployment models. Segmentation dimensions include deployment topology, cryptographic sophistication tier, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base growth projections for federated node counts and average revenue per node trajectories. Forecast inputs incorporate GPU cluster pricing volatility indices and EU AI Act compliance timeline assumptions.
Caveats apply where divergent national AI sovereignty frameworks or Byzantine fault tolerance breakthroughs in asynchronous aggregation protocols could materially shift the outlook. Practitioners should monitor hyperscaler bundling announcements and cryptographic engineering talent migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Generative AI Market