
 Global Mobile Artificial Intelligence Market | 2026-2036
Global Mobile Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Artificial Intelligence Market Foresight
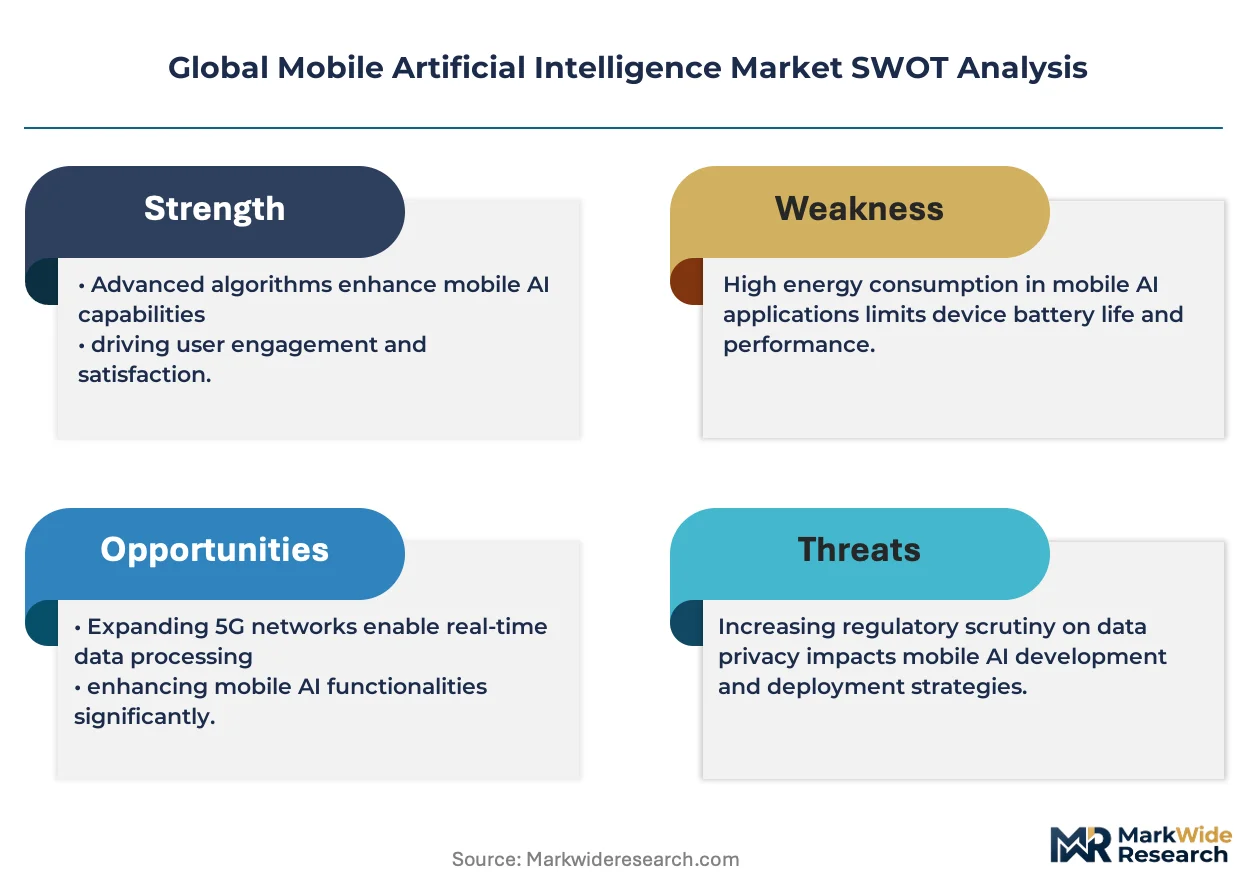
The EU AI Act is restructuring compliance obligations for mobile AI systems deployed in European consumer devices. Qualcomm Inc leverages its Snapdragon platform dominance to anchor on-device inference capabilities across Android ecosystems. Apple Inc differentiates through its Neural Engine silicon and tight hardware-software integration in iPhone architectures. Samsung Electronics competes by extending its Exynos chip roadmap with dedicated NPU cores for flagship Galaxy devices.
Mobile artificial intelligence encompasses neural processing units, optimized inference engines, and lightweight machine learning models designed to execute predictive and perceptual tasks directly on handheld hardware without persistent cloud connectivity. These systems typically operate within thermal envelopes below five watts while delivering real-time image segmentation, natural language understanding, and contextual recommendation functions. AI Chips capture the dominant margin pool as foundry capacity constraints and architectural specialization inflate premium pricing for smartphone-bound NPUs. Cloud-based AI retains structural importance for model training and federated learning orchestration, though latency-sensitive applications are accelerating migration toward On-device AI deployment across flagship and mid-tier handsets.
The Federal Communications Commission in the United States, the EU AI Act framework, and China's MIIT standards collectively shape product certification, data governance, and semiconductor export control regimes affecting mobile AI market access. The EU Green Deal's embodied carbon requirements are beginning to influence chip packaging and device lifecycle mandates for European-bound hardware. Stakeholders must monitor divergence between Washington's export restrictions on advanced AI accelerators and Beijing's domestic substitution incentives, as this tension will determine which architectures achieve scale in the next wave of handset refresh cycles.
Market Dynamics
On-device inference migration is compressing cloud dependency for latency-sensitive mobile workloads while foundry capacity constraints in Taiwan and South Korea inflate NPU pricing premiums.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements for consumer devices are accelerating investment in interpretable on-device models across European-bound handset portfolios.
- Smartphone photography segmentation:Real-time computational imaging pipelines are pulling dedicated neural processing silicon into mid-tier device roadmaps.
- China MIIT domestic substitution incentives:Local NPU design requirements are redirecting procurement toward indigenous chip architectures for domestic handset brands.
Market Restraints
- Advanced node foundry concentration:Sub-5nm fabrication capacity clusters in Taiwan and South Korea create supply vulnerability for flagship smartphone NPUs.
- Thermal envelope physics:Handheld power budgets below five watts cap inference throughput for large language model deployment.
- EU Green Deal embodied carbon rules:Chip packaging and device lifecycle mandates are adding compliance overhead for European market entry.
Strategic Opportunities
- India BIS certification pathways:Local assembly requirements for imported electronics are creating captive demand for edge-AI modules in domestic manufacturing.
- Federated learning orchestration:Privacy-preserving model updates across distributed handsets are converging with on-device training capabilities.
- Automotive handset integration:Digital key and driver monitoring applications are opening adjacent revenue pools for mobile AI silicon suppliers.
Industry Challenges
- On-device optimization expertise scarcity:Embedded systems engineers capable of quantizing transformer architectures for NPU execution command premium compensation.
- Cross-platform inference engine fragmentation:Proprietary SDKs from Qualcomm, MediaTek, and Apple force multi-path development for application developers targeting heterogeneous silicon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Artificial Intelligence Market |
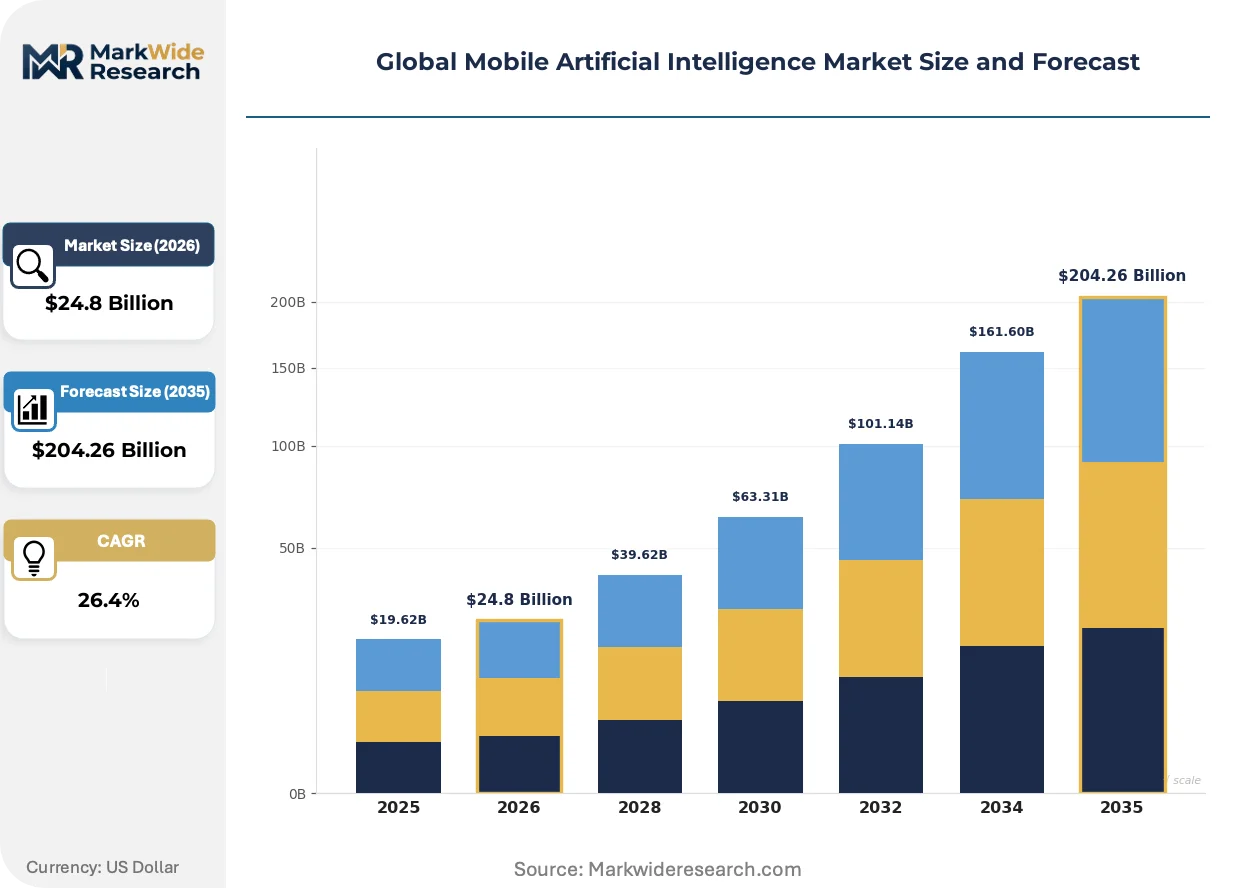
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $204.26 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AI Chips, AI Software, AI Platforms, AI Services, AI Frameworks Deployment: On-device AI, Cloud-based AI, Hybrid AI, Edge Computing, Fog Computing Application: Personal Assistants, Image Recognition, Predictive Analytics, Voice Authentication, Natural Language Processing End User: Smartphone Manufacturers, Telecom Operators, Enterprises, App Developers, System Integrators |
| Companies Covered | Qualcomm Inc, Apple Inc, Google LLC, Nvidia Corporation, Intel Corporation, Microsoft Corporation, Huawei Technologies, MediaTek, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Artificial Intelligence Market Shifts & Advancements
Neural processing architectures are fragmenting across specialization axes as handset manufacturers pursue differentiation through proprietary silicon-roadmap control.
Transformer-based vision models are modularizing across the mobile AI stack. Qualcomm and MediaTek are adopting block-sparse attention kernels into their NPU driver releases for 2024-2025 platforms. This compression is modularizing previously monolithic computer-vision pipelines into interchangeable sub-networks that OEMs can license and customize without full model retraining.
The EU AI Act risk-classification framework is restructuring algorithmic disclosure obligations for European consumer devices. High-risk biometric applications now require technical documentation and conformity assessment before market placement. Flagship handset launches in Germany and France are front-loading compliance investment to avoid 35-day notification delays.
Enterprise handset procurement is consolidating around security-certified device fleets. Financial services and healthcare employers are mandating on-device inference for voice transcription and document scanning to eliminate cloud data residency risks. This specification compression is most visible in US and UK enterprise mobility contracts where CISOs are rewriting RFP evaluation criteria.
Global Mobile Artificial Intelligence Market Segmentation
Segmentation in mobile artificial intelligence reveals how certification burdens, thermal constraints, and supply chain access partition commercial opportunity across hardware and software layers. Product and deployment categories carry divergent regulatory loads while application and end-user dimensions expose diverging margin structures.
Product Type:
AI Chips face the heaviest certification matrix, combining FCC Part 15 emissions testing in the United States, CE marking under EU Radio Equipment Directive, and MIIT network access licenses in China. AI Software and AI Platforms navigate lighter conformity assessment but must satisfy EU AI Act documentation requirements for high-risk biometric functions.
- AI Chips:Neural processing units and dedicated AI accelerators fabricated on advanced nodes below 7nm. Qualcomm's Snapdragon and Apple's Neural Engine dominate flagship handset procurement, though MediaTek's Dimensity series is gaining share in mid-tier Android portfolios as Chinese OEMs diversify supplier bases.
- AI Software:Optimized inference engines, quantization libraries, and power management middleware executing within sub-five-watt thermal envelopes. Google TensorFlow Lite and Qualcomm Neural Processing SDK command broad developer adoption, with Samsung's ONE UI AI layer capturing proprietary integration advantages in Galaxy device lines.
- AI Platforms:Integrated development environments bundling model training, edge optimization, and deployment orchestration. These systems concentrate in cloud-to-edge hybrid architectures serving enterprise mobility management suites.
- AI Services:Managed model hosting, federated learning coordination, and device fleet analytics delivered through subscription contracts. Telecom operators in South Korea and Japan are bundling these into 5G enterprise service tiers.
- AI Frameworks:Open-source and proprietary libraries enabling model compression and NPU kernel customization. PyTorch Mobile and ONNX Runtime are displacing older Caffe2 implementations across Android OEM roadmaps.
AI Chips sits at the top of the volume ranking, with AI Software climbing the fastest as quantization expertise becomes a bottleneck constraint.
Deployment:
Cost tier stratification separates deployment modes, with On-device AI commanding premium silicon pricing while Cloud-based AI amortizes across shared infrastructure. Hybrid architectures capture mid-market positioning by balancing latency requirements against hardware bill-of-materials pressure.
- On-device AI:Inference execution entirely within handset NPUs without persistent connectivity. Apple's A-series and M-series silicon, Qualcomm's Hexagon DSP, and MediaTek's APU architectures define this segment's hardware substrate, with photography and voice authentication driving flagship adoption.
- Cloud-based AI:Model execution on remote GPU clusters with handset serving as thin client. This mode retains dominance for large language model queries and training-phase computation, though data residency requirements in Germany and France are compressing its addressable share in European enterprise contracts.
- Hybrid AI:Dynamic workload partitioning between local NPU and cloud accelerator based on latency, bandwidth, and battery state. Samsung's Galaxy AI and Google's Pixel features exemplify this architecture, with model routing decisions handled by on-device orchestration layers.
- Edge Computing:Inference on network-side micro-datacenters positioned within 50 kilometers of handset populations. South Korean telecom operators are deploying these for real-time gaming optimization and AR navigation services.
- Fog Computing:Distributed processing across proximal device meshes including handsets, vehicles, and IoT gateways. Automotive digital key applications are emerging as the primary commercial traction point for this architecture.
On-device AI captures the dominant share of new handset bill-of-materials allocation, with Hybrid AI expanding most quickly as OEMs seek thermal envelope relief.
Application:
Customer type divergence separates consumer-facing perceptual applications from enterprise security mandates, with Image Recognition and Personal Assistants targeting mass-market volume while Voice Authentication and Predictive Analytics concentrate in regulated industries.
- Personal Assistants:Conversational AI executing natural language understanding and task orchestration. Amazon Alexa Custom Assistant and Google Assistant on-device variants are displacing cloud-dependent implementations in premium automotive and handset integrations.
- Image Recognition:Real-time scene segmentation, object detection, and computational photography pipelines. This application consumes the largest share of NPU compute cycles across flagship devices from Apple, Samsung, and Chinese OEMs.
- Predictive Analytics:Behavioral pattern recognition for battery optimization, app prefetching, and network selection. These functions operate largely invisibly to users but differentiate Android skin implementations.
- Voice Authentication:Biometric speaker identification for device unlock and payment authorization. EU AI Act high-risk classification is imposing conformity assessment overhead for European market entry.
- Natural Language Processing:On-device translation, summarization, and text generation. Transformer model compression breakthroughs are enabling this application's migration from cloud dependency.
Image Recognition maintains the steepest volume trajectory, with Natural Language Processing gaining share fastest as generative model quantization matures.
End User:
Supply concentration patterns diverge sharply across end-user categories, with Smartphone Manufacturers capturing captive NPU supply while App Developers and System Integrators face SDK fragmentation and platform-specific optimization burdens.
- Smartphone Manufacturers:OEMs and ODMs integrating AI silicon into handset reference designs. Apple, Samsung, Xiaomi, OPPO, and Vivo collectively account for the dominant procurement volume, with each pursuing proprietary differentiation through custom NPU architectures or exclusive software layers.
- Telecom Operators:Carriers bundling AI-enabled services into subscriber plans and enterprise mobility contracts. SK Telecom, NTT Docomo, and Verizon are deploying network-side AI acceleration for latency-sensitive applications.
- Enterprises:Corporate IT departments procuring security-certified device fleets with mandated on-device inference. Financial services and healthcare employers in the United States and United Kingdom are rewriting RFP criteria to eliminate cloud data residency risks.
- App Developers:Third-party software houses targeting heterogeneous NPU substrates through abstraction layers. Cross-platform tool fragmentation between Qualcomm, MediaTek, and Apple SDKs inflates development overhead.
- System Integrators:Consultancies and deployment specialists configuring enterprise mobility solutions. These players aggregate demand across regulated industries requiring EU AI Act compliance documentation.
Smartphone Manufacturers dominate procurement scale, with Enterprises climbing fastest as security certification requirements harden procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile artificial intelligence infrastructure traces its commercial lineage to semiconductor fabrication clusters established in Taiwan and South Korea during the 1980s and 1990s, with subsequent design specialization concentrating in the United States and China as smartphone ecosystems matured.
United States
FCC Part 15 emissions certification and NIST cybersecurity frameworks govern handset AI deployment for domestic and export markets. The CHIPS Act's $52 billion fabrication subsidy program is attracting advanced node capacity to Arizona and Texas, with Intel and TSMC breaking ground on facilities projected to reduce Taiwan concentration risk by the late 2020s. San Diego and Austin anchor the dominant NPU design clusters, housing Qualcomm's Snapdragon architecture teams and Apple's silicon engineering divisions.
China
MIIT network access licenses and domestic substitution mandates are redirecting procurement toward indigenous NPU architectures for Huawei, Xiaomi, and OPPO handset portfolios. The country's dual carbon goals are tightening embodied carbon thresholds for chip packaging exported under EU Green Deal compliance. Shenzhen and Shanghai fabrication corridors are scaling 7nm and below production for flagship device bound silicon, though advanced lithography equipment restrictions constrain sub-5nm roadmap execution.
South Korea
MFDS device certification and K-Network 2030 infrastructure investment are accelerating on-device AI integration across Samsung and LG handset portfolios. Government-backed AI semiconductor R&D consortia are channeling $450 million annually toward domestic NPU architecture development. Seoul and Pyeongtaek concentration of Samsung Electronics' foundry and memory operations creates captive supply advantages for Exynos chipset roadmaps targeting Galaxy device lines.
Germany
EU AI Act conformity assessment and CE marking under the Radio Equipment Directive impose 35-day notification delays for biometric-enabled handsets entering European markets. The country's national automotive regulator KBA is converging digital key standards with mobile AI security specifications. Munich and Stuttgart industrial corridors are emerging as enterprise mobility procurement centers, with BMW and Mercedes-Benz mandating on-device inference for fleet device deployments.
India
BIS certification pathways and PLI scheme production-linked incentives are creating captive demand for edge-AI modules in domestic handset assembly operations. TRAI data localization consultations are compressing cloud-dependent AI service architectures for telecom operator bundled offerings. Bangalore and Hyderabad design centers are attracting NPU software optimization engineering talent as Chinese OEMs establish captive development facilities to serve export and domestic markets.
Global Mobile Artificial Intelligence Market Competitive Landscape
Premium-margin players sit above commodity-margin players across silicon architectural control and software integration depth. The market structures around three tiers: integrated device manufacturers with captive semiconductor design, fabless chip architects licensing across OEM portfolios, and middleware abstraction layer providers. Strategic archetypes include full-stack verticalists controlling hardware-software boundaries, open-ecosystem enablers spanning heterogeneous silicon substrates, and cloud-to-edge orchestrators federating model deployment. Dominant competitive moves center on NPU architectural licensing expansion and strategic partnerships securing foundry capacity allocation.
Within the integrated verticalist tier, Apple Inc exemplifies full-stack control through proprietary Neural Engine silicon and tight iOS integration, while Qualcomm Inc occupies a position as the dominant Android ecosystem enabler licensing Snapdragon platforms across fragmented OEM bases. Samsung Electronics anchors a hybrid archetype combining captive Exynos design with strategic Qualcomm sourcing flexibility. These three entities represent the primary competitive poles structuring procurement negotiations and architectural roadmap influence across flagship and mid-tier handset segments.
| Leading Market Players |
|---|
| Qualcomm Inc |
| Apple Inc |
| Google LLC |
| Nvidia Corporation |
| Intel Corporation |
| Microsoft Corporation |
| Huawei Technologies |
| MediaTek |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Sub-5nm fabrication migration is simultaneously inflating capital intensity for neural processing units and concentrating pricing power among Taiwan and South Korea foundry operators serving flagship handset programs. This technology transition feeds directly into bill-of-materials pressure across Android OEM portfolios while Apple captures captive supply economics through in-house silicon design.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flagship Neural Engine deployments from mid-tier Dimensity integrations and entry-level DSP offload solutions. Price differentiation hinges on certification grade under EU AI Act high-risk biometric classifications and volume scale commitments from top-five smartphone OEMs. Cost compression in mid-tier NPUs is intensifying because Chinese OEMs are diversifying supplier bases away from Qualcomm exclusivity. Enterprise procurement teams in financial services exhibit lowest price sensitivity due to security mandate compliance overhead, while mass-market handset distributors face acute margin pressure.
Supply Chain Analysis
Refurbishment flows for retired flagship handsets are recovering Neural Engine and Hexagon DSP components for secondary market NPU supply in emerging economies. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced node fabrication, with China scaling 7nm domestic capacity for indigenous handset brands. Raw material dependencies draw from EUV lithography equipment, advanced packaging substrates, and high-bandwidth memory stacks. Single-source vulnerability runs through ASML lithography tool availability under Washington export restrictions. Distribution runs through Shenzhen and Seoul component markets feeding ODM assembly corridors in Vietnam and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework compounds procurement specifications across biometric-enabled handsets, converting compliance documentation into a recurring revenue stream for qualified NPU suppliers.
For Market Incumbents: Lock in foundry capacity allocation through multi-year wafer commitments at TSMC and Samsung foundry operations before Arizona and Texas greenfield facilities achieve yield parity. Defend against MediaTek share gains in Chinese OEM portfolios by accelerating Hexagon DSP licensing expansion into mid-tier 5G reference designs. Prioritize EU AI Act conformity assessment pre-certification to capture 35-day notification delay avoidance premiums from German and French handset distributors. For New Entrants and Emerging Players: Transformer quantization toolchains offer entry velocity against entrenched Qualcomm and Google SDK dominance in on-device inference optimization. White-space concentrates in India BIS-certified edge-AI modules for domestic PLI scheme assembly operations and federated learning orchestration layers serving enterprise mobility management suites. Go-to-market traction demands direct engagement with Bangalore and Hyderabad design centers where Chinese OEMs have established captive NPU software optimization facilities. For Investors and Strategic Acquirers: Valuations sit cheapest among middleware abstraction layer providers trapped between proprietary Qualcomm, MediaTek, and Apple SDK fragmentation. Long-term viability favors acquisition targets with demonstrated EU AI Act technical documentation capabilities and established relationships with system integrators serving regulated industries. Monitor Washington-Beijing export control divergence on advanced lithography equipment as the primary inflection signal for which NPU architectures achieve scale in next-generation handset refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Secures 35-day market access acceleration for biometric-enabled handsets in Germany and France. |
| Foundry Capacity Reservation | Locks wafer supply at TSMC and Samsung ahead of Arizona greenfield yield ramp. |
| Mid-Tier NPU Architecture Licensing | Expands Hexagon DSP and Dimensity APU penetration into Chinese OEM diversification programs. |
| Federated Learning Platform Development | Captures enterprise mobility contracts requiring privacy-preserving model updates across device fleets. |
| India PLI Scheme Manufacturing Localization | Qualifies for production-linked incentives in BIS-certified domestic handset assembly operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NPU architecture leads at fabless chip designers, smartphone OEM procurement officers, and EU notified body conformity assessors with secondary validation against SEC 10-K filings, MIIT network access license databases, and hyperscaler capex disclosures. Bottom-up triangulation across foundry utilization rates and top-down cross-checks against handset bill-of-materials estimates anchored volume and value outputs.
Segment-weighting approaches distributed forecast mass across AI Chips, AI Software, AI Platforms, AI Services, and AI Frameworks product categories, with further disaggregation by On-device AI, Cloud-based AI, Hybrid AI, Edge Computing, and Fog Computing deployment modes. CAGRs were derived from regression analysis of historical NPU shipment volumes against flagship and mid-tier handset production forecasts, incorporating EU AI Act implementation timelines and China MIIT domestic substitution policy trajectories as scenario inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Washington-Beijing export control escalation and EU Green Deal embodied carbon threshold tightening. Practitioners should monitor ASML lithography equipment licensing decisions and TSMC Arizona yield ramp schedules for early signals of supply constraint resolution or intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market