
 Smart Virtual Personal Assistants Market | 2026-2036
Smart Virtual Personal Assistants Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Virtual Personal Assistants Market Analytics
Cloud-native consumption models and API-first platform leasing is reconfiguring competitive entry barriers for AI assistant providers. Microsoft leverages its Azure infrastructure to anchor enterprise deployments across regulated industries. Google competes through deep integration with consumer hardware and search ecosystems. Anthropic differentiates via constitutional AI safety frameworks that appeal to risk-conscious institutional buyers.
Smart virtual personal assistants are software agents that interpret natural language inputs through NLP pipelines, execute contextual reasoning via machine learning models, and return actionable outputs through voice or text interfaces for task completion. Voice assistants currently occupy the largest product segment due to embedded smartphone and smart speaker penetration, while task automators represent the fastest-expanding category as enterprises seek workflow integration. Cloud computing underpins scalable inference delivery, though edge-optimized AI algorithms are gaining traction for latency-sensitive applications.
FDA oversight of clinical decision-support tools and HIPAA privacy rules constrain healthcare deployments in the United States, while the EU AI Act imposes risk-tiered obligations on automated systems processing personal data in Europe. GDPR data localization requirements and ISO 27001 certification demands shape procurement criteria for enterprise buyers across both jurisdictions. Stakeholders must monitor evolving algorithmic accountability standards and alignment between national AI frameworks and sector-specific data governance mandates.
Market Dynamics
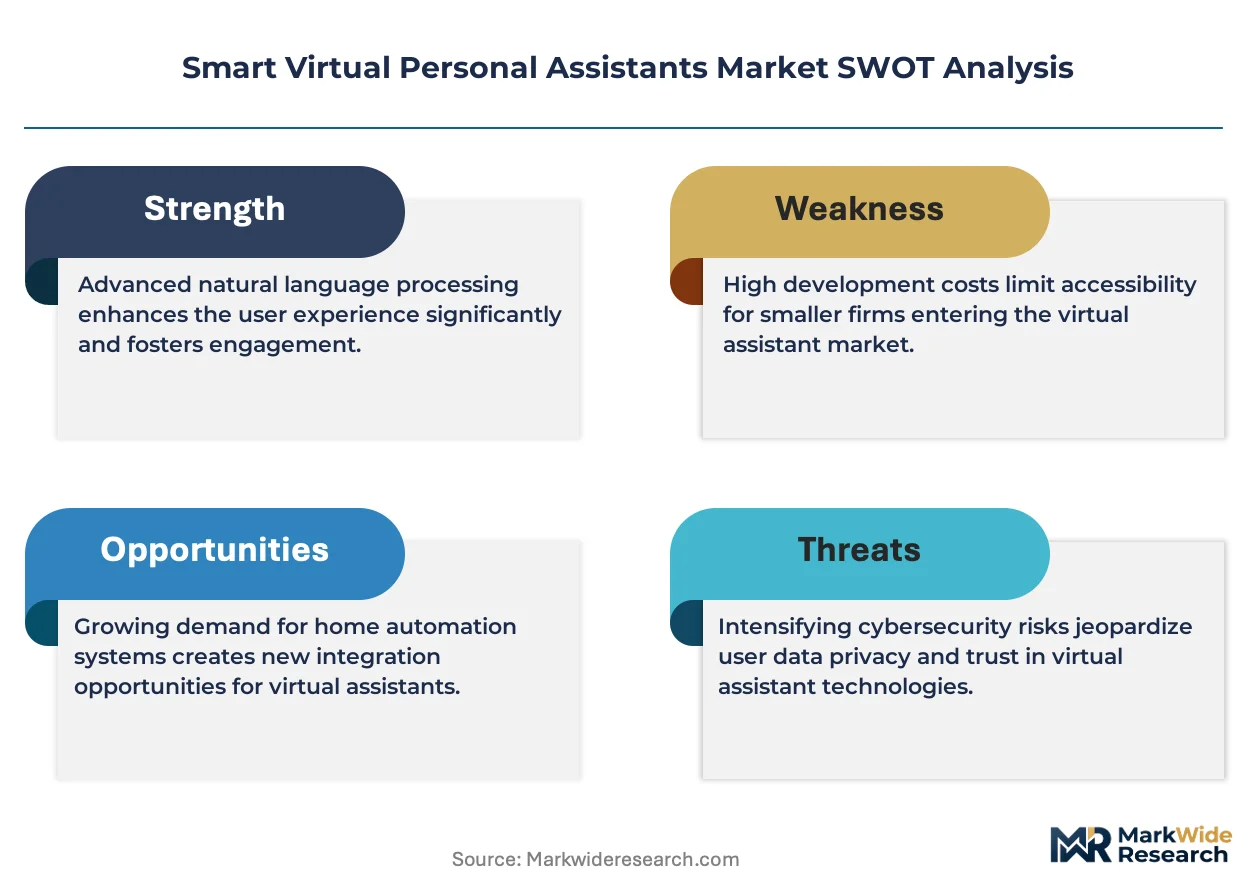
Cloud-native API architectures and edge-optimized inference engines are fragmenting deployment economics across enterprise and consumer segments, compressing the traditional infrastructure moats that once protected incumbent platform providers.
Growth Catalysts
- HIPAA-compliant healthcare automation:US hospitals and payers deploy voice-enabled clinical documentation tools to reduce administrative burden. FDA's evolving framework for clinical decision-support software accelerates procurement cycles.
- GDPR Article 25 data protection by design:European enterprise buyers mandate privacy-preserving NLP pipelines, creating procurement preference for assistants with federated learning architectures and on-device processing capabilities.
- Task automator integration:Financial services and legal sectors adopt workflow-embedded assistants that interface with CRM, ERP, and document management systems through standardized API connectors.
Market Restraints
- GPU and TPU supply concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node fabrication for AI accelerator chips, exposing inference cost structures to geopolitical supply disruptions.
- EU AI Act high-risk system classification:Automated systems processing biometric data or influencing credit decisions face conformity assessment burdens and post-market monitoring obligations that extend commercialization timelines.
- On-premise deployment cost barriers:Enterprises in regulated sectors requiring air-gapped infrastructure face 3-5x higher total cost of ownership versus cloud-native alternatives, constraining mid-market adoption.
Strategic Opportunities
- India's BIS certification pathway:The Bureau of Indian Standards is developing AI system safety standards for consumer electronics, creating first-mover advantage for assistants achieving compliance ahead of mandatory implementation.
- Multimodal convergence of voice, vision, and gesture:Automotive OEMs and smart home manufacturers seek unified interface layers that reduce cognitive load through contextual modality switching.
- Japan's METI AI governance guidelines:Human-centric AI principles and sector-specific implementation roadmaps offer regulatory clarity that reduces compliance uncertainty for enterprise deployments.
Industry Challenges
- Conversational AI talent scarcity:Shortages in computational linguistics, reinforcement learning from human feedback, and prompt engineering constrain product development velocity across vendor organizations.
- ISO 27001 and SOC 2 Type II certification timelines:Enterprise procurement mandates require 12-18 month audit cycles that delay market entry for emerging providers lacking established security postures.
- Legacy system integration complexity:Mainframe-dependent financial institutions and EHR-locked healthcare networks require custom middleware development that erodes margin on fixed-price implementation contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Virtual Personal Assistants Market |
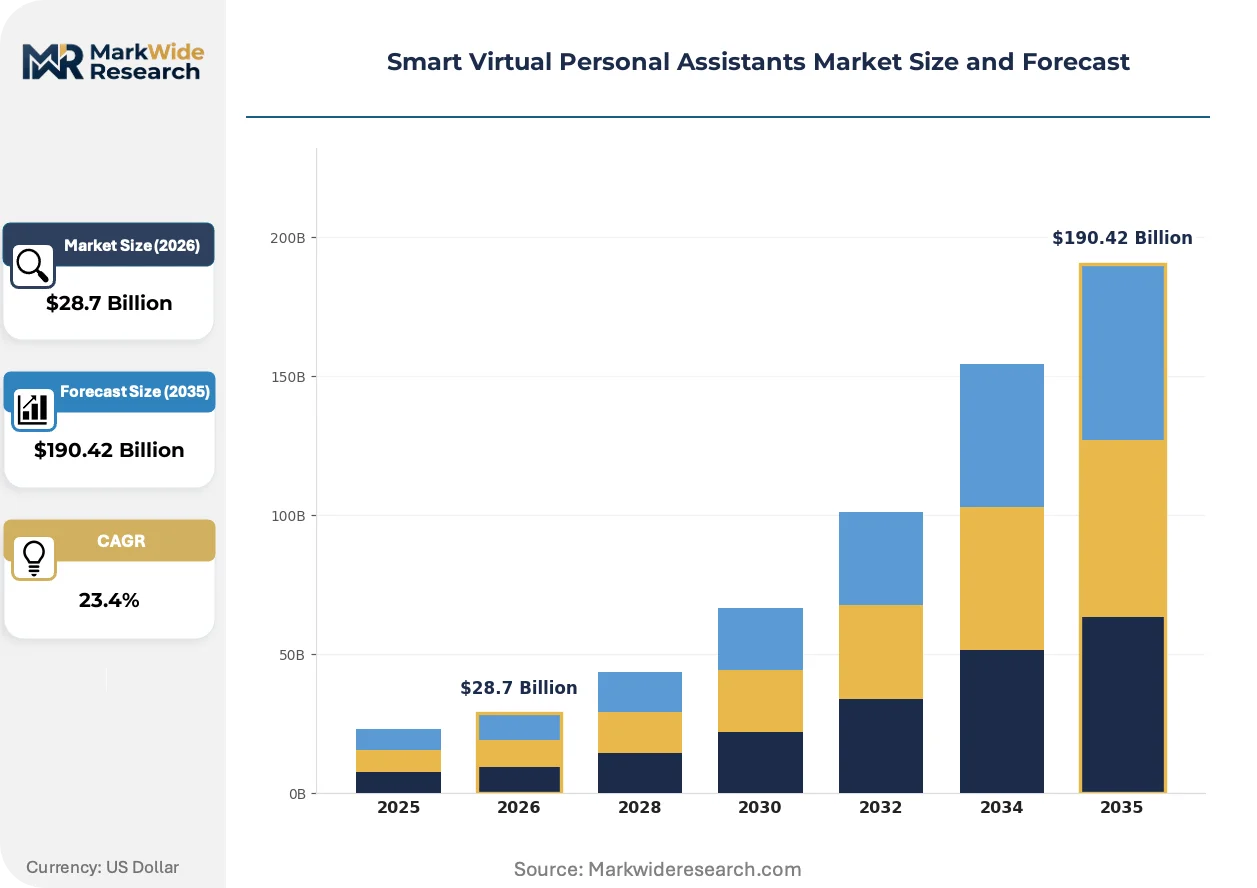
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $190.42 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Voice Assistants, Task Automators, Smart Speakers Technology: Natural Language Processing, Machine Learning, Cloud Computing, AI Algorithms Use Case: Customer Support, Personal Management, E-commerce, Smart Home Integration End User: Employees, Consumers, Enterprises, Developers |
| Companies Covered | Microsoft, IBM, Google, Anthropic, OpenAI, Amazon, Samsung, Arahi AI, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Virtual Personal Assistants Market Evolving Landscape
Natural language processing architectures are compressing inference costs while expanding contextual window capabilities, enabling assistants to handle multi-turn complex reasoning tasks previously requiring human intervention.
Small language models optimized for edge deployment are virtualizing the compute layer that once demanded centralized cloud infrastructure. Automotive manufacturers and industrial equipment vendors embed these models directly into vehicle ECUs and factory floor controllers, eliminating latency-dependent round trips to remote data centers. This distributed architecture is virtualizing the traditional SaaS delivery model and fragmenting pricing power away from hyperscale platform operators.
The EU AI Act's risk-tiered classification system imposes binding obligations on high-risk applications including credit scoring and recruitment automation. Providers must implement risk management systems, maintain technical documentation, and ensure human oversight capabilities that fundamentally reshape product development roadmaps. Financial services and HR technology segments in Germany, France, and the Netherlands are restructuring procurement criteria to prioritize vendors with established conformity assessment procedures.
Enterprise buyers are consolidating vendor relationships around integrated platform ecosystems rather than point solutions. Healthcare systems and banking groups negotiate enterprise-wide licenses that bundle voice assistants with cloud infrastructure, productivity software, and security services, displacing standalone specialist providers. This bundling dynamic is most pronounced in the United States, where Azure and Google Cloud anchor procurement decisions through existing infrastructure commitments.
Smart Virtual Personal Assistants Market Segmentation
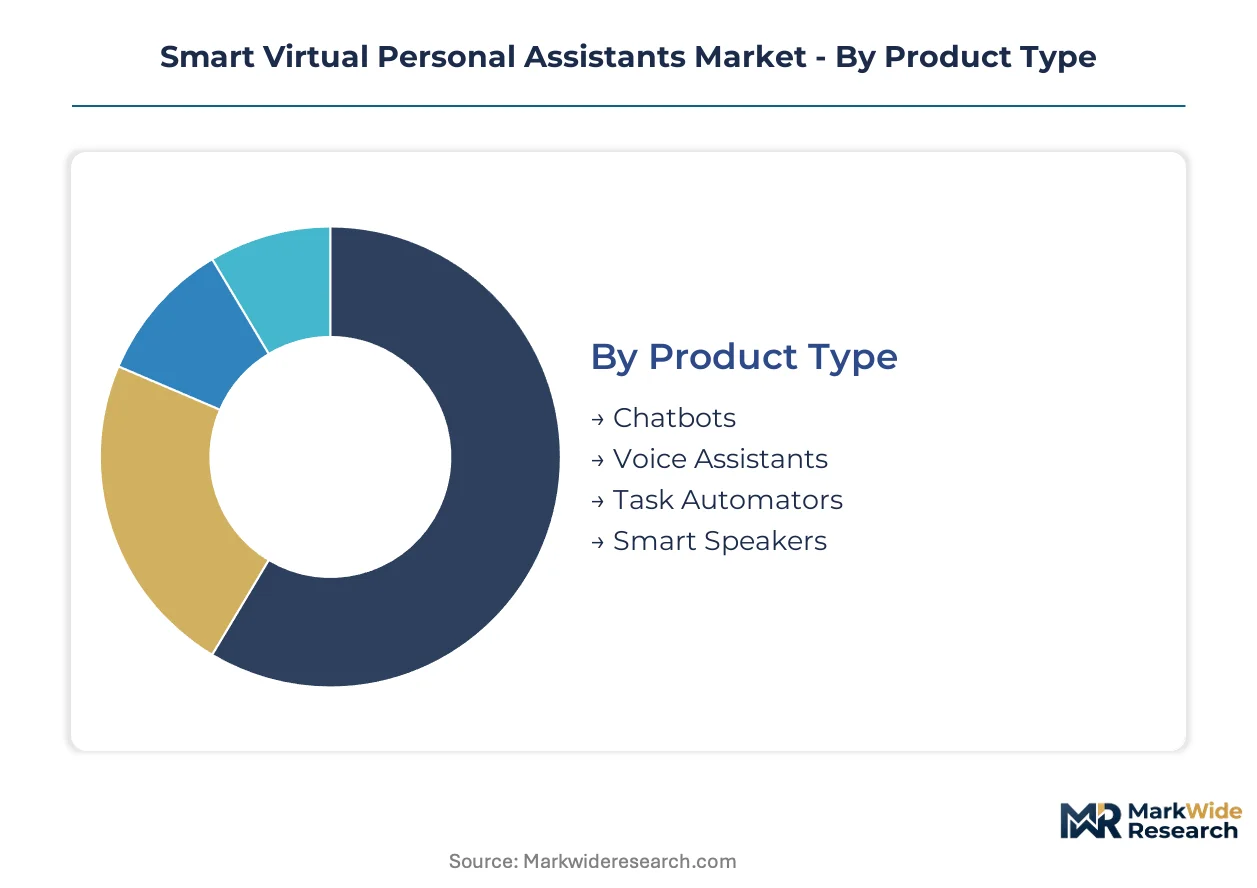
Segmentation in the Smart Virtual Personal Assistants Market reveals how deployment models, technical architectures, and user contexts fragment procurement criteria. Buyers prioritize different capabilities based on regulatory exposure, integration complexity, and end-user technical sophistication.
Product Type:
Cost tier differentiation separates consumer-grade hardware from enterprise software licenses and API consumption models.
- Voice Assistants:These systems process spoken commands through cloud-connected NLP pipelines, returning audio responses via smartphone, automotive, or smart speaker endpoints. US healthcare systems deploy FDA-scrutinized clinical documentation tools to reduce physician administrative burden. HIPAA compliance requirements and FDA's evolving clinical decision-support framework accelerate hospital procurement cycles for voice-enabled workflow tools.
- Task Automators:Workflow-embedded agents interface with CRM, ERP, and document management systems through standardized API connectors. Financial services and legal sectors in Germany and France adopt these tools to automate repetitive data entry and compliance documentation. GDPR Article 25 mandates for data protection by design favor vendors offering federated learning architectures and on-device processing capabilities.
- Chatbots:Text-based conversational interfaces deployed across websites and messaging platforms for customer service automation.
- Smart Speakers:Dedicated hardware devices with embedded microphones and speakers serving as ambient computing endpoints in residential environments.
Voice Assistants hold installed capacity. Task Automators is rotating up the share rankings.
Technology:
Application maturity varies sharply across inference deployment modes, from centralized cloud infrastructure to edge-optimized local execution.
- Natural Language Processing:Core linguistic analysis engines parse syntax, semantics, and intent from unstructured text or speech inputs. Transformer architectures with expanded contextual windows now handle multi-turn complex reasoning tasks. European enterprise buyers mandate privacy-preserving pipelines with on-device processing to satisfy GDPR data localization requirements.
- Cloud Computing:Scalable distributed infrastructure delivers model inference as metered API services. Azure and Google Cloud anchor enterprise procurement decisions through bundled infrastructure commitments in the United States. Cloud-native consumption models reconfigure competitive entry barriers for emerging assistant providers.
- Machine Learning:Statistical models trained on behavioral datasets to predict user intent and personalize responses.
- AI Algorithms:Proprietary reasoning frameworks governing decision-making logic and output generation.
Cloud Computing dominates current deployment volume. Natural Language Processing is climbing the fastest as edge optimization matures.
Use Case:
Customer type concentration shapes feature roadmaps, with B2B deployments demanding audit trails and B2C applications prioritizing frictionless interaction.
- Customer Support:Automated resolution of inquiries across voice, chat, and email channels with escalation protocols for complex issues. US banks and insurers deploy these systems at scale to manage high-volume transactional queries. Enterprise procurement mandates 12-18 month ISO 27001 and SOC 2 Type II certification cycles that delay market entry for emerging providers.
- Smart Home Integration:Unified control interfaces for lighting, climate, security, and entertainment systems through natural language commands. Automotive OEMs and residential construction developers in Japan seek multimodal convergence of voice, vision, and gesture to reduce cognitive load. METI's human-centric AI governance guidelines offer regulatory clarity that reduces compliance uncertainty.
- Personal Management:Calendar scheduling, reminder systems, and information retrieval for individual productivity.
- E-commerce:Product search, recommendation, and transaction completion through conversational interfaces.
Customer Support captures enterprise expenditure. Smart Home Integration is gaining share fastest as automotive and residential markets converge.
End User:
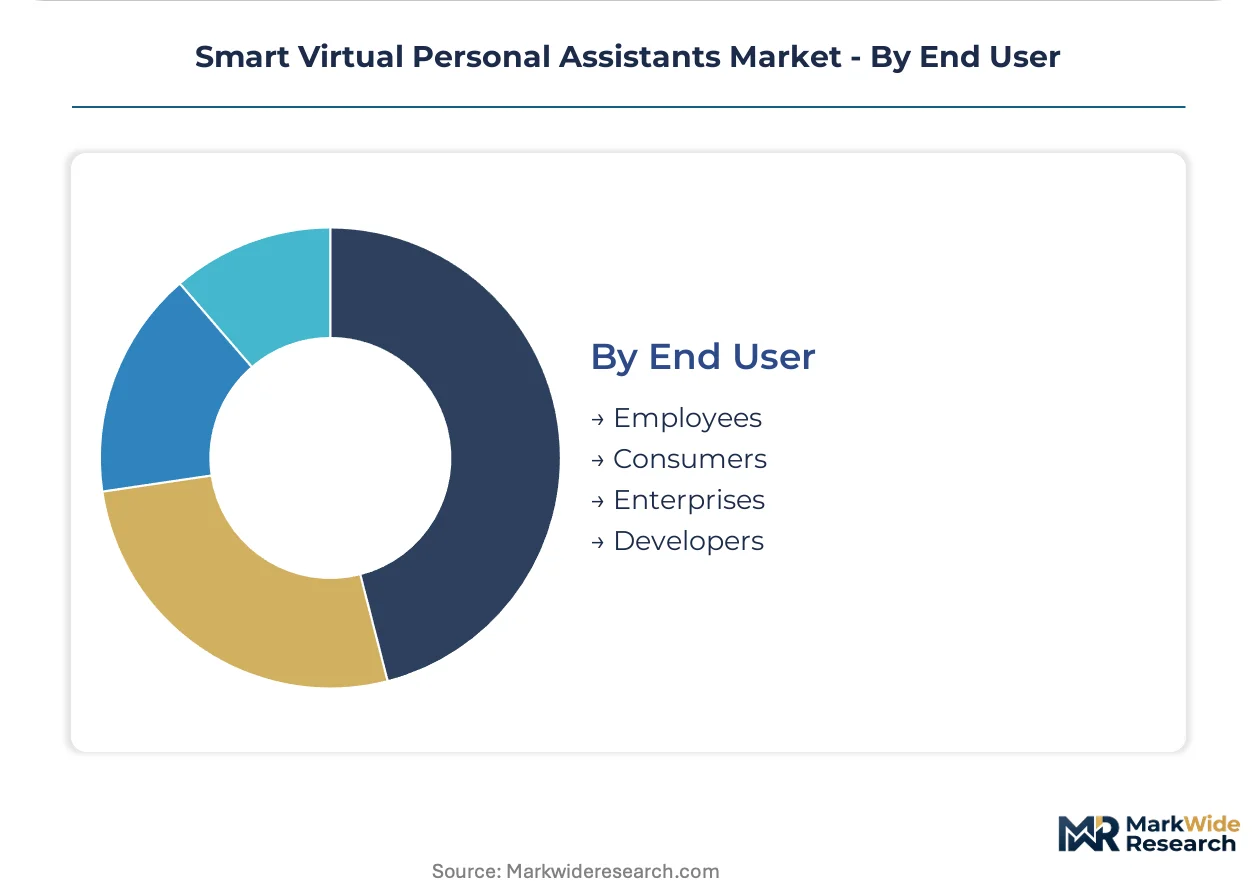
Volume concentration and margin structure diverge across technical sophistication tiers, from non-technical consumers to API-integrating developers.
- Enterprises:Organizations deploying assistants at departmental or organizational scale with centralized IT governance and security oversight. Healthcare systems and banking groups negotiate enterprise-wide licenses bundling voice assistants with cloud infrastructure and security services. This bundling dynamic displaces standalone specialist providers in the United States.
- Developers:Technical users building custom applications through API access and SDK toolkits. India's BIS certification pathway for AI system safety standards creates first-mover advantage for platforms achieving compliance ahead of mandatory implementation. Developer ecosystems concentrate innovation velocity in API-first platform leasing models.
- Consumers:Individual end-users interacting with assistants through personal devices without organizational procurement involvement.
- Employees:Workplace users accessing assistants through employer-provisioned tools and sanctioned application catalogs.
Enterprises dominate contract value. Developers is rotating up the share rankings as embedded deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement for voice-enabled automation clusters in healthcare and financial services verticals across five major economies. HIPAA compliance requirements in the United States and GDPR Article 25 mandates in Europe reshape deployment architectures and vendor selection criteria.
United States
Hospital systems and health insurers deploy FDA-scrutinized clinical documentation tools to reduce physician administrative burden. HIPAA privacy rules and the FDA's evolving clinical decision-support framework accelerate procurement cycles for voice-enabled workflow automation. Healthcare networks in Boston and the Research Triangle concentrate pilot deployments of ambient clinical intelligence.
Germany
Automotive OEMs and industrial equipment manufacturers integrate multimodal assistants into vehicle ECUs and factory floor systems. The EU AI Act's high-risk system classification imposes conformity assessment burdens on credit scoring and recruitment automation applications. Munich and Stuttgart anchor development clusters for edge-optimized inference engines.
Japan
Automotive manufacturers and residential construction developers seek unified voice-vision-gesture interfaces to reduce cognitive load. METI's human-centric AI governance guidelines offer regulatory clarity that reduces compliance uncertainty for enterprise deployments. Tokyo and Nagoya concentrate R&D investment in distributed AI architectures for latency-sensitive applications.
India
IT services firms and BPO operators adopt API-first platform leasing models to embed assistants into customer support workflows. The Bureau of Indian Standards is developing AI system safety standards for consumer electronics, creating first-mover advantage for early compliance achievers. Bangalore and Hyderabad anchor developer ecosystem concentration for conversational AI talent.
United Kingdom
Financial services firms and legal sector buyers mandate privacy-preserving NLP pipelines with federated learning architectures. GDPR data localization requirements and ISO 27001 certification demands shape procurement criteria for enterprise assistants. London and Edinburgh concentrate deployment of workflow-embedded task automators interfacing with CRM and document management systems.
Smart Virtual Personal Assistants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across cloud infrastructure, consumer hardware, and API platform layers. Hyperscale cloud operators leverage bundled infrastructure commitments to anchor enterprise procurement decisions. Three strategic archetypes dominate: infrastructure-anchored platforms, safety-framework differentiators, and hardware-embedded ecosystems. Competitive moves concentrate on API ecosystem expansion and edge optimization partnerships.
Within the infrastructure-anchored tier, Microsoft and Google exemplify platform operators leveraging cloud scale to bundle voice assistants with enterprise security and productivity services. Anthropic occupies a position among safety-conscious institutional buyers through constitutional AI frameworks. Amazon anchors the consumer hardware vector through smart speaker ecosystem penetration. These three represent distinct competitive positioning vectors rather than direct substitutability.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Anthropic |
| OpenAI |
| Amazon |
| Samsung |
| Arahi AI |
| Apple |
| Others |
Value Network & Pricing Analysis
GPU and TPU supply concentration in Taiwan and South Korea determines both pricing tier spreads and supply chain shape, as advanced node fabrication bottlenecks force cloud providers into long-term foundry commitments that compress margin flexibility across enterprise and consumer segments.
Pricing Analysis
Cost-plus contracts with semiconductor foundry indexation anchor enterprise SaaS pricing, with hyperscalers passing through wafer cost fluctuations via tiered consumption models. Price differentiation rests on inference latency guarantees and HIPAA certification tiers. Pricing pressure stems from edge-optimized model compression reducing cloud dependency. Mid-market healthcare buyers exhibit highest price sensitivity due to air-gapped deployment cost premiums.
Supply Chain Analysis
Supplier-financing facilities from Taiwan Semiconductor Manufacturing and Samsung Foundry extend payment terms for volume commitments, easing working capital strain for cloud operators. Advanced node fabrication concentrates in Taiwan and South Korea, with packaging and testing distributed across Malaysia and Vietnam. The supply chain draws from silicon wafers, EUV lithography equipment, and specialized substrates. Single-source vulnerability in sub-3nm process nodes threatens inference cost stability. Distribution runs through hyperscale cloud marketplaces and direct enterprise licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Virtual Personal Assistants Market represents high-growth disruption as FDA's clinical decision-support framework and the EU AI Act's risk-tiered obligations simultaneously expand addressable demand and erect compliance barriers that favor capitalized platforms.
For Market Incumbents: Build regulatory certification moats through ISO 27001 and SOC 2 Type II pre-certification pipelines that extend audit timelines for emerging competitors. Pursue backward integration into edge-optimized silicon design to reduce foundry dependency exposure. Anchor enterprise procurement through Azure and Google Cloud infrastructure bundling that displaces standalone specialists.
For New Entrants and Emerging Players: Pursue India's BIS certification pathway ahead of mandatory AI safety standards implementation to secure first-mover positioning in consumer electronics. Target workflow-embedded task automators for mid-market legal and financial services in Germany and France, where GDPR Article 25 mandates favor federated learning architectures. Lead with API-first platform leasing models that minimize upfront infrastructure investment.
For Investors and Strategic Acquirers: The EU AI Act's high-risk system classification reshapes the acquisition landscape toward platforms with established conformity assessment procedures and human oversight capabilities. Long-term viability centers on edge inference virtualization disrupting centralized cloud economics. Target developer ecosystem platforms with embedded deployment expansion trajectories. Monitor FDA clinical decision-support guidance evolution as inflection indicator for healthcare automation procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and Google Cloud bundling anchors enterprise procurement decisions across regulated US healthcare networks. |
| Regulatory Pre-Certification | ISO 27001 and SOC 2 Type II pipelines extend audit timelines that delay market entry for emerging competitors. |
| Edge Optimization Partnership | Automotive OEM collaborations for vehicle ECU embedding fragment pricing power away from hyperscale operators. |
| Acquisition of Specialist Firm | Conversational AI talent scarcity makes computational linguistics and RLHF teams priority targets for capability consolidation. |
| Geographic Expansion | India's BIS certification pathway creates first-mover advantage for platforms achieving compliance ahead of mandatory standards. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cloud platform engineers, enterprise IT procurement officers, healthcare system CIOs, and conversational AI product leads; and secondary validation against SEC filings from hyperscalers, FDA clinical decision-support guidance documents, EU AI Act implementation roadmaps, and hospital procurement database records. Bottom-up segment sizing triangulated against top-down infrastructure spend estimates.
Forecast inputs considered deployment model adoption curves, organization size penetration patterns, vertical regulatory exposure tiers, and regional cloud infrastructure commitments across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, use case context, and end-user technical sophistication. CAGRs derived from inference demand elasticity and enterprise automation substitution rates.
Sensitivities concentrate around foundry capacity allocation decisions, FDA guidance evolution timelines, and EU AI Act enforcement intensity. Forecasts reflect documented assumptions regarding edge optimization maturation and healthcare procurement cycle normalization. Macroeconomic contraction, geopolitical supply disruption, or fundamental NLP architecture breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market