
 Automotive HVAC Market | 2026-2036
Automotive HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive HVAC Market Analysis
Electrical engineering talent for thermal system design is collapsing across Tier-1 supplier bases, compressing development timelines for next-generation heat pump modules. Denso Corporation leverages its in-house semiconductor and compressor integration to sustain design-to-production velocity in Japanese and North American plants. Valeo anchors European OEM relationships through dedicated EV thermal management R&D centers in France and Germany. MAHLE GmbH competes by extending its compressor portfolio into CO2-based systems for cold-climate performance.
Automotive HVAC encompasses climate control systems that regulate cabin temperature, humidity, and air quality through vapor-compression cycles, typically operating with refrigerants at pressures between 1.5 and 3.5 MPa and temperature differentials across heat exchangers of 15°C to 25°C. These systems serve dual purposes of occupant comfort and, in electric vehicles, battery thermal stability to preserve range and charging speed. Compressors command the dominant margin pool within product type segmentation due to electromechanical complexity and refrigerant-specific engineering requirements. Automatic and smart technology categories are expanding fastest as cabin zone control and predictive thermal algorithms become standard in premium and mass-market EV platforms.
The EPA enforces refrigerant transition timelines under the AIM Act, while NHTSA fuel economy standards indirectly elevate HVAC efficiency targets through vehicle-level compliance obligations. EMA's framework for fluorinated gas restrictions under the EU Green Deal shapes European OEM sourcing strategies toward low-GWP alternatives. Stakeholders must monitor refrigerant chemistry patent landscapes and regional certification timelines to avoid supply chain displacement as regulatory phase-downs accelerate.
Market Dynamics
Heat pump architecture standardization for electric vehicle platforms is compressing development cycles while expanding system complexity beyond traditional cabin-only thermal management. Tier-1 suppliers must now integrate battery conditioning, motor cooling, and passenger comfort within unified control loops.
Growth Catalysts
- EPA AIM Act Phase-Down:The refrigerant transition mandate accelerates R-1234yf adoption across vehicle production lines, forcing equipment retooling that favors suppliers with certified low-GWP system portfolios.
- EV Battery Thermal Stability:Lithium-ion cell chemistry demands precise temperature maintenance during fast-charging cycles, expanding HVAC system scope from occupant comfort to powertrain protection.
- China Domestic EV Manufacturing:Heat pump penetration in Chinese electric vehicle platforms outpaces other production regions, creating concentrated demand for integrated compressor-heat exchanger modules.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger manufacturing depends on base metal prices that fluctuate with energy costs, compressing margin predictability for system integrators.
- Semiconductor Supply Concentration:Variable-speed compressor controllers and sensor arrays require chips sourced from concentrated East Asian foundry capacity, exposing production schedules to geographic disruption.
- R-1234yf Patent Licensing:Refrigerant chemistry intellectual property held by select chemical conglomerates imposes royalty structures that inflate system costs for non-integrated suppliers.
Strategic Opportunities
- CO2 Transcritical Systems:Cold-climate performance limitations of conventional refrigerants create white space for CO2-based heat pumps in Nordic and Canadian vehicle markets.
- Predictive Thermal Algorithms:Machine learning integration with navigation and occupancy sensors enables anticipatory cabin conditioning, differentiating premium EV platforms.
- Aftermarket Retrofit Channels:Aging internal combustion fleet conversion to low-GWP refrigerants under EPA enforcement creates service revenue pools for certified technician networks.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled thermal-fluid-electrical modeling for heat pump optimization requires engineers trained in specialized CAE platforms, with competition from aerospace and energy sectors.
- Dual Certification Timelines:SAE and ISO thermal performance standards diverge in test protocols, forcing redundant validation cycles for global vehicle programs.
- Legacy Architecture Integration:Internal combustion platforms with belt-driven compressors resist modular heat pump retrofit without structural redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive HVAC Market |
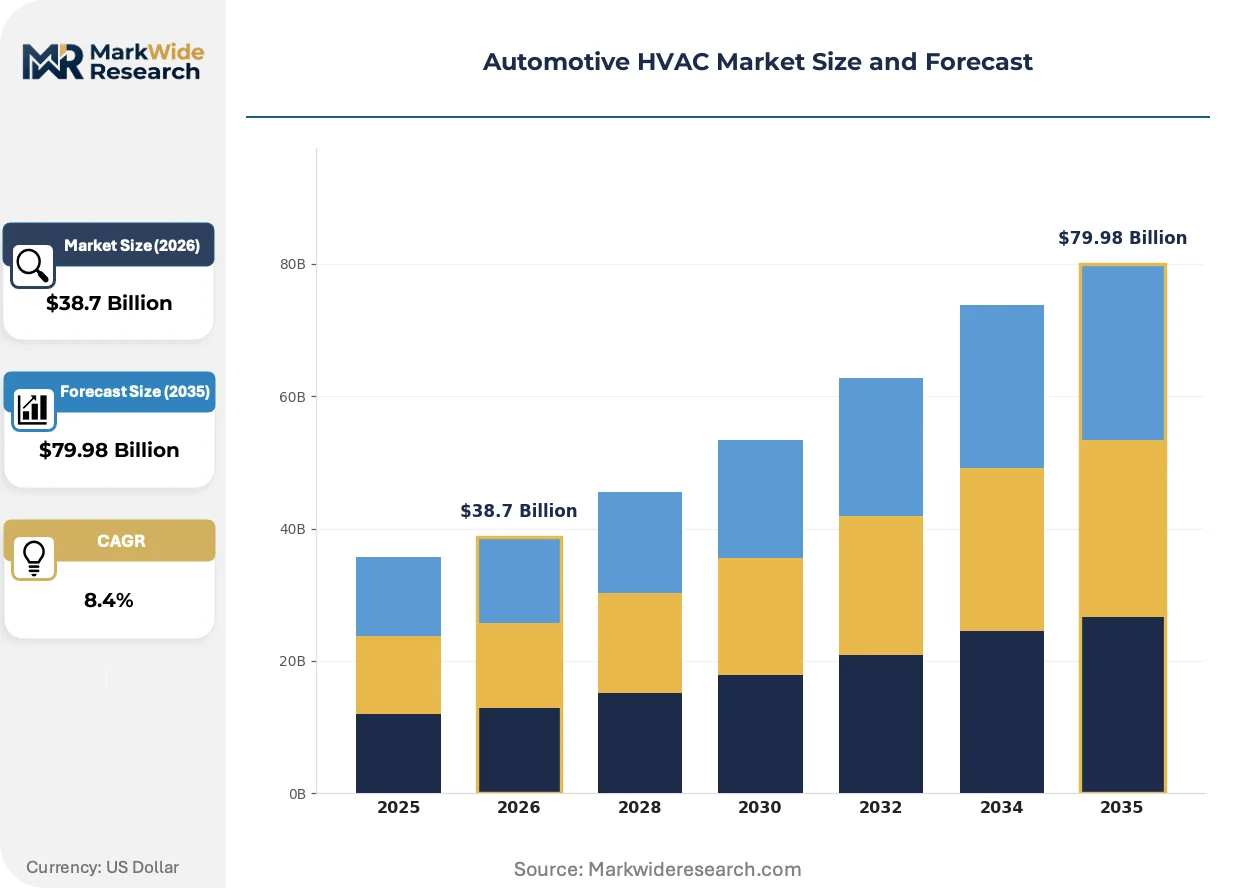
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Compressors, Evaporators, Blowers Technology: Manual, Automatic, Hybrid, Smart End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Installation: Integrated, Modular, Retrofit, Custom |
| Companies Covered | Marelli Corporation, MAHLE GmbH, Denso Corporation, Sensata Technologies, Keihin Corporation, Valeo, Sanden Holdings Corporation, Johnson Electric Holdings, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive HVAC Market Emerging Trajectories
Thermal management system architecture is bifurcating between integrated heat pump platforms for electric vehicles and efficiency-optimized conventional systems for remaining combustion production. This divergence demands distinct engineering competencies and supplier capabilities.
Refrigerant circuitry is decomposing into function-specific loops for battery, cabin, and power electronics thermal zones. EV manufacturers in Germany and Japan are adopting this distributed architecture to enable independent temperature targeting. The approach is decomposing the traditional single-evaporator design paradigm into modular subsystems that compress development timelines through parallel engineering workstreams.
The EU F-Gas Regulation and its automotive-specific amendments are accelerating refrigerant chemistry transitions with mandatory GWP thresholds. OEM sourcing departments now embed carbon-equivalent metrics alongside cost in supplier scorecards. European premium vehicle segments are responding fastest, with heat pump penetration rates exceeding other regulatory jurisdictions due to compliance-driven platform redesigns.
Buyer evaluation criteria are migrating from component cost to total cost of ownership metrics spanning energy consumption and service intervals. Fleet procurement departments for ride-hail and delivery operators now request predictive maintenance data feeds from HVAC system suppliers. This shift is most visible in California and the Netherlands, where electrified commercial vehicle deployment concentrates and uptime economics dominate acquisition decisions.
Automotive HVAC Market Segmentation
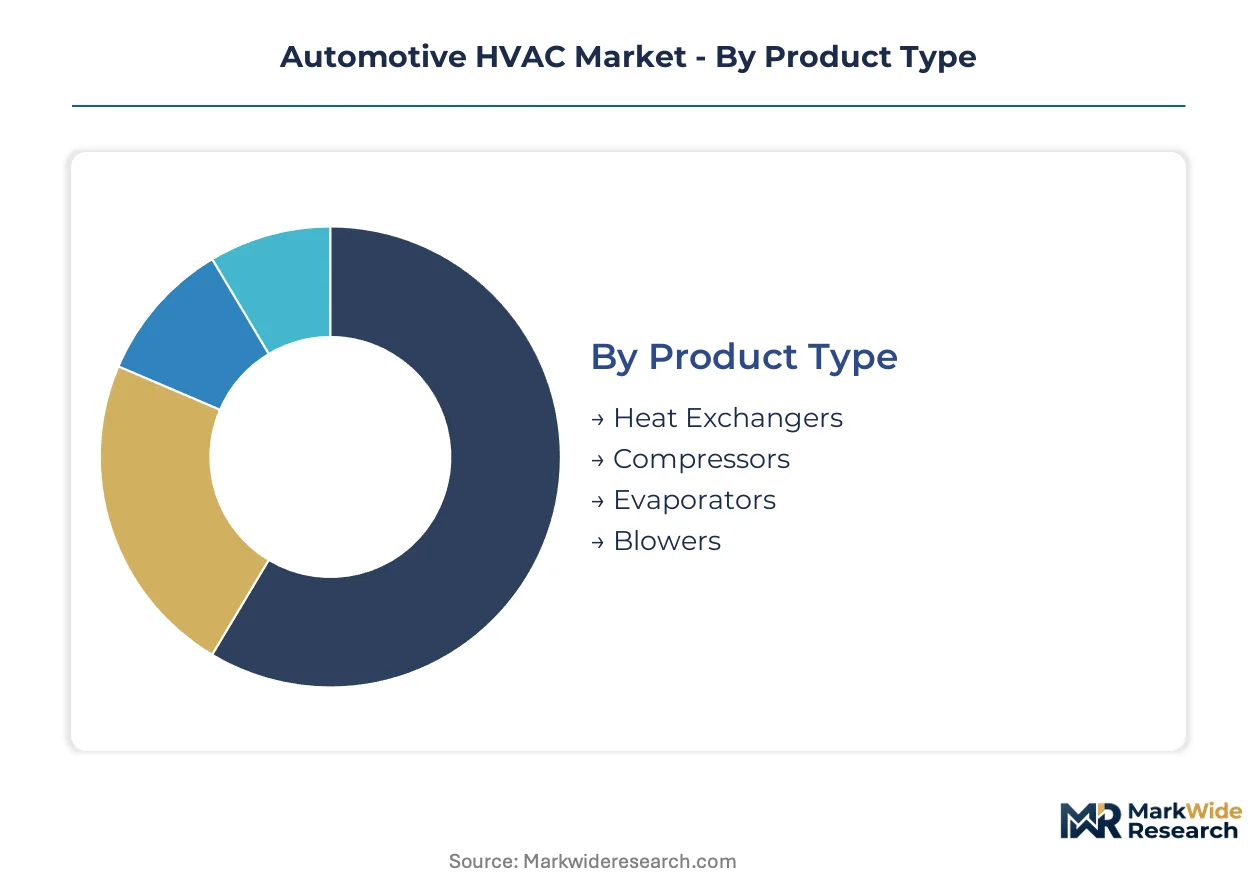
Automotive HVAC segmentation reveals where value concentrates across hardware, control intelligence, and channel access. Product type and technology categories capture the dominant margin pools, while installation and end-user dimensions determine go-to-market economics for suppliers.
Product Type:
Margin pools concentrate in electromechanical components where refrigerant-specific engineering and precision manufacturing create defendable positions.
- Compressors:Electromechanical units operating at 1.5 to 3.5 MPa with refrigerant-specific sealing and variable-speed control. Demand clusters in Chinese EV platforms where integrated compressor-heat exchanger modules support heat pump architectures. Patent licensing costs for R-1234yf compatibility compress margins for non-integrated suppliers.
- Heat Exchangers:Aluminum-copper assemblies managing 15°C to 25°C temperature differentials across refrigerant and coolant circuits. Procurement concentrates with OEMs pursuing battery thermal stability alongside cabin comfort, expanding unit size and complexity per vehicle. Base metal price volatility directly impacts manufacturing economics.
- Evaporators:Plate-fin or tube-and-fin configurations for cabin air cooling.
- Blowers:Centrifugal or axial fan assemblies for cabin air distribution.
Compressors hold installed capacity. Heat exchangers are rotating up the share rankings.
Technology:
Control sophistication determines pricing tiers, with sensor density and algorithmic content separating premium from standard offerings.
- Smart:Machine-learning-enabled systems integrating navigation data, occupancy sensing, and predictive thermal algorithms. Deployment concentrates in California and Netherlands fleet procurement where uptime economics and energy consumption metrics drive acquisition decisions. Predictive maintenance data feeds differentiate supplier relationships with commercial operators.
- Automatic:Multi-zone climate control with sensor-based temperature modulation. Penetration expands fastest in European premium segments responding to EU F-Gas Regulation compliance requirements and platform redesigns. Zone control complexity elevates semiconductor and sensor content per vehicle.
- Manual:Basic dial or lever-operated temperature and fan speed adjustment.
- Hybrid:Combined electric-compressor and engine-driven configurations for transitional powertrain architectures.
Automatic systems hold installed capacity. Smart technology is rotating up the share rankings.
End User:
Channel structure shapes service revenue potential and product lifecycle exposure for component suppliers.
- OEMs:Direct supply relationships for new vehicle production with platform-specific thermal system integration. Sourcing in Germany and Japan prioritizes distributed refrigerant circuitry architectures enabling independent battery, cabin, and power electronics temperature targeting. Design-to-production velocity requirements favor suppliers with in-house semiconductor and compressor capabilities.
- Fleet Operators:Centralized procurement for ride-hail and delivery electrified commercial vehicles. Concentrated deployment in California and Netherlands markets demands predictive maintenance data feeds and total cost of ownership metrics replacing component-first evaluation. Uptime economics dominate HVAC system selection criteria.
- Aftermarket Providers:Independent service networks for refrigerant conversion and component replacement.
- Dealerships:Authorized service channels for warranty and maintenance work.
OEMs hold installed capacity. Fleet operators are rotating up the share rankings.
Installation:
Integration depth determines engineering resource allocation and validation timeline exposure for suppliers.
- Integrated:Factory-installed systems designed into vehicle architecture with unified control loops for battery, motor, and cabin thermal management. EV platforms in China and Germany adopt this approach to compress development timelines through parallel engineering workstreams. Structural redesign requirements resist retrofit on legacy internal combustion platforms.
- Modular:Pre-assembled subsystems enabling parallel vehicle assembly line integration.
- Retrofit:EPA AIM Act-driven refrigerant conversion for aging internal combustion fleet.
- Custom:Specialized configurations for commercial vehicle or extreme climate applications.
Integrated systems hold installed capacity. Modular installation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese supply chains while Chinese manufacturers compress margins through vertical integration of compressor and heat exchanger production. European OEMs absorb premium engineering costs for EU F-Gas Regulation compliance. North American producers face EPA AIM Act retooling expenses that favor suppliers with certified low-GWP portfolios already validated for R-1234yf.
United States
Fleet electrification in California and ride-hail operator procurement drive demand for predictive thermal management systems with uptime data feeds. EPA AIM Act phase-down mandates accelerate R-1234yf conversion across domestic production lines. Detroit-area engineering centers focus on integrating battery conditioning with cabin comfort in unified control architectures for next-generation EV platforms.
China
Domestic EV manufacturers BYD and NIO integrate sophisticated heat pump architectures that expand thermal management scope beyond traditional cabin comfort. MIIT fuel efficiency standards and dual carbon goals pressure OEMs toward CO2-based system development. Shanghai and Shenzhen manufacturing clusters concentrate integrated compressor-heat exchanger module production for both domestic consumption and export markets.
Germany
Premium vehicle segments command heat pump penetration rates exceeding other regulatory jurisdictions through compliance-driven platform redesigns. EU F-Gas Regulation and automotive-specific amendments enforce mandatory GWP thresholds that reshape supplier scorecards. Stuttgart and Munich engineering centers pioneer distributed refrigerant circuitry architectures enabling independent battery, cabin, and power electronics temperature targeting.
Japan
Keihin and Denso anchor electromechanical component supply through in-house semiconductor integration that sustains design-to-production velocity. METI energy efficiency standards elevate HVAC system performance targets through vehicle-level compliance obligations. Nagoya and Tokyo manufacturing facilities concentrate variable-speed compressor controller production amid concentrated East Asian foundry exposure.
South Korea
Hyundai and Kia EV platforms drive demand for cold-climate heat pump performance that tests conventional refrigerant limitations. Ministry of Environment fluorinated gas management policies align with EU regulatory trajectories toward low-GWP alternatives. Seoul and Ulsan industrial complexes concentrate thermal system assembly for export-oriented vehicle programs targeting Nordic and Canadian markets.
Automotive HVAC Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated Japanese and Korean conglomerates commanding electromechanical complexity while Chinese suppliers compress manufacturing economics through captive component production. The vendor base stratifies across three tiers: semiconductor-integrated system architects, refrigerant-specialized component fabricators, and regional assembly contractors serving aftermarket channels. Dominant competitive moves include backward integration into compressor controller silicon and strategic partnerships with chemical conglomerates for R-1234yf patent licensing.
Within the integrated system architect tier, Denso Corporation and MAHLE GmbH occupy positions that exemplify divergent geographic anchoring strategies. Denso represents the semiconductor-captive Japanese model with Nagoya-centered engineering velocity, while MAHLE GmbH anchors European OEM relationships through Stuttgart-area R&D concentration. Valeo sits within the premium-tier European specialist archetype, with Paris-region engineering centers serving compliance-driven platform redesigns. These three entities collectively illustrate how refrigerant chemistry transitions and EV thermal architecture complexity are restructuring competitive position around in-house controller capabilities and regional regulatory proximity.
| Leading Market Players |
|---|
| Marelli Corporation |
| MAHLE GmbH |
| Denso Corporation |
| Sensata Technologies |
| Keihin Corporation |
| Valeo |
| Sanden Holdings Corporation |
| Johnson Electric Holdings |
| Hanon Systems |
| Others |
Supply Flow & Price Mechanics
R-1234yf refrigerant substitution for R-134a simultaneously redraws procurement geography toward Honeywell and Chemours patent territories and compresses margin structures for non-integrated suppliers lacking direct chemical conglomerate relationships. This chemistry transition reshapes both input cost trajectories and supplier qualification timelines across North American and European production lines.
Pricing Analysis
Geographic price spreads between Chinese integrated compressor-heat exchanger modules and European electromechanical components reach three-to-one ratios, with Shanghai and Shenzhen manufacturing clusters undercutting Stuttgart and Munich engineering centers on unit economics. Pricing stratifies across premium, standard, and economy tiers based on semiconductor integration depth and refrigerant certification grade. Pricing pressure stems from base metal volatility in aluminum-copper heat exchanger fabrication, with copper futures transmitting energy cost shocks directly into component landed costs. Fleet procurement departments in California and the Netherlands exhibit lowest price sensitivity due to uptime economics, while aftermarket retrofit channels face acute margin compression from EPA certification requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate Japanese and Korean compressor controller production, while European heat pump module assembly maintains strategic aluminum stockpiles against London Metal Exchange volatility. Geographic supply concentration centers on China for integrated compressor-heat exchanger modules, Japan for variable-speed controller silicon, and Germany for distributed refrigerant circuitry architectures. Raw material dependencies draw from Chilean copper cathode, Australian bauxite for aluminum smelting, and East Asian semiconductor wafer fabrication. Single-source vulnerability concentrates in R-1234yf refrigerant chemistry patents held by select chemical conglomerates. Distribution runs through Tier-1 supplier direct OEM relationships with platform-specific engineering validation, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where EPA AIM Act certification timelines and EU F-Gas Regulation compliance requirements create multi-year barriers against unqualified competitors.
For Market Incumbents: Shield installed OEM relationships by accelerating backward integration into compressor controller silicon production before East Asian foundry concentration disrupts supply schedules. Expand Stuttgart and Nagoya engineering center capacity to compress dual SAE-ISO validation cycles. Patent licensing leverage with refrigerant chemistry holders remains the critical defensive lever against margin erosion from royalty-encumbered competitors. For New Entrants and Emerging Players: Differentiate on CO2 transcritical system architectures for Nordic and Canadian cold-climate applications where conventional refrigerant performance limits create technical white space. Target aftermarket retrofit channels under EPA enforcement timelines, where certified technician network scarcity constrains incumbent response speed. Pursue fleet operator direct procurement relationships in California and Netherlands markets by embedding predictive maintenance data feeds as standard contract terms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European refrigerant-specialized component fabricators facing EU F-Gas Regulation compliance investment requirements. Long-term viability favors semiconductor-integrated system architects with captive controller production and direct OEM platform engineering relationships. Watch R-1234yf patent expiration schedules and CO2 system cost-parity thresholds as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Patent Licensing | Direct agreements with Honeywell or Chemours secure R-1234yf supply terms and block competitor access. |
| Compressor Controller Silicon Integration | In-house semiconductor production insulates against East Asian foundry disruption and sustains design velocity. |
| CO2 Transcritical System Development | Cold-climate performance advantages capture Nordic and Canadian OEM platform specifications ahead of rivals. |
| Predictive Thermal Algorithm Deployment | Machine-learning integration with navigation data differentiates premium EV platforms in California fleet procurement. |
| Aftermarket Certification Network Buildout | EPA AIM Act compliance creates captive service revenue pools from aging internal combustion fleet conversion. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU F-Gas Regulation amendments, vehicle production databases, and IHS Markit registration data. Primary interviews engaged Tier-1 supplier procurement directors, OEM platform thermal engineers, aftermarket distributor operations heads, and fleet procurement managers at California ride-hail operators. Bottom-up unit economics triangulate against top-down market sizing across compressor, heat exchanger, and control module categories.
Segmentation dimensions modeled span vehicle propulsion architecture, thermal system technology tier, installation integration depth, and regional production cluster across the projection horizon. CAGRs derive from fitted growth curves against historical adoption patterns for refrigerant transitions and EV platform penetration. Industry-specific forecast inputs incorporate EPA AIM Act phase-down enforcement timelines and MIIT fuel efficiency standard trajectories.
Material uncertainties — copper and aluminum price volatility, semiconductor supply disruption, refrigerant patent litigation outcomes — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement consistency and EV platform production scaling. Revision becomes warranted when base metal price swings exceed historical bands or when refrigerant chemistry patent pools fragment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market