
 Drone-In-A-Box Market | 2026-2036
Drone-In-A-Box Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-In-A-Box Market Analytics
EU Green Deal emissions monitoring mandates for industrial facilities is expanding compliance-driven procurement of autonomous aerial systems. Skydio leverages computer vision autonomy to dominate North American public safety deployments. Percepto anchors remote infrastructure inspection through AI-powered analytics platforms. AeroVironment sustains defense-sector relationships with hardened, portable drone systems.
A drone-in-a-box system integrates an unmanned aerial vehicle with an automated docking station, typically featuring battery swap mechanisms, weatherproofing rated to IP65 or higher, and edge computing nodes for pre-processed data transmission; the assembly enables repeatable, human-free flight cycles for commercial and industrial surveillance tasks. Multi-rotor drones lead current installations due to vertical takeoff precision in confined sites, while hybrid drones capture the fastest expansion as endurance demands stretch beyond thirty minutes for linear infrastructure surveys. Agricultural monitoring use cases mature around predictable seasonal scheduling, whereas delivery services concentrate margin pools in last-mile urban logistics where labor cost arbitrage proves decisive.
The FAA regulates beyond-visual-line-of-sight waivers under Part 107, while EASA implements specific category frameworks for autonomous operations across European member states, and ISO 21384-3 governs operational procedures that manufacturers must embed for cross-border market access. Regulatory fragmentation between FAA risk-based approvals and EASA's predefined standard scenarios forces dual certification strategies for vendors targeting transatlantic contracts. Stakeholders must monitor emerging detect-and-avoid performance standards that will determine which platforms qualify for dense airspace integration without human observers.
Market Dynamics
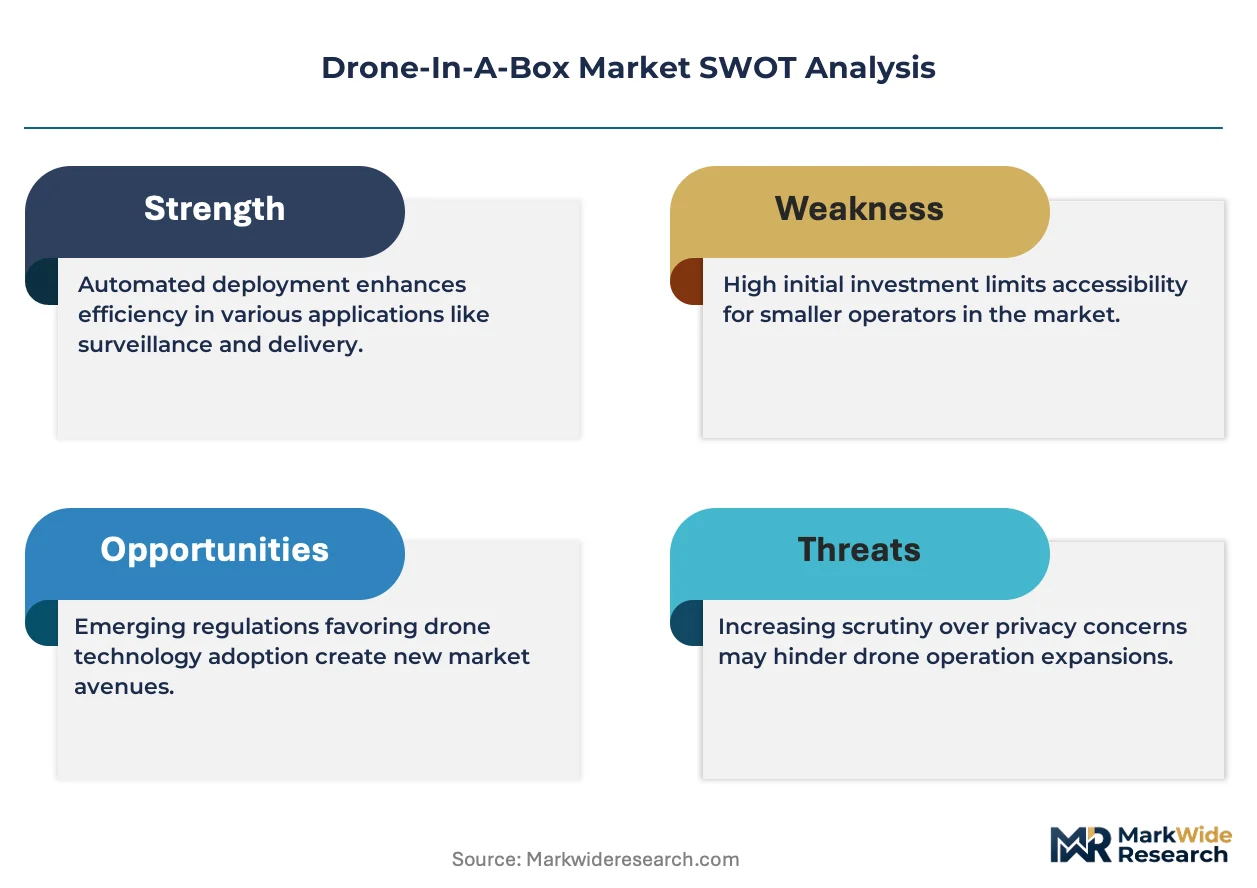
Beyond-visual-line-of-sight regulatory approvals are compressing deployment timelines and redrawing competitive boundaries between autonomous hardware vendors and software-centric autonomy providers.
Growth Catalysts
- FAA Part 107 waiver streamlining:Risk-based approval frameworks in the United States are accelerating commercial deployments for linear infrastructure inspection.
- EU Green Deal emissions mandates:Industrial facility operators across European member states now procure autonomous aerial systems for continuous environmental compliance monitoring.
- Edge computing integration:Onboard pre-processing nodes reduce bandwidth requirements and enable real-time anomaly detection for pipeline operators.
Market Restraints
- Dual certification burden:Transatlantic vendors face redundant compliance costs from divergent FAA risk-based approvals and EASA standard scenario frameworks.
- Lithium-ion battery supply concentration:Cell production clustering in East Asian manufacturing hubs exposes docking station manufacturers to input volatility and logistics disruption.
- Detect-and-avoid performance uncertainty:Pending technical standards for dense airspace integration without human observers create platform qualification delays.
Strategic Opportunities
- Hybrid drone endurance gaps:Thirty-plus-minute flight times for linear infrastructure surveys create white space for fixed-wing VTOL convergence platforms.
- Last-mile urban logistics:Labor cost arbitrage in dense metropolitan delivery corridors is concentrating margin pools for automated docking networks.
- ISO 21384-3 harmonization:Cross-border operational procedure standards will reduce certification friction for vendors targeting multi-jurisdictional contracts.
Industry Challenges
- Autonomy engineering talent scarcity:Computer vision and embedded systems specialists command premium compensation, constraining mid-tier vendor R&D scaling.
- Legacy SCADA integration complexity:Industrial facility operators require custom middleware development to connect drone data streams with existing asset management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-In-A-Box Market |
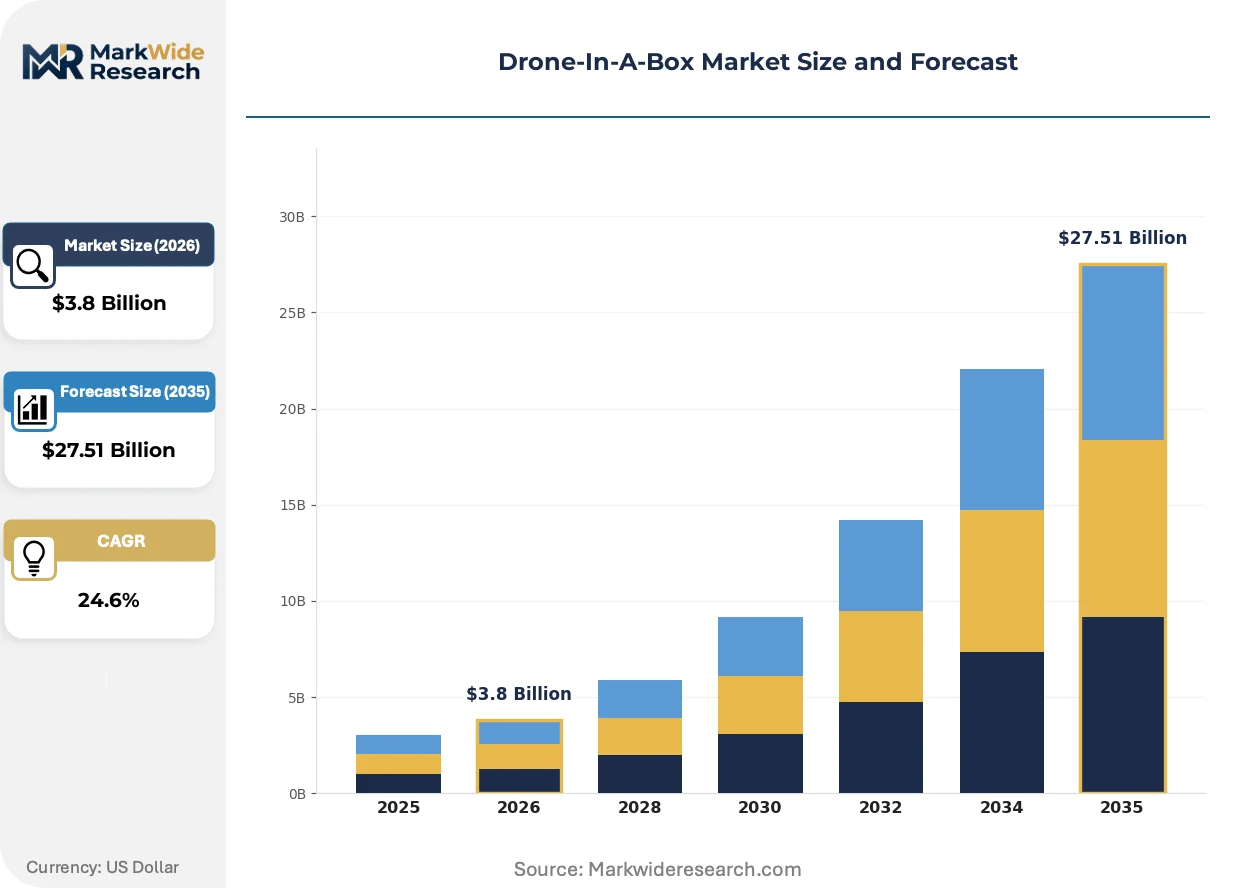
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multi-Rotor Drones, Hybrid Drones, Nano Drones Use Case: Surveillance, Delivery Services, Agricultural Monitoring, Infrastructure Inspection Technology: GPS, Computer Vision, LiDAR, Communication Protocols End User: Logistics, Agriculture, Public Safety, Construction |
| Companies Covered | Asylon, Skyfish, Percepto, Brinc, Draganfly, Skydio, Easy Aerial, AeroVironment, Azur Drones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-In-A-Box Market Evolving Landscape
Autonomous systems are migrating from pilot-dependent operations toward fully unattended flight cycles, with docking station intelligence and airspace integration protocols advancing in parallel.
Computer vision-based navigation is converging with automated battery swap mechanisms to enable true human-free operation cycles. Oil and gas pipeline operators in Texas deployment corridors are adopting these integrated systems fastest. The technology is converging with predictive maintenance platforms to compress inspection cycle times from weeks to hours.
EASA's specific category framework for autonomous operations is mandating predefined standard scenarios that simplify type certification for compliant vendors. Industrial inspection providers must now demonstrate conformity with standardized risk assessments rather than pursuing individual operational authorizations. European energy infrastructure operators are consolidating procurement around EASA-certified platforms to reduce regulatory uncertainty.
Facility operators are unbundling after-sales service contracts from hardware acquisition, favoring availability-based pricing tied to flight-hour guarantees. Traditional system integrators are losing ground to manufacturers offering direct performance commitments. This shift is most visible in agricultural monitoring, where seasonal scheduling predictability enables precise uptime contracting.
Drone-In-A-Box Market Segmentation
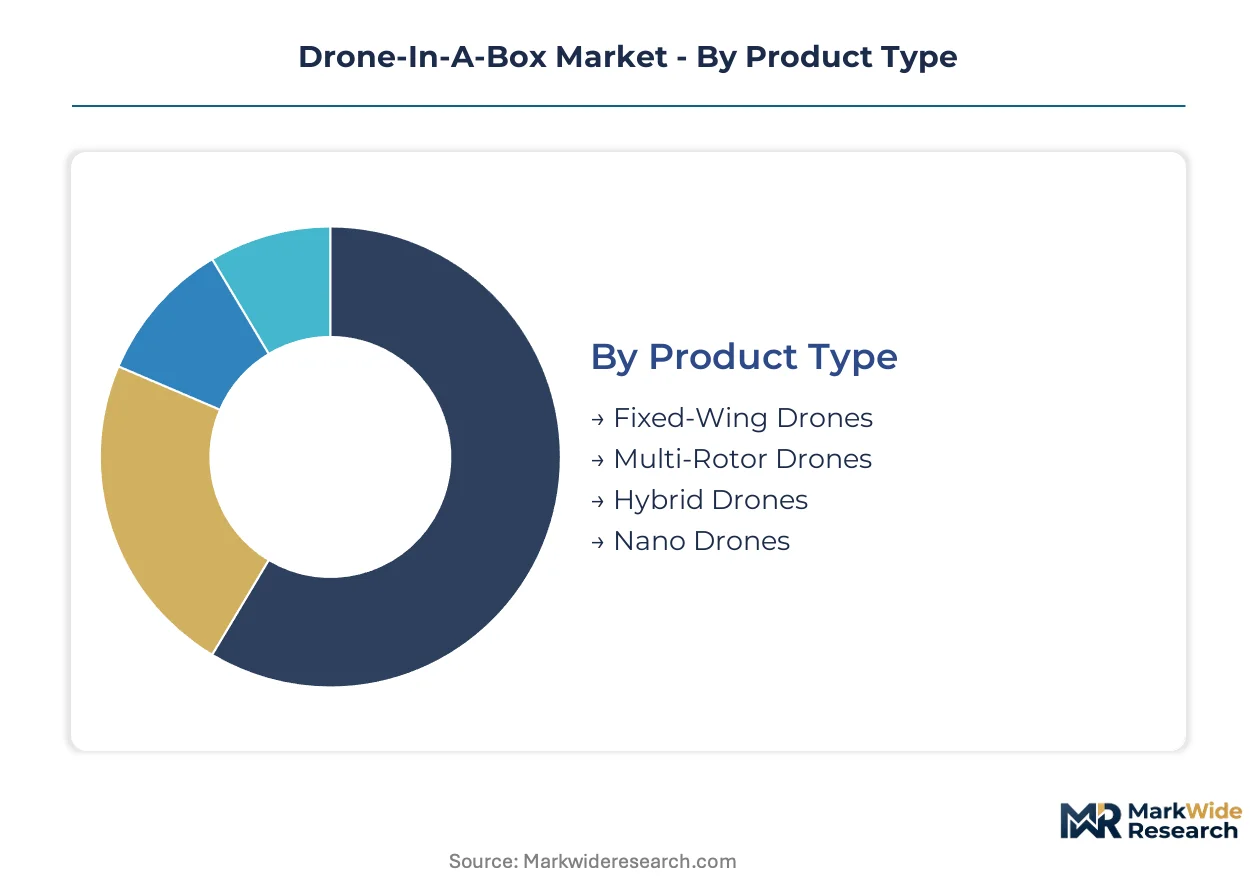
Drone-in-a-box systems fragment across platform architectures, mission profiles, and integration depths. Each segmentation axis reveals distinct margin structures and deployment constraints that shape procurement decisions across energy, logistics, and public safety verticals.
Product Type:
Standardization versus customization tension runs deepest here, with off-the-shelf multi-rotor platforms competing against engineered-to-order hybrid configurations for linear infrastructure missions.
- Multi-Rotor Drones:Vertical takeoff precision dominates confined-site deployments. Texas pipeline corridors concentrate procurement where terrain constraints prevent runway-dependent alternatives. FAA Part 107 waiver holders favor these for rapid deployment cycles.
- Hybrid Drones:Fixed-wing VTOL convergence delivers thirty-plus-minute endurance for power line and pipeline surveys. EASA specific category certification is accelerating European energy operator adoption ahead of dense airspace integration mandates.
- Fixed-Wing Drones:Runway-dependent platforms persist in agricultural monitoring where open-field access permits conventional launch profiles and endurance economics outweigh flexibility constraints.
- Nano Drones:Sub-250-gram platforms evade regulatory registration thresholds in urban delivery pilots, though payload limitations restrict commercial viability to lightweight document and pharmaceutical corridors.
Most installed capacity flows through Multi-Rotor Drones. Expansion is steepest in Hybrid Drones.
Use Case:
Volume concentration shifts toward recurring-revenue inspection contracts as one-off surveillance sales plateau and delivery economics remain unresolved.
- Infrastructure Inspection:Continuous leak detection and predictive maintenance compress cycle times from weeks to hours. Oil and gas operators in Texas deployment corridors drive procurement concentration.
- Surveillance:Perimeter security and event monitoring mature around predictable scheduling. Public safety agencies favor availability-based pricing tied to flight-hour guarantees over capital acquisition.
- Agricultural Monitoring:Seasonal predictability enables precise uptime contracting. European operators align procurement with EU Green Deal emissions verification mandates for industrial agriculture facilities.
- Delivery Services:Last-mile urban logistics concentrate margin pools where labor cost arbitrage proves decisive, though regulatory uncertainty around dense airspace integration delays scaled deployment.
Revenue pools concentrate in Infrastructure Inspection. Delivery Services face the steepest regulatory headwinds.
Technology:
Core navigation and sensing stacks determine platform autonomy levels and corresponding certification pathways across FAA and EASA jurisdictions.
- Computer Vision:Onboard autonomy enables true human-free operation cycles without GPS dependency. Edge computing integration reduces bandwidth requirements for real-time anomaly detection in pipeline monitoring.
- GPS:Satellite-dependent navigation remains baseline for agricultural and infrastructure missions where signal integrity permits. WAAS augmentation supports FAA Part 107 compliance in remote deployment corridors.
- LiDAR:Point-cloud generation supports precision mapping for construction progress monitoring and volumetric surveying. Integration costs limit adoption to high-value infrastructure inspection contracts.
- Communication Protocols:Mesh networking and cellular backhaul enable beyond-visual-line-of-sight command links. EASA standard scenario frameworks mandate specific redundancy levels for autonomous operation authorizations.
Computer Vision commands premium pricing. Communication Protocols face standardization pressure from pending detect-and-avoid performance mandates.
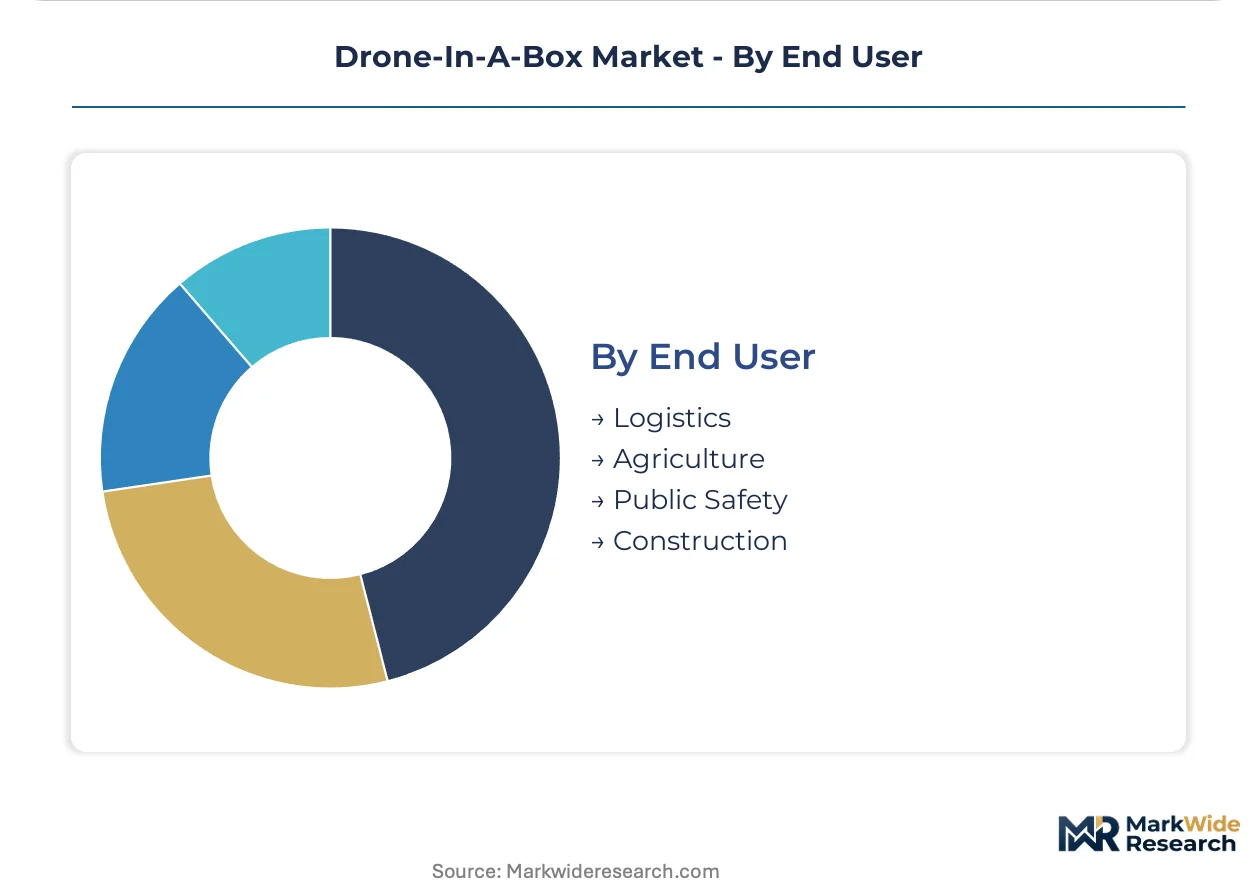
End User:
Customer sophistication and integration depth separate turnkey adopters from operators requiring custom middleware development for legacy SCADA connectivity.
- Logistics:E-commerce fulfillment networks and pharmaceutical distributors pilot automated docking networks in metropolitan corridors. Procurement favors availability-based contracts with flight-hour guarantees.
- Public Safety:Search-and-rescue and emergency response agencies prioritize rapid deployment autonomy. Skydio's computer vision platforms dominate North American procurement through hardened reliability credentials.
- Agriculture:Large-scale operators integrate seasonal monitoring with precision agriculture platforms. EU Green Deal compliance verification drives European procurement concentration.
- Construction:Progress monitoring and site security applications require BIM-compatible data formats. Custom middleware development connects drone streams with existing asset management platforms.
Logistics operators deploy the most experimental configurations. Agriculture delivers the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The drone-in-a-box industry traces its commercial origins to Israeli defense autonomy research, which migrated to North American energy infrastructure and European industrial compliance markets through successive regulatory adaptations.
United States
Texas pipeline operators deploy autonomous fleets for continuous leak detection across Permian Basin corridors. FAA Part 107 waiver streamlining accelerates beyond-visual-line-of-sight approvals for linear infrastructure inspection. Houston and Midland anchor concentrated procurement networks where energy infrastructure density creates deployment economies.
Germany
Industrial facility operators procure autonomous aerial systems for emissions verification under EU Green Deal mandates. EASA's specific category framework for autonomous operations simplifies type certification for compliant vendors. The Ruhr industrial cluster and Bavarian manufacturing zones drive standardization-focused procurement.
China
MIIT standards for unmanned aerial vehicle docking systems accelerate domestic platform certification for industrial surveillance. Dual carbon goals for emissions monitoring expand compliance-driven procurement across petrochemical facilities. Yangtze River Delta manufacturing hubs concentrate battery swap mechanism production.
United Arab Emirates
NEOM and Dubai smart city initiatives pilot automated docking networks for security and logistics applications. The country's civil aviation regulator advances risk-based approval frameworks for dense urban airspace integration. Abu Dhabi oil infrastructure operators test autonomous inspection platforms for offshore facility monitoring.
Australia
Mining operators in Western Australia deploy hardened docking stations for remote site surveillance and asset inspection. The country's civil aviation safety authority implements performance-based standards for beyond-visual-line-of-sight operations. Pilbara iron ore corridors concentrate early adoption of hybrid drone endurance platforms.
Drone-In-A-Box Market Competitive Landscape
Premium-margin players sit above commodity-margin players across autonomy sophistication and certification breadth. The vendor base stratifies between computer vision-native autonomy providers and hardware-centric system integrators. Three archetypes dominate: defense-hardened platform specialists, AI-native software autonomy providers, and industrial inspection turnkey operators. Competitive moves center on EASA-FAA dual certification investments and availability-based service contract structures displacing capital sales.
Within the computer vision autonomy tier, Skydio exemplifies North American public safety positioning through onboard navigation independence. Percepto occupies a position among industrial inspection specialists leveraging AI-powered analytics platforms for remote infrastructure monitoring. AeroVironment anchors defense-sector relationships with portable, hardened system architectures. These three represent distinct strategic postures: software-centric autonomy, integrated analytics platforms, and ruggedized military-grade hardware.
| Leading Market Players |
|---|
| Asylon |
| Skyfish |
| Percepto |
| Brinc |
| Draganfly |
| Skydio |
| Easy Aerial |
| AeroVironment |
| Azur Drones |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility cascades through drone-in-a-box manufacturing tiers, compressing margins on battery swap mechanisms while amplifying cost premiums for EASA-certified hybrid platforms with extended endurance specifications.
Pricing Analysis
Availability-based service contracts with flight-hour guarantees displace capital sales across industrial inspection verticals. Pricing stratifies across premium certified tiers, mid-market configurable platforms, and economy fixed-configuration units, with FAA-EASA dual certification commanding substantial premiums. Cost compression in the mid-tier intensifies as Chinese MIIT-certified platforms enter European energy procurement channels. Agricultural operators exhibit highest price sensitivity due to seasonal utilization constraints, whereas oil and gas pipeline operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cells force docking station manufacturers to qualify suppliers across China, South Korea, and Japan simultaneously. The supply chain draws from East Asian battery production hubs, Taiwanese semiconductor foundries for edge computing nodes, and German precision engineering for automated swap mechanisms. Single-source vulnerability concentrates in high-density energy cell formats. Distribution runs through direct manufacturer relationships with energy infrastructure operators and system integrator channels for public safety deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drone-in-a-box market compounds steadily as regulatory clarity around beyond-visual-line-of-sight operations unlocks deployment scale across linear infrastructure corridors.
For Market Incumbents: Lock in EASA-FAA dual certification breadth to defend against emerging Chinese MIIT-certified entrants targeting European energy procurement. Prioritize backward integration into battery swap mechanism production to reduce East Asian cell supply exposure. Deepen direct service relationships with Texas pipeline operators to secure multi-year availability contracts before competitive pressure intensifies. For New Entrants and Emerging Players: Industrial inspection software integrators represent the most penetrable channel partner type for computer vision autonomy specialists seeking infrastructure market entry. Target Australian mining operators in Western Australia where performance-based regulatory frameworks favor new platform qualification. Pursue agricultural monitoring in the European Union where EU Green Deal compliance verification mandates create procurement urgency with lower certification barriers than dense urban airspace. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native analytics platforms possessing EASA specific category certification pathways and established data integration with legacy SCADA systems. The five-to-ten year viability window favors vendors with demonstrated flight-hour guarantees in energy infrastructure rather than experimental urban delivery pilots. Watch FAA detect-and-avoid performance standard finalization as the inflection signal for platform qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA-FAA Dual Certification Investment | Unlocks transatlantic procurement contracts with oil and gas operators in Texas and emissions-mandated facilities in Germany. |
| Edge Computing Node Integration | Enables real-time anomaly detection for pipeline operators while reducing bandwidth dependency in remote deployment corridors. |
| Availability-Based Service Contract Structure | Displaces capital sales with recurring revenue streams tied to flight-hour guarantees in agricultural monitoring. |
| Hybrid Drone Endurance Platform Development | Captures thirty-plus-minute linear infrastructure survey demand from power line and pipeline operators. |
| Legacy SCADA Middleware Partnership | Resolves integration complexity blocking construction and industrial facility operator adoption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with FAA Part 107 waiver holders, EASA certification specialists, energy infrastructure procurement directors, and docking station engineering leads with secondary validation against FAA regulatory filings, EASA standard scenario documentation, MIIT certification databases, and customs trade data for lithium-ion cell imports. Bottom-up platform deployment estimates triangulated against top-down energy operator capital expenditure disclosures.
Historical reference periods anchored the forecast window to established beyond-visual-line-of-sight waiver approval timelines and EU Green Deal implementation phases. The analytical framework modeled platform architecture, use case vertical, autonomy technology stack, and end-user sophistication across the projection horizon. CAGRs derived from segment-level deployment trajectories and pricing evolution patterns, with specific inputs including EASA certification queue lengths and Texas pipeline corridor infrastructure investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to detect-and-avoid performance standard finalization and lithium supply chain disruption. Deviation in FAA-EASA regulatory harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Autonomous Aircraft Cameras Market
UAV
Micro Drone Market
UAV
Aerial Smart Weapons Market
UAV
Solar-Powered UAV Market
UAV
Enterprise Drone Management Solutions Market
UAV
Small UAV Market
UAV
Drone Data Management Market
UAV
GCC Drone Pilot Training Market
UAV
Anti-Drone Technology Market
UAV
Drone Inspection Service Market
UAV
UAV Simulator Software Market
UAV
Asia-Pacific Drone Motor Market
UAV
Europe Drones Market
UAV
Commercial Drone-Enabled Services Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Europe Drone Light Shows Market