
 Firefighting Drone Market | 2026-2036
Firefighting Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighting Drone Market Analysis
The gap between premium thermal-equipped units and basic visual-reconnaissance models is hardening as fire departments face budget constraints and capability requirements simultaneously. Skydio leverages autonomous navigation software to sustain leadership in confined-space urban deployments. Elistair anchors its position through tethered power systems that enable persistent aerial overwatch during extended structure fires. Draganfly differentiates via integrated payload platforms designed for hazardous material detection.
Firefighting drones are unmanned aerial vehicles engineered with heat-resistant composites, infrared sensors, and payload delivery mechanisms exceeding ten kilograms, purpose-built to access thermally compromised zones where human entry risks exceed operational thresholds. Multirotor configurations dominate municipal procurement due to vertical takeoff requirements amid dense urban infrastructure, while fixed-wing platforms serve wildfire perimeter mapping across extended operational ranges. Thermal imaging technology commands the steepest premium within the technology stack, as gas detection modules remain nascent outside industrial facility contracts.
The FAA governs commercial and public safety drone operations through Part 107 and specific public aircraft certificates, while the EPA influences payload chemistry standards for aerial fire suppression agents. NFPA standards increasingly incorporate UAV protocols into fire service operational guidelines, shaping departmental procurement specifications and training mandates. Stakeholders must monitor evolving liability frameworks around autonomous decision-making in active fire zones, as regulatory clarity will determine insurance costs and deployment authorizations.
Market Dynamics
The FAA's Part 107 waiver expansions for beyond-visual-line-of-sight operations are compressing deployment timelines for municipal fire departments, while thermal sensor cost curves and battery energy density improvements simultaneously reshape procurement specifications across urban and wildfire applications.
Growth Catalysts
- Extended wildfire seasons:California fire departments strain traditional aerial suppression resources, accelerating UAV fleet procurement for perimeter mapping and hotspot detection.
- Battery energy density gains:Lithium-sulfur cell commercialization extends flight endurance for multirotor platforms, enabling sustained structure fire overwatch without tethered power systems.
- NFPA 2400 integration:The National Fire Protection Association's small unmanned aircraft systems standard provides operational protocols that reduce departmental liability concerns and training standardization costs.
Market Restraints
- Thermal sensor import concentration:German and French infrared component suppliers dominate cooled detector supply, creating single-source vulnerability for North American drone assemblers.
- Payload weight-versus-endurance tradeoff:Ten-kilogram suppression tank capacity cuts flight time below operational thresholds for multirotor configurations in high-wind conditions.
- FAA certification bottlenecks:Type certification timelines for autonomous flight systems exceed eighteen months, delaying product launches for software-heavy navigation platforms.
Strategic Opportunities
- Hazmat response integration:Industrial facility fire contracts in Texas and Louisiana create demand for combined thermal-gas detection payloads that penetrate petrochemical infrastructure inspection.
- EU Green Deal procurement mandates:European municipal tenders increasingly require electric-powered aerial platforms, favoring battery-swappable drone architectures over combustion alternatives.
- AI-thermal fusion:Machine learning inference at the edge enables real-time hotspot classification without ground station latency, opening subscription-based software revenue streams for hardware manufacturers.
Industry Challenges
- Remote pilot certification throughput:FAA Part 107 examiner capacity constraints create six-month backlogs for fire department personnel qualification, delaying fleet operational readiness.
- Interoperability with legacy dispatch systems:CAD software protocols in older municipal IT architectures require middleware development for drone telemetry integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighting Drone Market |
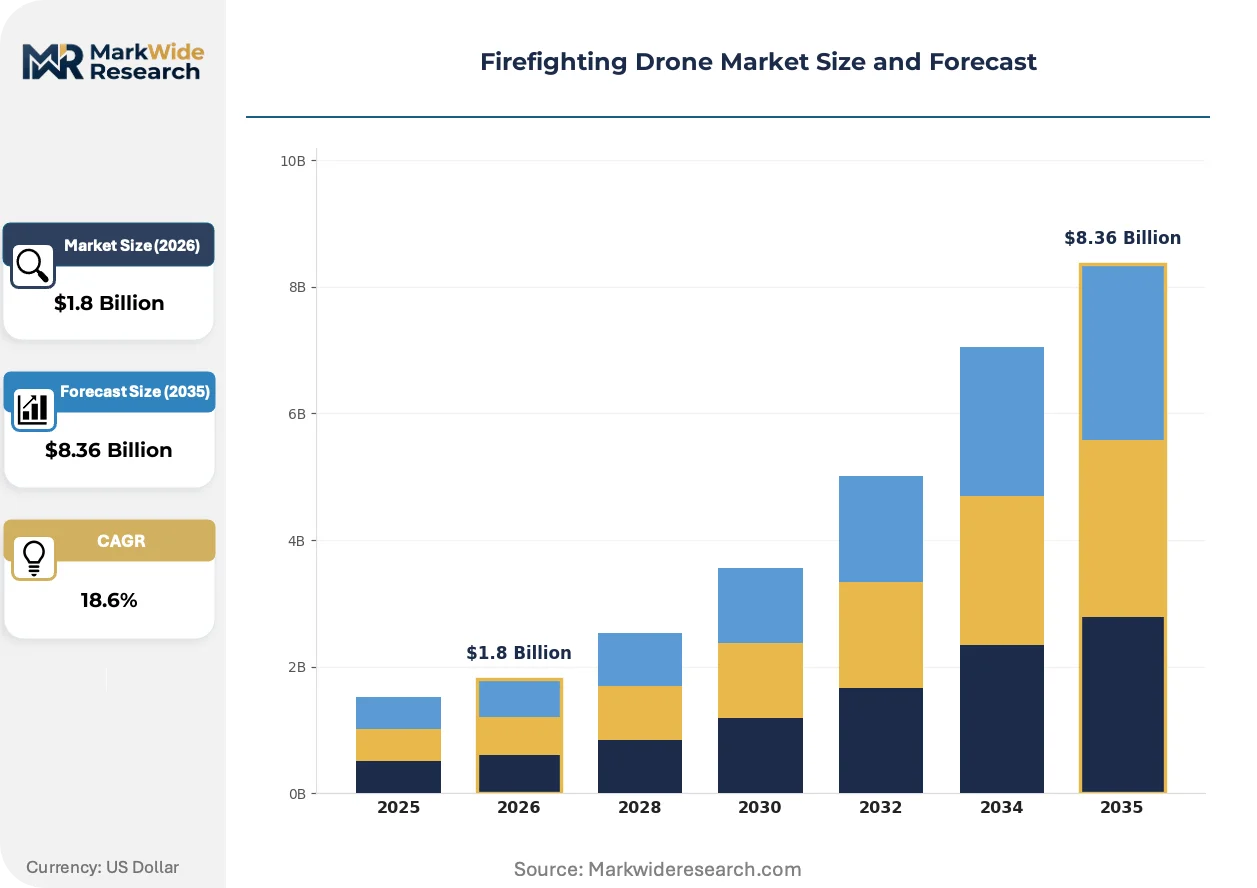
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-wing, Hybrid, Tethered Technology: Thermal Imaging, Gas Detection, GPS Navigation, Communication Systems End User: Fire Departments, Private Sector, Government Agencies, Search & Rescue Application: Fire Suppression, Aerial Surveillance, Search Operations, Damage Assessment |
| Companies Covered | Parrot, Elistair, Skydio, AUTEL Robotics, Fly4Future, AeroVironment, Drone Amplified, Draganfly, JOUAV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighting Drone Market Emerging Trajectories
Autonomous navigation software is absorbing capital allocation from hardware differentiation, while regulatory frameworks mature around liability allocation in active fire zones. These forces compress the competitive window for positioning around operational reliability rather than specification superiority.
Carbon fiber-aramid hybrid airframes are absorbing thermal shock loads that previously grounded missions above 120 degrees Celsius. Urban fire departments in Japan and South Korea adopt these materials for high-rise reconnaissance deployments where elevator shaft heat stratification exceeds conventional polymer limits. The structural consequence is absorbing premium pricing power from sensor suppliers into airframe manufacturers capable of certified heat-resistant construction.
REACH chemical registration requirements for aerial suppression foams are forcing reformulation of long-chain fluorocarbon agents across European procurement contracts. The EPA's parallel scrutiny of per- and polyfluoroalkyl substances in the United States creates regulatory alignment pressure on multinational chemical suppliers. Wildfire suppression service providers in Mediterranean Europe and the western United States face simultaneous compliance deadlines that compress supplier qualification timelines.
California municipal procurement offices now bundle drone services into multi-year fleet management contracts rather than capital equipment purchases. This displaces spot-buying of individual aircraft and shifts vendor relationships toward uptime-guarantee structures with penalty clauses for operational unavailability. The model concentrates vendor selection authority within state-level cooperative purchasing agreements, reducing individual department procurement autonomy.
Firefighting Drone Market Segmentation
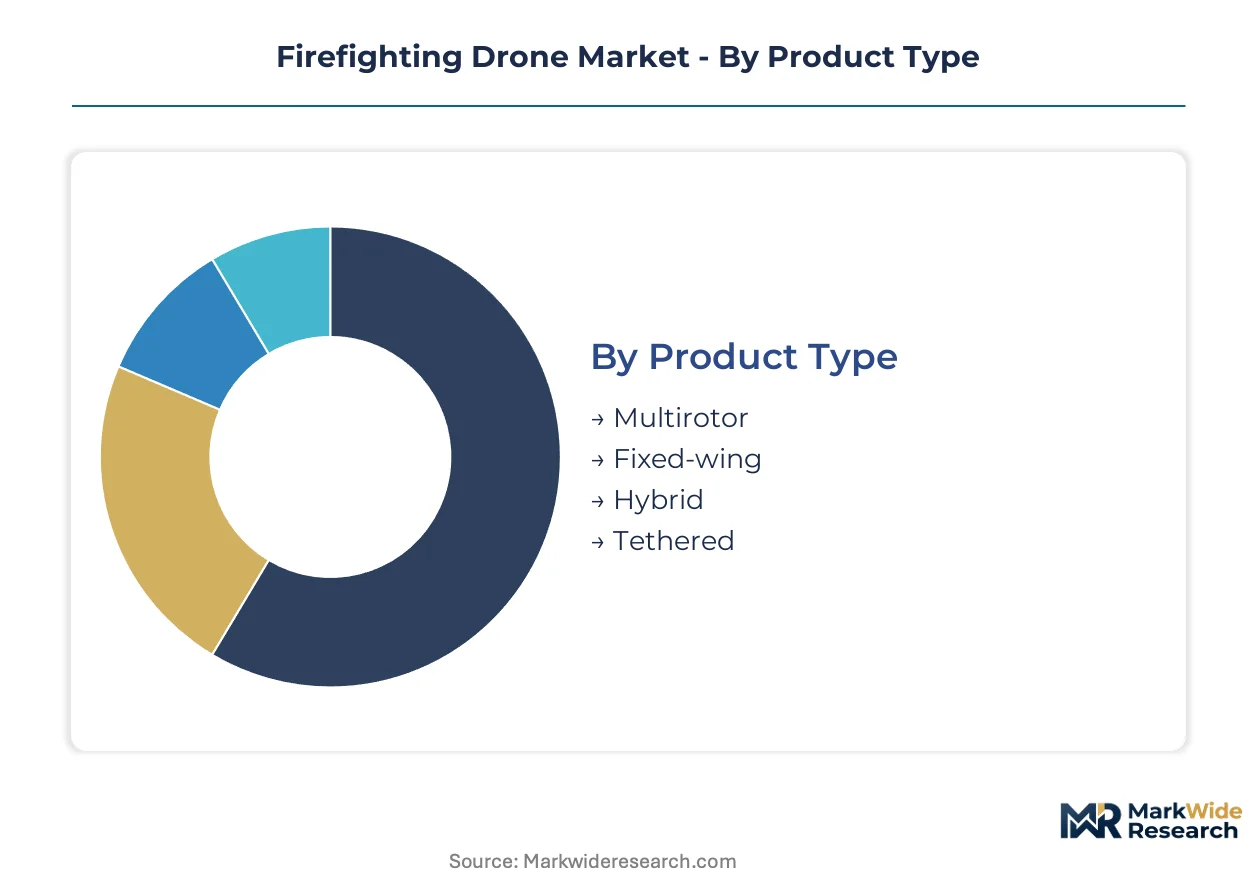
Firefighting drone procurement specifications diverge sharply between standalone aerial platforms and integrated fleet systems, with procurement officers weighing unit autonomy against command-and-control interoperability. Segment boundaries increasingly blur as multirotor units adopt tethered power modules and thermal sensors merge with gas detection arrays.
Product Type:
Integration depth varies from fully autonomous battery-powered units requiring no ground infrastructure to persistent systems demanding continuous tether connection and vehicle-mounted power supply.
- Multirotor:Vertical takeoff capability suits dense urban environments where helipad access is constrained. Fire departments in California and Texas concentrate procurement here for high-rise reconnaissance missions where maneuverability outweighs endurance requirements.
- Fixed-wing:Extended range and loiter time dominate wildfire perimeter mapping across operational theaters exceeding fifty kilometers. These platforms sacrifice hovering precision for fuel efficiency, with procurement concentrated in Mediterranean Europe and the western United States where fire front tracking demands sustained aerial presence.
- Hybrid:Combines multirotor agility with fixed-wing endurance through tilt-rotor or tail-sitter configurations. Japan's Tokyo Fire Department evaluates these for combined urban-rural deployment zones.
- Tethered:Persistent power supply enables unlimited flight duration for structure fire overwatch, with Elistair's power management systems anchoring municipal adoption in France and Germany.
Multirotor configurations lead volumes today; tethered systems are gaining share fastest in urban municipal procurement.
Technology:
Cost tier stratification separates premium sensor suites from baseline navigation packages, with thermal imaging commanding the steepest procurement premiums across all end-use categories.
- Thermal Imaging:Infrared sensors detect heat signatures through smoke obscuration, with cooled detector arrays from German and French suppliers dominating high-resolution applications. Fire departments in California and Australia prioritize these for hotspot detection in post-suppression smolder zones where visual reconnaissance fails.
- Gas Detection:Multi-sensor payloads identify hazardous atmospheric conditions including carbon monoxide, hydrogen cyanide, and volatile organic compounds. Industrial facility contracts in Texas and Louisiana drive adoption for petrochemical fire response where toxic plume mapping precedes human entry.
- GPS Navigation:RTK-GPS modules enable centimeter-level positioning for precision payload delivery in high-wind conditions.
- Communication Systems:Mesh networking and LTE-encrypted links maintain telemetry in RF-congested urban environments.
Thermal imaging leads volumes today; gas detection is expanding most quickly in industrial hazmat applications.
End User:
Customer type determines procurement autonomy, with municipal fire departments operating under public aircraft certificates while private contractors navigate Part 107 commercial frameworks.
- Fire Departments:Municipal agencies in the United States deploy UAV fleets under FAA public aircraft certificates with expanded beyond-visual-line-of-sight waivers. California departments strain traditional aerial suppression resources, accelerating fleet procurement for perimeter mapping.
- Private Sector:Industrial facility operators and insurance carriers contract aerial fire suppression services, with procurement concentrated in Texas petrochemical corridors and Louisiana refinery complexes.
- Government Agencies:Federal land management bodies coordinate wildfire response across multi-jurisdictional fire complexes.
- Search & Rescue:Mountain rescue services and maritime agencies adapt fire-rated thermal platforms for victim location in thermally challenging environments.
Fire departments lead volumes today; private sector contracts are climbing the fastest in industrial corridor deployment.
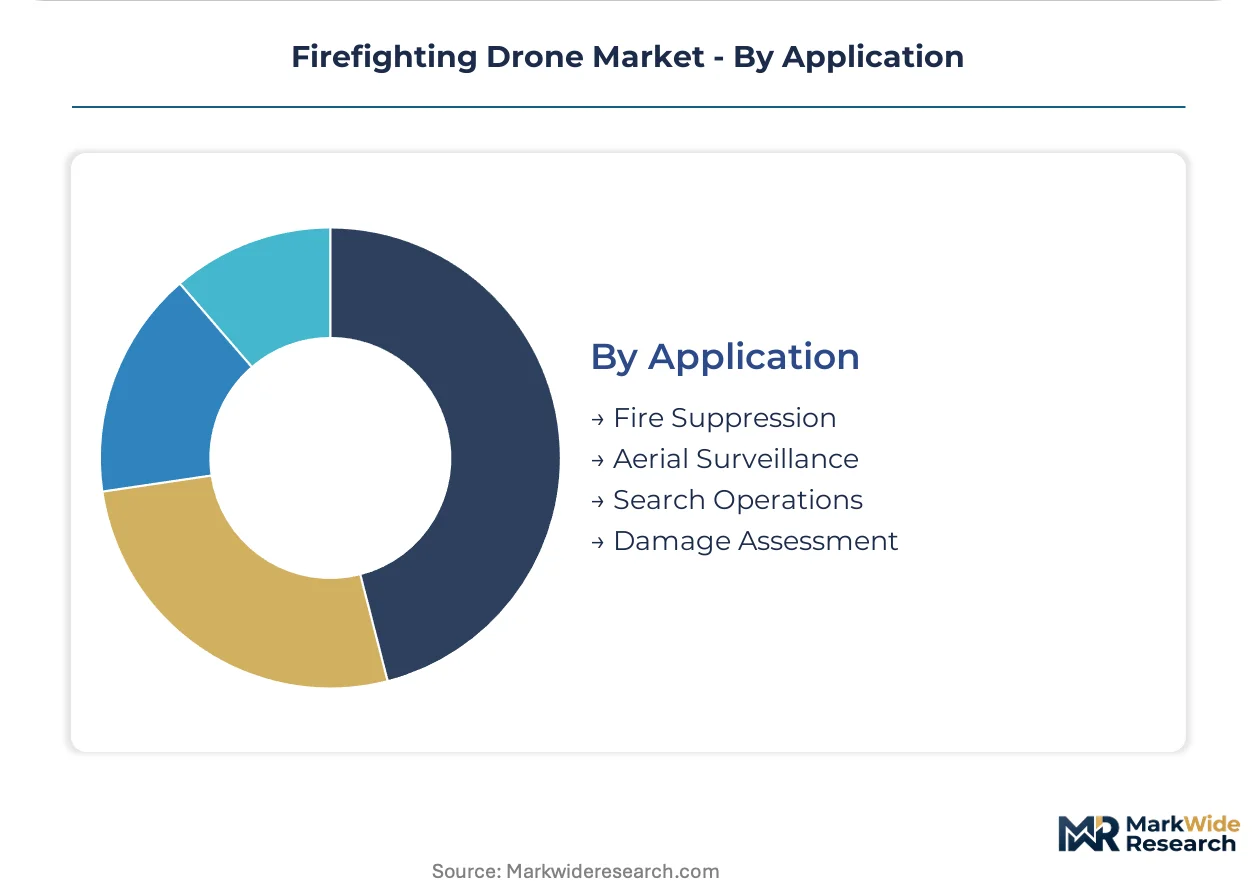
Application:
Maturity gradients separate established surveillance operations from emerging autonomous suppression missions where regulatory frameworks remain unsettled.
- Fire Suppression:Payload delivery systems deploy retardant, foam, or water charges in thermally compromised zones. Ten-kilogram tank capacity cuts flight endurance below operational thresholds in high-wind conditions, constraining adoption to low-altitude structure fire response.
- Aerial Surveillance:Real-time video feeds support incident command decision-making across wildfire perimeters and urban collapse zones. NFPA 2400 standardization reduces departmental liability concerns, accelerating procurement in the United States.
- Search Operations:Thermal-equipped units locate victims through smoke and debris obscuration.
- Damage Assessment:Post-incident documentation supports insurance claims and structural engineering evaluation.
Aerial surveillance leads volumes today; fire suppression shows the steepest expansion trajectory as payload-weight tradeoffs improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified drone pilot concentrations in California, Bavaria, and Tokyo anchor procurement expertise for thermal-equipped aerial platforms. Municipal fire departments in these clusters leverage established training infrastructure to accelerate fleet deployment timelines.
United States
Extended wildfire seasons in California strain traditional aerial suppression resources, accelerating UAV procurement for perimeter mapping and hotspot detection. The FAA's Part 107 waiver expansions for beyond-visual-line-of-sight operations remove operational barriers for public safety agencies. Los Angeles County Fire Department deploys tethered systems for high-rise structure fire overwatch.
Germany
Industrial facility fire contracts along the Rhine-Ruhr corridor drive demand for combined thermal-gas detection payloads. REACH chemical registration requirements for aerial suppression foams force reformulation of long-chain fluorocarbon agents across European procurement contracts. Bavarian municipal fire departments evaluate carbon fiber-aramid hybrid airframes for elevator shaft heat stratification missions.
France
Persistent aerial overwatch requirements during extended structure fires favor tethered power systems in dense urban environments. The EU Green Deal procurement mandates increasingly require electric-powered aerial platforms, favoring battery-swappable drone architectures. Paris Fire Brigade anchors adoption of unlimited-duration flight systems for metro tunnel fire response.
Japan
High-rise reconnaissance deployments in Tokyo demand heat-resistant composites exceeding 120 degrees Celsius operational thresholds. METI standards for autonomous navigation in confined spaces shape municipal procurement specifications. Tokyo Fire Department evaluates hybrid tilt-rotor configurations for combined urban-rural deployment zones.
Australia
Post-suppression smolder zone detection across Victoria's extended fire seasons prioritizes cooled thermal detector arrays. The country's national aviation regulator coordinates public safety certificate frameworks with state-level fire service authorities. Melbourne metropolitan fire districts concentrate procurement for wildfire perimeter mapping across operational theaters exceeding fifty kilometers.
Firefighting Drone Market Vendor Landscape
Top-tier vendors anchor premium thermal-equipped segments, while mid-tier assemblers compete on payload modularity and regional service networks. The vendor base stratifies across three functional tiers: autonomous navigation specialists, tethered power system providers, and integrated payload platform builders. Dominant competitive moves include strategic partnerships with municipal cooperative purchasing agreements and technology licensing for NFPA 2400-compliant operational protocols.
Within the tethered power archetype, Elistair anchors persistent aerial overwatch capabilities for European municipal adoption. Skydio occupies a position exemplifying autonomous navigation software leadership in confined-space urban deployments. Draganfly represents the integrated payload platform segment, with hazardous material detection capabilities penetrating industrial facility contracts.
| Leading Market Players |
|---|
| Parrot |
| Elistair |
| Skydio |
| AUTEL Robotics |
| Fly4Future |
| AeroVironment |
| Drone Amplified |
| Draganfly |
| JOUAV |
| Others |
Supply Flow & Price Mechanics
Lithium-sulfur cell commercialization simultaneously compresses battery cost curves and redraws supplier maps, shifting procurement power from German and French infrared detector houses toward East Asian cell manufacturers and carbon fiber-aramid composite specialists.
Pricing Analysis
Bundled fleet-management contracts with uptime guarantees now displace unit-transactional sales across California municipal procurement, compressing spot-buying premiums. Three-tier pricing structure across premium thermal-equipped, standard visual-reconnaissance, and economy tethered-power configurations separates cooled-detector arrays from uncooled alternatives. Cost compression in the standard tier intensifies as battery energy density gains reduce tethered-power premiums. Private sector industrial contracts in Texas and Louisiana show least price sensitivity due to hazmat liability exposure.
Supply Chain Analysis
Dual-sourcing mandates from municipal procurement offices in California and Texas now require qualified secondary suppliers for cooled infrared detectors and lithium-sulfur cells. Manufacturing concentrates in Germany and France for thermal sensors, South Korea and Japan for advanced battery cells, and China for carbon fiber-aramid composites. Single-source vulnerability in cooled detector supply creates procurement risk for North American assemblers. Distribution runs through state-level cooperative purchasing agreements that concentrate vendor selection authority away from individual departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in persistent aerial overwatch systems, where tethered-power architectures capture premium pricing as battery chemistry improvements compress operating costs for fleet operators.
For Market Incumbents: Acquire autonomous navigation software assets to defend against Skydio's confined-space positioning. Secure FAA Part 107 examiner partnerships to accelerate fire department pilot certification throughput and lock in fleet management contract renewals. Backward integration into carbon fiber-aramid composite manufacturing insulates against heat-resistant airframe supply constraints. For New Entrants and Emerging Players: FAA Part 107 waiver expansions in the United States open a window for beyond-visual-line-of-sight service providers to penetrate California municipal procurement. Target industrial hazmat response contracts in Texas and Louisiana where gas detection payload integration lags thermal imaging penetration. Lead with AI-thermal fusion software subscriptions to bypass hardware certification bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among tethered-power system specialists with established European municipal footprints and NFPA 2400 protocol compliance. Long-term viability hinges on regulatory clarity for autonomous decision-making liability in active fire zones. Watch FAA type certification timeline compression as the inflection signal for software-heavy navigation platform commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Thermal Fusion Platform Launch | Machine learning inference at the edge enables real-time hotspot classification without ground station latency. |
| Backward Integration into Battery Cells | In-house lithium-sulfur production secures supply for extended-duration multirotor platforms. |
| NFPA 2400 Certification Investment | Operational protocol compliance reduces municipal fire department liability concerns and training standardization costs. |
| Tethered Power System Partnership | Vehicle-mounted supply modules anchor persistent overwatch contracts in dense urban environments. |
| Industrial Hazmat Service Expansion | Combined thermal-gas detection payloads penetrate petrochemical infrastructure inspection contracts in Texas. |
Methodological Framework
Bottom-up municipal fire department procurement modeling reconciled against top-down thermal sensor and battery cell supply tracking forms the analytical core. Primary interviews with fire chiefs, FAA Part 107 examiners, municipal procurement officers, and tethered power system engineers combined with secondary validation from FAA waiver filings, NFPA standard documentation, and EPA aerial suppression agent registrations. Triangulation across these sources anchors volume and value estimates.
Historical procurement trendline analysis identified inflection points in fleet-management contract adoption and lithium-sulfur cell commercialization timelines. Segmentation modeling spanned product type, technology tier, end-user category, and application maturity across the projection horizon. CAGRs derived from unit shipment trajectories and average selling price evolution, with specific inputs from battery energy density improvement curves and thermal sensor cost reduction patterns.
Revisions become necessary when FAA autonomous flight system certification timelines extend beyond current eighteen-month baselines or when REACH chemical registration requirements force additional aerial suppression foam reformulation. Deviation in municipal cooperative purchasing agreement concentration would shift vendor selection dynamics and pricing power materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Drone Software Market
UAV
Europe Commercial Drones Market
UAV
Global Drone Light Shows Market
UAV
Drone Motors Market
UAV
Small UAV Market
UAV
UAV Simulator Market
UAV
Europe Drone Light Shows Market
UAV
Global Drone Autopilots Market
UAV
Airborne Digital Battlefield Market
UAV
Anti-Drone Market
UAV
Small Drone Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Solar-Powered UAV Market
UAV
Middle-East and Africa Drones Market
UAV
Utility Drone Market
UAV
Delivery Drones Market