
 Folate Market | 2026-2036
Folate Market Size, Share, and Industry Trends Forecast 2026-2036
Folate Market Intelligence
The divergence in manufacturing scale between large-scale chemical synthesis and specialized bioproduction is reorganizing the competitive landscape. Global chemical giant BASF SE leverages its vast production infrastructure to serve high-volume segments efficiently. In contrast, DSM Nutritional Products differentiates through its research and development investment in advanced, bioactive forms like 5-methyltetrahydrofolate. Meanwhile, Jiangxi Tianxin Pharmaceutical Co., Ltd. competes on production efficiency and immense scale within the core folic acid category.
Folate is a water-soluble B vitamin, with folic acid representing the stable, synthetic form widely used in food fortification and dietary supplements. Its fundamental biological role involves coenzyme activity in single-carbon transfers, which is crucial for cellular processes like DNA synthesis and repair. The food fortification application relies heavily on cost-effective folic acid, establishing it as the market's volume leader. Conversely, the dietary supplements application shows rapid uptake of higher-value 5-methyltetrahydrofolate due to its perceived superior bioavailability and direct metabolic utility.
Regulatory frameworks from bodies like the US FDA and the European Food Safety Authority (EFSA) mandate fortification levels and define acceptable health claims. In China, standards set by the NMPA and SAMR govern the use of folate in infant formula and health foods, creating specific market access requirements. Navigating the divergent global standards for novel folate forms versus traditional folic acid is a critical strategic decision for manufacturers.
Market Dynamics
The folate market's core dynamic is the pronounced segmentation between high-volume, cost-driven folic acid for food fortification and high-value, bioactive forms for premium supplements. This bifurcation shapes manufacturing scale, R&D priorities, and regulatory navigation for all participants.
Growth Catalysts
- Mandatory Food Fortification:National policies requiring folic acid addition to staple foods, such as flour and cereals under FSSAI guidelines in India and FDA mandates in the US, create a large, stable demand base for the synthetic form.
- Prenatal Health Focus:Heightened consumer and clinical emphasis on preventing neural tube defects drives consistent demand for folate in prenatal dietary supplements, particularly for advanced forms with perceived higher bioavailability.
- Geriatric Nutrition:Expanding elderly populations in developed nations like Japan and Germany support the inclusion of folate in nutritional products aimed at cognitive function, cardiovascular health, and managing homocysteine levels.
Market Restraints
- Regulatory Path Divergence:Navigating disparate and often lengthy approval processes for novel folate forms, as opposed to the well-established framework for folic acid, creates significant market entry barriers, with bodies like EFSA and the FDA having distinct data requirements.
- Input Cost Volatility:The production economics of synthetic folic acid are closely tied to the price of specific chemical precursors, exposing manufacturers to margin pressure from fluctuations in the petrochemical supply chain.
- Bioavailability Education Gap:Communicating the metabolic advantages of premium 5-methyltetrahydrofolate (5-MTHF) over standard folic acid to mass-market consumers remains a significant hurdle, limiting its adoption to well-informed or niche segments.
Strategic Opportunities
- Personalized Nutrition Services:The emergence of direct-to-consumer platforms that offer customized vitamin regimens based on genetic testing or lifestyle questionnaires presents an opportunity for incorporating specific folate forms tailored to individual metabolic needs.
- Functional Food and Beverage Fortification:There is a growing opportunity to incorporate stabilized, bioactive folates into value-added products like functional beverages, yogurts, and plant-based milks, moving beyond mandated staple food fortification.
- Animal Nutrition Enhancement:The application of folate in specialized animal feed formulations, particularly for improving the reproductive performance and health of breeding livestock in the poultry and swine industries, represents an underpenetrated market.
Industry Challenges
- Clinical Data Substantiation:Generating the robust clinical evidence required by regulators like the US FTC and European EFSA to support health and bioavailability claims for next-generation folates is a costly and time-consuming operational challenge.
- Supply Chain Traceability:Implementing and maintaining verifiable traceability systems to guarantee the purity and origin of folate, a critical requirement for sensitive applications like infant formula governed by China's SAMR, adds significant operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folate Market |
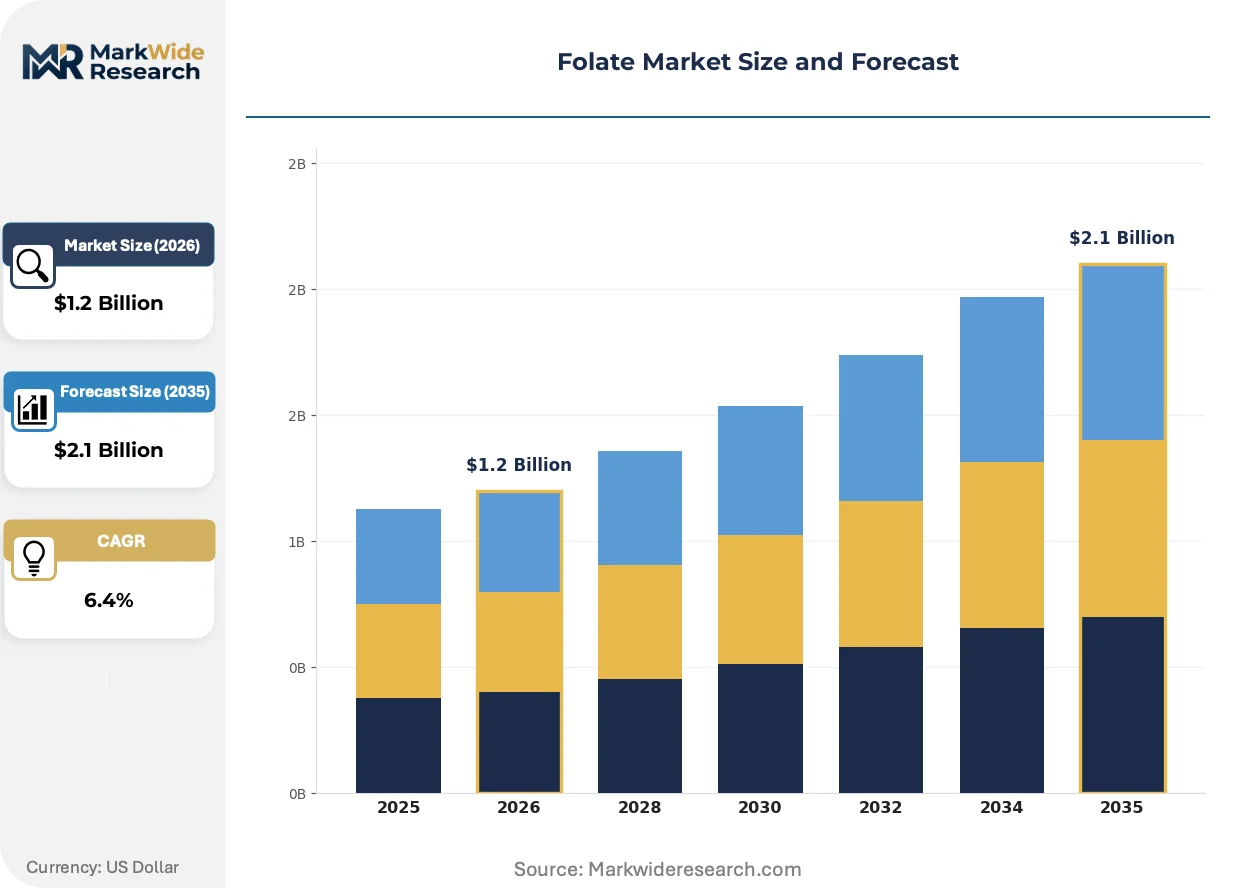
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folic Acid, 5-Methyltetrahydrofolate, Folinic Acid, L-Methylfolate Application: Dietary Supplements, Food Fortification, Pharmaceuticals, Animal Nutrition, Cosmetics End User: Supplement Manufacturers, Food & Beverage Producers, Pharmaceutical Firms, Animal Feed Companies Distribution Channel: Pharmacies, Online Retailers, Health Stores, Supermarkets, Direct Sales |
| Companies Covered | Jiangxi Tianxin Pharmaceutical Co., Ltd., Niutang Chemical, BASF SE, Lesaffre, Jiheng Pharmaceutical Co., Ltd., DSM Nutritional Products, Zydus Lifesciences Limited, Emcure Pharmaceuticals Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folate Market Strategic Shifts & Innovations
The market is being redefined by a scientific push toward ingredients with superior metabolic activity and precision delivery systems. This evolution favors differentiated products over commodity-grade folic acid, particularly within the high-margin dietary supplement and functional food sectors.
Microencapsulation is a critical technology used to shield sensitive folate compounds from degradation due to heat, light, or pH changes during food processing. The infant formula and functional food industries are primary adopters of these advanced delivery systems. This technological progress is miniaturizing the protective coating on each active particle, which improves dispersion in final products and ensures targeted release within the body.
Health authorities worldwide, including Health Canada and regulators in South America, are progressively expanding mandatory fortification programs. These policies now often include additional food vehicles like maize flour and rice, broadening the base for folic acid consumption. This regulatory expansion compels investment in blending and quality control infrastructure among food processors in affected regions, solidifying demand for commodity-grade folic acid.
A significant shift in consumer purchasing criteria toward "clean label" and non-GMO ingredients is influencing product formulation in the premium supplement space. This behavioral change challenges the dominance of synthetically produced folic acid, creating a clear preference for bio-identical forms like 5-MTHF or naturally sourced folates. The trend is most pronounced in the North American and Western European markets, where it serves as a key brand differentiator.
Folate Market Segmentation
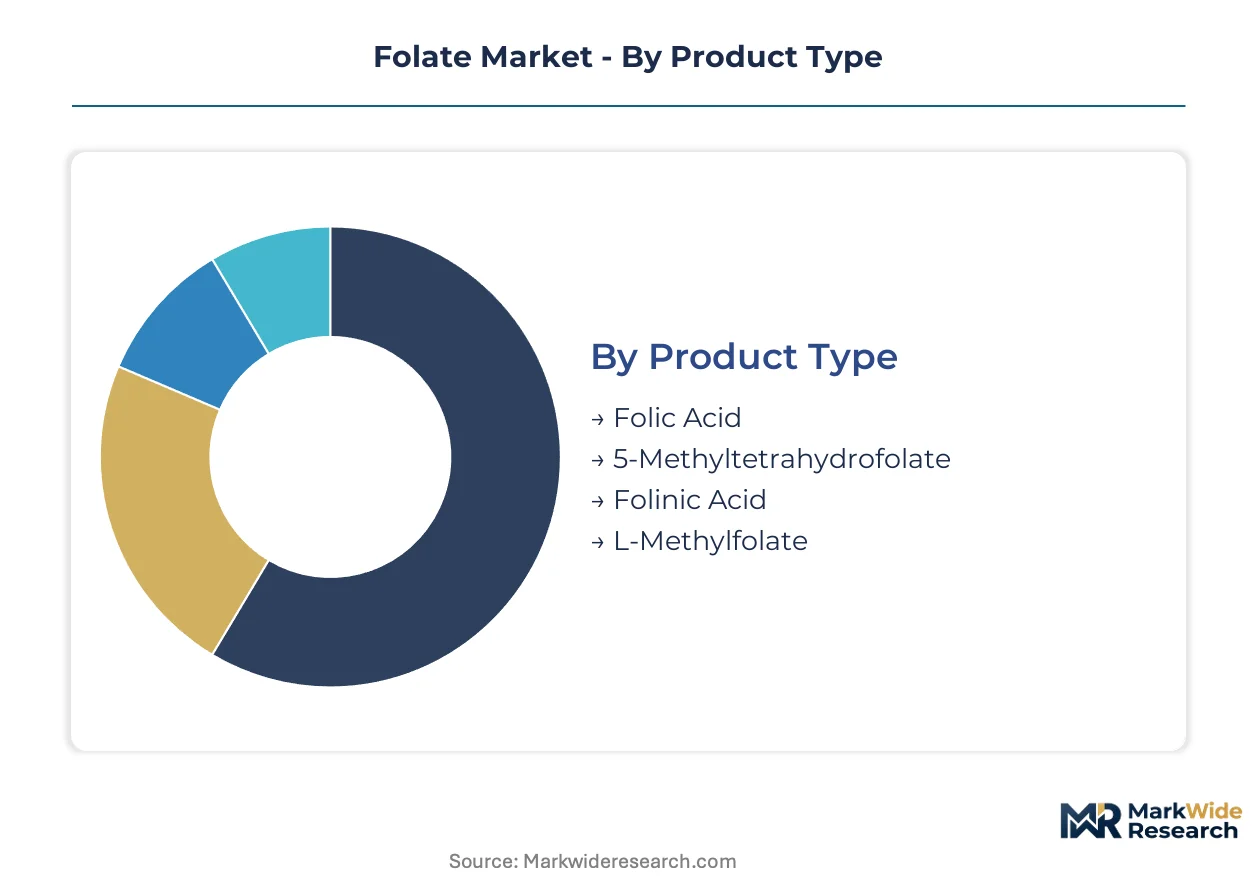
The folate market's segmentation reveals the diverse needs and strategic priorities across its value chain, from raw material production to end-use applications. Understanding these distinct segments is crucial for manufacturers to tailor product offerings and navigate regulatory complexities effectively.
Product Type:
The folate market's product segmentation highlights varying degrees of substitution pressure, particularly as advanced forms challenge the long-standing dominance of synthetic folic acid.
- Folic Acid:This stable, synthetic form of vitamin B9 is widely used for food fortification due to its cost-effectiveness and stability. Demand concentrates in national public health initiatives requiring staple food enrichment, particularly in countries like India and the US.
- 5-Methyltetrahydrofolate:The metabolically active, bioactive form of folate, offering superior bioavailability compared to synthetic folic acid. Its demand is strongest in premium dietary supplements for prenatal health and personalized nutrition, especially in North American and Western European markets.
- Folinic Acid:A reduced folate form, primarily utilized in specific pharmaceutical applications and medical treatments.
- L-Methylfolate:Another metabolically active folate form, often found in specialized dietary supplements targeting individuals with specific genetic variations.
Folic Acid anchors the volume base while 5-Methyltetrahydrofolate gains share at the steepest rate.
Application:
Application segments differentiate the folate market by cost-effectiveness and value proposition, reflecting distinct requirements for bulk commodity versus specialized ingredient use.
- Food Fortification:Involves adding folic acid to staple foods like flour and cereals to address public health deficiencies, driven by mandatory regulations. This application represents the largest volume segment, with significant demand from national programs in China and India.
- Dietary Supplements:Focuses on providing concentrated folate forms, including 5-methyltetrahydrofolate, for individual health needs, particularly prenatal and geriatric nutrition. Growth in this segment is driven by consumer awareness of bioavailability and personalized health trends in markets like Germany and Japan.
- Pharmaceuticals:Utilizes folate in specific drug formulations and medical therapies for targeted health conditions.
- Animal Nutrition:Incorporates folate into specialized animal feed to enhance livestock health and reproductive performance, particularly in poultry and swine industries.
- Cosmetics:A niche application where folate is explored for its potential skin health benefits in topical formulations.
Food Fortification drives the largest volume demand, while Dietary Supplements show the steepest expansion trajectory.
End User:
End user segmentation highlights the varied procurement scales and technical requirements across different industrial buyers within the folate market.
- Food & Beverage Producers:These entities integrate folic acid into staple food products under fortification mandates, requiring large volumes of cost-effective, stable ingredients. Their demand is heavily influenced by regulatory compliance and public health policies in various countries.
- Supplement Manufacturers:These companies formulate a wide range of dietary supplements, often favoring advanced folate forms like 5-methyltetrahydrofolate for enhanced bioavailability. Their purchasing decisions are guided by consumer preferences for "clean label" products and clinical efficacy in markets like the US.
- Pharmaceutical Firms:Procure high-purity folate derivatives for use in prescription medications and specialized medical nutrition products.
- Animal Feed Companies:Source folate ingredients for inclusion in livestock and aquaculture feed formulations to support animal growth and health.
Food & Beverage Producers represent the largest purchasing volume, with Supplement Manufacturers driving innovation in product variety.
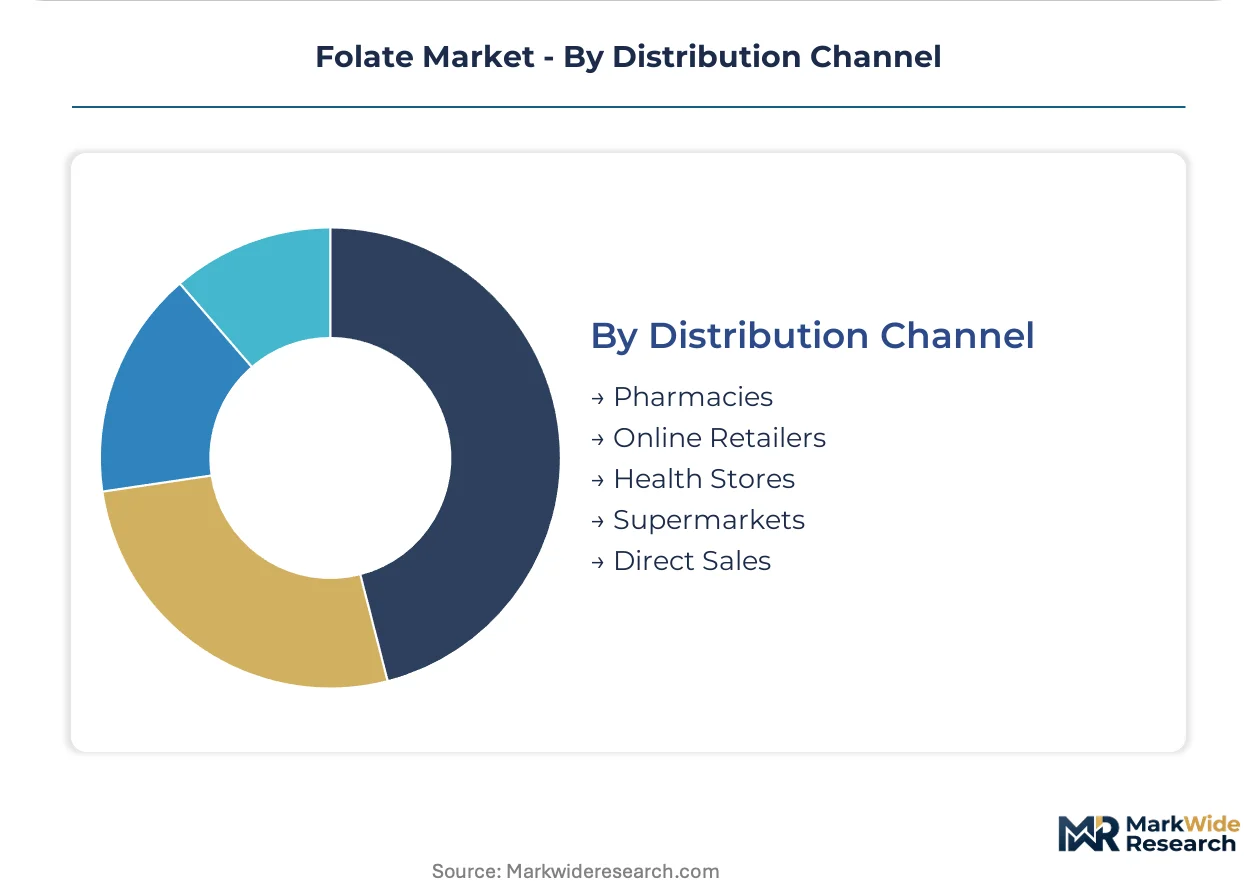
Distribution Channel:
Distribution channel analysis reveals how different customer types access folate products, ranging from direct industrial procurement to consumer-facing retail models.
- Direct Sales:This channel primarily serves industrial clients such as food and beverage producers, pharmaceutical firms, and animal feed companies, involving bulk purchases and direct contractual relationships. It ensures efficient supply chain management for high-volume, commodity-grade folate ingredients.
- Online Retailers:Provides a platform for consumers to purchase a wide array of folate supplements, including premium bioactive forms, often leveraging direct-to-consumer models. This channel benefits from personalized nutrition trends and broad geographic reach, particularly for differentiated products in developed markets.
- Pharmacies:Offer over-the-counter folate supplements and prescription-based folate products, serving consumers seeking health advice.
- Supermarkets:Stock fortified food products and a selection of basic folate supplements, catering to general consumer convenience.
- Health Stores:Specialize in natural and organic health products, providing a retail point for premium and "clean label" folate supplements.
Direct Sales facilitates the largest volume transactions, while Online Retailers are expanding consumer access most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global folate market exhibits distinct consumption patterns across geographies, with some regions prioritizing public health fortification while others focus on premium supplement forms. China and India lead in high-volume folic acid demand due to national policies. Developed markets like the United States and Germany show stronger preferences for advanced, bioactive folate forms.
China
Demand for folic acid is substantial, driven by extensive food fortification programs and a large consumer base. The NMPA and SAMR govern folate use, especially in infant formula, ensuring strict quality standards. Major pharmaceutical and food ingredient manufacturers in the Yangtze River Delta concentrate on large-scale production.
India
Folic acid consumption is high due to national public health initiatives targeting nutritional deficiencies. FSSAI guidelines mandate fortification of staple foods like flour and rice, creating a stable market base. Manufacturers in Gujarat and Maharashtra supply the vast domestic food processing industry.
United States
The market shows a strong bifurcation between mandatory food fortification and premium dietary supplements. The FDA mandates folic acid fortification in grain products, ensuring widespread public exposure. Supplement manufacturers in California and the Northeast focus on advanced 5-methyltetrahydrofolate forms.
Germany
Consumer preference for bioactive folate forms is pronounced, especially in the dietary supplements segment for prenatal and geriatric nutrition. EFSA regulations influence health claims and ingredient approvals for novel folate compounds. Specialized ingredient producers in Bavaria and North Rhine-Westphalia innovate in advanced folate manufacturing.
Japan
The market emphasizes high-value nutritional products and geriatric health applications, with a focus on cognitive and cardiovascular health. Japan's Ministry of Health, Labour and Welfare oversees dietary supplement regulations and functional food approvals. Research and development clusters in the Kanto region drive innovation in personalized nutrition ingredients.
Folate Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the folate market's competitive dynamics. This tiered structure reflects the dual nature of demand, encompassing both high-volume commodity folic acid for fortification and specialized bioactive forms for premium supplements. Strategic archetypes include global chemical giants leveraging vast infrastructure, specialized nutritional ingredient providers focused on R&D, and regional pharmaceutical manufacturers competing on efficiency. Capacity expansion, strategic partnerships, and targeted portfolio diversification remain dominant competitive moves across the industry.
Within the global chemical giant archetype, BASF SE exemplifies leveraging vast production infrastructure to efficiently serve high-volume segments, particularly for synthetic folic acid. DSM Nutritional Products occupies a position as a specialized nutritional ingredient provider, driving innovation and research in advanced, bioactive forms like 5-methyltetrahydrofolate. Jiangxi Tianxin Pharmaceutical Co., Ltd. sits within the regional pharmaceutical manufacturer archetype, competing effectively on production efficiency and immense scale within the core folic acid category, primarily for the Asian market.
| Leading Market Players |
|---|
| Jiangxi Tianxin Pharmaceutical Co., Ltd. |
| Niutang Chemical |
| BASF SE |
| Lesaffre |
| Jiheng Pharmaceutical Co., Ltd. |
| DSM Nutritional Products |
| Zydus Lifesciences Limited |
| Emcure Pharmaceuticals Ltd. |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
The substitution dynamic between cost-effective synthetic folic acid and premium 5-methyltetrahydrofolate is reshaping global supply geography and pricing economics. This shift influences manufacturing locations and market segment value capture.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for high-volume folic acid, while premium bioactive forms like 5-methyltetrahydrofolate utilize value-based pricing. Price differentiation stems from quality grade, particularly between food fortification and pharmaceutical applications, and volume scale. Cost compression runs through the commodity folic acid segment, driven by immense production efficiency from Chinese manufacturers. Food and Beverage Producers exhibit the highest price sensitivity, whereas Pharmaceutical Firms prioritize purity and efficacy over cost.
Supply Chain Analysis
Petrochemical precursor availability represents a chokepoint for synthetic folic acid production, impacting global supply stability. Geographic supply concentrates in China and India for commodity folic acid, with specialized bioactive forms originating from Germany and Switzerland. The supply chain relies on specific chemical intermediates for folic acid, making it vulnerable to input cost volatility from the petrochemical supply chain, which directly influences manufacturing margins. Distribution runs primarily through direct sales channels for industrial clients, while online retailers are expanding access for premium supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The folate market presents a fragmentation opportunity, driven by the demand-side shift toward personalized nutrition services. This shift creates distinct niches for specialized product forms and tailored delivery.
For Market Incumbents:Secure high-volume segments by optimizing cost structures and expanding folic acid capacity in regions like China and India, while investing in microencapsulation technology for functional foods. Diversify into advanced bioactive forms like 5-methyltetrahydrofolate to counter the "clean label" consumer preference. Clinical data substantiation for next-generation folates, aligning with regulators like the US FDA and EFSA, is a critical lever against substitute technologies.
For New Entrants and Emerging Players:Differentiate on metabolic utility and targeted efficacy by focusing on premium dietary supplements for personalized nutrition services. Target the underpenetrated animal nutrition segment, particularly for improving reproductive performance in poultry and swine industries. Leverage direct-to-consumer models and genetic testing platforms to reach consumers seeking specific folate forms like L-Methylfolate, which is a highly penetrable niche.
For Investors and Strategic Acquirers:Regulatory harmonization of novel folate form approvals across major bodies like the US FDA and EFSA reshapes the acquisition landscape for specialized ingredient producers. The market demonstrates strong long-term viability, driven by persistent public health mandates and expanding consumer health trends. Acquisition targets should focus on specialized bioproduction firms with robust R&D pipelines for bioactive folate forms. Harmonization signals increased cross-border M&A activity in advanced nutrition ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bioactive Folates | Increases supply of high-value 5-methyltetrahydrofolate for premium dietary supplements in Western markets. |
| Microencapsulation Technology Investment | Protects sensitive folate compounds from degradation, enabling broader functional food and beverage fortification. |
| Clinical Data Generation for Novel Forms | Supports regulatory approval and health claims for next-generation folates with bodies like the US FDA. |
| Direct-to-Consumer Platform Development | Expands market access for personalized nutrition services and specialized folate regimens. |
| Strategic Partnerships in Animal Nutrition | Enhances market penetration for folate applications in breeding livestock health and reproductive performance. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, regulatory affairs specialists, and product managers anchored the qualitative base, validated against extensive secondary data like trade statistics, company annual reports, and government health statistics. A dual approach of bottom-up data aggregation and top-down market sizing ensured comprehensive analysis, with triangulation strengthening data integrity.
Sensitivity analysis informed the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions included product type, application, end user, distribution channel, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and future projections, incorporating mandatory fortification mandates and evolving consumer health awareness. This approach provided robust market sizing.
The analysis sits within stated boundaries; outcomes outside major regulatory changes or unforeseen technological breakthroughs would require recalibration. Forecasts reflect underlying assumptions regarding market dynamics and competitive responses. Practitioners should keep alternative scenarios live as global trade policies and scientific understanding evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Medicinal Mushroom Supplement Market