
 Inositol Market | 2026-2036
Inositol Market Size, Share, and Industry Trends Forecast 2026-2036
Inositol Market Analysis
Fermentation-based biomanufacturing is rewriting production economics for high-purity inositol, displacing traditional extraction from corn steep liquor with engineered yeast strains that yield pharmaceutical-grade myoinositol at lower impurity profiles. DSM-Firmenich leverages its integrated biotechnology platform to control strain development and downstream purification across European and Asian facilities. Zhucheng Haotian Pharm anchors Shandong province's supply base with captive fermentation capacity serving domestic pharmaceutical and export nutraceutical channels. TSUNO Co., Ltd. differentiates through Japanese pharmacopeia-grade certification and long-standing relationships with research institutions requiring ultrahigh-purity phosphoinositides.
Inositol denotes a cyclohexanehexol stereoisomer family, with myoinositol representing the predominant bioactive form synthesized via microbial fermentation or extracted from phytic acid hydrolysates, typically achieving purity thresholds exceeding 99.5% for pharmaceutical applications. The compound functions primarily as a second-messenger precursor in insulin signaling pathways and membrane phospholipid synthesis, driving its therapeutic use in polycystic ovary syndrome, anxiety disorders, and gestational diabetes protocols. Powder formulations dominate commercial volume due to lower production costs and flexible dosing in bulk nutraceutical compounding, while capsule and tablet forms command premium positioning in direct-to-consumer mental health and PCOS supplement portfolios. Myoinositol maintains mature market leadership with established clinical validation, though D-chiro inositol is gaining formulation share in insulin-sensitizing applications where stereoisomer-specific activity matters.
The US FDA maintains dietary supplement Current Good Manufacturing Practice enforcement that shapes purity documentation requirements for inositol imports, while China's NMPA and SAMR administer GB standards for food-grade and pharmaceutical-grade fermentation products that determine domestic market access and export eligibility. The European Food Safety Authority evaluates novel food and health claim substantiation for inositol-containing products under EFSA guidance, creating a bifurcated compliance pathway between generic supplement positioning and approved medical food designations. Stakeholders must monitor regulatory divergence between pharmacopeia-grade and food-grade specifications as jurisdictions tighten contaminant thresholds for myoinositol sourced from genetically modified microbial strains.
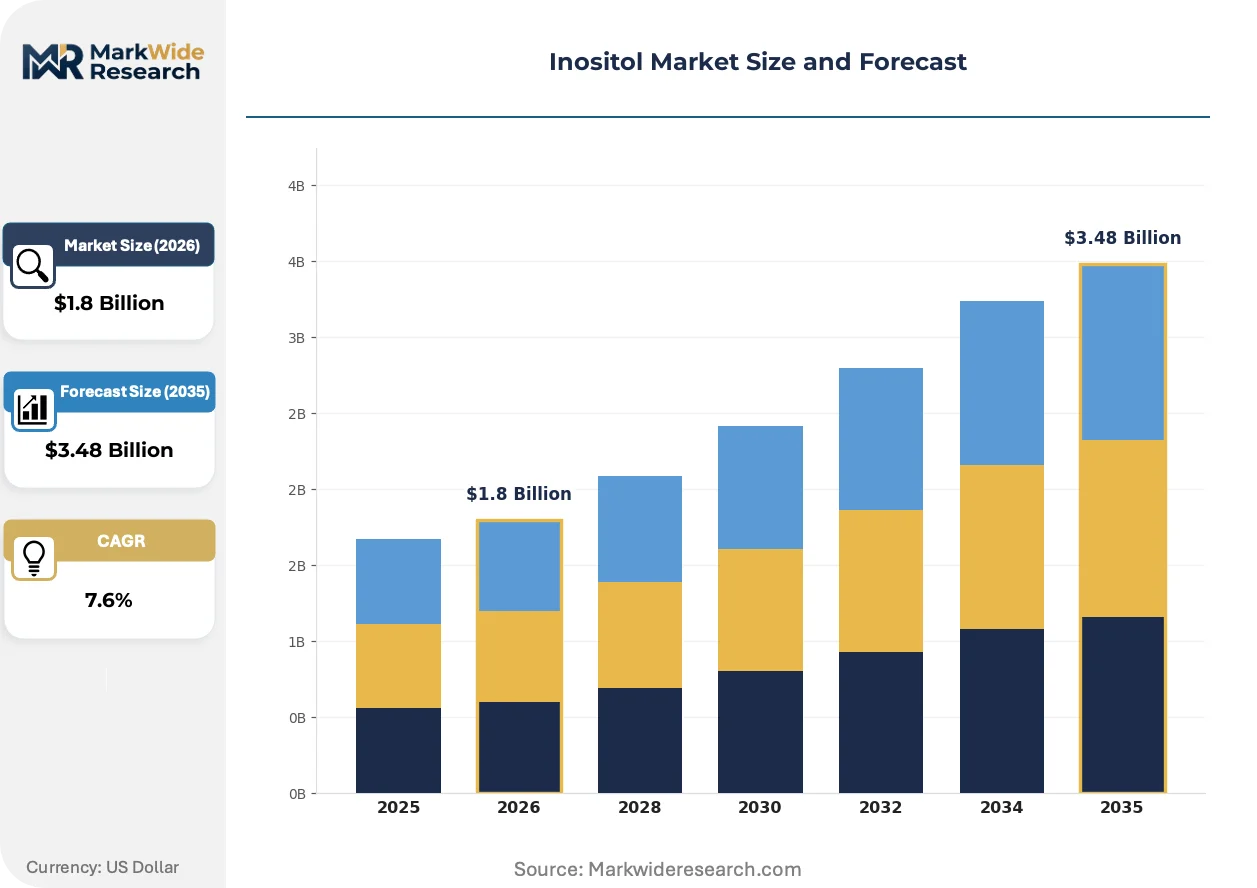
Market Dynamics
Fermentation-based myoinositol production is consolidating supply around Shandong and Jiangsu provinces, while China's NMPA tightens GB standards and US FDA CGMP enforcement intensifies documentation burdens for cross-border nutraceutical shipments.
Growth Catalysts
- Insulin-sensitizing protocols:Polycystic ovary syndrome treatment guidelines in North America and Europe now incorporate myoinositol as first-line metabolic support, expanding prescription-adjacent nutraceutical demand.
- GB standards alignment:China's SAMR harmonization of food-grade and pharmaceutical-grade purity thresholds is accelerating domestic fermentation capacity upgrades that simultaneously serve export markets.
- Phosphoinositide research:Academic neuroscience and cancer biology programs are consuming ultrahigh-purity inositol derivatives for signal transduction studies, creating a premium tier above commodity nutraceutical grades.
Market Restraints
- Corn steep liquor dependency:Traditional extraction routes face input cost volatility from agricultural commodity cycles, squeezing margin structures for non-fermentation producers.
- Shandong supply concentration:Contract manufacturing clusters in eastern China create geographic single-point vulnerability for North American and European brand owners seeking dual-source security.
- GMO strain disclosure:EFSA novel food evaluations and consumer labeling preferences in Germany and France impose friction on genetically modified yeast-derived products despite superior purity profiles.
Strategic Opportunities
- Gestational diabetes protocols:Maternal health clinics in Italy and Spain are piloting myoinositol supplementation as standard-of-care, opening clinical-channel positioning distinct from retail nutraceuticals.
- Direct-to-consumer mental health:Anxiety and panic disorder applications are migrating from psychiatric prescribing to subscription wellness platforms, enabling margin capture outside pharmacy distribution.
- Japanese pharmacopeia certification:PMDA-aligned ultrahigh-purity standards command 40-60% price premiums in research-institution procurement, rewarding investment in downstream purification technology.
Industry Challenges
- Fermentation scale-up talent:Industrial microbiology and downstream processing expertise concentrates at a handful of academic programs in the Netherlands and Denmark, constraining rapid capacity expansion.
- Dual carbon compliance:China's MEE energy-intensity targets for chemical manufacturing are forcing retrofit investments at existing fermentation facilities, compressing near-term free cash flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inositol Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Myoinositol, D-Chiro Inositol, Phosphoinositides, Others Application: Neurotransmitter Regulation, PCOS Treatment, Mental Health, Dietary Supplements End User: Pharmaceutical Companies, Nutraceutical Manufacturers, Research Institutions, Hospitals Form: Powder, Liquid, Capsules, Tablets |
| Companies Covered | DSM-Firmenich, TSUNO Co., Ltd., Zhucheng Haotian Pharm Co. Ltd, Inner Mongolia Kingdomway Pharmaceutical Co., Ltd., Anhui Huaheng Biotechnology Co., Ltd, Shandong Runde Biotechnology Co., Merck KGaA (Sigma-Aldrich), Ronas Chemicals Ind. Co. Ltd, Charles Bowman & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inositol Market Emerging Trajectories
Biomanufacturing strain engineering and regulatory disclosure requirements are simultaneously elevating purity benchmarks and fragmenting competitive positioning across pharmaceutical, nutraceutical, and research-grade tiers.
CRISPR-optimized Saccharomyces cerevisiae strains with enhanced inositol-1-phosphate synthase expression are achieving 99.9% purity without multiple recrystallization steps. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these platforms to reduce solvent waste disposal costs. The technology is rendering obsolete traditional corn steep liquor extraction for applications above food-grade specifications.
EFSA's 2023 updated guidance on novel food applications for microbial-derived ingredients now mandates whole-genome sequencing disclosure for genetically modified production strains. European brand owners are reformulating supply agreements to include regulatory defense indemnification clauses. Research-grade phosphoinositide suppliers with pre-existing pharmacopeia certifications are capturing market access that new entrants cannot replicate within standard commercialization timelines.
Specialized maternal health clinics in Italy and reproductive endocrinology practices in the United Kingdom are consolidating procurement through group purchasing organizations, displacing fragmented pharmacy and e-commerce purchasing. These clinical buying collectives negotiate multi-year supply contracts with guaranteed purity documentation. The shift concentrates volume among fermentation producers with existing pharmaceutical-grade certifications, marginalizing commodity-grade suppliers.
Inositol Market Segmentation
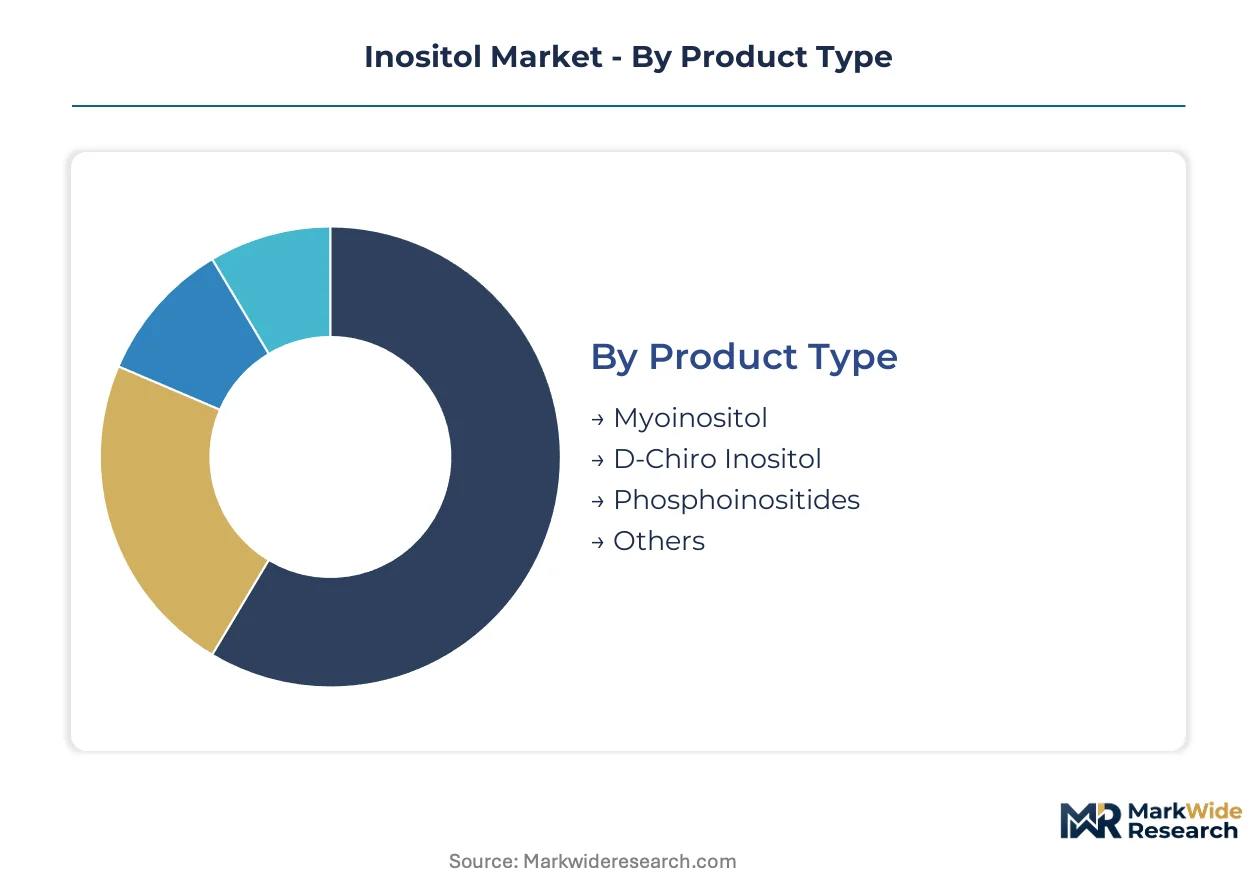
Inositol segmentation reveals how purity requirements and clinical validation tiers fragment supply economics across pharmaceutical, nutraceutical, and research channels. Product stereochemistry and downstream processing intensity determine which manufacturers capture margin in each tier.
Product Type:
After-sales technical support intensity escalates dramatically from commodity nutraceutical grades through pharmacopeia-certified derivatives, with research-grade phosphoinositides demanding dedicated analytical documentation and batch-specific certificates of analysis.
- Myoinositol:The predominant cyclohexanehexol stereoisomer synthesized via engineered yeast fermentation or corn steep liquor extraction, achieving purity thresholds exceeding 99.5% for pharmaceutical applications. Demand concentrates in China's Shandong province fermentation clusters serving North American PCOS supplement brands, where insulin-sensitizing protocol adoption drives volume.
- D-Chiro Inositol:The epimeric form exhibiting stereospecific activity in insulin signal transduction, produced through selective enzymatic inversion or chromatographic separation of myoinositol feedstocks. Italian and Spanish maternal health clinics are consolidating procurement through clinical buying collectives, opening prescription-adjacent positioning distinct from retail channels.
- Phosphoinositides:Membrane lipid derivatives requiring ultrahigh-purity downstream processing for neuroscience and cancer biology research.
- Others:Minor stereoisomers and synthetic analogs including scyllo-inositol for neurodegenerative research protocols.
By volume, Myoinositol leads. By growth pace, D-Chiro Inositol is ahead.
Application:
Cost tier stratification separates premium clinical-channel positioning from commodity nutraceutical retail, with reimbursement-adjacent applications commanding documentation investments that generic supplement brands cannot justify.
- PCOS Treatment:First-line metabolic support protocols in North American and European reproductive endocrinology practices, where myoinositol supplementation addresses insulin resistance and ovarian function. United Kingdom group purchasing organizations are negotiating multi-year supply contracts with guaranteed purity documentation, concentrating volume among fermentation producers with existing pharmaceutical-grade certifications.
- Mental Health:Anxiety and panic disorder applications migrating from psychiatric prescribing to subscription wellness platforms, enabling margin capture outside pharmacy distribution. German and Swiss contract manufacturers are adopting CRISPR-optimized yeast platforms to reduce solvent waste disposal costs while meeting EFSA novel food disclosure requirements.
- Neurotransmitter Regulation:Second-messenger precursor applications in academic signal transduction research requiring ultrahigh-purity grades.
- Dietary Supplements:Bulk powder formulations for flexible dosing in compounding and direct-to-consumer wellness portfolios.
PCOS Treatment commands the highest purity premiums. Mental Health is expanding most quickly into direct-to-consumer channels.
End User:
Customer type determines documentation burden and contract structure, with research institutions paying 40-60% premiums for pharmacopeia-aligned ultrahigh-purity standards that nutraceutical manufacturers will not absorb.
- Pharmaceutical Companies:Integrated drug developers sourcing myoinositol for active pharmaceutical ingredient synthesis and formulation excipients, requiring FDA Current Good Manufacturing Practice documentation and batch release testing. China's NMPA tightening of GB standards for pharmaceutical-grade fermentation products is accelerating domestic capacity upgrades that simultaneously serve export markets.
- Nutraceutical Manufacturers:Contract manufacturers and brand owners in North America and Europe compounding bulk powder into finished supplements, facing intensified FDA CGMP enforcement on purity documentation for cross-border shipments.
- Research Institutions:Academic neuroscience and cancer biology programs consuming ultrahigh-purity phosphoinositides for signal transduction studies.
- Hospitals:Maternal health clinics in Italy piloting myoinositol supplementation as standard-of-care for gestational diabetes protocols.
Pharmaceutical Companies anchor volume procurement. Research Institutions generate the steepest price premiums per kilogram.
Form:
Manufacturing margin concentrates in finished dosage forms, with powder serving as the cost-optimized input for bulk compounding while capsules and tablets capture consumer-facing brand economics.
- Powder:Dominant commercial volume due to lower production costs and flexible dosing in bulk nutraceutical compounding, produced through spray drying or crystallization of fermentation broth. Shandong and Jiangsu province fermentation facilities supply North American and European contract manufacturers seeking dual-source security.
- Capsules:Premium positioning in direct-to-consumer mental health and PCOS supplement portfolios, requiring encapsulation equipment and stability testing investments that powder suppliers avoid.
- Tablets:Compressed dosage forms for pharmacy and clinical distribution channels with established monograph specifications.
- Liquid:Pediatric and geriatric formulations with solubility-enhanced delivery systems for populations with swallowing difficulties.
Powder leads by tonnage shipped. Capsules are gaining share fastest in subscription wellness platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation facilities in Shandong and Jiangsu provinces export pharmaceutical-grade myoinositol to North American nutraceutical brands and European contract manufacturers, with regulatory divergence between FDA CGMP and EFSA novel food disclosure requirements shaping compliance investments.
United States
Reproductive endocrinology practices incorporate myoinositol into PCOS treatment protocols, expanding prescription-adjacent nutraceutical demand. FDA Current Good Manufacturing Practice enforcement intensifies documentation burdens for cross-border shipments from Chinese suppliers. California and New Jersey host contract manufacturing clusters that compound bulk powder into finished capsules for direct-to-consumer mental health platforms.
China
NMPA tightening of GB standards for pharmaceutical-grade fermentation products accelerates domestic capacity upgrades serving export markets. SAMR harmonization of food-grade and pharmaceutical-grade purity thresholds reshapes import-export compliance for Shandong and Jiangsu production clusters. Zhucheng and Lianyungang anchor the supply base with captive fermentation capacity for North American and European brand owners.
Germany
Contract manufacturers adopt CRISPR-optimized yeast platforms to reduce solvent waste disposal costs while meeting EFSA novel food disclosure requirements. German pharmacopeia-grade certification commands premium positioning in research-institution procurement. Bavaria and North Rhine-Westphalia concentrate nutraceutical compounding operations for anxiety and panic disorder applications.
Italy
Maternal health clinics pilot myoinositol supplementation as standard-of-care for gestational diabetes protocols, opening clinical-channel positioning distinct from retail nutraceuticals. Group purchasing organizations negotiate multi-year supply contracts with guaranteed purity documentation. Lombardy and Emilia-Romagna host reproductive endocrinology practices consolidating procurement through clinical buying collectives.
Japan
Academic neuroscience and cancer biology programs consume ultrahigh-purity phosphoinositides for signal transduction studies, creating a premium tier above commodity nutraceutical grades. PMDA-aligned pharmacopeia standards command price premiums in research-institution procurement. Tokyo and Osaka metropolitan areas concentrate downstream purification technology investments serving domestic and export research channels.
Inositol Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three tiers: fermentation-based manufacturers with integrated biotechnology platforms, extraction-based suppliers dependent on agricultural feedstocks, and research-grade specialists with pharmacopeia certifications. Structure consolidates around Shandong province production clusters while fragmenting across European and Japanese ultrahigh-purity niches. Strategic archetypes include scale-driven fermentation operators, purity-differentiated research suppliers, and brand-integrated nutraceutical compounders. Dominant competitive moves encompass capacity expansion in Chinese fermentation facilities and portfolio diversification into D-chiro inositol stereoisomer production.
Within the fermentation-integrated tier, DSM-Firmenich represents multinational biotechnology platform control across European and Asian facilities. Zhucheng Haotian Pharm Co. Ltd anchors Shandong province supply concentration with captive capacity serving domestic pharmaceutical and export nutraceutical channels. TSUNO Co., Ltd. occupies a position within the research-grade specialist archetype, exemplifying Japanese pharmacopeia-grade certification for ultrahigh-purity phosphoinositide applications.
| Leading Market Players |
|---|
| DSM-Firmenich |
| TSUNO Co., Ltd. |
| Zhucheng Haotian Pharm Co. Ltd |
| Inner Mongolia Kingdomway Pharmaceutical Co., Ltd. |
| Anhui Huaheng Biotechnology Co., Ltd |
| Shandong Runde Biotechnology Co. |
| Merck KGaA (Sigma-Aldrich) |
| Ronas Chemicals Ind. Co. Ltd |
| Charles Bowman & Company |
| Others |
Supply Flow & Price Mechanics
Shandong province fermentation clusters anchor global myoinositol capacity, concentrating upstream supply power among engineered-yeast producers who dictate contract terms to North American and European nutraceutical brands seeking pharmaceutical-grade certification. This geographic concentration enables tiered pricing stratification across research-grade, pharmaceutical-grade, and food-grade purity thresholds, with downstream buyers absorbing documentation costs for FDA CGMP and EFSA novel food compliance.
Pricing Analysis
Cost-plus contracts with corn steep liquor indexation dominate traditional extraction routes, while fermentation-based suppliers leverage fixed-cost platforms to offer volume-scaled pricing. Price differentiation hinges on pharmacopeia certification tier and GMO strain disclosure documentation, with German and French buyers demanding premium transparency. Pricing pressure stems from Shandong supply concentration as contract manufacturers seek dual-source security. Nutraceutical compounders exhibit highest price sensitivity; research institutions absorb 40-60% premiums for PMDA-aligned ultrahigh-purity grades.
Supply Chain Analysis
Zhucheng Haotian Pharm and Shandong Runde Biotechnology anchor contract-manufacturing concentration in eastern China, with DSM-Firmenich operating integrated European facilities. Supply draws from engineered Saccharomyces cerevisiae strains, corn steep liquor feedstocks, and chromatographic separation resins. Single-source vulnerability concentrates in Shandong-Jiangsu corridor disruption. Distribution runs through clinical buying collectives in Italy and the United Kingdom, direct-to-consumer wellness platforms in Germany and Switzerland, and research-procurement channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than commodity powder volumes, with guaranteed purity documentation and batch-specific analytical certificates emerging as recurring-revenue layers that fermentation producers monetize across clinical and research channels.
For Market Incumbents: Harden pharmacopeia-grade certification moats against CRISPR-optimized yeast platform commoditization by investing in downstream phosphoinositide purification technology. Expand captive fermentation capacity in Jiangsu province to dilute Shandong geographic concentration risk. Lock multi-year supply contracts with Italian maternal health clinics and United Kingdom group purchasing organizations before clinical-channel procurement consolidates further. For New Entrants and Emerging Players: Pursue gestational diabetes protocol positioning in Spanish and Italian reproductive endocrinology practices, where prescription-adjacent clinical channels remain underpenetrated by established nutraceutical brands. Target anxiety and panic disorder applications on subscription wellness platforms, where German and Swiss contract manufacturers seek D-chiro inositol stereoisomer supply. Lead with EFSA novel food regulatory defense indemnification as a differentiated service layer. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-integrated specialists with existing pharmaceutical-grade certifications over extraction-dependent agricultural feedstock players. Long-term viability accrues to producers controlling CRISPR strain development and downstream purification in a single platform. Watch for PMDA-aligned ultrahigh-purity procurement acceleration in Japanese academic neuroscience programs as signal of research-grade tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphoinositide Purification Technology Investment | Captures 40-60% price premiums in Japanese research-institution procurement channels. |
| Dual-Source Fermentation Capacity Expansion | Mitigates Shandong supply concentration vulnerability for North American brand owners. |
| EFSA Novel Food Regulatory Defense Indemnification | Reduces procurement friction for German and French GMO strain disclosure requirements. |
| Clinical Buying Collective Contract Structuring | Secures multi-year volume commitments from Italian maternal health clinic networks. |
| D-Chiro Inositol Stereoisomer Production Diversification | Addresses insulin-sensitizing protocol demand in Spanish reproductive endocrinology practices. |
Methodological Framework
Desk research of FDA Warning Letters, EFSA novel food application databases, and NMPA GB standard filings preceded structured interviews with fermentation plant managers, nutraceutical contract manufacturing procurement leads, reproductive endocrinology clinic administrators, and research-institution procurement officers. Secondary validation drew from customs trade data, pharmacopeia certification registries, and clinical trial protocol publications. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-referenced stakeholder inputs.
Assumptions held regulatory disclosure requirements and purity threshold trajectories within current FDA CGMP and EFSA guidance patterns, while varying corn steep liquor commodity price cycles and CRISPR strain licensing diffusion rates across the projection horizon. Segmentation dimensions modeled included product stereochemistry, application protocol tier, end-user documentation burden, and regional regulatory cluster. CAGRs were derived from installed fermentation capacity expansion schedules correlated with clinical guideline adoption curves in PCOS and gestational diabetes treatment protocols.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by extraction-dependent agricultural feedstock producers or accelerated PMDA certification investments by new entrants would shift outcomes. Regulatory divergence between pharmacopeia-grade and food-grade specifications, plus GMO strain labeling preference evolution in European markets, constitute primary revision risks. Quarterly review of NMPA GB standard amendment proposals and EFSA whole-genome sequencing disclosure enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Argentina Nutraceuticals Market