
 US Protein Supplements Market | 2026-2036
US Protein Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
US Protein Supplements Market Insights
Fitness enthusiasts and casual lifestyle consumers is unwinding the long-standing dominance of competitive bodybuilders in protein supplement purchasing. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and outpatient channels with medical-grade formulations. Quest Nutrition differentiates through flavor innovation and clean-label positioning that resonates with mainstream grocery shoppers. Glanbia plc controls upstream whey protein supply through its dairy processing infrastructure, securing margin capture across ingredient and finished goods tiers.
Protein supplements encompass concentrated, isolated, or hydrolyzed protein formulations derived from animal or plant sources, typically delivering 15-30 grams of protein per serving through powder, bar, or ready-to-drink delivery systems. Whey protein dominates manufacturing throughput due to superior leucine content and rapid absorption kinetics, while soy and emerging plant proteins occupy expanding shelf space amid flexitarian dietary shifts. Ready-to-drink formats command premium price positioning in convenience channels, whereas powder maintains volume leadership through cost-per-serving economics and customization flexibility.
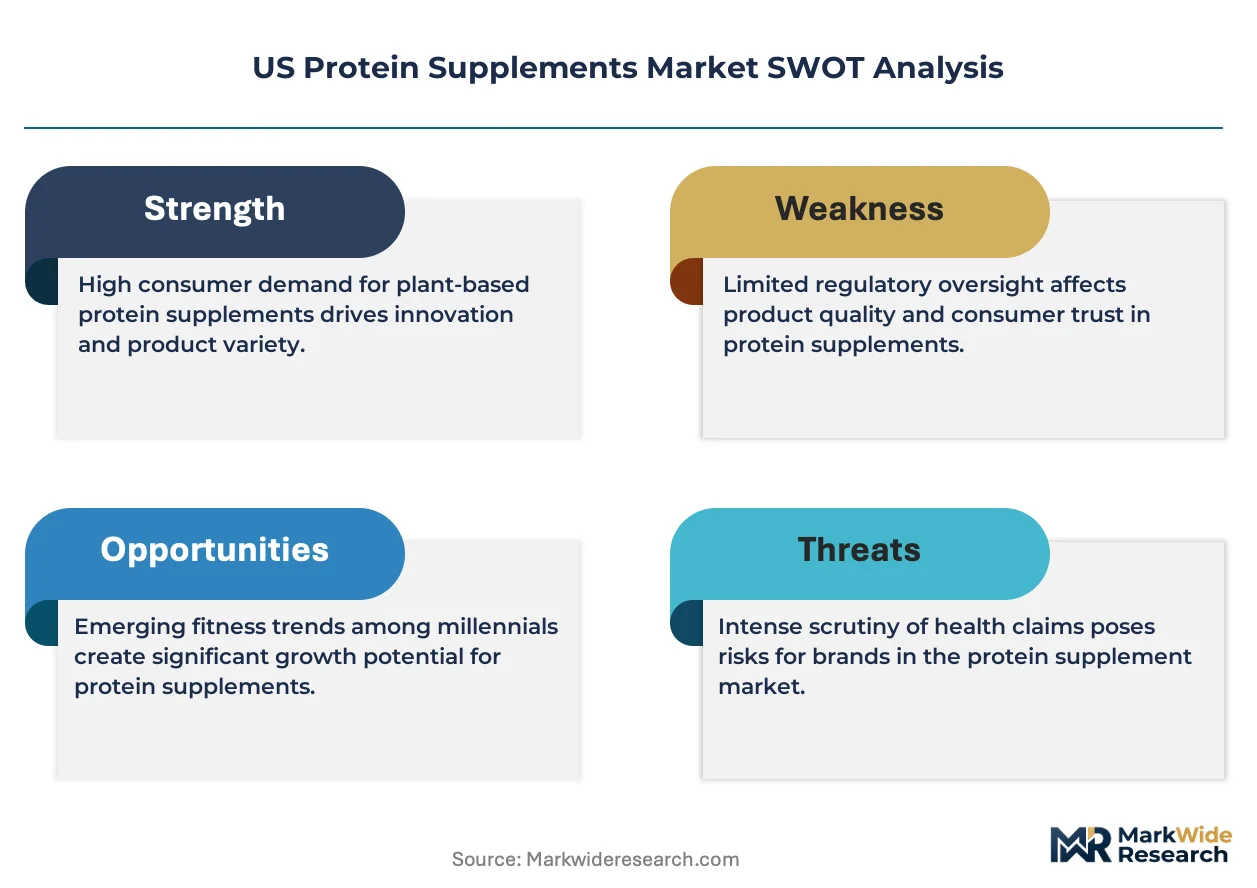
FDA Current Good Manufacturing Practice regulations and FTC substantiation requirements enforce label accuracy and prohibit unsubstantiated health claims, elevating compliance costs for smaller entrants while benefiting established operators with quality infrastructure. USDA Organic certification and NSF Certified for Sport standards further segment accessible market tiers, creating differentiated positioning for premium and performance-focused brands. Stakeholders must monitor evolving FDA guidance on novel protein sources and state-level legislation affecting supplement sales taxation and age restrictions.
Market Dynamics
FDA Current Good Manufacturing Practice enforcement is compressing formulation flexibility while elevating quality infrastructure requirements across the US protein supplements sector. This regulatory tightening coincides with flexitarian dietary shifts that are fragmenting traditional whey-dominant demand patterns into plant-protein alternatives.
Growth Catalysts
- NSF Certified for Sport adoption:Collegiate and professional athletic programs mandate third-party testing protocols, expanding addressable market for verified-clean formulations in Texas and Florida training facilities.
- Ready-to-drink format penetration:Convenience-channel placement in California gas stations and drugstores captures impulse purchase behavior from time-constrained professionals.
- USDA Organic certification pipeline:Premium grocery retailers in metropolitan clusters demand certified supply, pulling reformulation investment toward organic whey and plant protein sourcing.
Market Restraints
- Whey protein input volatility:Dairy commodity price swings tied to Midwest milk production cycles compress margin predictability for powder manufacturers.
- Supply concentration in Upper Midwest:Three dairy processing cooperatives control majority domestic whey isolate output, creating bottleneck risk for finished goods producers.
- FTC substantiation requirements:Advertising claim documentation demands elevate legal compliance costs disproportionately for sub-scale entrants.
Strategic Opportunities
- Clinical nutrition channel expansion:Hospital outpatient and long-term care facilities in Florida and Arizona present underdeveloped distribution for medical-grade protein formulations.
- Cell-cultured protein convergence:Precision fermentation technologies intersecting with supplement manufacturing enable novel amino acid profiles distinct from conventional dairy or plant sources.
- Direct-to-subscription models:Personalized nutrition platforms bypass retail margin extraction while capturing recurring revenue from California and New York metro consumers.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, flavor masking, and clean-label stability commands premium compensation in competitive labor markets.
- Dual certification timeline compression:Simultaneous FDA facility registration and NSF sport certification processes extend product launch windows by 8-14 months.
- Legacy ERP integration friction:Lot-tracking and recall management systems require substantial reconfiguration to meet serialized supply chain mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Protein Supplements Market |
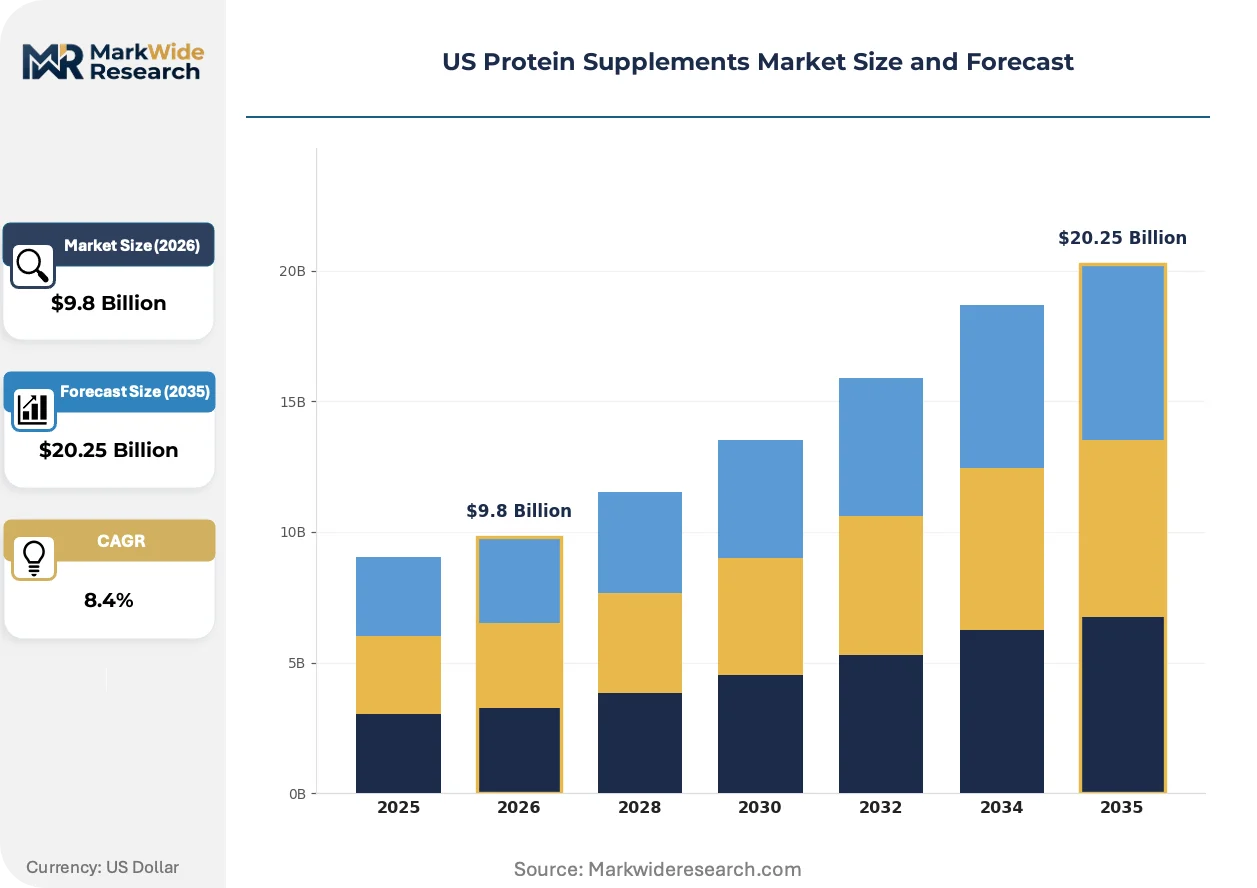
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Casein, Soy, Egg Form: Powder, Bar, Ready-to-Drink, Capsule End User: Athletes, Bodybuilders, Fitness Enthusiasts, Vegetarians Distribution Channel: Online, Supermarkets, Health Stores, Gyms |
| Companies Covered | BellRing Brands, Abbott Laboratories, Herbalife Nutrition Ltd., Nestlé S.A., GNC Holdings Inc., CytoSport Inc., Iovate Health Sciences International Inc., Quest Nutrition, Glanbia plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Protein Supplements Market Trends and Innovations
Protein source diversification is fragmenting manufacturing investment across animal, plant, and novel fermentation-derived inputs. Three concurrent developments are compressing traditional category boundaries while elevating technical sophistication requirements.
Precision fermentation-derived proteins are decomposing conventional supply chain dependencies on agricultural commodity cycles. Biotech startups in California and Massachusetts pilot facilities at 10,000-liter scales, attracting venture funding from institutional investors seeking decoupled production economics. This technology is decomposing the historical link between dairy futures pricing and finished goods margin structure.
FDA guidance development on novel protein sources is compressing approval timelines for fermentation-derived ingredients while elevating safety documentation burdens. The agency's Emerging Technology Program creates expedited review pathways for qualified applicants, though GRAS self-determination remains contested for certain microbial strains. Supplement brands with pre-submission engagement histories capture first-mover positioning in this regulatory window.
Subscription-based personalized nutrition is displacing mass-market SKUs among high-frequency users in coastal metropolitan markets. Algorithm-driven formulation matching protein type, dosage, and flavor to individual microbiome data compresses brand loyalty while elevating churn risk. This behavioral shift concentrates most visibly in California and New York, where digital health integration penetrates earliest.
US Protein Supplements Market Segmentation
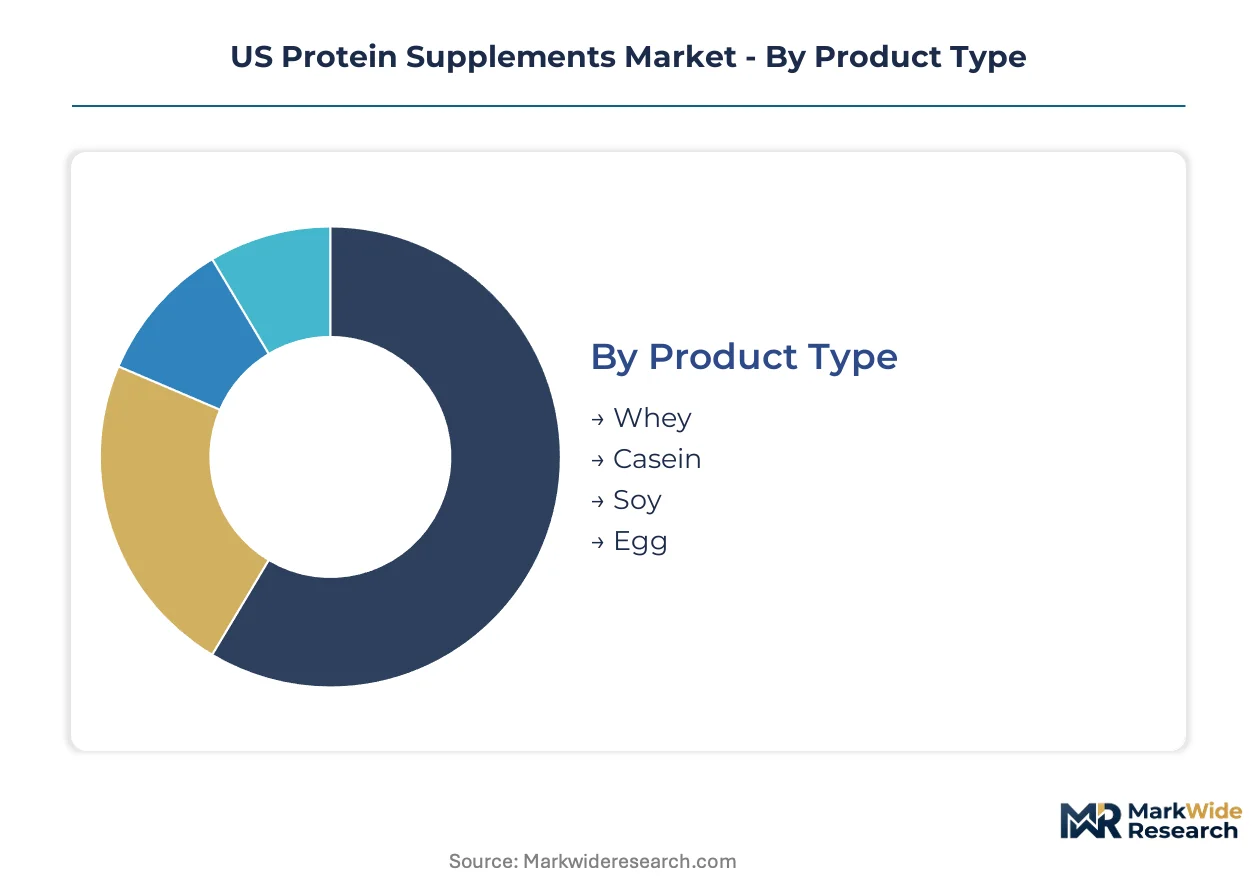
Segmentation in the US protein supplements market reveals divergent growth vectors across formulation chemistry, delivery convenience, and channel economics. Understanding these partitions exposes where margin capture concentrates versus where volume expansion accelerates.
Product Type:
Domestic dairy infrastructure dominates whey and casein sourcing, while soy and egg proteins draw partially on import supply chains for raw material diversification.
- Whey:Rapidly absorbed complete protein with superior leucine density per gram. Demand concentrates in Texas and Florida gym chains where NSF Certified for Sport procurement mandates elevate quality specifications. FDA dairy facility inspections enforce consistent manufacturing standards.
- Casein:Slow-digesting micellar structure delivers sustained amino acid release over 6-8 hours. Overnight recovery protocols in collegiate athletic programs across California drive institutional purchasing contracts.
- Soy:Plant-based complete protein with established GRAS status. Flexitarian consumers in metropolitan grocery channels sustain volume despite flavor masking challenges.
- Egg:Albumen-derived alternative for dairy-intolerant users. Niche positioning in specialized nutrition stores with limited mainstream retail penetration.
Whey holds the largest share; momentum sits with soy amid flexitarian dietary shifts.
Form:
Cost-per-serving economics stratify sharply across formats, with powder commanding unit efficiency and ready-to-drink extracting convenience premiums.
- Powder:Bulk packaging enables sub-dollar per-serving economics. Home-blending culture in cost-conscious Midwest markets sustains household penetration rates.
- Bar:Shelf-stable matrix combining protein with carbohydrate and fat macronutrients. Impulse placement at California convenience stores captures commuter consumption occasions.
- Ready-to-Drink:Pre-mixed liquid formulations in single-serve bottles. Premium price positioning in drugstore and gas station channels across high-income zip codes drives revenue per transaction.
- Capsule:Compressed protein delivery for swallowing-preference consumers. Limited absorption efficiency constrains expansion beyond specialty supplement retailers.
Powder maintains volume leadership; ready-to-drink is climbing the fastest on per-unit value extraction.
End User:
Professional versus recreational usage patterns split procurement behavior between institutional contracts and discretionary retail purchasing.
- Athletes:Collegiate and professional competitors with program-supplied nutrition protocols. Third-party testing requirements from NCAA and professional leagues elevate certified-product demand in Texas and Florida training facilities.
- Bodybuilders:Traditional high-volume consumers with precise macronutrient tracking. Concentrated purchasing through specialty retailers with bulk powder preference.
- Fitness Enthusiasts:Recreational gym-goers prioritizing convenience and taste. Mainstream grocery channel migration in California and New York metro areas accelerates format diversification.
- Vegetarians:Dietary-restriction-driven consumers seeking complete amino acid profiles. Plant-protein blends in natural food co-ops and online subscription services capture loyalty.
Fitness enthusiasts hold the largest share; vegetarians are gaining share fastest on dietary identity alignment.
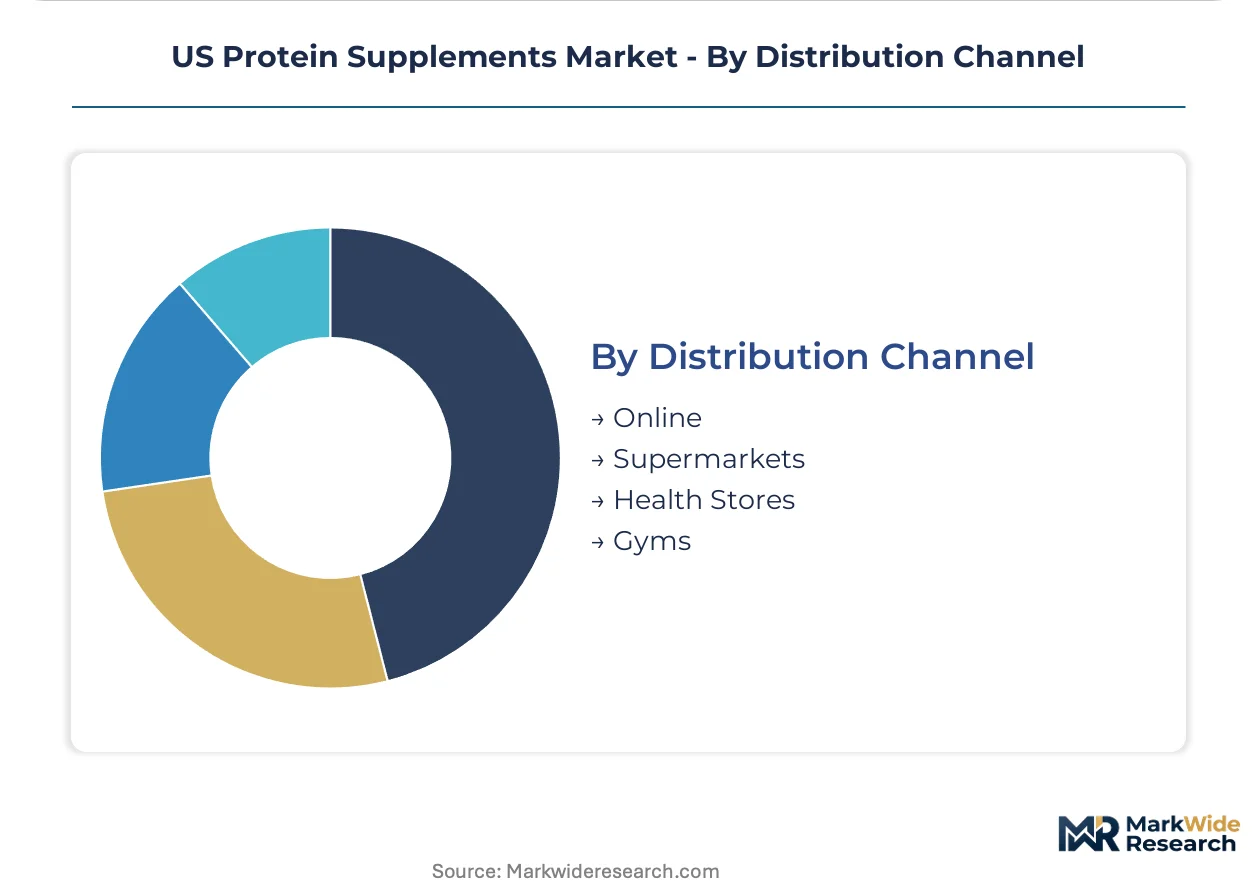
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer models bypassing retail markup while brick-and-mortar enables tactile evaluation.
- Online:Direct-to-consumer and marketplace platforms with subscription automation. California and New York metro consumers drive highest digital penetration rates for personalized nutrition algorithms.
- Supermarkets:Mass-market placement with promotional velocity dependence. Clean-label positioning in premium grocery banners differentiates from conventional placement.
- Health Stores:Specialty retailers with trained staff consultation. Knowledgeable consumer base in affluent suburban markets sustains premium pricing tolerance.
- Gyms:Point-of-exercise impulse and membership-bundle distribution. Florida and Texas fitness chains with high member density enable captive audience marketing.
Online holds the largest share; gyms are expanding most quickly on contextual consumption timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three dairy processing cooperatives in the Upper Midwest control the majority of domestic whey isolate output, creating geographic chokepoints that ripple through finished goods availability across the country. This upstream concentration shapes downstream pricing and formulation decisions for manufacturers nationwide.
California
Fitness enthusiasts and casual lifestyle consumers drive volume in Los Angeles and San Francisco metro areas, where gym penetration rates exceed national averages. FDA dairy facility inspections enforce consistent manufacturing standards for brands operating in the state. Precision fermentation startups in South San Francisco pilot novel protein production at 10,000-liter scales, attracting venture capital toward decoupled supply chains.
Texas
Collegiate and professional athletic programs in Dallas-Fort Worth and Houston mandate NSF Certified for Sport procurement protocols, elevating demand for third-party tested formulations. FTC substantiation requirements apply to advertising claims targeting these performance-focused buyer segments. Regional distribution hubs in the state serve expanding gym-chain placement for ready-to-drink formats.
Florida
Hospital outpatient and long-term care facilities in Miami and Tampa present underdeveloped channels for medical-grade protein formulations. USDA Organic certification requirements influence sourcing decisions for premium grocery retailers in the state. Abbott Laboratories leverages clinical nutrition heritage to anchor healthcare channel relationships in these metropolitan clusters.
New York Metro
Subscription-based personalized nutrition platforms capture recurring revenue from digitally integrated consumers in Manhattan and Brooklyn. FDA Current Good Manufacturing Practice regulations elevate compliance costs for direct-to-consumer brands shipping into the region. Algorithm-driven formulation services concentrate technical talent and venture funding in this coastal corridor.
Illinois
Cost-conscious Midwest markets sustain bulk powder penetration through home-blending culture in Chicago and surrounding suburbs. Dairy commodity price volatility tied to regional milk production cycles compress margin predictability for local manufacturers. Glanbia plc controls upstream whey protein supply through dairy processing infrastructure serving formulation facilities across the state.
US Protein Supplements Market Competitive Landscape
Concentration sits with diversified nutrition conglomerates and specialized sports nutrition brands that have built quality infrastructure to satisfy FDA and third-party certification requirements. The competitive structure spans three tiers: clinical nutrition specialists with hospital channel access, mainstream consumer brands with grocery retail placement, and emerging precision fermentation players with novel protein technologies. M&A activity targets flavor innovation capabilities and direct-to-consumer subscription platforms, while capacity expansion concentrates in Upper Midwest dairy processing corridors and California biotech clusters.
Within the clinical nutrition tier, Abbott Laboratories exemplifies hospital and outpatient channel anchoring through medical-grade formulation heritage. Quest Nutrition occupies a position exemplifying clean-label positioning and flavor innovation resonance with mainstream grocery shoppers. Glanbia plc represents upstream supply control, securing margin capture across ingredient and finished goods tiers through dairy processing infrastructure. These three players illustrate the archetype diversity spanning healthcare channels, consumer retail, and vertical supply integration that defines competitive positioning in this market.
| Leading Market Players |
|---|
| BellRing Brands |
| Abbott Laboratories |
| Herbalife Nutrition Ltd. |
| Nestlé S.A. |
| GNC Holdings Inc. |
| CytoSport Inc. |
| Iovate Health Sciences International Inc. |
| Quest Nutrition |
| Glanbia plc |
| Others |
Pricing and Supply Chain Analysis
FDA Current Good Manufacturing Practice enforcement gates both supply qualification and price differentiation simultaneously, compressing margin flexibility for non-compliant operators while elevating certified-product premiums. NSF Certified for Sport and USDA Organic tiers command substantial price separation from conventional formulations, with certification investment creating defensible positioning against commodity competition.
Pricing Analysis
FDA Current Good Manufacturing Practice dictates the pricing tier structure across the US protein supplements sector, separating NSF Certified for Sport formulations at premium positioning from standard-grade powders. Three-tier pricing stratifies across premium certified, standard compliant, and economy private-label levels, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies because dairy commodity volatility feeds directly into input costs. Fitness enthusiasts in California and New York metro areas exhibit lowest price sensitivity, while Midwest bulk powder buyers anchor the most cost-conscious segment.
Supply Chain Analysis
The Upper Midwest anchors domestic whey protein isolate production through three dairy processing cooperatives controlling majority output. Raw material dependencies center on fluid milk supply, filtration equipment, and specialized drying infrastructure. Single-source vulnerability concentrates in Wisconsin and Minnesota processing corridors, where limited alternative suppliers create bottleneck exposure for finished goods manufacturers. Distribution runs through direct-to-manufacturer contracting for bulk ingredients, with regional blending facilities in Illinois and California handling final formulation and packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based personalized nutrition services expand faster than hardware-equivalent powder sales, creating a service-attach layer that captures recurring revenue from algorithm-driven formulation matching.
For Market Incumbents: Compound defensive positioning through backward integration into precision fermentation capacity and exclusive NSF Certified for Sport procurement contracts with Texas and Florida collegiate athletic programs. Emerging biotech entrants threaten ingredient supply disruption; captive production of novel protein sources preserves margin control against commodity dairy cycles. For New Entrants and Emerging Players: Lead with direct-to-subscription models targeting California and New York metro fitness enthusiasts, where algorithm-driven personalization displaces mass-market brand loyalty. Hospital outpatient channels in Florida and Arizona present underpenetrated white space for medical-grade formulations. Go-to-market execution should emphasize microbiome-matched product customization over conventional flavor marketing. For Investors and Strategic Acquirers: FDA guidance development on novel protein sources reshapes the acquisition landscape toward precision fermentation platforms with pre-submission regulatory engagement histories. Long-term viability favors vertically integrated operators spanning ingredient production through finished goods, with certification infrastructure as the durable moat. Watch for GRAS self-determination contestation rulings as the signal indicating regulatory window compression for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | California biotech clusters attract venture funding toward decoupled protein production economics. |
| Dual Certification Investment | Simultaneous FDA facility registration and NSF sport certification accelerates institutional channel access. |
| Direct-to-Consumer Subscription Launch | Algorithm-driven personalization captures recurring revenue from digitally integrated coastal metro consumers. |
| Clinical Nutrition Channel Expansion | Hospital outpatient relationships in Florida and Arizona leverage Abbott Laboratories' heritage positioning. |
| Flavor Innovation Acquisition | Quest Nutrition's clean-label capabilities demonstrate resonance with mainstream grocery shopper migration. |
Research Methodology
Desk research of FDA enforcement actions, USDA organic certification databases, and dairy commodity futures preceded structured interviews with protein formulation scientists, sports nutrition brand managers, hospital procurement directors, and health food retail category buyers. Secondary validation drew from NSF International certification registries, FTC advertising substantiation case files, and dairy cooperative production disclosures. Bottom-up demand modeling triangulated against top-down market sizing across ingredient supply tiers.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeled by protein source chemistry, delivery format convenience, end-user procurement behavior, and channel margin structure. CAGRs derive from iterative convergence of historical trajectory analysis and forward-looking elasticity estimates. Industry-specific forecast inputs include collegiate athletic program procurement mandates and precision fermentation pilot scale-up timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or accelerated precision fermentation commercialization would require recalibration. Forecasts reflect documented assumptions regarding dairy commodity cycles, regulatory approval timelines for novel proteins, and subscription platform adoption curves. Recalibration cycles align with material shifts in FDA guidance issuance, NSF certification requirement updates, and venture deployment into alternative protein production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market