
 Ferrous Fumarate Market | 2026-2036
Ferrous Fumarate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrous Fumarate Market Analysis
China is narrowing its position as the dominant API manufacturing base for ferrous fumarate, with Henan province hosting multiple dedicated fermentation and chemical synthesis facilities. Vifor Pharma leverages its vertical integration into iron deficiency therapy development to sustain European supply chain priority. DSM Nutritional Products anchors its position through backward integration into mineral premix formulation, while Allied Biochem Pvt. Ltd. competes on cost-optimized bulk powder exports from Western India.
Ferrous fumarate is an iron(II) salt of fumaric acid containing approximately 33% elemental iron by weight, produced through direct reaction of reduced iron with fumaric acid or via ferrous sulfate conversion processes. Pharmaceutical-grade material commands stricter USP/EP limits on heavy metal contaminants and microbial load than feed or food-grade variants, directing its primary use toward hematinic tablets and capsules for treating iron deficiency anemia. Tablet formulations dominate current volume demand due to established stability profiles and patient compliance advantages in hospital and pharmacy channels. Powder segments exhibit faster expansion in food fortification programs where dry blending into flour and cereal matrices reduces formulation complexity.
US FDA cGMP inspections and USP monograph updates shape API import acceptance criteria for ferrous fumarate entering American pharmaceutical supply chains, while India's CDSCO enforces mandatory testing protocols for iron content dissolution and bioequivalence in generic hematinic products. EMA's revised guidelines on iron supplementation safety thresholds in pregnancy are tightening label claims across European nutraceutical applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate qualification barriers for multi-territory product registrations.
Market Dynamics
Pharmaceutical-grade purity mandates from CDSCO, FDA, and EMA are compressing supplier qualification timelines while simultaneously fragmenting procurement across dual-source requirements for hematinic API security.
Growth Catalysts
- CDSCO dissolution mandates:India's tightened bioequivalence testing for generic iron supplements is disqualifying substandard API imports and consolidating demand around certified pharmaceutical-grade ferrous fumarate suppliers.
- EFSA fortification guidelines:Germany's cereal and flour producers are reformulating with ferrous fumarate to meet revised iron supplementation thresholds in processed foods.
- Direct reduced iron processes:Henan province chemical synthesis facilities are achieving higher elemental iron yields through optimized fumaric acid reaction kinetics.
Market Restraints
- Heavy metal input volatility:Lead and arsenic contamination risks in mineral ore feedstocks force continuous batch testing that adds 12-18% to API qualification costs.
- Henan supply concentration:Over 60% of global fermentation and chemical synthesis capacity sits within a single Chinese province, exposing buyers to regional environmental shutdowns.
- Ferrous bisglycinate substitution:Chelated iron alternatives with superior gastrointestinal tolerability are capturing premium prenatal supplement formulations.
Strategic Opportunities
- Sub-Saharan anemia programs:WHO-backed flour fortification initiatives in Nigeria and Kenya are creating institutional procurement channels for food-grade ferrous fumarate powder.
- USP-EP pharmacopeial harmonization:Aligned heavy metal limits across American and European compendia will reduce dual-registration testing burdens for multi-territory suppliers.
- Direct-to-clinic distribution:Hospital system GPOs are consolidating hematinic purchasing through e-procurement platforms that bypass traditional wholesale markups.
Industry Challenges
- Analytical chemistry talent scarcity:USP heavy metal testing and dissolution profile validation require specialized technicians that API manufacturers struggle to recruit in Western India and Central China.
- cGMP facility requalification:FDA inspection findings on environmental monitoring and batch record integrity are forcing 18-24 month remediation cycles at legacy fermentation plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrous Fumarate Market |
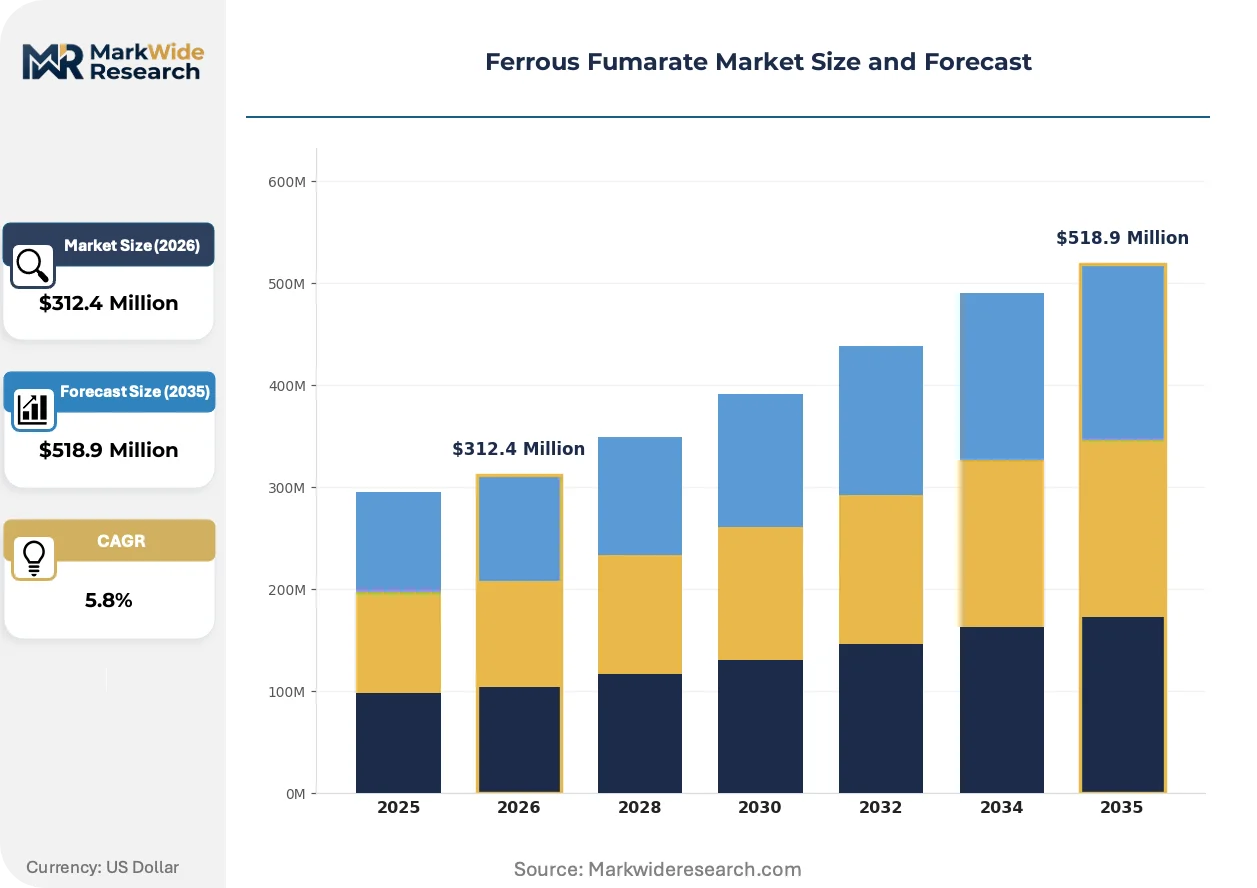
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquids, Powder Application: Dietary Supplements, Pharmaceuticals, Nutraceuticals, Fortification End User: Hospitals, Pharmacies, Online Retailers, Nutritional Clinics Distribution Channel: Direct Sales, Wholesalers, Retail Stores, E-commerce |
| Companies Covered | Vifor Pharma, Ironwood Pharmaceuticals, Galenica Group, Allied Biochem Pvt. Ltd., Lonye Technology Limited, Shreeji Industries, Henan Sinotech Import & Export Corporation, Particle Dynamics International, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrous Fumarate Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory data integrity requirements are reshaping documentation architectures across pharmaceutical and nutraceutical supply chains.
Continuous wet granulation with integrated roller compaction is hybridizing traditional batch tablet processing for ferrous fumarate hematinics. European contract manufacturers are adopting these lines to reduce excipient segregation and moisture-induced degradation. The technology is hybridizing quality assurance workflows by enabling parametric release that bypasses end-point testing delays.
EMA's revised iron supplementation safety thresholds in pregnancy are forcing label claim revisions across European nutraceutical applications. Manufacturers must reformulate to stricter maximum daily dose declarations or face market withdrawal. Prenatal supplement SKUs in Germany and France are responding with split-dose formulations that distribute elemental iron across multiple daily tablets.
Hospital procurement consolidation through group purchasing organizations is compressing supplier margins while demanding extended payment terms. Traditional pharmaceutical distributors in the United States are losing hematinic volumes to direct manufacturer-GPO contracts. The shift is most visible in integrated delivery networks across Texas and Florida where formulary standardization favors single-source ferrous fumarate tablets.
Ferrous Fumarate Market Segmentation
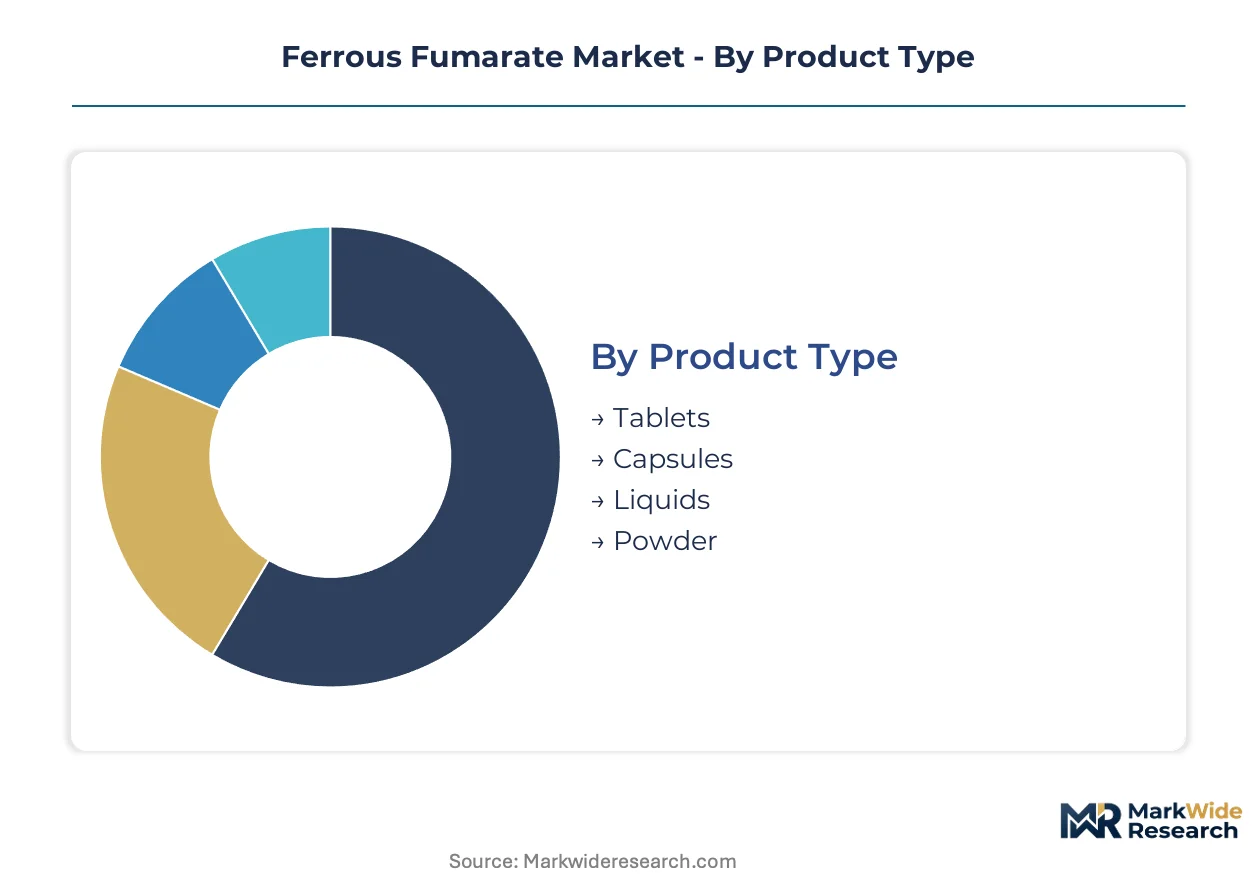
Ferrous fumarate procurement patterns diverge sharply across formulation types and end-use channels. Pharmaceutical-grade specifications, retail distribution economics, and institutional purchasing protocols each reshape supplier priorities and margin structures within this hematinic API market.
Product Type:
Cycle times compress most dramatically in powder processing where dry blending bypasses tablet compression entirely, while liquid formulations demand extended stability testing that stretches batch release timelines.
- Tablets:Compressed dosage forms containing ferrous fumarate with standardized USP dissolution profiles. Hospital GPOs in Texas and Florida are consolidating procurement around single-source tablet contracts that bypass traditional wholesale markups. Tablet formulations anchor the volume base while powder segments gain share at the steepest rate.
- Capsules:Gelatin or HPMC shells enclosing ferrous fumarate granules with modified release characteristics. Nutraceutical brands in Germany favor capsule presentations for prenatal supplement lines reformulating under EMA's revised pregnancy safety thresholds.
- Liquids:Aqueous suspensions requiring stringent microbial load controls and taste-masking excipients. Pediatric anemia programs in Nigeria specify liquid formats for WHO-backed flour fortification initiatives.
- Powder:Bulk API material for food fortification and compounding pharmacies. Cereal manufacturers across Germany source powder grades for dry blending into flour matrices under EFSA-backed iron fortification guidelines.
Tablet formats dominate hospital procurement while powder applications expand most quickly through institutional food fortification channels.
Application:
Cost tiers separate pharmaceutical-grade material commanding USP/EP heavy metal certification from feed-grade variants with relaxed contaminant thresholds.
- Dietary Supplements:Over-the-counter hematinic products targeting general wellness and athletic populations. German retailers are reformulating SKUs with split-dose ferrous fumarate tablets to distribute elemental iron across multiple daily doses.
- Pharmaceuticals:Prescription-grade iron deficiency therapeutics subject to CDSCO bioequivalence mandates and FDA cGMP inspections. Indian generic manufacturers face tightened dissolution testing protocols that disqualify substandard API imports.
- Nutraceuticals:Functional food and beverage applications with label claims bridging nutrition and therapeutic benefit. European contract manufacturers adopt continuous wet granulation to reduce excipient segregation in these value-added formulations.
- Fortification:Institutional flour and cereal enrichment programs. Sub-Saharan anemia initiatives in Kenya create procurement channels for food-grade ferrous fumarate powder with reduced qualification burdens.
Pharmaceutical applications command premium pricing while fortification programs demonstrate the steepest volume expansion trajectory.
End User:
Customer type determines specification stringency, with hospitals demanding batch-level CoA documentation that pharmacies rarely require.
- Hospitals:Integrated delivery networks with formulary standardization and direct manufacturer contracting. IDNs across Texas bypass traditional distributors through e-procurement platforms that compress supplier margins.
- Pharmacies:Community and chain retail dispensing prescription and OTC hematinics. German pharmacy channels face reformulation pressures from EFSA guidelines reshaping iron supplement sourcing patterns.
- Online Retailers:Direct-to-consumer platforms with private-label supplement offerings. These channels favor capsule and tablet formats with extended shelf stability for warehouse distribution.
- Nutritional Clinics:Specialized facilities prescribing therapeutic iron regimens. Clinics in Western India source compounded liquid formulations from regional API manufacturers competing on cost-optimized bulk powder exports.
Hospitals anchor institutional volume while online retailers climb the fastest as consumer purchasing shifts toward direct channels.
Distribution Channel:
Supply concentration in Henan province chemical synthesis facilities shapes channel economics, with direct sales capturing margin that wholesaler networks disperse across multiple handling stages.
- Direct Sales:Manufacturer-to-institution contracts bypassing intermediary markups. Hospital GPOs in Florida leverage direct relationships with ferrous fumarate tablet suppliers to secure extended payment terms.
- Wholesalers:Traditional pharmaceutical distributors losing hematinic volumes to direct manufacturer contracts. These intermediaries retain relevance in fragmented pharmacy markets lacking GPO consolidation.
- Retail Stores:Brick-and-mortar pharmacies and mass merchandisers with OTC supplement sections. German cereal and flour producers supply retail chains reformulating under revised iron supplementation thresholds.
- E-commerce:Digital platforms with algorithmic pricing and subscription replenishment models. These channels expand most quickly in prenatal supplement categories where split-dose ferrous fumarate tablets attract repeat purchase behavior.
Direct sales dominate institutional procurement while e-commerce demonstrates the steepest growth trajectory in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade consumption concentrates in prescription channels across the United States and Germany, while food fortification programs drive powder-grade demand in Nigeria and Kenya. China's Henan province anchors API manufacturing output for export markets.
United States
Hospital group purchasing organizations in Texas and Florida consolidate hematinic procurement through direct manufacturer contracts that bypass traditional pharmaceutical distributors. FDA cGMP inspections and USP monograph updates shape API import acceptance criteria for ferrous fumarate entering American pharmaceutical supply chains. The Southeast and Southwest regions host integrated delivery networks that standardize formulary around single-source tablet suppliers.
Germany
Cereal and flour producers reformulate with ferrous fumarate powder to meet EFSA-backed iron fortification guidelines in processed foods. EMA's revised iron supplementation safety thresholds in pregnancy force label claim revisions across European nutraceutical applications. Bavaria and North Rhine-Westphalia anchor contract manufacturing capacity for continuous wet granulation lines serving prenatal supplement brands.
China
Henan province chemical synthesis facilities achieve higher elemental iron yields through optimized fumaric acid reaction kinetics. NMPA oversight and GB standards compliance requirements filter substandard API production from export channels. The province hosts over sixty percent of global fermentation and chemical synthesis capacity, exposing buyers to regional environmental shutdown risks.
India
Generic manufacturers expand procurement of pharmaceutical-grade ferrous fumarate for anemia therapeutics amid tightening CDSCO purity mandates on dissolution and bioequivalence. Western India houses cost-optimized bulk powder export operations competing on volume scale. Maharashtra and Gujarat cluster API qualification laboratories struggling to recruit analytical chemistry talent for USP heavy metal testing.
Nigeria
WHO-backed flour fortification initiatives create institutional procurement channels for food-grade ferrous fumarate powder with reduced qualification burdens compared to pharmaceutical specifications. Pediatric anemia programs specify liquid formulations for distribution through primary health centers. Lagos and Abuja anchor distribution networks reaching northern grain-producing regions.
Ferrous Fumarate Market Vendor Landscape
Capability concentration sits with European pharmaceutical developers holding therapy-specific regulatory dossiers; scale advantage sits with Chinese chemical synthesis operations feeding bulk powder export markets. The vendor base stratifies across three tiers: multinational nutrition houses with backward integration into mineral premix formulation, mid-size API specialists serving generic drug manufacturers, and regional chemical exporters competing on cost-optimized fermentation output. Consolidation pressure runs through hospital GPO contracting and dual-source procurement mandates that disqualify single-facility suppliers.
Among European pharmaceutical developers, Vifor Pharma and Galenica Group occupy positions anchored in iron deficiency therapy portfolios. DSM Nutritional Products represents the nutrition house archetype with captive supply chain control over mineral premix operations. At the bulk manufacturing end, Allied Biochem Pvt. Ltd. and Henan Sinotech Import & Export Corporation exemplify regional specialists serving cost-sensitive export markets. These named entities illustrate competitive positioning without exhausting the full participant roster.
| Leading Market Players |
|---|
| Vifor Pharma |
| Ironwood Pharmaceuticals |
| Galenica Group |
| Allied Biochem Pvt. Ltd. |
| Lonye Technology Limited |
| Shreeji Industries |
| Henan Sinotech Import & Export Corporation |
| Particle Dynamics International |
| DSM Nutritional Products |
| Others |
Supply Flow & Price Mechanics
Henan province's concentration of over sixty percent of global ferrous fumarate fermentation and chemical synthesis capacity positions Chinese bulk manufacturers to capture upstream margin pools, while downstream pricing power concentrates with European pharmaceutical developers holding therapy-specific regulatory dossiers and hospital GPOs consolidating procurement through direct manufacturer contracts.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical-grade ferrous fumarate procurement, with hospital GPOs in Texas and Florida securing extended payment terms that compress supplier margins. Price differentiation separates USP/EP-certified pharmaceutical-grade material from food-grade and feed-grade variants, with certification level and volume scale as primary drivers. Pricing pressure stems from ferrous bisglycinate substitution in premium prenatal segments, forcing cost compression in standard tablet formulations. Generic drug manufacturers in India demonstrate highest price sensitivity, while European nutraceutical brands absorb premiums for EMA-compliant split-dose formulations.
Supply Chain Analysis
Reduced iron feedstock and fumaric acid reagents anchor upstream dependencies, with mineral ore quality directly affecting heavy metal contamination risks that force continuous batch testing. Manufacturing concentrates in China, India, and Switzerland, with Henan province facilities feeding bulk powder export markets and Western India operations competing on cost-optimized fermentation output. Single-source vulnerability runs through Henan environmental shutdown exposure, where regional regulatory actions can disrupt sixty percent of global capacity. Distribution runs through direct manufacturer-to-institution contracts for hospital systems, while traditional pharmaceutical wholesalers retain relevance only in fragmented pharmacy markets lacking GPO consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
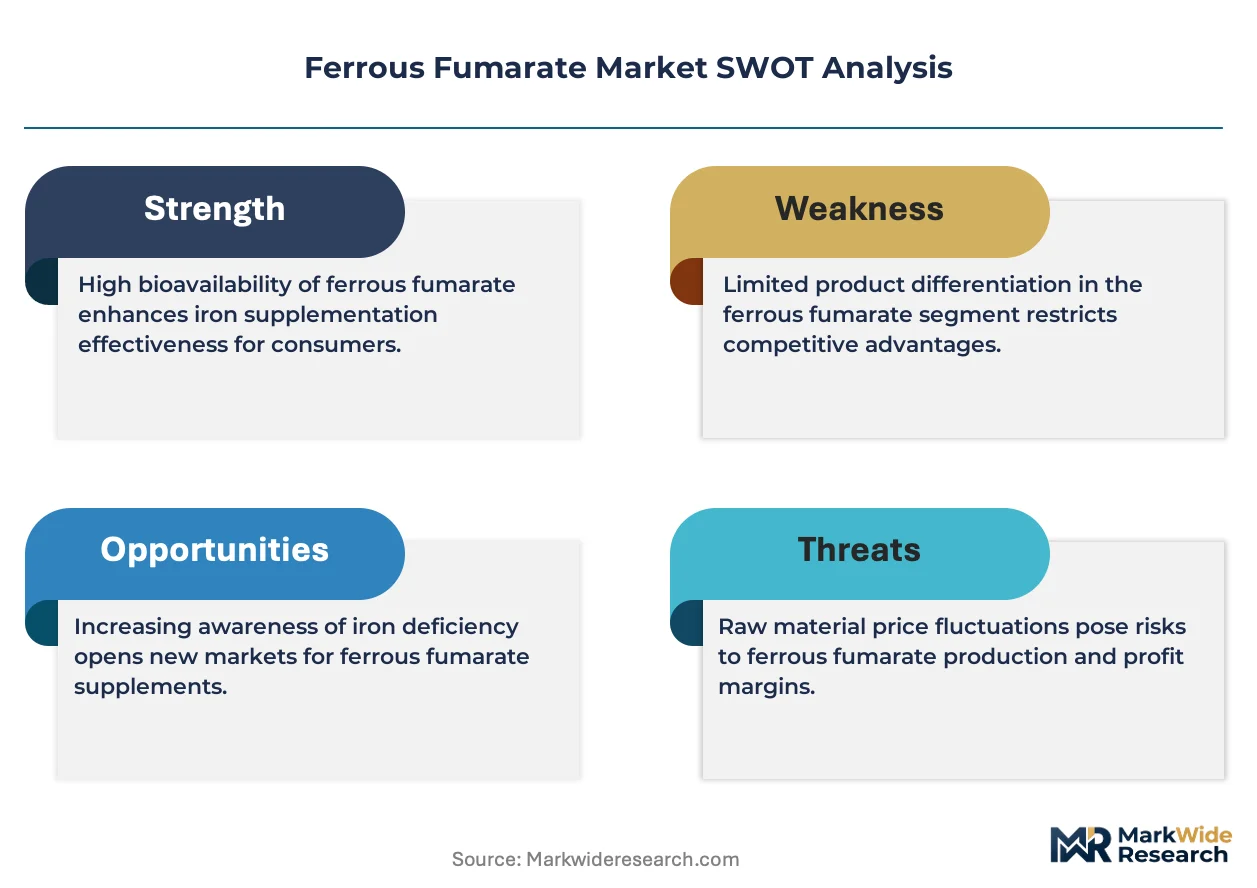
Ferrous fumarate markets reward regulatory entrenchment, where CDSCO bioequivalence dossiers and FDA cGMP inspection histories create switching costs that lock hospital formularies and disqualify new supplier qualification.
For Market Incumbents: Entrench position through backward integration into mineral premix formulation and captive analytical chemistry capabilities, addressing talent scarcity that constrains Western India and Central China competitors. Expand USP-EP pharmacopeial harmonization advocacy to reduce dual-registration burdens for multi-territory suppliers. Defend against ferrous bisglycinate substitution by accelerating continuous manufacturing adoption that compresses batch cycle times and enables real-time release testing. For New Entrants and Emerging Players: Pursue white-space opportunities in Sub-Saharan flour fortification programs, where WHO-backed initiatives in Nigeria and Kenya create institutional procurement channels with reduced qualification burdens compared to pharmaceutical specifications. Target food-grade powder segments as the most penetrable entry point, bypassing CDSCO and FDA cGMP barriers that protect prescription-grade incumbents. Establish direct-to-clinic distribution partnerships that bypass entrenched wholesale networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-size API specialists serving generic drug manufacturers, where CDSCO tightening and hospital GPO consolidation create exit pressure for owners seeking liquidity. Long-term viability favors platforms with dual-source manufacturing footprints spanning Indian and Chinese production to mitigate Henan concentration risk. Monitor USP-EP pharmacopeial harmonization progress as the critical inflection signal for margin expansion in multi-territory suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | European contract manufacturers adopting integrated roller compaction lines reduce excipient segregation and moisture-induced degradation in hematinic tablets. |
| Backward Integration into Mineral Premix | DSM Nutritional Products anchors competitive position through captive supply chain control over iron source qualification and formulation. |
| Dual-Source Manufacturing Footprint | Suppliers spanning Indian and Chinese production mitigate Henan province environmental shutdown concentration risk. |
| Direct-to-Clinic Distribution Partnership | Hospital GPOs in Texas and Florida bypass traditional pharmaceutical distributors through e-procurement platform consolidation. |
| Pharmacopeial Harmonization Advocacy | Aligned USP-EP heavy metal limits reduce dual-registration testing burdens for suppliers seeking multi-territory product approvals. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA cGMP inspection records, CDSCO bioequivalence submission databases, EMA guideline revisions, and USP monograph updates. Interviews with API manufacturing plant managers, pharmaceutical procurement leads at hospital GPOs, regulatory affairs directors, and hematinic formulation scientists inform supply chain and pricing dynamics. Bottom-up volume estimates from facility-level production data triangulate against top-down market sizing derived from customs trade flows and pharmaceutical import records.
Forecast inputs span pharmaceutical-grade versus food-grade specification tiers, tablet versus powder formulation splits, hospital versus pharmacy distribution channels, and regional regulatory cluster adoption patterns. CAGRs derive from segmented growth rate analysis applied across the projection horizon, with pharmaceutical applications modeled against anemia prevalence trends and fortification programs tracked against WHO institutional procurement commitments. Iron ore feedstock cost volatility and fumaric acid supply availability enter as sensitivity variables.
Sensitivities concentrate around CDSCO dissolution mandate enforcement intensity, Henan province environmental regulatory actions, and EFSA fortification guideline revision timing. Cross-checking against hospital GPO contract award databases and pharmaceutical import customs records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Bone Supplements Market