
 IP DECT Phones Market | 2026-2036
IP DECT Phones Market Size, Share, and Industry Trends Forecast 2026-2036
IP DECT Phones Market Outlook
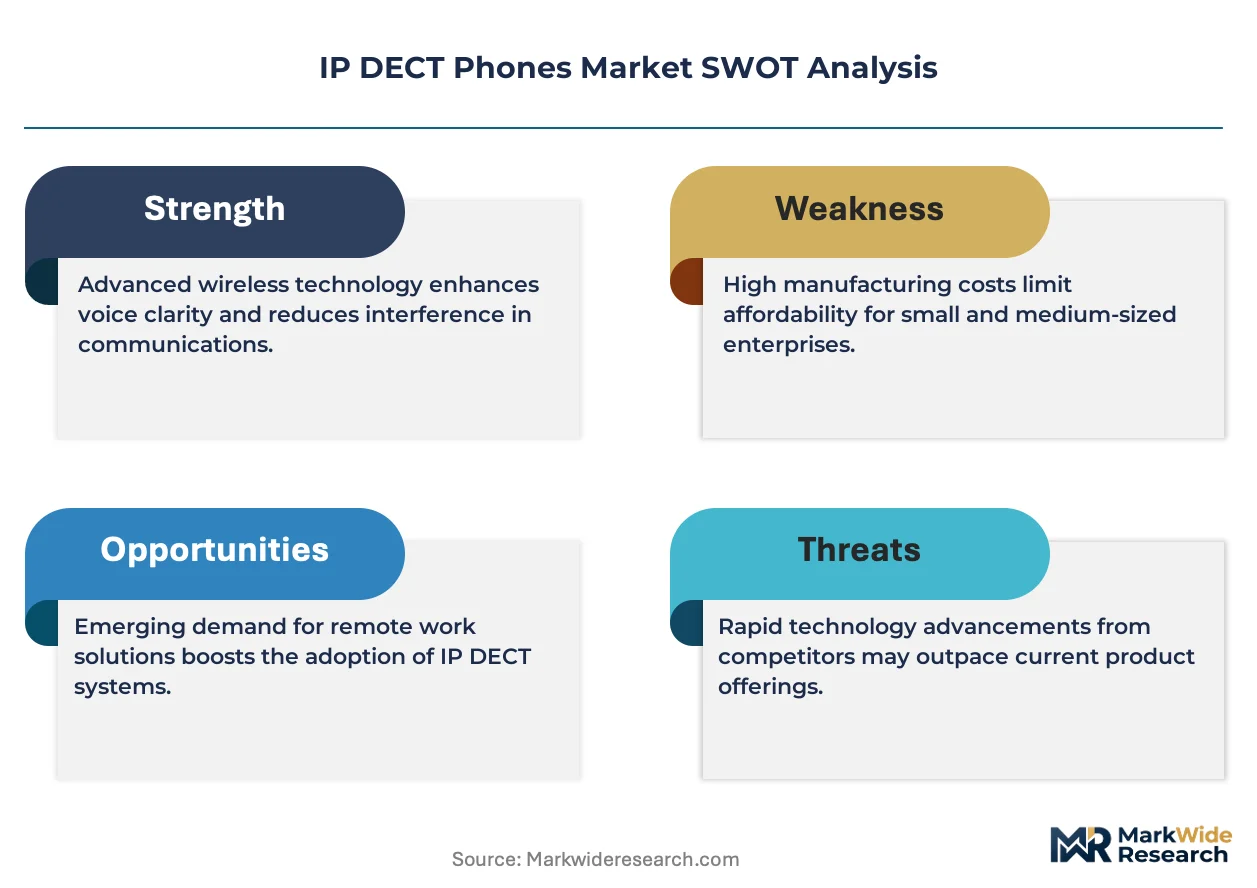
Healthcare is pivoting toward dedicated wireless handsets for nurse call integration and patient room mobility. Panasonic Corporation leverages its audio engineering heritage to sustain premium positioning in base station hardware. Yealink competes aggressively on price-performance ratios for SME cloud deployments. Gigaset Communications anchors European manufacturing with in-house production of DECT protocol chipsets.
IP DECT phones are cordless telephony endpoints that register to VoIP networks via SIP protocol, operating in the 1.9 GHz frequency band with G.722 wideband audio codec support for HD voice quality. Their primary commercial purpose is to deliver wireline-grade call clarity with wireless mobility across office floors, hospital wards, and residential complexes. Wireless handset configurations capture the largest revenue pool among product types as enterprises prioritize user mobility over fixed base station density. Cloud-based deployment models are expanding fastest as IT departments offload PBX maintenance to hosted platforms. SME end users represent the most contested segment, with vendors racing to bundle managed provisioning tools that reduce on-site technical requirements.
FCC Part 15 rules govern unlicensed spectrum operation in the United States, while ETSI EN 301 406 defines European DECT interoperability standards, and Japan's TELEC certification imposes additional RF emission constraints for imports. These frameworks shape product design cycles, regional SKU fragmentation, and certification cost structures that favor established manufacturers with dedicated compliance teams. Stakeholders must monitor spectrum reallocation debates and SIP security mandate expansions as governments tighten critical communication infrastructure protections.
Market Dynamics
The migration from on-premise PBX systems to cloud-hosted voice platforms is compressing hardware refresh cycles and forcing base station manufacturers to bundle managed provisioning tools directly into firmware. This shift privileges vendors with software engineering depth over pure hardware specialists.
Growth Catalysts
- EU Radio Equipment Directive:Harmonized electromagnetic compatibility standards reduce SKU fragmentation across member states, lowering certification overhead for multi-country deployments.
- Nurse call integration:Healthcare facilities in Germany and the Netherlands are mandating wireless handset interoperability with patient monitoring systems, creating pull for SIP-native DECT endpoints.
- G.722 wideband codec adoption:HD voice quality specifications in enterprise RFPs are displacing narrowband legacy systems, favoring hardware with dedicated audio DSPs.
Market Restraints
- Silicon supply concentration:DECT protocol chipsets rely on a limited number of European foundry partners, exposing lead times to geopolitical friction.
- Wi-Fi 6E substitution:Dual-band enterprise wireless LANs are capturing voice traffic that previously required dedicated DECT infrastructure, particularly in greenfield office builds.
- FCC Part 15 spectrum congestion:Unlicensed 1.9 GHz operation faces interference from adjacent industrial IoT deployments in dense urban US markets.
Strategic Opportunities
- India's Smart Cities Mission:Municipal infrastructure projects are specifying wireless intercom systems for public housing, opening a greenfield segment for cost-optimized handsets.
- CE-RED cybersecurity mandates:Upcoming radio equipment security requirements will obsolete non-compliant legacy inventory, creating replacement demand.
- Bluetooth-DECT convergence:Hybrid chipsets enabling seamless handoff between cellular, DECT, and short-range wireless are unlocking mobile workforce use cases.
Industry Challenges
- SIP security certification timelines:TLS 1.3 and SRTP mandate compliance for healthcare deployments is extending product validation cycles by four to six months.
- Legacy analog integration:Hybrid environments requiring simultaneous support for TDM and IP trunking are complicating firmware architecture and QA matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP DECT Phones Market |
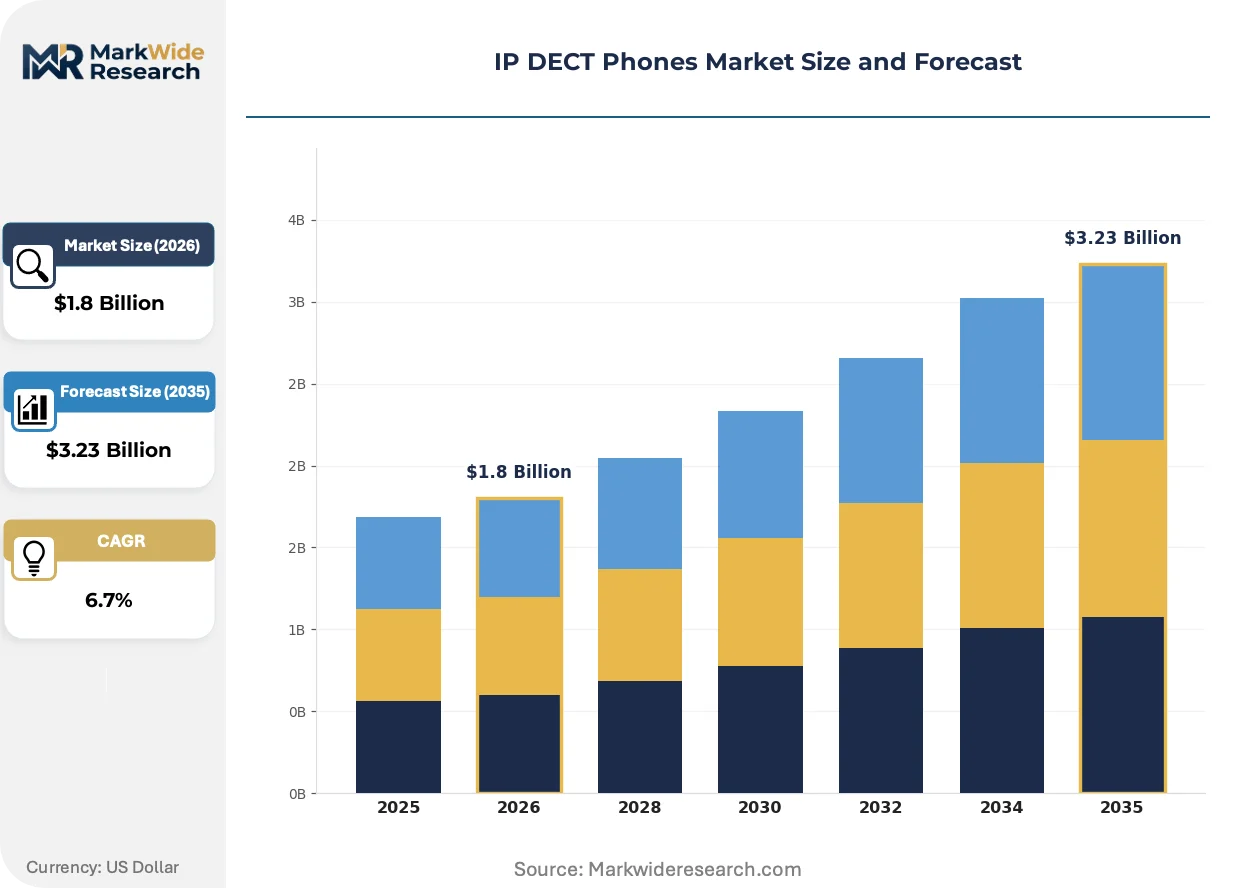
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Handset, Base Station, Repeaters, Accessories Connectivity: Wi-Fi, LAN, Bluetooth, USB End User: Residential, SMEs, Large Enterprises, Healthcare Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | BT, Motorola, Panasonic Corporation, Yealink, Grandstream, Gigaset Communications, Alcatel, Mitel, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP DECT Phones Market Strategic Shifts
Edge computing architectures are redistributing voice processing intelligence away from centralized servers, altering how base stations handle signaling and media streams. This architectural pivot favors hardware vendors with embedded software capabilities.
Multi-cell DECT roaming is decentralizing call control across distributed base station meshes, eliminating single points of failure in large facilities. Hospital networks in Scandinavia are deploying these architectures to support uninterrupted clinician mobility across campus environments. The technology is compressing infrastructure redundancy costs while raising software complexity for handset firmware.
ETSI EN 301 406 interoperability testing is tightening certification requirements for cross-vendor handset-base station pairing, particularly for advanced features like seamless handover. Manufacturers must now submit to third-party conformance labs before CE marking, extending time-to-market for new product families. German enterprise buyers are prioritizing certified interoperability in RFP scoring, disadvantaging unverified imports.
Subscription-based hardware provisioning is displacing perpetual license models for SME cloud telephony deployments. IT departments in France and Benelux markets are offloading firmware management to service providers in exchange for per-seat monthly fees. This shift concentrates purchasing authority with hosted PBX operators rather than end-user organizations.
IP DECT Phones Market Segmentation
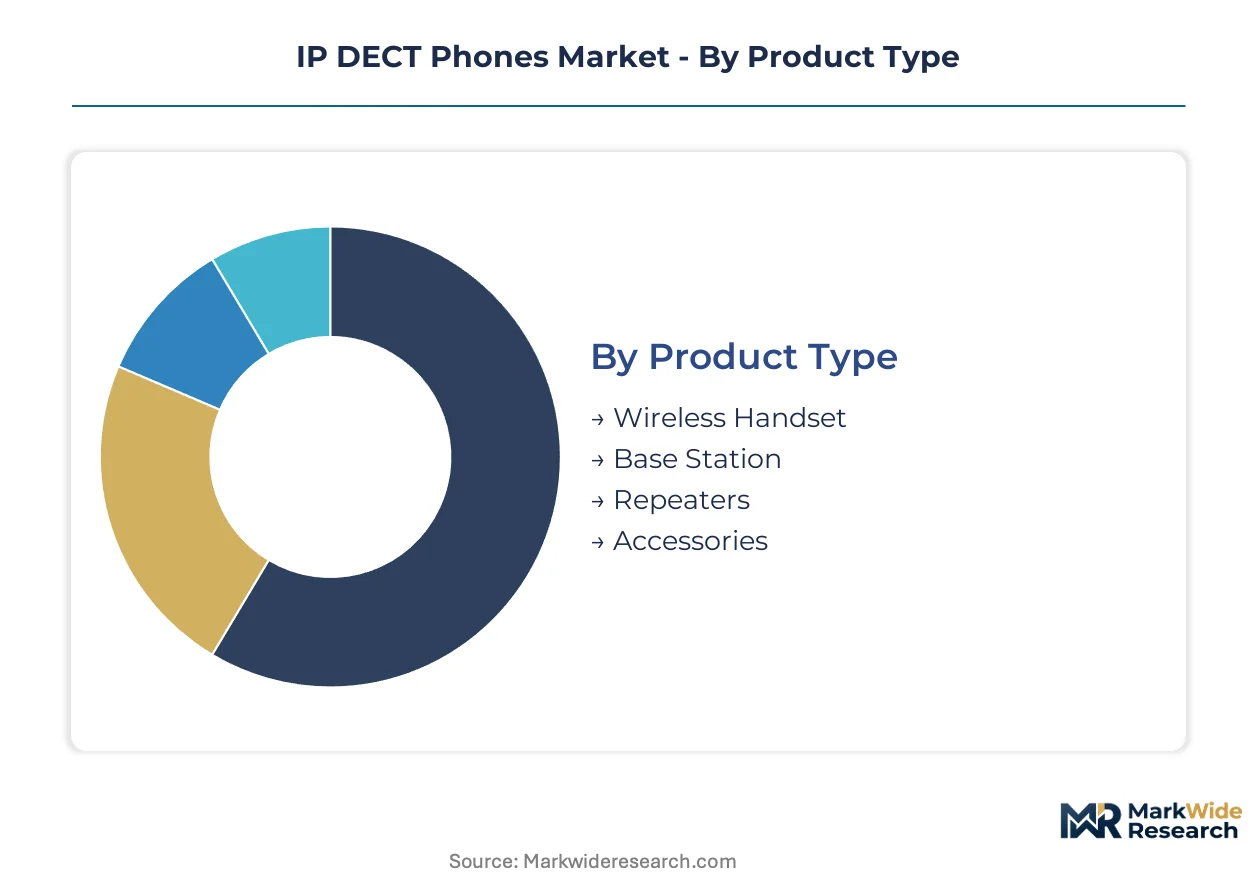
Segmentation in IP DECT phones reveals how purchasing logic splits between infrastructure buyers seeking wireless coverage density and endpoint buyers prioritizing user mobility. The four category framework—product type, connectivity, end user, and deployment model—maps directly onto decision-maker roles from facilities managers to IT directors.
Product Type:
Volume concentrates in endpoint hardware while premium margins attach to infrastructure components that anchor network reliability.
- Wireless Handset:Portable SIP endpoints with G.722 codec support and DECT roaming capability. Demand clusters in German hospital networks where nurse call integration mandates drive bulk procurement of clinical-grade handsets with antimicrobial housings.
- Base Station:Fixed access points managing radio resource allocation and handset registration across cellular coverage zones. Large enterprise campuses in the Netherlands prioritize multi-cell deployments with seamless handover for warehouse and logistics mobility.
- Repeaters:Signal amplification nodes extending DECT coverage into RF-shadowed building zones such as elevator shafts and underground parking structures.
- Accessories:Charging cradles, belt clips, and protective cases generating aftermarket revenue streams with lower technical barriers to entry.
Mature deployment sits with base station infrastructure. Newer deployment is concentrated in wireless handset refresh cycles driven by HD voice mandates.
Connectivity:
Backhaul architecture determines whether voice traffic rides dedicated DECT spectrum or converges onto shared enterprise LAN infrastructure.
- Wi-Fi:Dual-radio handsets bridging DECT voice with 802.11 data services. SME buyers in France favor converged endpoints that reduce device count for mobile workers.
- LAN:Ethernet-tethered base stations providing deterministic latency for call control signaling. German manufacturing plants specify wired backhaul to isolate voice from production network traffic.
- Bluetooth:Short-range pairing enabling proximity-based features such as automatic handset login when entering base station range.
- USB:Peripheral connectivity for PC-based softphone integration and firmware provisioning in managed service deployments.
LAN backhaul dominates established enterprise installations. Wi-Fi convergence is climbing fastest among cloud-telephony adopters seeking infrastructure simplification.
End User:
Customer scale fragments purchasing authority between centralized IT procurement and distributed departmental budgets.
- Residential:Single-base consumer installations with basic call features and limited handset expansion. European retail channels in Germany and the Netherlands stock self-install bundles with plug-and-play provisioning.
- SMEs:Multi-handset deployments with hosted PBX integration and web-based management portals. French IT resellers compete aggressively on per-seat monthly pricing with zero upfront hardware costs.
- Large Enterprises:Campus-wide multi-cell systems requiring centralized provisioning and LDAP directory integration. Scandinavian hospital networks demand site-wide roaming with 99.999% availability SLAs.
- Healthcare:Clinical-grade endpoints with IEC 60601 medical electrical safety certification and EMR system interoperability. German procurement frameworks mandate nurse call integration and antimicrobial surface treatments.
Large enterprise accounts anchor professional services revenue. Healthcare represents the steepest expansion trajectory as clinical workflow digitization accelerates wireless handset deployment.
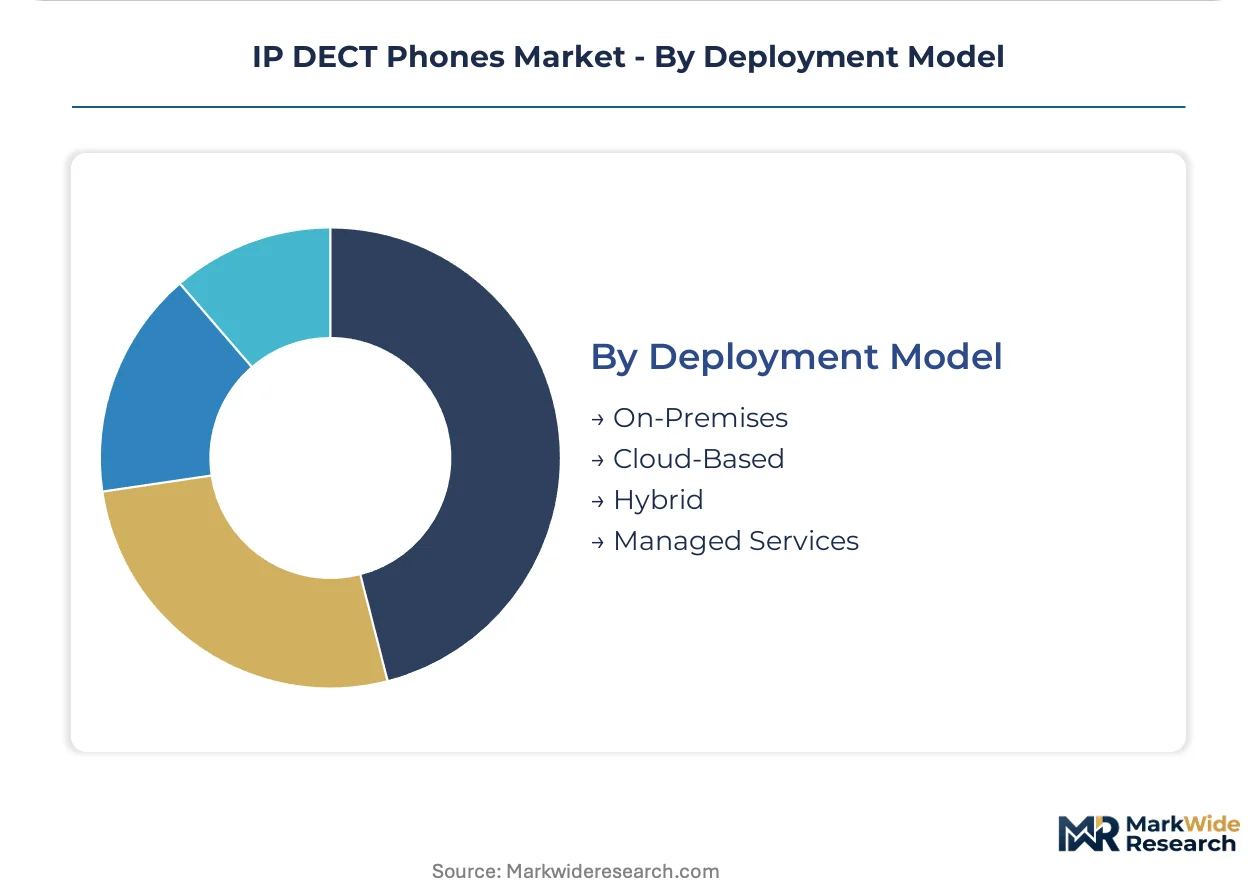
Deployment Model:
Operational responsibility shifts between customer IT staff and external service providers based on capital preference and technical staffing constraints.
- On-Premises:Customer-owned PBX infrastructure with internal IT managing firmware updates and capacity planning. German automotive suppliers maintain legacy Siemens and Avaya integrations requiring hybrid TDM-IP trunking.
- Cloud-Based:Hosted voice platforms with zero on-site server footprint and automatic feature updates. Benelux SMEs are migrating fastest as IT departments offload maintenance overhead to service providers.
- Hybrid:Split architectures preserving on-site call control for local survivability while trunking to cloud services for geographic redundancy.
- Managed Services:Full outsourcing encompassing hardware provisioning, monitoring, and break-fix support under fixed monthly fees.
On-premises deployment retains installed base concentration. Cloud-based models are gaining share fastest as subscription economics displace capital expenditure cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters for enterprise telephony equipment concentrate procurement authority in Düsseldorf and Stuttgart corridors. Benelux cloud-telephony adoption accelerates hosted voice migration among SMEs seeking zero on-site infrastructure. Healthcare digitization mandates across Scandinavia drive clinical-grade handset deployment with nurse call integration.
United States
FCC Part 15 rules govern unlicensed 1.9 GHz spectrum operation for DECT endpoints, with Part 68 terminal equipment registration requirements shaping import compliance. Dense urban markets face spectrum congestion from adjacent industrial IoT deployments. Dallas-Fort Worth hosts enterprise voice distribution networks serving mid-market cloud PBX adopters.
Germany
The EU Radio Equipment Directive harmonizes electromagnetic compatibility standards, reducing SKU fragmentation for multi-country enterprise deployments. CE-RED cybersecurity mandates approaching implementation will obsolete non-compliant legacy inventory. Manufacturing clusters in North Rhine-Westphalia anchor Gigaset Communications' in-house DECT protocol chipset production.
Netherlands
Healthcare facilities mandate wireless handset interoperability with patient monitoring systems, creating pull for SIP-native DECT endpoints. ETSI EN 301 406 interoperability testing tightens certification for cross-vendor handset-base station pairing. Rotterdam logistics hubs deploy multi-cell roaming systems for warehouse mobility across distributed coverage zones.
France
Subscription-based hardware provisioning displaces perpetual licenses as IT departments offload firmware management to service providers. ANSM clinical communication requirements influence healthcare procurement specifications for antimicrobial handset housings. Paris-region SMEs drive fastest cloud-telephony migration in Western Europe through per-seat monthly pricing models.
India
TRAI regulations on wireless intercom systems shape municipal infrastructure specifications for public housing projects. India's Smart Cities Mission specifies cost-optimized handsets for greenfield wireless deployment. Bangalore IT corridors pilot converged DECT-WiFi endpoints for hybrid office environments.
IP DECT Phones Market Competitive Environment
Top-tier vendors anchor premium hardware tiers, while mid-market specialists compete aggressively on price-performance ratios for SME cloud deployments. The vendor base stratifies across audio engineering heritage, in-house chipset production, and managed provisioning software depth. Two strategic archetypes dominate: vertically integrated European manufacturers with captive DECT protocol capabilities, and Asia-Pacific volume players leveraging cloud-telephony distribution partnerships. Competitive moves concentrate on M&A for SIP security certification capabilities and strategic partnerships with hosted PBX operators.
Within the integrated-manufacturing tier, Panasonic Corporation and Gigaset Communications exemplify divergent geographic anchoring—Japanese audio heritage against European captive chipset production. Yealink occupies a position representing aggressive price-performance competition for cloud-native deployments. These three entities collectively illustrate how vendor strategy fragments across premium audio engineering, regional manufacturing concentration, and SME-focused subscription economics.
| Leading Market Players |
|---|
| BT |
| Motorola |
| Panasonic Corporation |
| Yealink |
| Grandstream |
| Gigaset Communications |
| Alcatel |
| Mitel |
| Philips |
| Others |
Value Chain & Pricing Dynamics
Embedded firmware engineers in Taiwan's Hsinchu Science Park command compensation premiums that widen pricing spreads between premium clinical-grade handsets and economy SME tiers, compressing margins for vendors without captive chipset production.
Pricing Analysis
Short lead-time premiums attach to DECT protocol chipsets sourced from European foundries, while spot inventory of legacy narrowband handsets trades at distressed clearing prices. Pricing stratifies across premium, standard, and economy tiers based on G.722 codec certification and antimicrobial housing specifications. Cost compression in the economy tier stems from Wi-Fi 6E substitution pressure. Healthcare procurement committees show least price sensitivity due to nurse call integration mandates, while French SME resellers compete aggressively on per-seat monthly pricing.
Supply Chain Analysis
Reverse logistics flows for base station refurbishment concentrate in Germany's North Rhine-Westphalia corridor, where Gigaset Communications operates captive remanufacturing facilities for warranty returns and trade-in programs. DECT protocol chipsets draw from German and Taiwanese fabrication partners, with RF frontend components sourced from Japanese suppliers. Single-source vulnerability sits with European foundry capacity for medical-grade certification chipsets. Distribution runs through hosted PBX operators in Benelux and IT resellers in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IP DECT phones market reads as a cost-of-compliance story where CE-RED cybersecurity mandates erect barrier-to-entry moats favoring vendors with dedicated certification teams and in-house testing laboratories.
For Market Incumbents: Acquire SIP security certification capabilities to compress healthcare validation timelines threatened by TLS 1.3 mandate expansion. Consolidate multi-cell roaming software stacks through selective capability purchases, defending against Wi-Fi 6E substitution in greenfield enterprise builds. Channel control through exclusive hosted PBX partnerships anchors recurring revenue streams. For New Entrants and Emerging Players: Launch via India's Smart Cities Mission municipal procurement channels, targeting cost-optimized wireless intercom specifications with stripped-down handset configurations. White-space concentrates in public housing infrastructure where TRAI regulations favor local assembly. Cloud-telephony distribution partnerships in France and Benelux accelerate customer acquisition without field sales overhead. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated European manufacturers given CE-RED cybersecurity mandate implementation, which will obsolete non-compliant legacy inventory and concentrate procurement authority with certified vendors. Acquisition target archetype: mid-scale vendors with in-house DECT protocol chipset production and established healthcare interoperability credentials. Monitor ETSI EN 301 406 interoperability testing queue lengths as inflection indicator for certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| CE-RED Cybersecurity Certification | Upcoming mandates will obsolete non-compliant legacy inventory, creating replacement demand cycles. |
| Multi-Cell Roaming Software Stack | Hospital networks in Scandinavia prioritize campus-wide mobility with 99.999% availability SLAs. |
| Bluetooth-DECT Hybrid Chipset Development | Convergence unlocks mobile workforce use cases with seamless cellular-to-DECT handoff. |
| Hosted PBX Operator Partnership | Subscription economics in France and Benelux concentrate purchasing authority with service providers. |
| India Smart Cities Distribution | Municipal infrastructure projects specify cost-optimized handsets for public housing greenfield deployment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hosted PBX operators, healthcare IT procurement managers, DECT chipset design engineers, and enterprise voice systems integrators. ETSI documentation, FCC Part 15 rulemakings, and TELEC certification databases provided standards validation. Bottom-up handset shipment modeling triangulated against top-down enterprise telephony spend analysis.
Granularity-level modeling disaggregated volume and value across product type, connectivity architecture, end-user scale, and deployment model dimensions throughout the forecast period. CAGRs derived from logistic adoption curve fitting for cloud-telephony migration and replacement cycle compression assumptions. Nurse call integration mandate timelines and Wi-Fi 6E enterprise penetration curves served as industry-specific demand drivers.
Spectrum reallocation debates, SIP security mandate expansion timelines, and foundry capacity utilization rates are the dominant revision risks. Forecasts reflect documented assumptions regarding certification timeline stability and healthcare capital expenditure continuity. Practitioners should monitor ETSI interoperability testing queue lengths, CE-RED implementation enforcement intensity, and European foundry order book visibility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Radio Access Network Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Argentina Telecom Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Bahrain Telecom Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Indonesia Telecom Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Ireland Telecom Market
Telecommunications
Cambodia ICT Market
Telecommunications
Promotional Sms Market