
 United Arab Emirates Telecom Market | 2026-2036
United Arab Emirates Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Telecom Market Analytics
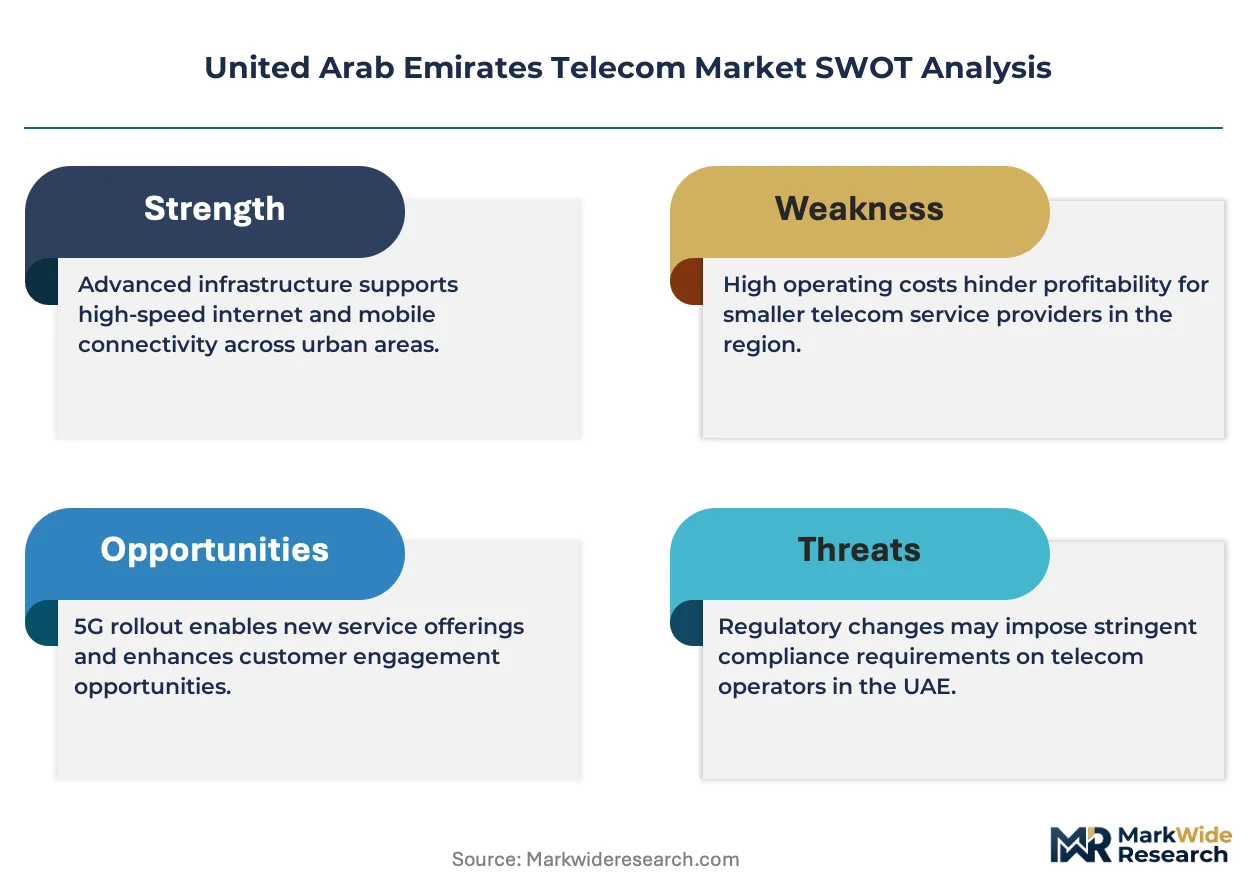
Enterprise cloud communications is pivoting as the fastest-rising vertical in the United Arab Emirates telecom landscape. e& UAE leverages its fiber backbone to dominate enterprise connectivity in Dubai's commercial districts. Emirates Integrated Telecommunications PJSC anchors residential broadband expansion across Abu Dhabi and the northern emirates. Huawei Technologies competes aggressively in 5G infrastructure tenders through localized R&D partnerships.
The United Arab Emirates Telecom sector encompasses mobile, fixed-line, broadband, and satellite services delivered over 5G, fiber optic, and satellite communication architectures with latency thresholds below 10 milliseconds for enterprise-grade applications. Its primary commercial purpose is enabling digital service delivery across government, enterprise, and consumer segments. Mobile services generate the largest revenue pool while 5G technology captures the fastest growth trajectory. Fiber optic infrastructure sustains premium margins in enterprise broadband where latency-sensitive applications command higher service tiers.
TRAI spectrum allocation frameworks and the UAE's national 5G strategy shape infrastructure investment cycles and operator licensing conditions. MOHAP data sovereignty requirements and ISO 27001 certification mandates constrain cross-border data routing and cloud service architecture choices. Stakeholders must monitor evolving spectrum refarming decisions and satellite-terrestrial integration policies to align capital deployment with regulatory timelines.
Market Dynamics
5G standalone rollouts and fiber densification are compressing infrastructure investment cycles across the Emirates. TRAI spectrum refarming timelines and MOHAP data sovereignty mandates force operators to synchronize capital deployment with regulatory windows rather than pure demand signals.
Growth Catalysts
- Enterprise cloud communications:Dubai's commercial districts drive demand for unified communications-as-a-service. Latency-sensitive trading floors and smart building management systems require sub-10 millisecond connectivity.
- Abu Dhabi government digitalization:Federal digitization mandates expand procurement for secure broadband and satellite backup circuits across ministry networks.
- TRAI 5G spectrum frameworks:Predictable licensing conditions reduce regulatory uncertainty and accelerate infrastructure rollout timelines for mobile network operators.
Market Restraints
- Equipment supply concentration:5G radio access network hardware sourcing depends heavily on East Asian manufacturing clusters, exposing operators to geopolitical supply disruptions.
- Skilled technician scarcity:Fiber splicing and millimeter-wave antenna calibration require specialized labor pools that remain underdeveloped in the northern emirates.
- MOHAP data localization:Cross-border routing restrictions force redundant domestic infrastructure investments that inflate operational expenditure baselines.
Strategic Opportunities
- Ras Al Khaimah industrial zones:Underpenetrated manufacturing corridors present greenfield fiber deployment opportunities tied to port automation and logistics parks.
- Satellite-terrestrial convergence:Low-earth orbit integration with 5G core networks enables coverage extension for maritime and desert remote operations.
- Fujairah smart port mandates:Federal trade corridor investments create captive demand for private network slices and edge computing nodes.
Industry Challenges
- Legacy copper decommissioning:Operators face stranded asset write-downs and customer migration friction when retiring aging DSL infrastructure.
- ISO 27001 certification timelines:Enterprise cloud service providers encounter 12-18 month compliance cycles that delay contract commencements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Telecom Market |
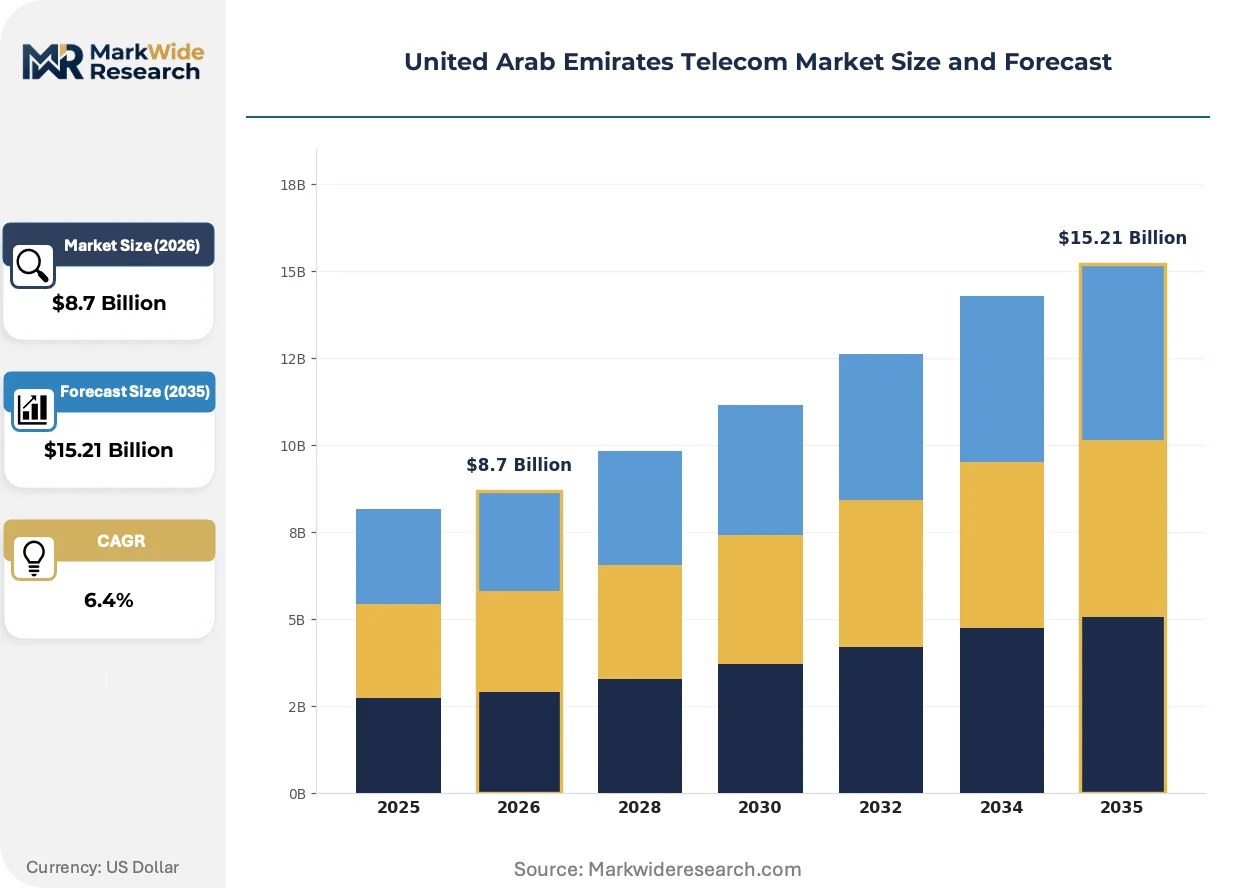
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Broadband Services, VoIP Services Technology: 5G, 4G LTE, Fiber Optic, Satellite Communication End User: Residential, Enterprises, Government, SMBs Customer Type: Individual Users, Corporate Clients, Public Institutions, Tourists |
| Companies Covered | Cisco Systems, Ericsson, e& UAE (Etisalat), Yahsat (Al Yah Satellite Communications Company), Thuraya Telecommunications Company, Emirates Integrated Telecommunications PJSC (du), Nokia Corporation, Inmarsat plc, Huawei Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Telecom Market Evolving Landscape
Network function virtualization and AI-driven traffic management are dissolving traditional hardware-software boundaries in Emirati telecom architecture. These shifts compress equipment refresh cycles while elevating software engineering capabilities.
Open RAN architectures are integrating disaggregated hardware and software components from multi-vendor ecosystems. Emirates mobile operators pilot these deployments in Dubai's dense urban corridors to reduce vendor lock-in and accelerate feature deployment. The structural consequence is integrating cloud-native operational models into radio access networks previously dominated by integrated equipment stacks.
MOHAP data sovereignty requirements and ISO 27001 certification mandates are tightening cross-border data routing constraints. Cloud service providers must architect domestic-only data paths and obtain federal security clearances. Government and healthcare verticals respond by demanding dedicated infrastructure zones with physical segregation from international traffic.
Subscription-based network-as-a-service models are displacing capital-intensive ownership structures among mid-sized enterprises. Dubai's commercial real estate sector leads this transition, procuring managed Wi-Fi and SD-WAN through operational expenditure contracts. Procurement teams in retail and hospitality verticals now prioritize service-level agreements over equipment specifications.
United Arab Emirates Telecom Market Segmentation
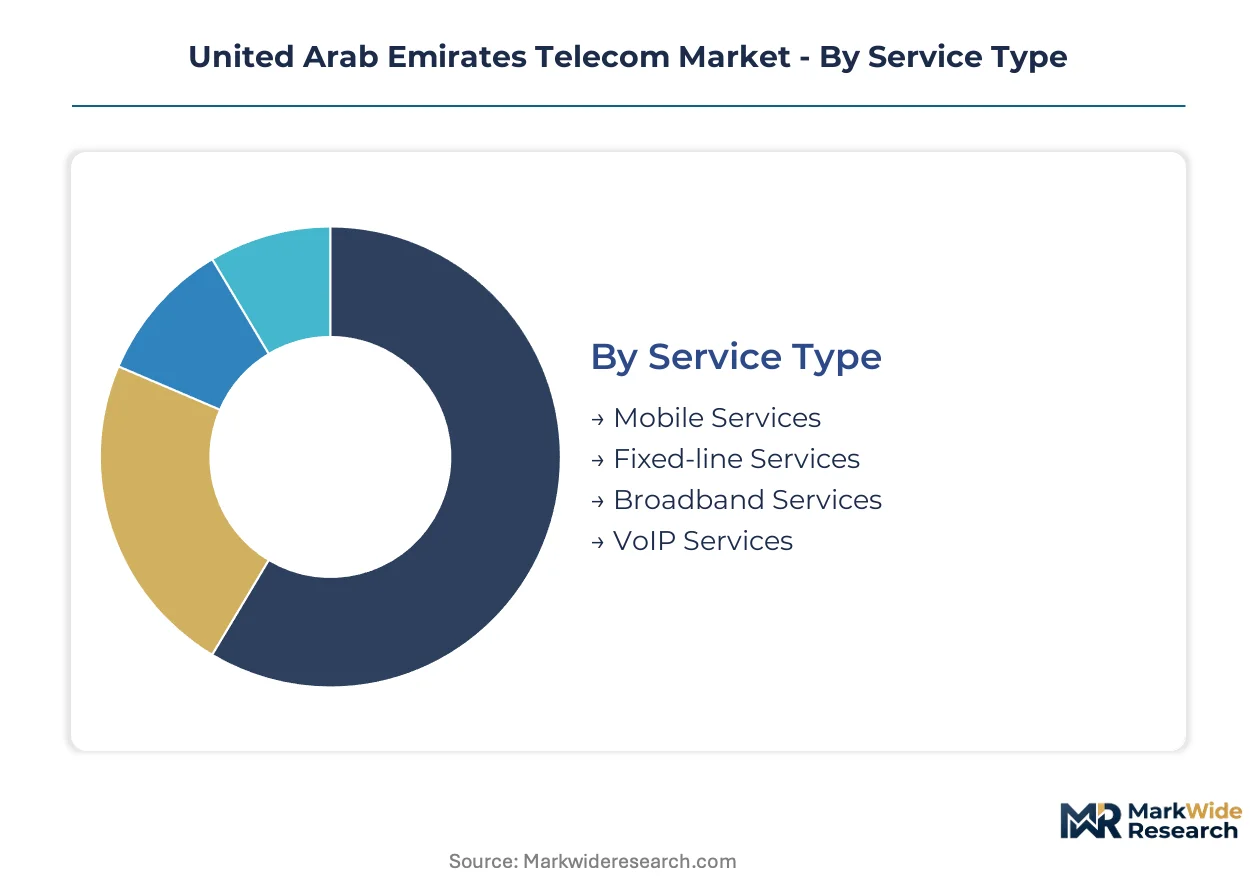
Segmentation in the UAE telecom sector reveals how purchasing power, latency requirements, and regulatory exposure fragment demand across service tiers. Buyers prioritize connectivity reliability, data sovereignty compliance, and total cost of ownership depending on their operational scale and vertical exposure.
Service Type:
Enterprise procurement teams weight service selection against application criticality and uptime guarantees rather than headline bandwidth figures.
- Mobile Services:Voice and data delivery over cellular architectures generates the largest revenue pool through consumer subscriptions and enterprise mobility contracts. Dubai's financial trading floors and logistics corridors drive premium tier adoption where sub-10 millisecond latency commands price premiums.
- Broadband Services:Fixed-line internet access over fiber and copper infrastructure serves residential streaming demands and enterprise cloud connectivity. Abu Dhabi's government digitalization zones and northern emirates residential clusters concentrate procurement volume with MOHAP data localization requirements shaping architecture choices.
- Fixed-line Services:Traditional PSTN voice connectivity persists in legacy government installations and regulated industries requiring circuit-switched reliability.
- VoIP Services:Packet-switched voice delivery over IP networks displaces conventional telephony in cost-sensitive SMB segments and distributed enterprise branches.
Volume sits with Mobile Services; growth tilts toward Broadband Services.
Technology:
Capital deployment cycles and spectrum availability determine which technology layers operators prioritize for infrastructure refresh.
- 5G:New radio access technology operating in sub-6GHz and millimeter-wave bands enables network slicing and ultra-reliable low-latency communication. Dubai's smart city corridor and industrial automation zones in Jebel Ali represent the densest deployment concentration where TRAI spectrum frameworks reduce licensing friction.
- Fiber Optic:Glass-core transmission infrastructure delivering symmetrical gigabit speeds sustains premium margins in enterprise broadband. e& UAE leverages its fiber backbone to dominate commercial district connectivity where latency-sensitive applications require dedicated physical paths.
- 4G LTE:Mature cellular technology provides coverage continuity in suburban and exurban zones pending 5G densification.
- Satellite Communication:Geostationary and low-earth orbit systems extend connectivity to maritime routes and desert remote operations beyond terrestrial infrastructure reach.
Revenue concentrates in Fiber Optic deployments; 5G claims the steepest expansion trajectory.
End User:
Security clearance requirements and procurement authorization thresholds segment buyers into distinct sales motion categories.
- Enterprises:Large organizations with dedicated IT procurement functions demand managed services and service-level agreements spanning unified communications and cloud connectivity. Dubai International Financial Centre tenants and Abu Dhabi sovereign wealth entities anchor contract value with ISO 27001 certification mandates extending sales cycles.
- Government:Federal and emirate-level ministries require secure broadband and satellite backup circuits with domestic-only data routing. Federal digitization mandates expand procurement volume across ministry networks with MOHAP data sovereignty compliance as table stakes.
- Residential:Individual households consuming streaming and gaming services over fixed and mobile broadband.
- SMBs:Small and medium businesses with limited IT staff favor subscription-based network-as-a-service models over capital-intensive ownership.
Contract value aggregates with Enterprises; public sector procurement is expanding most quickly.
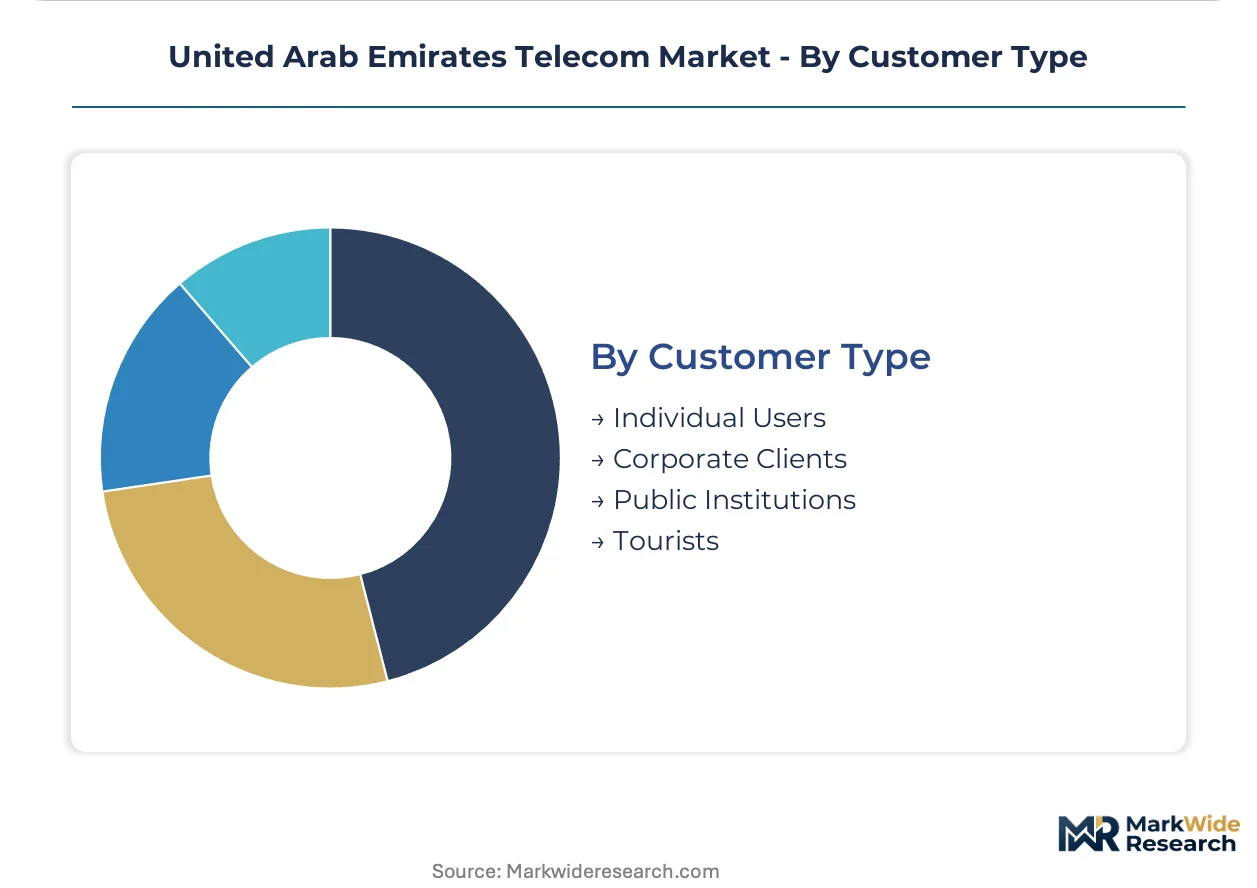
Customer Type:
Duration of stay and billing relationship structure differentiate how operators package and price service access.
- Corporate Clients:Multi-site organizations with centralized procurement negotiate enterprise service agreements covering managed WAN and mobility fleets. Dubai commercial real estate developers and hospitality groups lead adoption of operational expenditure-based network contracts.
- Public Institutions:Government agencies and state-owned enterprises with sovereign guarantee backing purchase through formal tender processes with extended evaluation timelines.
- Individual Users:Citizens and residents subscribing to consumer mobile and broadband plans on monthly or annual terms.
- Tourists:Short-term visitors purchasing prepaid SIM cards and temporary data passes through airport retail and hospitality distribution.
Account density favors Individual Users; revenue per connection climbs fastest with Corporate Clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's free zones and Abu Dhabi's industrial cities concentrate telecom infrastructure investment through tax incentives and streamlined licensing. The UAE's national 5G strategy channels capital toward emirate-level digitalization corridors. TRAI spectrum frameworks coordinate deployment timelines across the federation.
Dubai
Dubai International Financial Centre tenants demand sub-10 millisecond connectivity for algorithmic trading platforms. Dubai Development Authority zoning codes mandate fiber-ready infrastructure in new commercial developments. Smart city deployments in Downtown Dubai and Dubai Silicon Oasis drive dense 5G small cell installations.
Abu Dhabi
Federal ministry digitalization programs expand procurement for secure broadband circuits with domestic-only routing. Abu Dhabi Department of Economic Development incentives attract cloud service providers to Masdar City and Khalifa Industrial Zone. Government sovereign wealth entities anchor enterprise contract value with extended ISO 27001 compliance cycles.
Sharjah
Sharjah Research Technology and Innovation Park anchors demand for research network infrastructure and educational broadband. Sharjah Commerce and Tourism Development Authority streamlines telecom licensing for hospitality and retail verticals. University City clusters concentrate fiber deployment serving academic and research institutions.
Northern Emirates
Ras Al Khaimah Economic Zone and Fujairah Port Authority investments create captive demand for industrial automation networks. Federal transport corridor mandates require private 5G slices for logistics and maritime operations. Skilled technician scarcity in fiber splicing and antenna calibration constrains deployment velocity in these zones.
United Arab Emirates Telecom Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated operators controlling infrastructure layers and equipment vendors competing for 5G deployment contracts. The market structure concentrates around three archetypes: legacy telecom operators with fiber backbones, satellite communications providers serving remote operations, and multinational equipment vendors licensing radio access technology. Competitive moves center on spectrum acquisition positioning and strategic partnerships with government digitalization programs.
Among UAE-based operators, e& UAE and Emirates Integrated Telecommunications PJSC occupy positions as integrated service providers with established fiber footprints. Huawei Technologies exemplifies the equipment vendor archetype competing through localized R&D partnerships. These three entities represent the dominant competitive anchors shaping procurement dynamics across Dubai's commercial districts and Abu Dhabi's government networks.
| Leading Market Players |
|---|
| Cisco Systems |
| Ericsson |
| e& UAE (Etisalat) |
| Yahsat (Al Yah Satellite Communications Company) |
| Thuraya Telecommunications Company |
| Emirates Integrated Telecommunications PJSC (du) |
| Nokia Corporation |
| Inmarsat plc |
| Huawei Technologies |
| Others |
Value Network & Pricing Analysis
Enterprise procurement teams in Dubai's financial and commercial districts anchor pricing power for telecom operators, with subscription-based network-as-a-service models displacing capital-intensive ownership structures across mid-market segments. This buyer concentration compresses margins on standardized connectivity while enabling premium capture for latency-guaranteed service tiers.
Pricing Analysis
Short lead-time deployments command substantial premiums in Dubai's dense commercial corridors where trading floors and smart building systems require sub-10 millisecond connectivity on accelerated timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies enterprise broadband, with ISO 27001 certification tiers and dedicated physical fiber paths driving differentiation. Cost compression in standard-tier mobile data is intensifying because of equipment supply concentration from East Asian manufacturing clusters. SMB segments exhibit highest price sensitivity, favoring operational expenditure contracts over capital-intensive infrastructure ownership.
Supply Chain Analysis
Freight and logistics costs for 5G radio access network hardware hinge on maritime routing through East Asian manufacturing clusters in China, South Korea, and Japan. Radio frequency components, fiber optic cable, and millimeter-wave antenna arrays draw from specialized production facilities concentrated in these jurisdictions. Single-source vulnerability in semiconductor chipsets for baseband units exposes operators to geopolitical disruption. Distribution runs through operator-direct procurement with equipment vendors and systems integrators serving government and enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE telecom market is consolidating around operators with fiber backbone density and government security clearances, with MOHAP data sovereignty mandates forcing smaller cloud service providers into compliance investments that strain capital reserves.
For Market Incumbents: Extend fiber densification into Ras Al Khaimah industrial zones and Fujairah port corridors before regulatory windows close. Deepen vertical integration into edge computing infrastructure to capture private network slice demand from maritime and logistics operators. ISO 27001 certification investments anchor government contract retention against emerging cloud-native competitors. For New Entrants and Emerging Players: Systems integrators with federal security clearances represent the most viable channel partnership path for satellite-terrestrial convergence offerings targeting desert remote operations. Underpenetrated manufacturing corridors in the northern emirates offer white-space entry with lower incumbent density than Dubai's saturated commercial districts. Position around managed Wi-Fi and SD-WAN subscription models to bypass capital-intensive infrastructure build requirements. For Investors and Strategic Acquirers: The window for entry favors cloud-native software vendors with AI-driven traffic management capabilities and existing MOHAP compliance frameworks. Long-term viability centers on 5G core network virtualization plays that reduce hardware dependency and accelerate feature deployment cycles. Monitor TRAI spectrum refarming announcements as inflection indicators for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Acquisition Positioning | TRAI licensing frameworks reward early movers with predictable deployment timelines in dense urban corridors. |
| Fiber Backbone Extension | e& UAE leverages existing infrastructure to dominate latency-sensitive enterprise connectivity in Dubai's financial districts. |
| Cloud-Native Operational Model | Open RAN pilots in Dubai Silicon Oasis reduce vendor lock-in and compress equipment refresh cycles. |
| Data Sovereignty Compliance Investment | MOHAP mandates create defensive moats for providers with domestic-only routing architecture and federal security clearances. |
| Satellite-Terrestrial Integration | Low-earth orbit partnerships extend coverage to maritime routes and desert operations beyond terrestrial infrastructure reach. |
Research Methodology
Regulatory filings from TRAI, MOHAP policy documents, and operator spectrum auction records formed the secondary backbone for market sizing and infrastructure deployment tracking. Primary interviews with network engineering directors at mobile operators, enterprise IT procurement managers in Dubai International Financial Centre, government digitalization program leads, and satellite communications specialists triangulated demand signals against secondary validation. Bottom-up service revenue modeling and top-down macroeconomic anchoring converged on segment-level estimates.
Historical trendline analysis of capital expenditure cycles and subscriber growth patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, technology layer, end-user vertical, and customer relationship structure. CAGRs were derived from regression analysis of infrastructure investment timelines and regulatory milestone schedules, with 5G standalone rollout pace and fiber densification velocity as key forecast inputs.
Caveats apply where TRAI spectrum refarming delays, East Asian supply chain disruptions, or MOHAP regulatory revisions could materially shift the outlook. Forecasts reflect documented assumptions about infrastructure deployment timelines and enterprise adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE Base Station System Market
Telecommunications
Oman Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Thailand Telecom Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Philippines Telecom Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Telecom API Platform Market
Telecommunications
Global GPON Technology Market
Telecommunications
Russia Telecom Market
Telecommunications
IP DECT Phones Market
Telecommunications
Utility Communications Market
Telecommunications
Vietnam Telecom Market
Telecommunications
France Telecom Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Diameter Signaling Control Market