
 Refrigerated Warehousing Market | 2026-2036
Refrigerated Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Warehousing Market Analysis
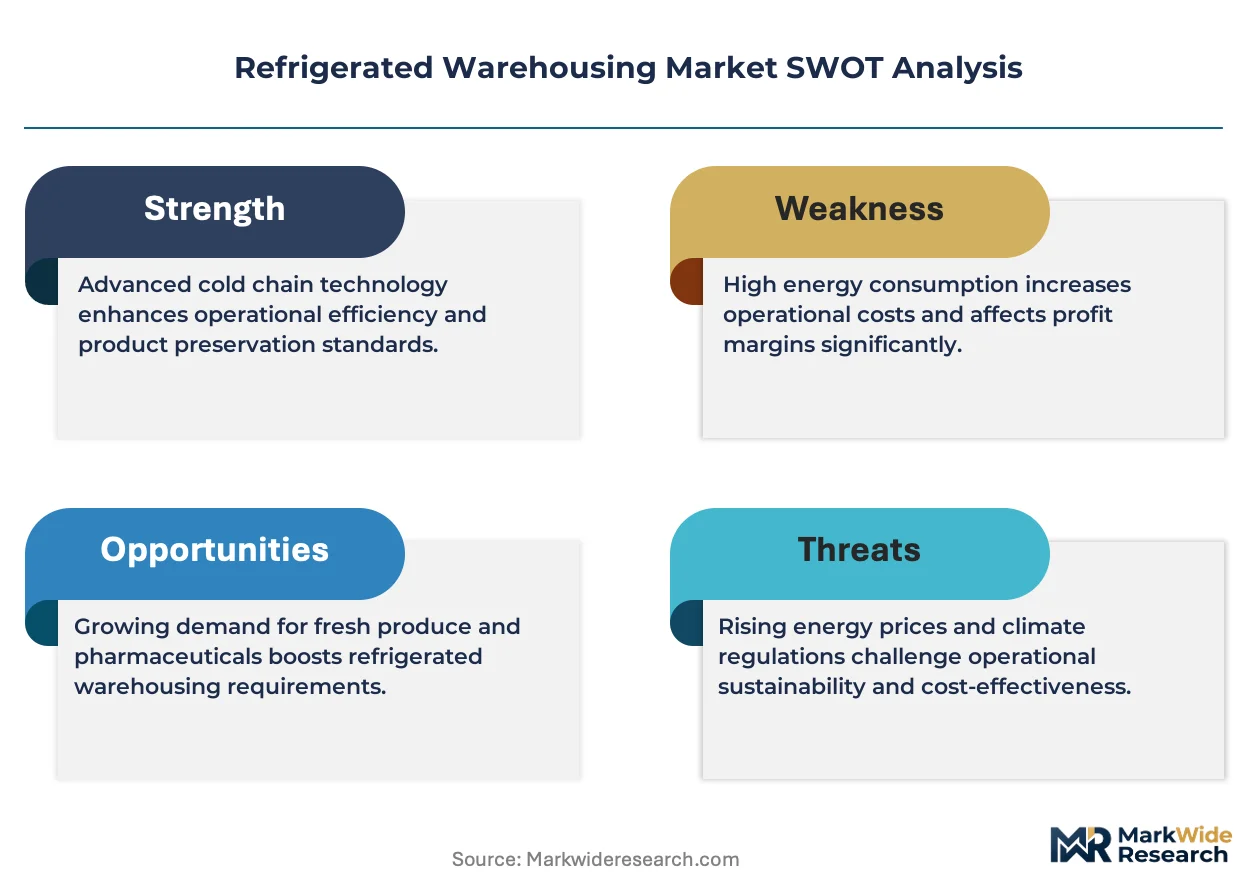
North American third-party cold storage capacity is broadening as protein exporters and dairy processors seek temperature-controlled buffer stock. Lineage Logistics leverages automated high-bay AS/RS architecture to sustain throughput density in port-adjacent facilities. Americold Logistics anchors domestic protein distribution through its integrated rail and drayage network. NewCold competes on energy efficiency with its fully automated European-designed deep-freeze campuses.
Refrigerated warehousing denotes climate-controlled facilities engineered to maintain perishable goods within precise temperature bands, typically spanning minus 25 degrees Celsius for frozen proteins to plus 15 degrees Celsius for pharmaceutical stability chambers, utilizing vapor-compression or emerging CO2 transcritical refrigeration cycles. These facilities function as critical nodes in temperature-sensitive supply chains, preventing microbial proliferation and preserving biochemical potency from production through last-mile delivery. Frozen storage occupies the dominant share of installed pallet positions globally, reflecting the structural dominance of meat, seafood, and processed food inventories. Automated storage and retrieval systems represent the fastest-growing technology segment, as labor scarcity and throughput requirements push operators toward robotic crane systems and WMS-integrated control platforms.
The EPA's Significant New Alternatives Policy program governs refrigerant transitions in US facilities, while the EU F-Gas Regulation mandates phased HFC reductions that compel ammonia and CO2 system investments across European cold chain networks. India's BIS energy efficiency standards for cold storage equipment are tightening compliance thresholds for new warehouse construction permits. Stakeholders must monitor refrigerant transition timelines and automation capital cycles to align facility investments with evolving regulatory baselines and throughput economics.
Market Dynamics
The EU F-Gas Regulation is compressing hydrofluorocarbon refrigerant availability and forcing a wholesale equipment transition across European cold storage networks. This single mandate is cascading through capital planning cycles, retrofit timelines, and technology procurement decisions.
Growth Catalysts
- Biologics cold chain integrity:Pharmaceutical manufacturers require minus 70 to plus 8 Celsius stability corridors for mRNA vaccines and cell therapies. FDA validation protocols now mandate continuous temperature logging.
- India PLI scheme for food processing:Government production-linked incentives are subsidizing cold storage buildouts for horticulture and dairy cooperatives. Organized retail expansion in tier-2 cities accelerates pallet position demand.
- CO2 transcritical refrigeration:Ammonia-CO2 cascade systems eliminate synthetic refrigerant dependency while delivering energy density for deep-freeze operations. European operators lead adoption curves.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping materials face commodity price swings that compress equipment margin structures. Chinese smelter output fluctuations transmit directly to cold storage capex quotes.
- Sk ammonia system engineering:Specialized industrial refrigeration contractors concentrate in Germany, Denmark, and the Netherlands. Project queues extend 14-18 months for complex cascade installations.
- Legacy HFC asset stranding:Facilities with R-404A or R-507 systems face accelerated depreciation as phasedown timelines tighten. Residual value collapse complicates refinancing for independent operators.
Strategic Opportunities
- Pharmaceutical stability chambers:Biologics manufacturers seek validated plus 15 to plus 25 Celsius environments with redundant HVAC and 24/7 monitoring. This segment commands premium lease rates per pallet position.
- Automated high-bay AS/RS retrofit:Labor scarcity in US Midwest protein processing hubs creates openings for robotic crane integration. WMS-integrated control platforms compress labor cost per throughput unit.
- EU Green Deal financing windows:Cold storage operators accessing Recovery and Resilience Facility grants can defray CO2 system conversion costs. Green bond issuance for certified facilities expands capital access.
Industry Challenges
- Industrial refrigeration technician scarcity:Ammonia system certification requires OSHA-compliant training programs that graduate insufficient cohorts. Retirement waves among 1980s-era mechanics accelerate knowledge gaps.
- WMS-TMS integration complexity:Automated warehouses require real-time data handoffs between warehouse management and transportation platforms. Legacy ERP architectures fragment visibility across multi-modal handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Warehousing Market |
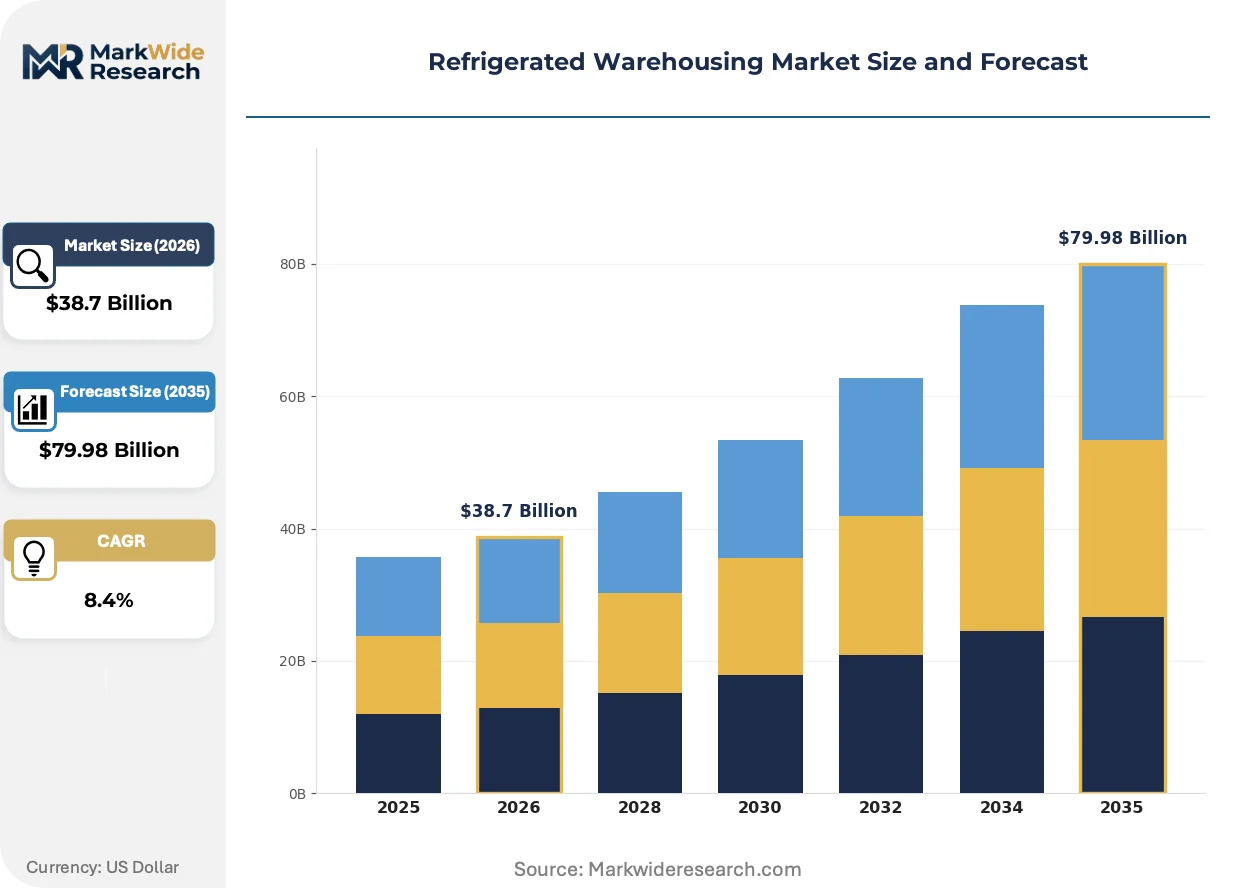
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Chilled Storage, Frozen Storage, Cooler Rooms, Multi-Temperature Storage Service Type: Public Warehousing, Private Warehousing, Co-Managed Warehousing, Third-Party Logistics End User: Food & Beverage, Pharmaceuticals, Chemicals, E-commerce Technology: Refrigeration Systems, Automated Storage, Control Systems, Monitoring Systems |
| Companies Covered | Lineage Logistics, Americold Logistics, United States Cold Storage, Nichirei Logistics Group, Burris Logistics, NewCold, VersaCold Logistics Services, Interstate Cold Storage, Swire Cold Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Warehousing Market Emerging Trajectories
Automation density and refrigerant chemistry are the twin vectors reshaping competitive economics. Operators who synchronize robotic throughput with low-GWP cooling architectures are separating from conventional pallet-rate competitors.
CO2 transcritical booster systems are rewriting energy economics for deep-freeze campuses in Northern Europe. Danish engineering firms deploy these configurations for minus 25 Celsius protein storage with coefficient-of-performance ratios that challenge ammonia in temperate climates. German dairy processors and Dutch seafood exporters now specify CO2 as default for new greenfield developments.
The EPA's Significant New Alternatives Policy program is restricting high-GWP refrigerant approvals for new cold storage construction. US facility developers must now navigate SNAP-listed alternatives or face permitting delays. California Air Resources Board alignment with federal phasedowns creates a de facto national compliance floor for multi-state operators.
Direct-to-restaurant distribution is compressing traditional wholesale layers in North American protein channels. Foodservice operators now procure case-ready portions through port-adjacent cold storage bypassing regional distribution centers. This pattern concentrates throughput demand within 50 miles of major import gateways.
Refrigerated Warehousing Market Segmentation
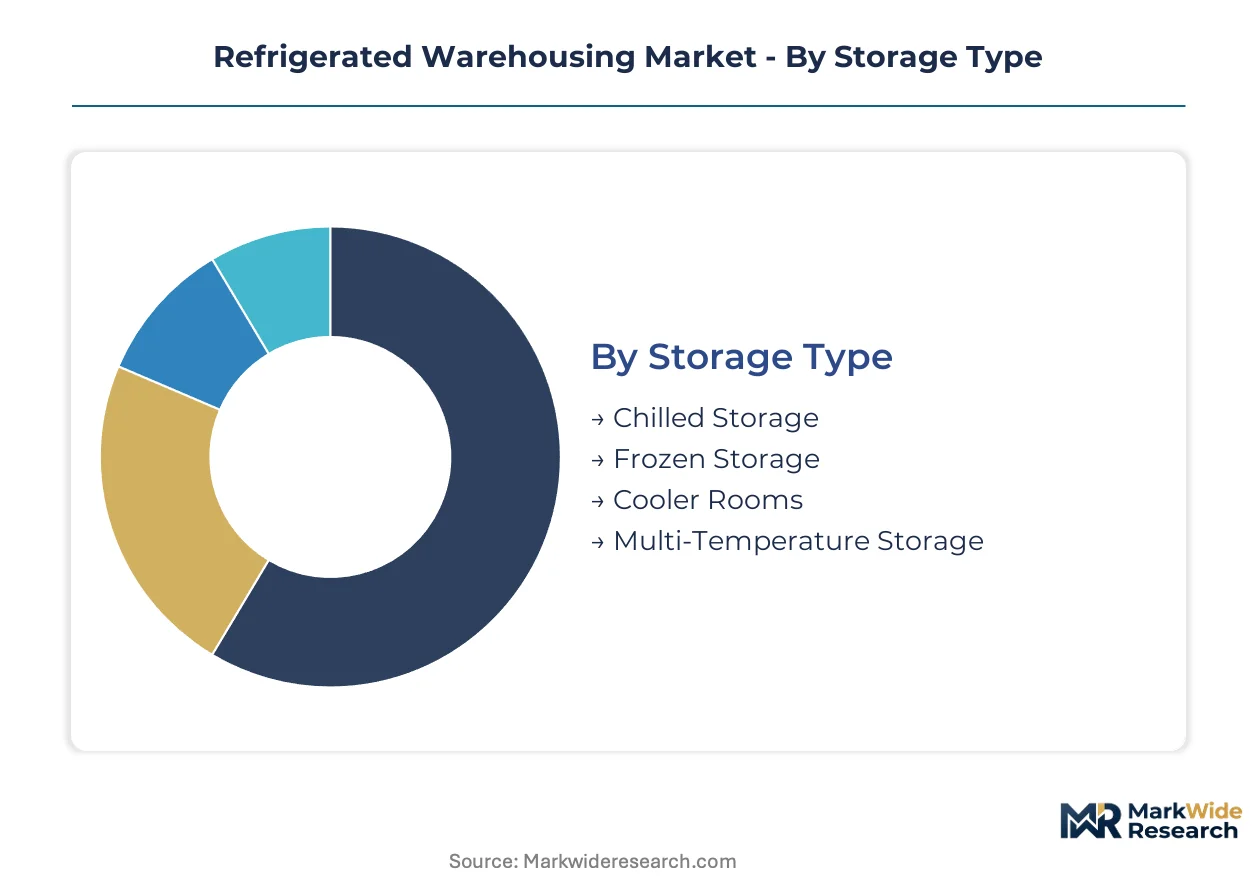
Refrigerated warehousing segmentation reveals how temperature specificity, ownership models, and automation intensity fragment capital deployment. Operators configure facility architecture around distinct biological preservation requirements and supply chain control preferences.
Storage Type:
Temperature band specialization spans from standardized frozen protein vaults to highly customized pharmaceutical stability chambers with redundant HVAC zones.
- Frozen Storage:Minus 25 Celsius environments preserve meat, seafood, and processed food inventories through vapor-compression or CO2 transcritical cycles. Protein exporters in Brazil and dairy processors in New Zealand anchor demand for deep-freeze pallet positions. Energy density requirements favor ammonia-CO2 cascade systems in new greenfield developments.
- Chilled Storage:Zero to plus 4 Celsius corridors handle fresh produce, dairy, and short-shelf-life prepared foods. Indian horticulture cooperatives under the PLI scheme are expanding chilled capacity for mango and grape export cold chains. Temperature excursions here trigger rapid microbial proliferation, demanding continuous monitoring.
- Multi-Temperature Storage:Flexible zones switch between frozen and chilled setpoints via modular refrigeration units. E-commerce grocery fulfillment centers in Germany deploy these for mixed-cart order consolidation.
- Cooler Rooms:Plus 2 to plus 15 Celsius spaces serve beverage distribution and pharmaceutical stability applications. Wine importers in France and vaccine distributors in Switzerland specify precise humidity control alongside temperature management.
Most installed capacity flows through Frozen Storage. Expansion is steepest in Multi-Temperature Storage.
Service Type:
Ownership and operational control models range from fully outsourced third-party arrangements to captive private facilities with direct labor management.
- Third-Party Logistics:Specialized cold chain operators provide temperature-controlled warehousing as a service with integrated transportation management. Lineage Logistics and Americold Logistics dominate North American port-adjacent capacity. Customers avoid capital intensity while accessing automated high-bay infrastructure.
- Private Warehousing:Food manufacturers and pharmaceutical companies operate captive facilities for inventory security and quality control. Nestlé and Unilever maintain proprietary frozen networks for strategic raw material buffers. Capital commitment locks in long-term cost structures but eliminates third-party margin stacking.
- Public Warehousing:Multi-tenant facilities lease pallet positions to fragmented shippers without dedicated space commitments. Seasonal agricultural exporters in Spain and Italy rely on public cold storage for harvest peak absorption.
- Co-Managed Warehousing:Hybrid arrangements split facility ownership and operational responsibility between brand owners and logistics specialists. Japanese seafood processors favor this model for import distribution center management.
Third-Party Logistics commands the largest revenue pool. Private Warehousing is gaining share fastest among biologics manufacturers seeking validated environments.
End User:
Biological preservation requirements and regulatory intensity create distinct customer segments with divergent facility specifications.
- Food & Beverage:Frozen proteins, dairy, fresh produce, and beverages constitute the foundational demand base. USDA inspection protocols and FDA food safety mandates govern facility design in US protein processing corridors.
- Pharmaceuticals:mRNA vaccines and cell therapies demand minus 70 to plus 8 Celsius stability corridors with continuous temperature logging. FDA validation protocols and EMA good distribution practice requirements drive facility certification costs upward.
- Chemicals:Temperature-sensitive industrial precursors and specialty reagents require controlled environments with fire suppression integration. German chemical clusters specify ATEX-compliant refrigeration for flammable material zones.
- E-commerce:Direct-to-consumer grocery and meal-kit fulfillment compresses order cycle times. Automated storage and retrieval systems integrated with warehouse management platforms enable same-day delivery promises in urban UK markets.
Food & Beverage retains dominant volume share. Pharmaceuticals is climbing the fastest on per-pallet premium pricing.
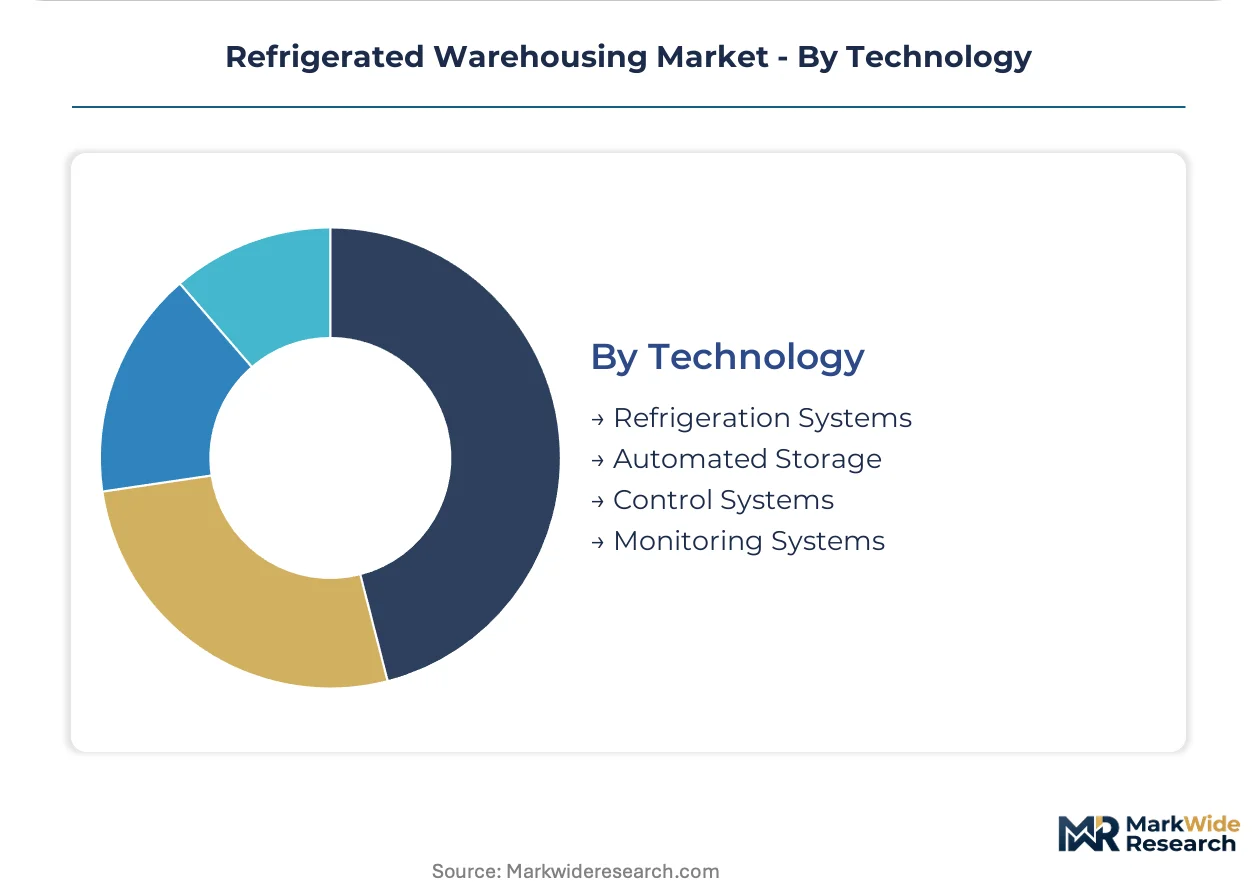
Technology:
Mechanical systems and digital infrastructure layers determine energy efficiency, labor productivity, and regulatory compliance trajectories.
- Refrigeration Systems:Vapor-compression, ammonia-CO2 cascade, and emerging CO2 transcritical configurations deliver cooling capacity. The EU F-Gas Regulation is accelerating synthetic refrigerant phaseout across German and Dutch facility retrofits.
- Automated Storage:Robotic crane systems and high-bay AS/RS architectures compress labor requirements per throughput unit. NewCold's European-designed deep-freeze campuses demonstrate energy efficiency gains alongside automation density.
- Control Systems:Warehouse management platforms integrate refrigeration setpoints with inventory location logic. Real-time optimization reduces energy consumption during low-throughput periods.
- Monitoring Systems:Continuous temperature logging with FDA 21 CFR Part 11-compliant documentation supports pharmaceutical validation. Wireless sensor networks alert operators to deviations before product compromise occurs.
Refrigeration Systems absorbs the largest capital share. Automated Storage is expanding most quickly as labor scarcity intensifies in US Midwest protein hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cold storage capital toward jurisdictions with extended refrigerant phaseout timelines. Operators in markets with slower HFC restrictions capture cost advantages while European competitors absorb accelerated retrofit burdens.
United States
Protein exporters and dairy processors drive port-adjacent capacity expansion. The EPA's Significant New Alternatives Policy program restricts high-GWP refrigerant approvals, forcing SNAP-listed alternatives into new construction. Automated high-bay facilities cluster in Chicago and Omaha protein processing corridors.
Germany
Dairy processors and pharmaceutical distributors anchor demand for deep-freeze and stability chamber capacity. The EU F-Gas Regulation mandates aggressive HFC phasedowns, compelling ammonia-CO2 cascade investments. Engineering contractors in Hamburg and Frankfurt face 14-18 month project queues for complex retrofits.
India
Horticulture cooperatives and organized retail chains expand cold storage networks under the PLI scheme for food processing. BIS energy efficiency standards tighten compliance thresholds for new warehouse permits. Maharashtra and Gujarat host concentrated buildouts for mango and grape export infrastructure.
Netherlands
Seafood exporters and reefer transshipment operators require minus 25 Celsius protein vaults. The EU Green Deal's Recovery and Resilience Facility grants defray CO2 system conversion costs for Dutch operators. Rotterdam-adjacent campuses deploy transcritical booster configurations for energy density.
Brazil
Beef and poultry exporters seek temperature-controlled buffer stock for Asian market access. The national pharmaceutical regulator enforces good distribution practice standards for biologics transit. São Paulo state concentrates multi-temperature facilities serving domestic retail chains.
Refrigerated Warehousing Market Vendor Landscape
Established operators occupy the standard tier; emerging entrants pursue automation-intensive specialization. The market structures around three tiers: global network players with integrated rail and port access, regional specialists with niche temperature capabilities, and automation-first developers of high-bay deep-freeze campuses. Consolidation pressure intensifies as refrigerant transition timelines compress asset valuations. Dominant competitive moves include facility automation retrofits and strategic port-adjacent capacity positioning.
Among North American network operators, Lineage Logistics and Americold Logistics exemplify the integrated infrastructure archetype with automated high-bay architectures and multimodal connectivity. NewCold occupies a distinct position as a European-engineered automation specialist competing on energy efficiency in deep-freeze applications. These three anchors represent divergent capital deployment strategies: domestic network density, integrated transportation control, and greenfield automation economics.
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold Logistics |
| United States Cold Storage |
| Nichirei Logistics Group |
| Burris Logistics |
| NewCold |
| VersaCold Logistics Services |
| Interstate Cold Storage |
| Swire Cold Storage |
| Others |
Supply Flow & Price Mechanics
Industrial refrigeration technician concentration in Germany, Denmark, and the Netherlands compresses project queues to 14-18 months, widening labor-cost spreads between premium automated facilities and conventional pallet-rate competitors. This scarcity differential separates pricing tiers: operators with in-house ammonia-CO2 cascade engineering command lease premiums while independents absorb margin compression from contractor dependency.
Pricing Analysis
Distributor margin stacking in third-party logistics separates final pallet rates from underlying facility economics. Three-tier pricing structure across premium, standard, and economy levels reflects automation density, certification grade, and geographic port adjacency. Pricing pressure stems from copper and aluminum commodity volatility transmitting directly to heat exchanger capex quotes. Food and beverage exporters show highest price sensitivity; pharmaceutical biologics manufacturers accept premium spreads for FDA-validated stability corridors.
Supply Chain Analysis
Refrigeration equipment supply rests on German engineering contractors, Danish CO2 system specialists, and Chinese aluminum smelter output. Heat exchanger fabrication draws from copper Chilean mine production and German precision manufacturing. Single-source vulnerability concentrates in ammonia-CO2 cascade engineering expertise clustered in Northern Europe. Distribution runs through port-adjacent cold storage nodes serving protein export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated warehousing functions as a geographic-arbitrage play where Indian PLI scheme subsidies and extended HFC phaseout timelines compress facility buildout costs against European retrofit burdens under EU F-Gas Regulation mandates.
For Market Incumbents: Deepen automation retrofit intensity in US Midwest protein processing hubs before labor scarcity hardens into structural constraint. Acquire ammonia-CO2 cascade engineering capabilities through captive contractor relationships or facility-level vertical integration to defray 14-18 month project queue risk. Lock port-adjacent land positions near Rotterdam, Chicago, and São Paulo as foodservice bypass patterns concentrate throughput within 50-mile import gateways.
For New Entrants and Emerging Players: Begin with pharmaceutical stability chamber specialization in India and Brazil where biologics cold chain infrastructure lags mRNA vaccine distribution requirements. Target Maharashtra and Gujarat horticulture cooperatives under PLI scheme subsidies for chilled storage buildout. Lead with CO2 transcritical energy efficiency credentials against legacy HFC-dependent competitors facing accelerated depreciation.
For Investors and Strategic Acquirers: Food manufacturers with captive cold storage networks are the most active acquirer in this space, seeking temperature-controlled buffer stock security. Long-term viability centers on facilities with automation-ready architecture and refrigerant transition flexibility. Watch EU Green Deal financing window closures as inflection indicator for European asset valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay AS/RS Retrofit | Robotic crane integration compresses labor cost per throughput unit in US protein hubs. |
| CO2 Transcritical System Conversion | EU F-Gas Regulation mandates eliminate synthetic refrigerant dependency in German facilities. |
| Port-Adjacent Capacity Expansion | Direct-to-restaurant distribution concentrates demand within 50 miles of Rotterdam and Chicago. |
| Pharmaceutical Stability Chamber Certification | FDA validation protocols command premium lease rates from mRNA vaccine distributors. |
| Backward Integration into Ammonia Engineering | Captive contractor relationships defray 14-18 month project queue risk in Denmark and Germany. |
Methodological Framework
Multiple input streams — facility operator interviews, refrigeration engineering contractor assessments, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged cold storage facility managers, ammonia system contractors, pharmaceutical logistics directors, and food processor procurement leads. Secondary validation drew from EPA SNAP refrigerant approvals, EU F-Gas Regulation implementation timelines, Indian BIS cold storage standards, and customs trade data on protein export volumes. Bottom-up pallet position counts and top-down cold chain infrastructure investment flows were triangulated for consistency.
Data-stream reconciliation across storage type, service model, temperature band, and automation intensity dimensions produced volume and value outputs throughout the forecast period. CAGRs were derived from facility investment pipelines, refrigerant transition timelines, and pharmaceutical cold chain expansion trajectories. Modeled inputs included PLI scheme disbursement schedules, EU Green Deal financing window availability, and labor force graduation rates from OSHA-compliant ammonia certification programs.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations to HFC phasedown timelines and breakthrough solid-state cooling technologies. Forecasts reflect assumptions about commodity price stability and contractor capacity expansion. A small set of named triggers warrants ongoing watch: EU Recovery and Resilience Facility grant exhaustion, Indian organized retail penetration rates in tier-2 cities, and US Midwest refrigeration technician training program graduation volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Luxembourg Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
Bulgaria Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
United States Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Czech Republic Facility Management Market