
 North America Water Enhancer Market | 2026-2036
North America Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Water Enhancer Market Analytics
Multi-source flavor ingredient procurement is repositioning how North American water enhancer manufacturers manage supply resilience and cost volatility. PepsiCo leverages its captive beverage distribution network to sustain shelf presence across mass retail channels. The Kraft Heinz Company anchors its position through concentrated flavor R&D partnerships with specialty chemical suppliers. Nestlé S.A. differentiates via premium natural-positioned sub-brands targeting wellness-oriented households.
Water enhancers comprise concentrated liquid, powder, tablet, or encapsulated formulations designed to dissolve in still or carbonated water, delivering flavor, electrolytes, vitamins, or functional extracts without bottled beverage logistics. These products typically contain less than five calories per serving, relying on non-nutritive sweeteners, natural flavors, and acidulants to achieve sensory profiles comparable to ready-to-drink alternatives. Liquid concentrates dominate current volume due to dosing convenience and established supermarket placement, while tablet formats represent the fastest-growing structural segment as on-the-go portability aligns with fitness enthusiast usage occasions. Distribution through health stores captures disproportionate margin pools relative to volume share, reflecting premium positioning and educated consumer self-selection.
The FDA governs ingredient safety declarations and nutrition fact panel compliance for water enhancers sold in the United States, while Health Canada and the PMRA regulate flavor additive approvals and labeling standards for Canadian market access. The USDA's organic certification program creates a parallel compliance pathway for natural-positioned products, influencing raw material sourcing decisions and finished-good pricing architecture. Stakeholders must monitor evolving state-level sugar taxation proposals and municipal plastic reduction mandates that could reshape single-serve packaging formats and concentrate-to-water dilution ratios.
Market Dynamics
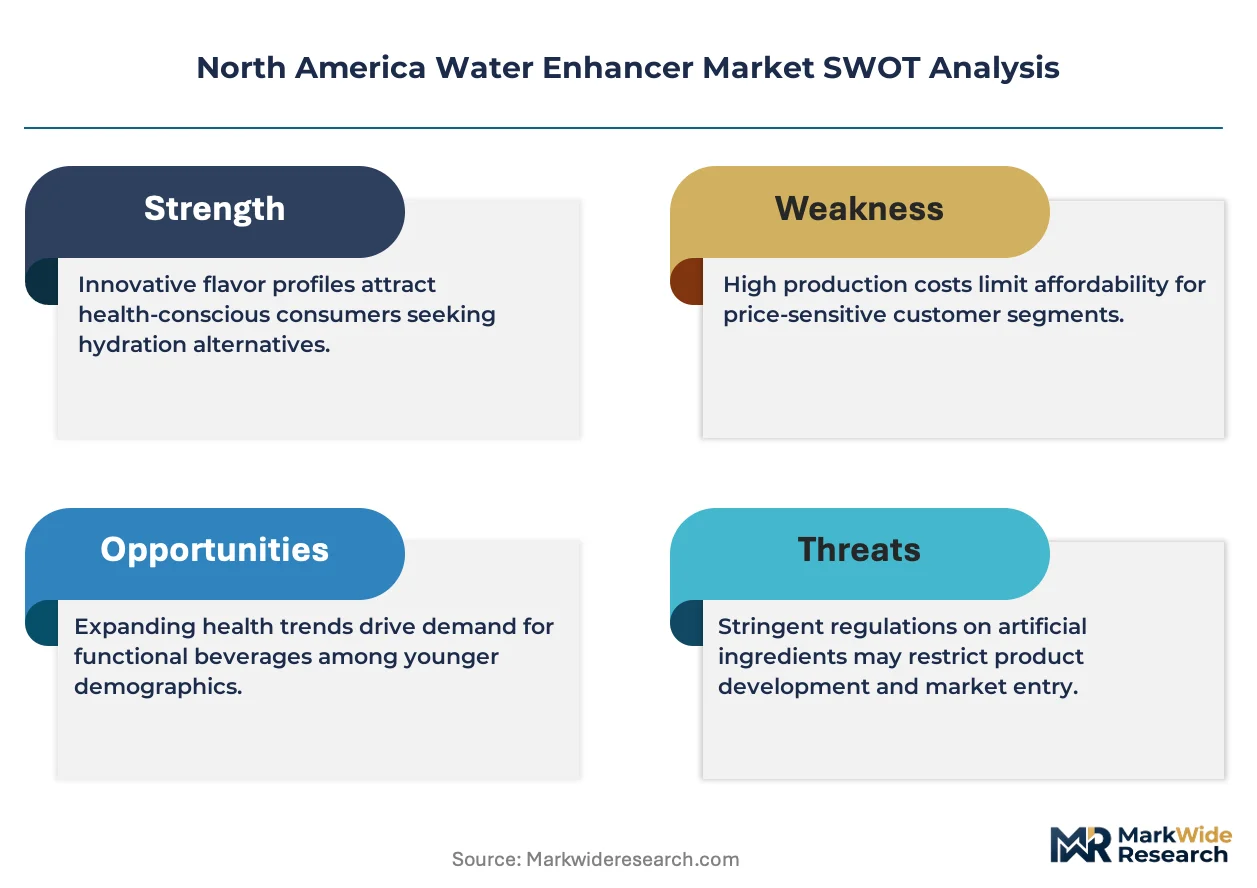
FDA's updated nutrition labeling requirements for added sugars are forcing rapid reformulation across North American water enhancer portfolios. Manufacturers must pivot toward natural sweeteners and clean-label ingredient decks while maintaining sensory parity with legacy formulations.
Growth Catalysts
- Low-sugar beverage alternatives:Health-conscious consumers in the United States and Canada are rejecting traditional carbonated soft drinks. Water enhancers deliver flavor satisfaction with under five calories per serving.
- Health Canada's PMRA flavor additive pathway:Streamlined approvals for natural-positioned ingredients are accelerating clean-label product launches across Ontario and British Columbia retail channels.
- Fitness hydration segment concentration:Metropolitan clusters in California, Texas, and Ontario generate disproportionate volume for electrolyte-enhanced liquid concentrates targeting gym and outdoor recreation occasions.
Market Restraints
- Natural sweetener cost volatility:Stevia and monk fruit extract prices fluctuate with agricultural yields in Southeast Asian growing regions, compressing margin structures for mid-tier brands.
- Single-serve packaging compliance:Municipal plastic reduction mandates in California and New York City are forcing costly format redesigns for portable liquid concentrate sachets.
- Clean-label technical limitations:Natural preservatives deliver shorter shelf stability than synthetic alternatives, constraining distribution radius and inventory turnover velocity.
Strategic Opportunities
- USDA organic certification pathway:Premium-positioned sub-brands targeting wellness-oriented households in Colorado and Pacific Northwest markets command 40-60% price premiums over conventional equivalents.
- Tablet format portability:On-the-go fitness enthusiasts in Texas and Florida are shifting from liquid bottles to dissolvable tablets, opening shelf-space expansion in convenience and travel retail.
- Health store channel margin capture:Specialty retailers in Toronto and Vancouver generate disproportionate profitability relative to volume through educated consumer self-selection and premium positioning.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging natural ingredient stability and sensory performance concentrates among a limited pool of specialists in New Jersey and California R&D clusters.
- Dual-label compliance complexity:Simultaneous FDA and Health Canada nutrition panel requirements force parallel packaging runs, inflating working capital requirements for cross-border SKUs.
- Legacy retail slotting fee structures:Mass supermarket chains in the United States demand disproportionate promotional spending to secure shelf placement against entrenched beverage conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Water Enhancer Market |
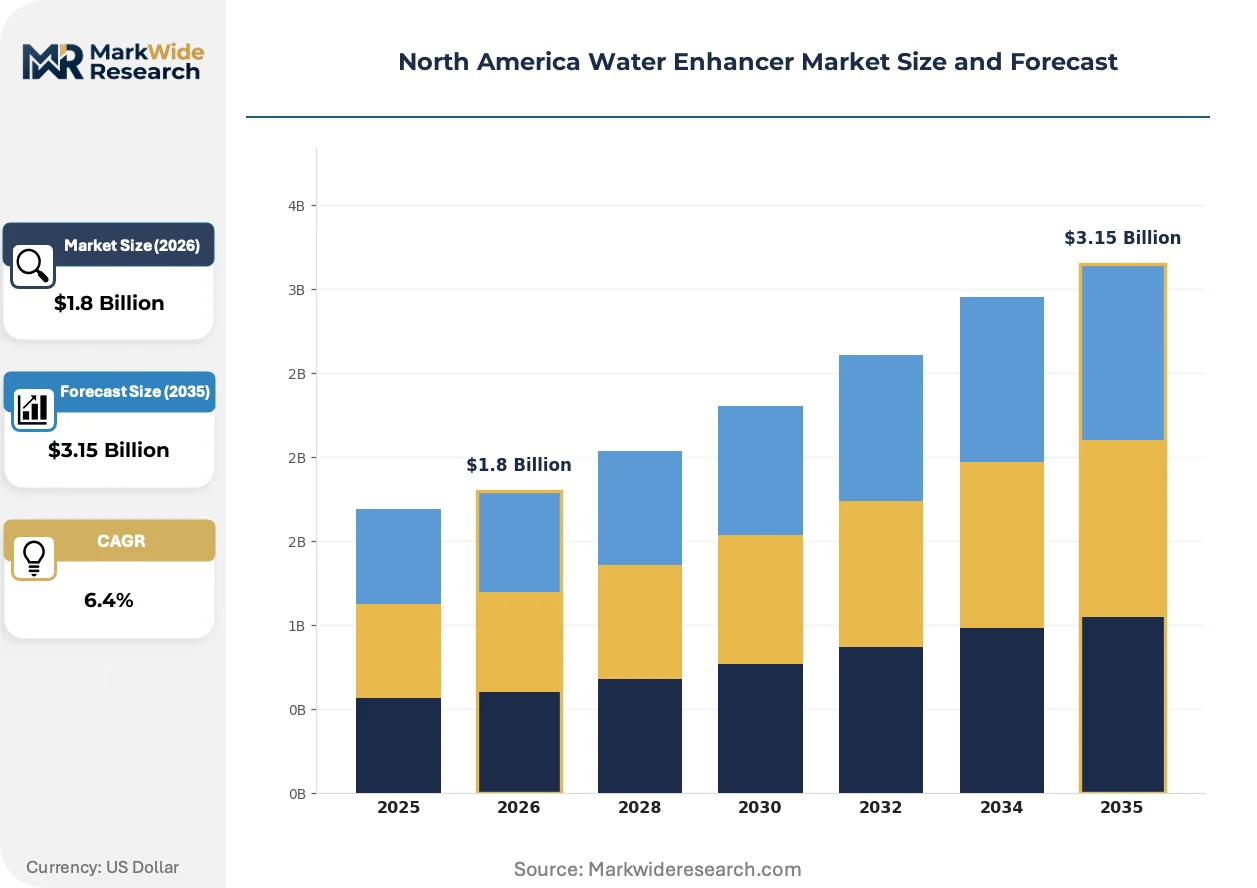
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Tablet, Concentrate Flavor Category: Citrus, Berry, Tropical, Herbal Distribution Channel: Online, Supermarkets, Health Stores, Convenience Stores End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, General Consumers |
| Companies Covered | Nestlé S.A., The Jel Sert Company, The Kraft Heinz Company, Mondelez International, Heartland Food Products Group, PepsiCo, Inc., Keurig Dr Pepper, Dyla Brands, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Water Enhancer Market Evolving Landscape
Encapsulation technology and portable dosing formats are compressing traditional liquid concentrate dominance. Manufacturers now compete on convenience architecture rather than flavor variety alone.
Micro-encapsulated flavor delivery systems are modularizing how functional extracts and vitamins survive shelf storage without synthetic stabilizers. Sports nutrition brands in California and Texas are adopting these systems fastest, enabling probiotic and nootropic ingredient inclusion previously incompatible with aqueous matrices. The technology is modularizing supply chain requirements by decoupling manufacturing from cold-chain logistics.
FDA's added sugars disclosure mandate is restructuring formulation priorities across United States production facilities. Manufacturers must now quantify and prominently display sweetener content, accelerating stevia and allulose substitution programs. Sugar-reduction claims have become the primary packaging communication hierarchy for mass-market liquid concentrates.
Fitness enthusiasts are fragmenting purchase occasions across multiple channel types rather than consolidating supermarket trips. Specialty running stores and climbing gyms in Colorado and Ontario now stock curated water enhancer selections alongside apparel, displacing traditional grocery as the discovery channel. This behavioral shift is most visible among millennial and Gen Z consumers in Austin, Denver, and Vancouver metropolitan zones.
North America Water Enhancer Market Segmentation
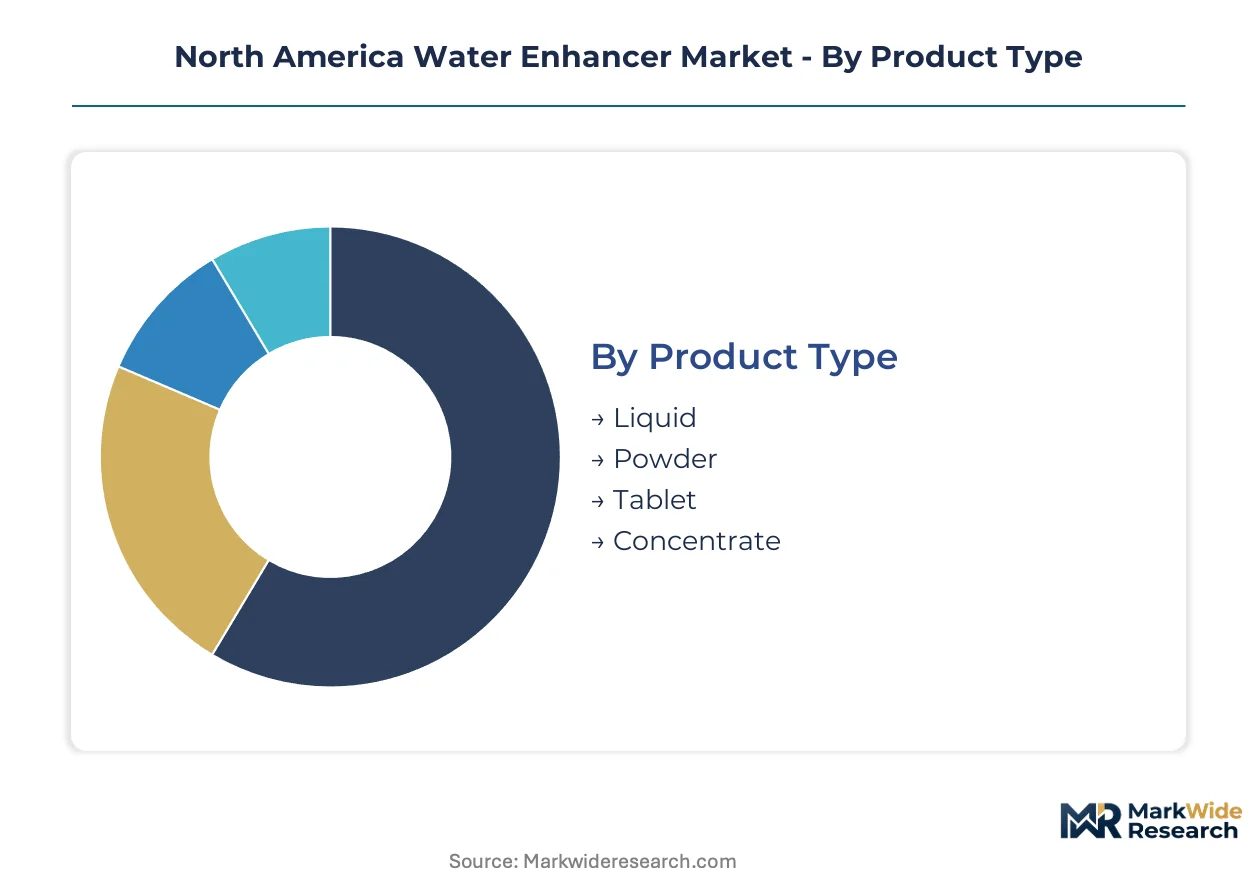
Water enhancer manufacturers structure portfolios around four distinct dimensions that govern formulation investment, channel economics, and consumer targeting. Product format decisions determine manufacturing capital allocation and shelf-space negotiations. Flavor positioning, distribution architecture, and end-user segmentation together shape margin capture and brand loyalty trajectories across the United States and Canada.
Product Type:
Replacement cycles vary dramatically by format, with liquid concentrates facing saturation pressure from portable alternatives that command premium unit economics and faster household replenishment rates.
- Liquid:Pre-dosed squeeze bottles or droppers containing concentrated flavor and functional additives dissolve instantly in water. Demand clusters in suburban United States households seeking refrigerator-door convenience and predictable portion control for family consumption.
- Powder:Single-serve stick packs or bulk canisters deliver lightweight, shelf-stable formulations with extended ambient storage tolerance. Fitness enthusiasts across Texas and Florida prefer powder for gym bag portability and airline travel compliance.
- Tablet:Compressed effervescent or slow-dissolve formats eliminate liquid spillage risk and reduce shipping weight. Outdoor recreation retailers in Colorado and British Columbia are expanding tablet assortments for hiking and camping occasions.
- Concentrate:Ultra-compact multi-dose bottles requiring precise dilution ratios appeal to bulk buyers and foodservice operators. Commercial adoption concentrates in workplace wellness programs across Ontario corporate campuses.
Volume placements concentrate in liquid formats; the faster expansion belongs to tablet.
Flavor Category:
Flavor preference maps directly to functional ingredient compatibility and clean-label positioning intensity across Canadian and United States retail channels.
- Citrus:Lemon, lime, and orange profiles dominate electrolyte-enhanced sports formulations due to natural acidity masking mineral aftertaste. California and Arizona consumers show strongest affinity for citrus-positioned hydration products.
- Berry:Strawberry, raspberry, and blueberry variants accommodate antioxidant and vitamin fortification without cloying sweetness. Health stores in Toronto and Vancouver generate disproportionate berry SKU velocity.
- Tropical:Mango, pineapple, and coconut profiles target vacation-occasion consumption and summer seasonal programming. Convenience stores in Florida and Hawaii stock tropical assortments year-round.
- Herbal:Lavender, chamomile, and botanical infusions support relaxation and sleep-positioned functional claims. Pacific Northwest metropolitan consumers in Seattle and Portland drive herbal segment expansion.
Citrus and berry split mainstream volume; herbal is climbing the fastest.
Distribution Channel:
Channel selection determines pricing architecture and consumer education requirements, with specialty retail commanding margin premiums that subsidize mass-market customer acquisition.
- Online:Direct-to-consumer and marketplace platforms enable subscription replenishment and flavor variety bundling. Urban millennials in Austin and Denver prefer online discovery for niche functional formulations unavailable in physical retail.
- Supermarkets:Mass grocery chains provide scale velocity and impulse purchase placement at beverage aisle endcaps. Slotting fee structures favor established conglomerates with promotional war chests.
- Health Stores:Specialty retailers curate premium natural-positioned assortments with trained staff consultation. Vancouver and Boulder health stores achieve 40-60% price premiums through educated consumer self-selection.
- Convenience Stores:Grab-and-go single-serve formats target immediate consumption and travel replenishment. Texas and Florida convenience chains are expanding tablet and powder sachet placements.
Supermarkets anchor volume throughput; health stores deliver steepest margin expansion.
End User:
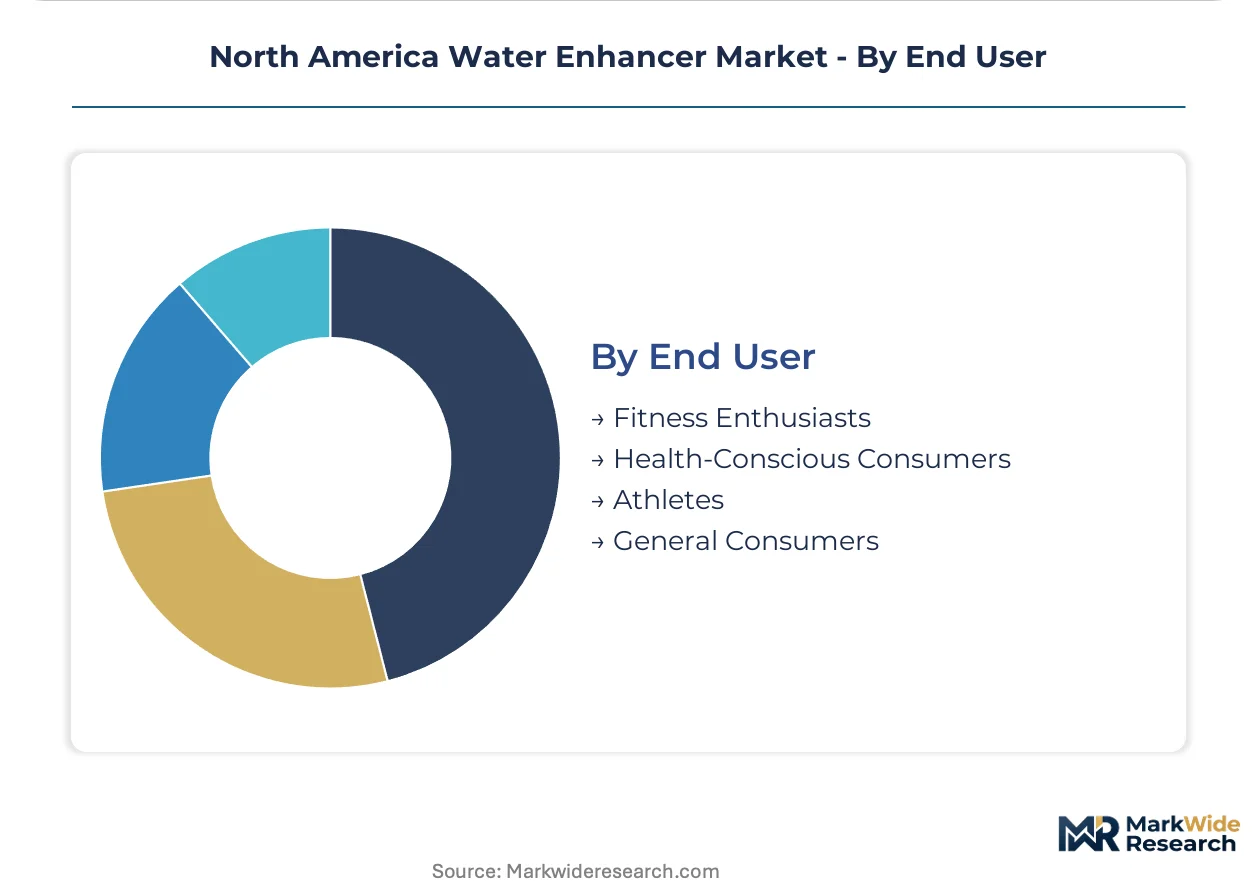
User archetypes dictate functional ingredient loading, packaging format preferences, and price sensitivity thresholds that manufacturers must reconcile within constrained SKU counts.
- Fitness Enthusiasts:Gym-regular consumers prioritize electrolyte replenishment, branched-chain amino acid fortification, and rapid dissolution in shaker bottles. Metropolitan clusters in California and Texas generate disproportionate liquid concentrate demand.
- Health-Conscious Consumers:Wellness-oriented households scrutinize sweetener sources and additive transparency, favoring USDA organic and non-GMO verified positioning. Colorado and Pacific Northwest markets show strongest clean-label affinity.
- Athletes:Competitive and endurance sports participants require precise sodium, potassium, and magnesium dosing for performance optimization. Sports nutrition retailers in Ontario and British Columbia serve this segment.
- General Consumers:Mainstream households seeking sugar reduction without flavor sacrifice drive mass-market volume and promotional dependency. Suburban United States supermarkets capture this broad base.
Fitness enthusiasts and health-conscious consumers concentrate premium volume; athlete-targeted formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia and monk fruit agricultural supply chains from Southeast Asian growing regions anchor North American water enhancer manufacturing economics. Cross-border formulation compliance between the United States and Canada shapes dual-label packaging requirements. Metropolitan fitness clusters in California, Texas, and Ontario concentrate disproportionate demand velocity for electrolyte-enhanced formats.
United States
FDA's updated nutrition labeling requirements for added sugars are forcing rapid reformulation toward stevia and allulose across United States production facilities. The USDA's organic certification program creates premium pricing pathways for natural-positioned sub-brands in Colorado and Pacific Northwest markets. California's metropolitan fitness clusters generate concentrated demand for liquid concentrate formats targeting gym and outdoor recreation occasions.
Canada
Health Canada's PMRA streamlined approvals for natural-positioned flavor additives are accelerating clean-label product launches across Ontario and British Columbia retail channels. Municipal plastic reduction mandates in Toronto and Vancouver are forcing format redesigns for portable liquid concentrate packaging. British Columbia's outdoor recreation retailers are expanding tablet format assortments for hiking and camping consumption occasions.
Mexico
Rising health-consciousness among middle-class consumers in Mexico City and Monterrey is driving trial of low-calorie beverage alternatives. The country's national food safety regulator maintains additive approval pathways that parallel FDA frameworks for cross-border manufacturing integration. Northern border states concentrate maquiladora production capacity serving United States private-label programs.
North America Water Enhancer Market Competitive Landscape
Portfolio diversification dominates the current landscape as conglomerates and specialists reposition around clean-label ingredient transitions. The vendor base concentrates among three tiers: multinational beverage conglomerates with captive distribution networks, mid-cap specialty brands with health-store channel depth, and private-label manufacturers serving mass retail price points. Strategic archetypes include scale-driven liquid concentrate incumbents, tablet-format portability innovators, and organic-certified premium sub-brand architects. M&A activity and strategic R&D partnerships represent the dominant competitive vectors as formulation expertise scarcity intensifies.
Within the multinational conglomerate tier, PepsiCo, Inc. and The Coca-Cola Company exemplify scale-driven positioning through established mass retail shelf presence and beverage aisle dominance. Nestlé S.A. occupies a distinct premium-natural archetype targeting wellness-oriented households through sub-brand differentiation. The Kraft Heinz Company and Mondelez International sit within the diversified packaged goods constellation, leveraging flavor R&D infrastructure across adjacent snacking and beverage categories.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Jel Sert Company |
| The Kraft Heinz Company |
| Mondelez International |
| Heartland Food Products Group |
| PepsiCo, Inc. |
| Keurig Dr Pepper |
| Dyla Brands |
| The Coca-Cola Company |
| Others |
Value Network & Pricing Analysis
Fitness enthusiasts and health-conscious households concentrate demand for water enhancers, anchoring a pricing model that separates premium USDA-certified organic tiers from conventional mass-market equivalents through clean-label ingredient transparency and certification investment.
Pricing Analysis
Service bundling remains unbundled in water enhancer pricing, with manufacturers charging separately for subscription replenishment, flavor variety packs, and functional ingredient fortification. Three-tier pricing structure across premium organic, standard natural-positioned, and economy private-label levels separates buyer segments by certification grade and sweetener source. Price differentiation hinges on USDA organic verification and stevia versus synthetic sweetener positioning. Cost compression in mid-tier natural formulations is intensifying because agricultural yield volatility in Southeast Asian monk fruit growing regions squeezes margin structures. Mass-market supermarket buyers show highest price sensitivity, while health store channel consumers absorb 40-60% premiums for organic verification.
Supply Chain Analysis
Domestic-content mandates in California and New York municipal plastic reduction programs are reshaping sourcing toward North American packaging suppliers and biodegradable material providers. Stevia and monk fruit extraction capacity concentrates in China, Thailand, and Malaysia, with flavor compound manufacturing clustering in New Jersey and California R&D corridors. Raw material dependencies center on Southeast Asian agricultural stevia leaf supply, Brazilian citrus oil for acidulant profiles, and German-engineered encapsulation equipment. Single-source vulnerability runs through concentrated stevia extract supply from Chinese processing facilities. Distribution runs through PepsiCo and Coca-Cola captive beverage networks for mass retail penetration, with specialty health stores served through independent natural products distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around formulation expertise scarcity and clean-label transition costs that weaker private-label manufacturers cannot absorb, forcing exit or acquisition by conglomerates with captive R&D infrastructure.
For Market Incumbents: Deepen backward integration into stevia and monk fruit agricultural supply through offtake agreements with Thai and Chinese growers, securing volume commitments that mid-tier competitors cannot match. Expand encapsulation technology R&D partnerships with New Jersey specialty chemical clusters to accelerate probiotic and nootropic ingredient inclusion. Defend against tablet-format portability innovators by acquiring dissolvable technology specialists before shelf-space displacement accelerates in Texas and Florida convenience channels. For New Entrants and Emerging Players: Micro-encapsulated flavor delivery systems offer a technology-first wedge into sports nutrition white space, where California and Texas fitness enthusiasts prioritize functional ingredient stability over brand heritage. Target health store channel penetration in Vancouver and Boulder, where educated consumer self-selection generates margin pools that subsidize mass-market customer acquisition. Pursue direct-to-consumer subscription models with flavor variety bundling to bypass legacy supermarket slotting fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap natural-positioned brands with Health Canada PMRA approval pathways and established British Columbia retail presence, where regulatory compliance assets compound valuation. Long-term viability over a five-to-ten-year window rests on clean-label transition completion and USDA organic certification infrastructure. Watch for inflection signals in California municipal plastic mandate enforcement timelines, which will force format redesign investments that strain undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks 40-60% price premiums in Colorado and Pacific Northwest health store channels. |
| Encapsulation Technology Partnership | Enables probiotic inclusion previously incompatible with aqueous matrices for California sports nutrition brands. |
| Tablet Format Manufacturing Scale-Up | Captures portability demand from Texas and Florida outdoor recreation enthusiasts. |
| Direct-to-Consumer Subscription Launch | Bypasses legacy supermarket slotting fees that favor PepsiCo and Coca-Cola promotional spending. |
| Southeast Asian Agricultural Offtake Agreement | Secures stevia extract supply against Chinese processing facility concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with beverage brand managers, health store category buyers, FDA regulatory affairs specialists, and flavor chemist R&D directors. Secondary validation drew from FDA nutrition labeling guidance documents, Health Canada PMRA flavor additive approval databases, USDA organic certification registries, and Nielsen retail audit data for water enhancer velocity. Bottom-up SKU-level demand modeling triangulated against top-down category value estimates from packaged goods industry associations.
Granularity-level modeling operated at product format, flavor category, distribution channel, and end-user segmentation dimensions, with additional disaggregation by metropolitan fitness cluster geography. CAGRs were derived through trend extrapolation of historical volume trajectories, adjusted for regulatory inflection points and clean-label transition timelines. Forecast inputs incorporated FDA added sugars disclosure mandate compliance costs, Health Canada streamlined approval pathway velocity, and municipal plastic reduction mandate implementation schedules across California and New York jurisdictions.
Several conditions sit outside the modeled scope, including unforeseen agricultural yield shocks in Southeast Asian stevia growing regions, abrupt shifts in FDA sweetener safety classifications, and disruptive packaging material innovations that could render current format economics obsolete. Forecasts reflect documented assumptions regarding clean-label transition completion rates and health-conscious consumer willingness-to-pay premiums. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Trans-Resveratrol Market