
 Germany Water Enhancer Market | 2026-2036
Germany Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Water Enhancer Market Foresight
Market Context
The price-performance gap between premium functional enhancers and basic flavor drops is hardening as ingredient transparency becomes a decisive purchase factor. BOLERO GmbH leverages its sugar-free formulation expertise to sustain volume leadership in discount retail channels. The Kraft Heinz Company anchors its position through broad supermarket distribution, while Waterdrop Microdrink GmbH differentiates via compact microdrink cubes targeting urban professionals.
Technical Definition and Segment Structure
Germany water enhancers comprise concentrated liquid drops, effervescent tablets, and soluble powders designed to modify taste, mineral content, or nutritional profile of potable water, typically containing electrolytes, vitamins, plant extracts, or natural flavor compounds at dilution ratios of 1:50 to 1:200. These products serve commercial and household users seeking alternatives to sugar-sweetened beverages or single-use bottled functional drinks. Electrolyte powders lead product type revenue due to sports nutrition crossover demand, while vitamin boosters capture the fastest growth as immunity positioning resonates with senior and professional segments. Online retailers now command the highest margin pool among distribution channels by eliminating intermediary shelf fees and enabling subscription-based replenishment models.
Regulatory Environment and Outlook
The EU Food Information to Consumers Regulation and Germany's national BfR guidelines on food supplements govern labeling claims and additive safety, with EFSA health claim authorization requirements limiting unsubstantiated wellness marketing. REACH compliance and the EU Single-Use Plastics Directive further constrain packaging material choices, steering producers toward glass and aluminum formats. Stakeholders must monitor impending EU packaging and packaging waste regulation revisions that will mandate minimum recycled content thresholds and deposit-return expansion.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing format economics across Germany, forcing manufacturers to abandon single-use plastic bottles in favor of concentrated drops and refillable systems that slash logistics costs and shelf space requirements.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on disposable plastic beverage containers is redirecting consumer spend toward concentrated enhancer formats that eliminate bottle waste entirely.
- Fitness culture concentration:Metropolitan gym density in Berlin, Munich, and Hamburg creates clustered demand for electrolyte powders among amateur athletes seeking hydration alternatives.
- Ingredient transparency platforms:Digital traceability systems are enabling clean-label positioning that commands shelf premium in organic retail channels.
Market Restraints
- Natural flavor input volatility:Citrus and botanical extract costs fluctuate with Mediterranean harvest cycles, squeezing margin on premium positioning.
- Glass bottle supply concentration:German pharmaceutical-grade glass manufacturing clusters in Bavaria create single-source risk for premium format packaging.
- EFSA health claim authorization:The 18-24 month substantiation timeline blocks rapid immunity-positioning product launches.
Strategic Opportunities
- Eastern federal states:Saxony and Thuringia show underpenetrated enhancer consumption relative to western per-capita benchmarks.
- Workplace hydration programs:Corporate wellness contracts represent a channel bypassing retail slotting fees entirely.
- EU packaging waste regulation revisions:Pending recycled content mandates will advantage domestic producers with established circular supply partnerships.
Industry Challenges
- Food technologist scarcity:Formulation expertise bridging beverage science and supplement regulation commands premium compensation in Frankfurt and Munich labor markets.
- BfR compliance timeline:Novel ingredient safety assessments extend development cycles by 8-14 months versus conventional flavor systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Water Enhancer Market |
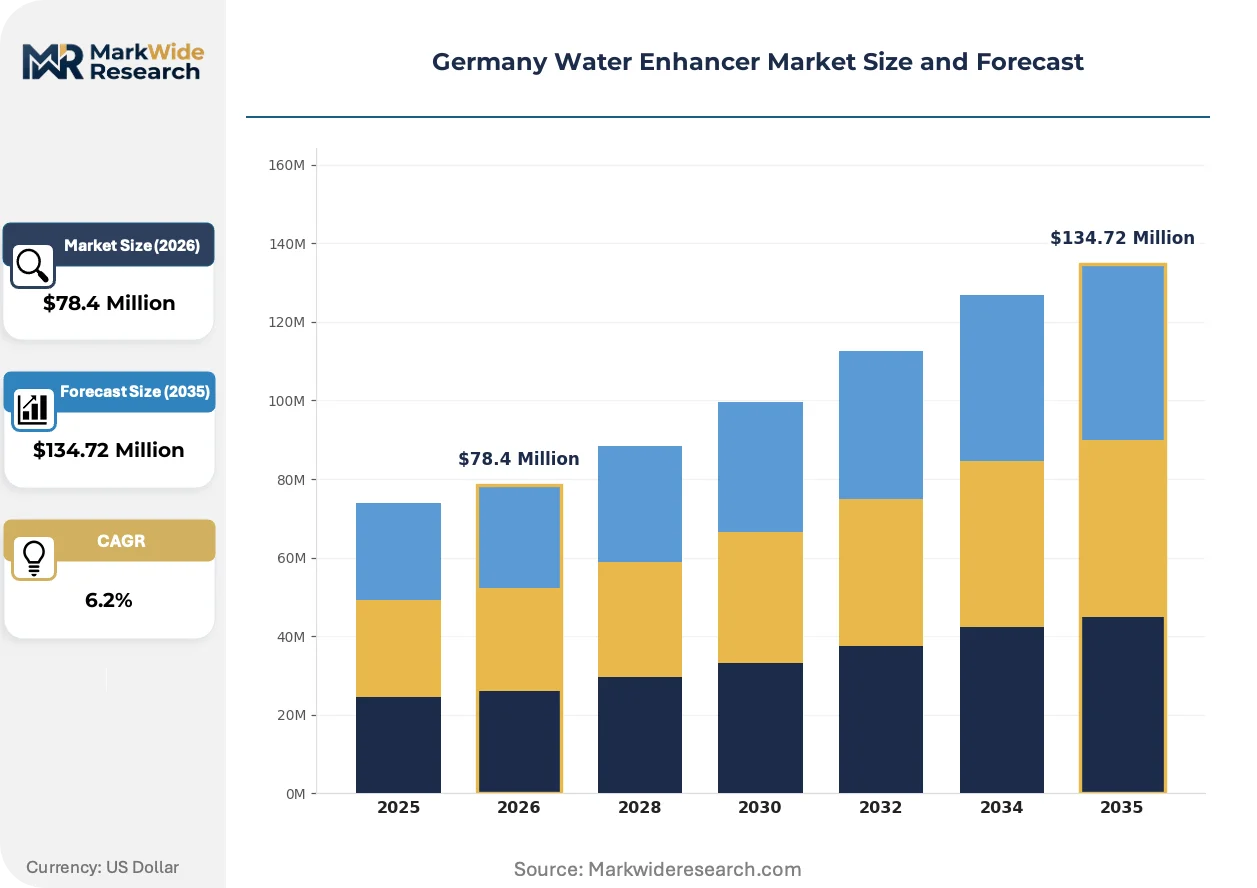
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Drops, Electrolyte Powders, Vitamin Boosters, Herbal Infusions, Mineral Additives Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Pharmacies, Direct Sales Customer Type: Health Enthusiasts, Athletes, Seniors, Busy Professionals, Students Application: Fitness Hydration, Dietary Supplement, Detoxification, Flavor Enhancement, Wellness Therapy |
| Companies Covered | BOLERO GmbH, Dyla LLC, The Kraft Heinz Company, Wisdom Natural Brands, Salto GmbH, Waterdrop Microdrink GmbH, Holy Energy GmbH, Mijuwi GmbH, BRITA SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Water Enhancer Market Shifts & Advancements
Concentrated microdose formats are compressing the traditional liquid enhancer category, with solid-state delivery systems capturing shelf space from legacy drop bottles across German drugstore and supermarket channels.
Microencapsulation technology for heat-stable vitamin preservation is overtaking standard spray-drying in electrolyte powder manufacturing. Sports nutrition brands in North Rhine-Westphalia are adopting these formats for summer distribution without cold-chain requirements. This shift is enabling ambient retail placement that expands point-of-sale density beyond refrigerated sections.
The EU Green Deal's packaging and packaging waste regulation is mandating minimum 35% recycled content in all beverage-adjacent packaging by 2030. German manufacturers are accelerating aluminum tube and glass vial transitions ahead of enforcement timelines. Premium-positioned microdrink cubes are absorbing the highest compliance costs, pushing mid-tier players toward private-label contract manufacturing.
Subscription replenishment models are capturing repeat purchase volume from impulse-driven supermarket buying. Urban professionals in Hamburg and Frankfurt are locking into 90-day auto-ship cycles for personalized vitamin stacks. This behavioral shift concentrates customer lifetime value with direct-to-consumer platforms, eroding traditional retail slotting fee economics across the category.
Germany Water Enhancer Market Segmentation
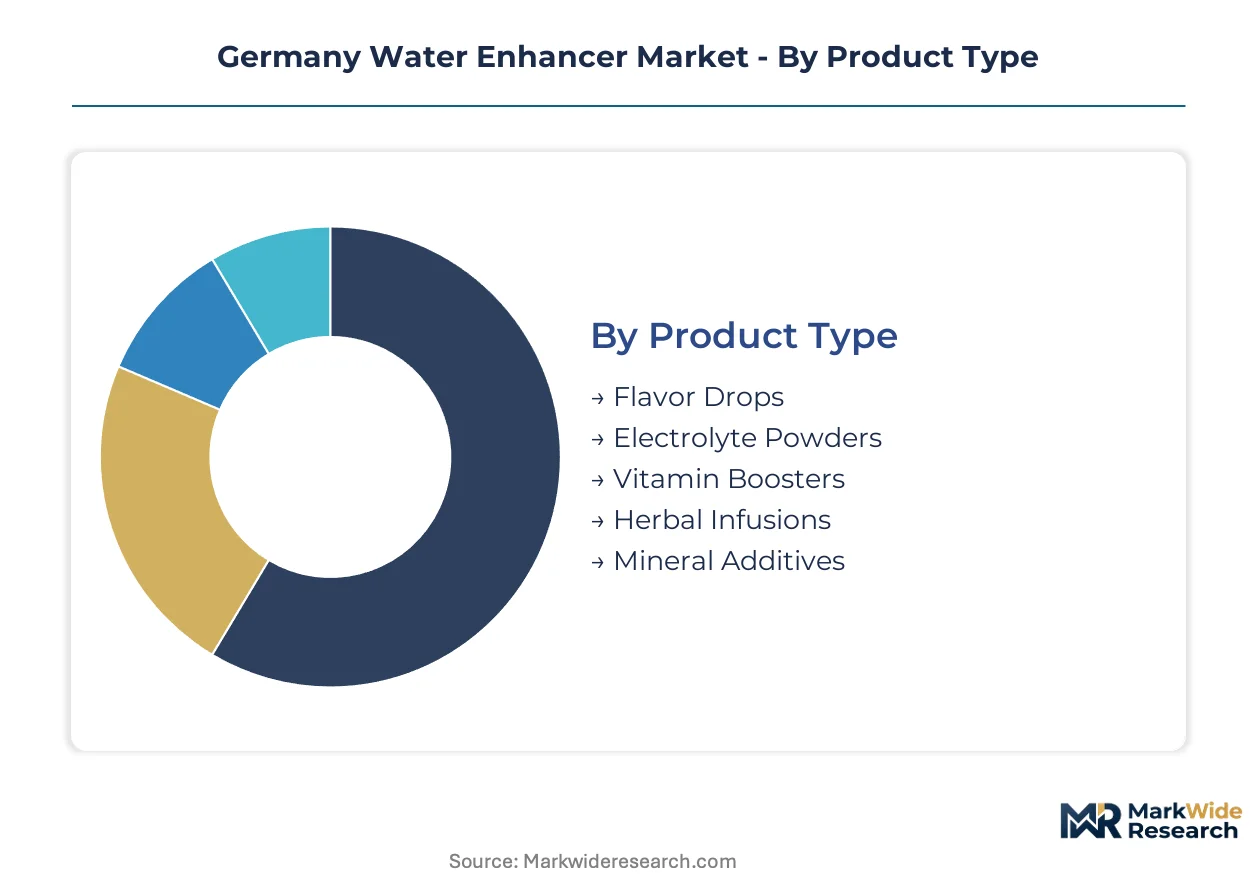
Water enhancer segmentation in Germany reflects divergent hydration philosophies across consumer archetypes. Product formats, purchase channels, and use cases fragment along lines of convenience, performance, and preventive health investment.
Product Type:
Standardization dominates mass-market flavor drops while customization accelerates in functional powders targeting specific physiological outcomes.
- Flavor Drops:Concentrated liquid formulations with dilution ratios typically ranging 1:50 to 1:80, relying on artificial and natural flavor compounds. Demand clusters in discount retail channels across North Rhine-Westphalia where price-sensitive households seek bottled water alternatives.
- Electrolyte Powders:Sodium, potassium, and magnesium blends with microencapsulation technology for ambient stability. Amateur athletes in Munich and Hamburg gym clusters drive volume through sports nutrition crossover, with summer distribution eliminating cold-chain dependencies.
- Vitamin Boosters:Ascorbic acid and B-complex fortified soluble powders. Immune positioning resonates with senior households in Berlin metropolitan districts.
- Herbal Infusions:Botanical extracts from chamomile, ginseng, and hibiscus targeting relaxation and adaptogenic claims.
- Mineral Additives:Calcium and magnesium concentrates for tap water mineralization, prevalent in southern German regions with soft water infrastructure.
Leading the category by volume: Electrolyte Powders. Growing fastest: Vitamin Boosters.
Distribution Channel:
Margin capture shifts from shelf-slotting economics toward direct relationship models as subscription platforms erode traditional retail intermediation.
- Supermarkets:Edeka, Rewe, and Aldi Süd chains dominate impulse purchase volume with dedicated beverage-aisle placement. Berlin and Munich hypermarkets command highest SKU density for trial-size formats.
- Online Retailers:Amazon.de and specialized sports nutrition platforms command the highest margin pool through elimination of intermediary shelf fees. Auto-ship subscriptions concentrate customer lifetime value among Hamburg and Frankfurt urban professionals.
- Specialty Stores:Organic food retailers and fitness boutiques curate premium-positioned clean-label assortments.
- Pharmacies:Apotheken channels emphasize medical-grade electrolyte rehydration with BfR-compliant labeling.
- Direct Sales:Corporate wellness contracts and gym partnerships bypass retail slotting entirely.
Volume concentration: Supermarkets. Margin expansion: Online Retailers.
Customer Type:
Demographic targeting hardens around life-stage hydration needs, with professional stress and athletic performance commanding premium positioning.
- Health Enthusiasts:Consumers prioritizing ingredient transparency and clean-label positioning across organic retail channels. This segment absorbs the steepest expansion trajectory as preventive wellness investment displaces reactive healthcare spending.
- Athletes:Amateur and semi-professional competitors seeking electrolyte replacement without sugar-sweetened beverage calories. Concentrated demand in metropolitan gym clusters of Berlin, Munich, and Hamburg.
- Seniors:Vitamin-fortified and mineral-enhanced formats targeting medication-interaction-conscious hydration.
- Busy Professionals:Microdrink cubes and single-serve portability for workplace consumption.
- Students:Price-optimized flavor drops for budget-constrained hydration alternatives.
Fastest-expanding segment: Health Enthusiasts. Volume anchor: Athletes.
Application:
Use-case fragmentation mirrors the broader functional beverage migration from refreshment toward physiological outcome claims.
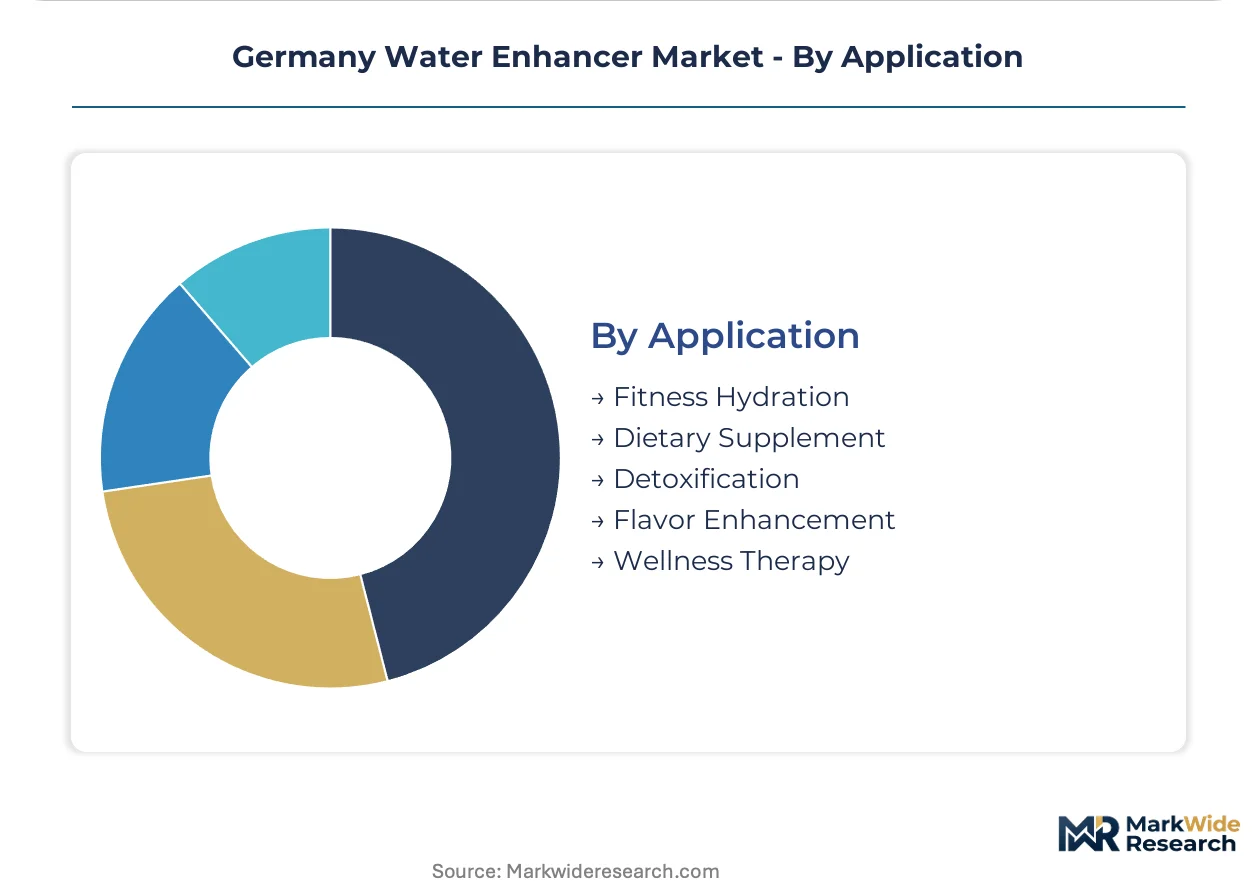
- Fitness Hydration:Electrolyte replacement during and post-exercise, commanding the largest revenue share through sports nutrition channel integration.
- Dietary Supplement:Vitamin and mineral fortification for nutritional gap coverage, fastest-climbing application as immunity positioning resonates across age cohorts.
- Detoxification:Herbal and antioxidant blends targeting liver support and metabolic claims.
- Flavor Enhancement:Palatability improvement for tap water consumption, baseline volume driver in price-sensitive segments.
- Wellness Therapy:Adaptogenic and nootropic positioning for stress management and cognitive support.
Revenue concentration: Fitness Hydration. Application gaining share fastest: Dietary Supplement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors Germany's water enhancer demand through its dense fitness studio concentration and professional workforce seeking workplace hydration solutions. The capital's organic retail channel penetration exceeds national averages by a significant margin.
Bavaria
Munich's amateur athlete population drives electrolyte powder consumption through sports nutrition crossover demand. The BfR's food supplement guidelines govern labeling claims for products distributed through Bavarian pharmacy chains. Ingredient formulators cluster around the Greater Munich area to access pharmaceutical-grade glass packaging suppliers.
North Rhine-Westphalia
Discount retail dominance in Cologne and Düsseldorf corridors channels price-sensitive households toward basic flavor drops. The EU Single-Use Plastics Directive accelerates format transitions in this manufacturing-heavy region. Logistics hubs near the Dutch border enable efficient distribution of concentrated enhancer formats across Benelux markets.
Hamburg
Urban professionals in Hamburg's banking and media sectors sustain subscription replenishment models for microdrink cubes. The city's port infrastructure supports aluminum tube imports for compliant packaging transitions. Fitness culture concentration in HafenCity and Eppendorf districts generates clustered electrolyte demand.
Baden-Württemberg
Stuttgart's automotive workforce exhibits strong preventive health investment patterns favoring vitamin boosters. The region's food technology research institutes support microencapsulation development for heat-stable formulations. Clean-label positioning resonates strongly with organic retail channels in Freiburg and Heidelberg university cities.
Germany Water Enhancer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Germany's water enhancer landscape. The vendor base fragments between established beverage conglomerates and specialized supplement formulators. Three strategic archetypes dominate: sugar-free formulation specialists, broad-distribution supermarket anchors, and compact-format urban professionals. M&A activity concentrates on acquiring microencapsulation capabilities, while strategic partnerships with circular packaging suppliers accelerate compliance ahead of EU mandates.
Among German-registered entities, BOLERO GmbH and Waterdrop Microdrink GmbH occupy distinct positioning archetypes. BOLERO GmbH exemplifies the sugar-free mass-market specialist with discount channel penetration. Waterdrop Microdrink GmbH represents the compact-format premium tier targeting metropolitan professionals. The Kraft Heinz Company anchors the multinational conglomerate segment through supermarket distribution scale. These three entities collectively illustrate the competitive tension between formulation expertise, format innovation, and channel reach that defines category dynamics.
| Leading Market Players |
|---|
| BOLERO GmbH |
| Dyla LLC |
| The Kraft Heinz Company |
| Wisdom Natural Brands |
| Salto GmbH |
| Waterdrop Microdrink GmbH |
| Holy Energy GmbH |
| Mijuwi GmbH |
| BRITA SE |
| Others |
Supply & Pricing Matrix
Microencapsulation technology for heat-stable vitamin preservation is simultaneously compressing per-unit production costs and concentrating supplier power among German pharmaceutical-grade formulators. The shift from spray-drying to ambient-stable electrolyte powders eliminates cold-chain dependencies while creating single-source dependencies on Bavarian packaging clusters.
Pricing Analysis
Value-based pricing anchored to physiological outcome claims commands shelf premiums in organic retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient transparency certification and microencapsulation sophistication. Cost compression in economy flavor drops is intensifying because Mediterranean citrus harvest volatility squeezes natural extract margins. Students represent the most price-sensitive buyer archetype, while health enthusiasts absorb the steepest premiums for clean-label positioning.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian pharmaceutical-grade glass manufacturers serving premium microdrink cube formats. Raw material dependencies draw from Mediterranean citrus belt harvests, Chinese botanical extract processors, and domestic aluminum tube suppliers. Tariff exposure on aluminum imports from non-EU sources threatens packaging cost stability. Distribution runs through Edeka and Rewe supermarket networks for impulse volume, with Amazon.de and direct-to-consumer platforms capturing subscription replenishment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive functions as a cost-of-compliance moat, elevating capital requirements for packaging transitions and advantaging incumbents with established circular supply partnerships.
For Market Incumbents: Cement market position by acquiring microencapsulation capabilities from Stuttgart-area food technology institutes before capability scarcity intensifies. Expand aluminum tube and glass vial sourcing contracts ahead of EU packaging waste regulation enforcement timelines. Channel control through direct-to-consumer subscription platforms represents the priority defensive lever against retail slotting fee erosion. For New Entrants and Emerging Players: The EU Green Deal's packaging waste directives in Germany open a window for concentrated drop formats that eliminate single-use plastic entirely. Eastern federal states of Saxony and Thuringia present the most penetrable geography relative to western per-capita benchmarks. Corporate wellness contracts bypass retail intermediation entirely and offer the most viable go-to-market angle for asset-light entrants. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by beverage conglomerates seeking sugar-free formulation expertise or microencapsulation capabilities. Long-term viability favors formulators with BfR pre-approval relationships and circular packaging partnerships already operational. Watch for EFSA health claim authorization timelines as the critical inflection signal for immunity-positioned vitamin booster valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capability Acquisition | Heat-stable vitamin preservation enables ambient distribution through Rewe and Edeka networks without refrigeration. |
| Circular Packaging Partnership | Aluminum tube and glass vial transitions satisfy EU Green Deal recycled content mandates ahead of enforcement. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models concentrate customer lifetime value among Hamburg and Frankfurt urban professionals. |
| Corporate Wellness Channel Expansion | Workplace hydration contracts bypass supermarket slotting fees and establish recurring revenue anchors. |
| Eastern Federal States Distribution Buildout | Saxony and Thuringia penetration closes the per-capita consumption gap with Berlin and Munich benchmarks. |
Research Methodology
Multi-period observation of SKU proliferation rates, pricing tier migration, and channel shift patterns anchored the trend analysis, supplemented by interviews with category buyers at Edeka and Rewe, formulation scientists at Stuttgart food technology institutes, procurement leads at aluminum packaging suppliers, and regulatory affairs specialists navigating BfR compliance timelines. Secondary validation drew from EU packaging waste regulation filings, EFSA health claim authorization databases, Nielsen retail audit data for German beverage categories, and customs records tracking botanical extract imports. Bottom-up segment sizing triangulated against top-down category value estimates.
Input-output matrices modeled volume and value trajectories across product type, distribution channel, customer archetype, and application dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate convergence analysis. Forecast inputs incorporated EU Single-Use Plastics Directive implementation pace, microencapsulation technology adoption curves in North Rhine-Westphalia sports nutrition manufacturing, and subscription replenishment model penetration rates among urban professionals.
Caveats apply where EFSA health claim authorization delays, Mediterranean citrus harvest failures, or aluminum supply disruptions could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Veratrole Market