
 Japan Water Enhancer Market | 2026-2036
Japan Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Water Enhancer Market Foresight
A capital-intensity divergence between multinational beverage conglomerates and domestic pharmaceutical-backed entrants is bifurcating competitive dynamics in Japan's water enhancer landscape. PepsiCo Inc leverages its global procurement infrastructure to sustain cost advantages across liquid concentrate lines. Otsuka Pharmaceutical Co., Ltd anchors its position through pharmacy-linked distribution networks that competitors cannot easily replicate.
Water enhancers comprise concentrated flavoring systems—typically acidulants, natural or artificial sweeteners, and stabilizers dissolved in water or spray-dried into powders—designed to transform plain water into palatable, low-calorie beverages at point of consumption. Liquid concentrates currently dominate shelf space in Japanese supermarkets due to established consumer familiarity with dilutable formats, though powdered mixes represent the fastest-expanding segment as commuters prioritize pocket-sized portability. Single-serve packs command premium placement in convenience stores, where turn velocity outperforms bulk jar alternatives.
METI's consumer product safety guidelines intersect with Japan's Food Sanitation Act enforcement by the Ministry of Health, Labour and Welfare to mandate precise allergen labeling and additive quantification on water enhancer packaging. JIS standards for food-contact materials further constrain pouch and bottle substrate selection, elevating compliance costs for imported formulations. Stakeholders must monitor whether upcoming revisions to Japan's Plastic Resource Circulation Act will compel format redesigns or spur investment in biodegradable single-serve packaging before regulatory deadlines crystallize.
Market Dynamics
Japan's water enhancer sector is compressing around portability mandates as metropolitan commuters reject bulky liquid bottles for pocket-sized powder sachets, forcing format redesigns across manufacturing lines.
Growth Catalysts
- Food Sanitation Act revisions:METI and the Ministry of Health, Labour and Welfare now mandate granular additive disclosure, creating competitive advantage for domestic formulators with cleaner-label capabilities.
- Single-serve powder innovation:Spray-drying technology advances enable stable flavor encapsulation without refrigeration, unlocking convenience store distribution density previously unreachable for liquid concentrates.
- Tokyo-Osaka corridor demand:Young professionals in these metropolitan clusters sustain premium velocity for on-the-go hydration solutions with reduced sugar content.
Market Restraints
- Stevia and monk fruit input volatility:Natural high-intensity sweetener supply concentrates in Southeast Asian extraction facilities, exposing Japanese formulators to climate-driven harvest fluctuations.
- JIS food-contact material compliance:Substrate selection for single-serve pouches faces restrictive migration testing protocols that elevate packaging costs above regional competitors.
- Plastic Resource Circulation Act pressure:Upcoming biodegradability mandates threaten existing petroleum-based flexible packaging investments before alternatives achieve cost parity.
Strategic Opportunities
- Pharmacy-linked wellness positioning:Otsuka Pharmaceutical's distribution template demonstrates viable pathways for functional hydration claims targeting aging demographics in suburban prefectures.
- Dual carbon goal alignment:METI incentives for packaging lightweighting reward format shifts from liquid concentrates to concentrated powders with reduced logistics emissions.
- Convenience store channel expansion:Turn velocity data from Lawson and 7-Eleven outlets supports dedicated cooler placement for premium single-serve lines.
Industry Challenges
- Flavor chemist talent scarcity:Japanese universities produce insufficient formulation specialists trained in acidulant-stabilizer interactions for clean-label applications.
- Legacy liquid concentrate retooling:Existing bottling infrastructure requires capital-intensive conversion to powder filling lines with nitrogen-flush sealing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Water Enhancer Market |
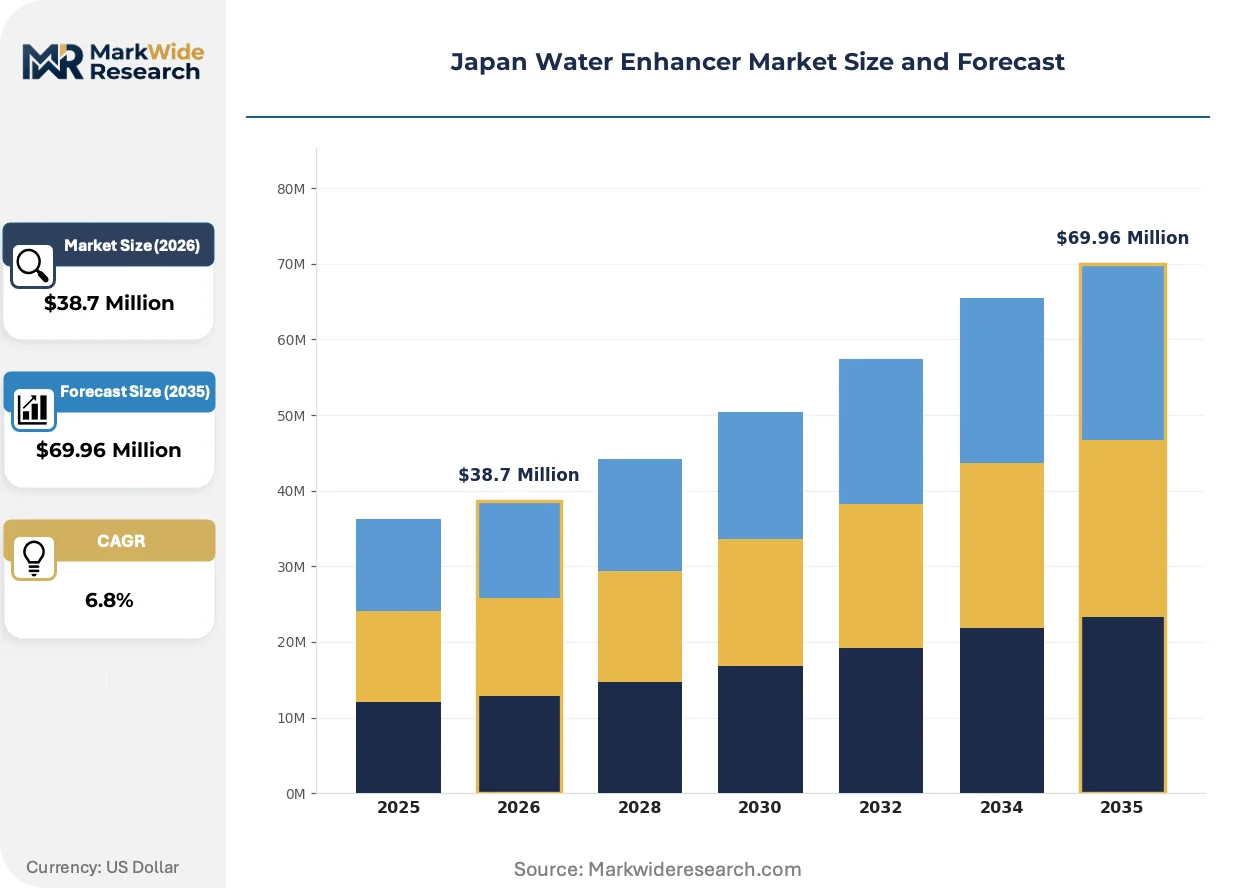
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrates, Powdered Mixes, Ready-to-Drink, Drops Flavor Profile: Citrus, Berry, Tropical, Herbal Packaging Type: Single-Serve Packs, Bottles, Pouches, Jars Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | PepsiCo Inc, The Coca-Cola Company, Nestle S.A., The Kraft Heinz Company, Britvic Plc, Otsuka Pharmaceutical Co., Ltd, Dyla LLC, Kraft Foods, Jel Sert, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Water Enhancer Market Shifts & Advancements
Active reformulation is compressing traditional sweetener systems as manufacturers respond to simultaneous pressures from clean-label consumer preference and tightening additive disclosure mandates under Japanese food law.
Spray-dried natural flavor encapsulation is displacing liquid concentrate dominance in Japanese retail channels. Commuters in Tokyo's Yamanote Line corridor now prioritize sachet formats that dissolve without stirring. This displacement is collapsing shelf-space allocation for dilutable bottles in metropolitan convenience stores.
METI's Plastic Resource Circulation Act enforcement is accelerating substrate innovation. Manufacturers must demonstrate biodegradability or recyclability pathways for single-serve pouches by statutory deadlines. Powder formats gain regulatory advantage through reduced packaging mass per serving compared to liquid alternatives.
Channel concentration around convenience retail is fragmenting traditional supermarket dominance. Lawson, FamilyMart, and 7-Eleven now dictate velocity-based shelf placement algorithms that favor high-margin single-serve units. This shift is most visible in Osaka's Umeda district, where office-worker foot traffic sustains multiple daily purchase occasions.
Japan Water Enhancer Market Segmentation
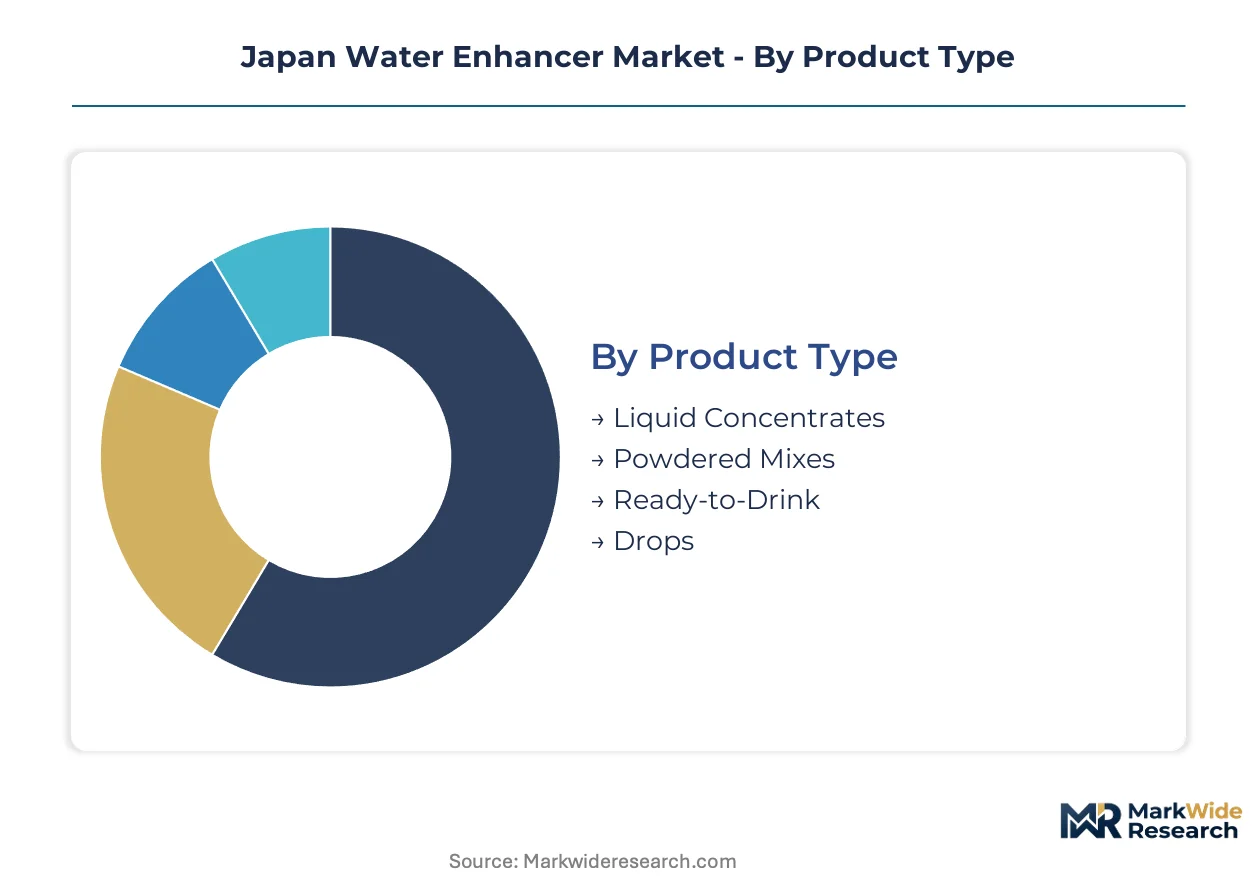
Format selection in Japan's water enhancer sector determines regulatory exposure under METI packaging guidelines and JIS food-contact material standards. Each segment carries distinct compliance burdens and channel access profiles that shape competitive positioning.
Product Type:
METI's Plastic Resource Circulation Act enforcement creates divergent compliance pathways across formulation formats, with liquid concentrates facing heavier substrate restrictions than dried alternatives.
- Liquid Concentrates:Acidulant-stabilizer emulsions suspended in aqueous bases require multilayer barrier bottles to prevent oxidation. Established shelf presence in Tokyo metropolitan supermarkets sustains volume, though JIS migration testing elevates packaging costs above powder alternatives.
- Powdered Mixes:Spray-dried flavor encapsulation enables nitrogen-flush sachet sealing without refrigeration. Single-serve portability aligns with Osaka commuter corridors where turn velocity at Lawson and FamilyMart outlets outperforms liquid alternatives.
- Ready-to-Drink:Pre-diluted formulations eliminate consumer mixing but multiply logistics emissions and shelf space requirements.
- Drops:Ultra-concentrated pipette formats target precision dosing for wellness-positioned consumers in pharmacy channels.
Established volume favors liquid concentrates; emerging adoption favors powdered mixes.
Flavor Profile:
Clean-label formulation constraints under Food Sanitation Act revisions reshape viable flavor pathways, with natural extract documentation requirements favoring certain botanical categories over synthetic alternatives.
- Citrus:Yuzu and sudachi extracts command premium positioning in Kanto-region convenience stores. Domestic sourcing from Wakayama and Ehime prefectures reduces supply chain exposure to Southeast Asian climate volatility.
- Berry:Acai and blueberry concentrates rely heavily on imported raw materials subject to harvest fluctuation.
- Tropical:Mango and passionfruit profiles target younger demographics in Osaka's Umeda district with vacation-association marketing.
- Herbal:Matcha and mugwort variants leverage indigenous ingredient recognition for functional hydration claims in suburban pharmacy networks.
Geographic sourcing concentration favors citrus; import dependency constrains berry expansion.
Packaging Type:
Biodegradability mandates under Japan's Plastic Resource Circulation Act force substrate innovation timelines that vary dramatically by format mass and material complexity.
- Single-Serve Packs:Flexible film sachets minimize material per serving and enable dedicated cooler placement at 7-Eleven outlets. Powder-compatible formats gain regulatory advantage through reduced packaging mass versus liquid alternatives.
- Bottles:PET and glass containers dominate liquid concentrate retail but face statutory pressure to demonstrate circularity pathways.
- Pouches:Stand-up flexible formats occupy intermediate shelf space between sachets and bottles.
- Jars:Bulk powder containers sustain household pantry stocking in suburban prefectures with lower convenience store density.
Channel velocity favors single-serve packs; household penetration favors jars.
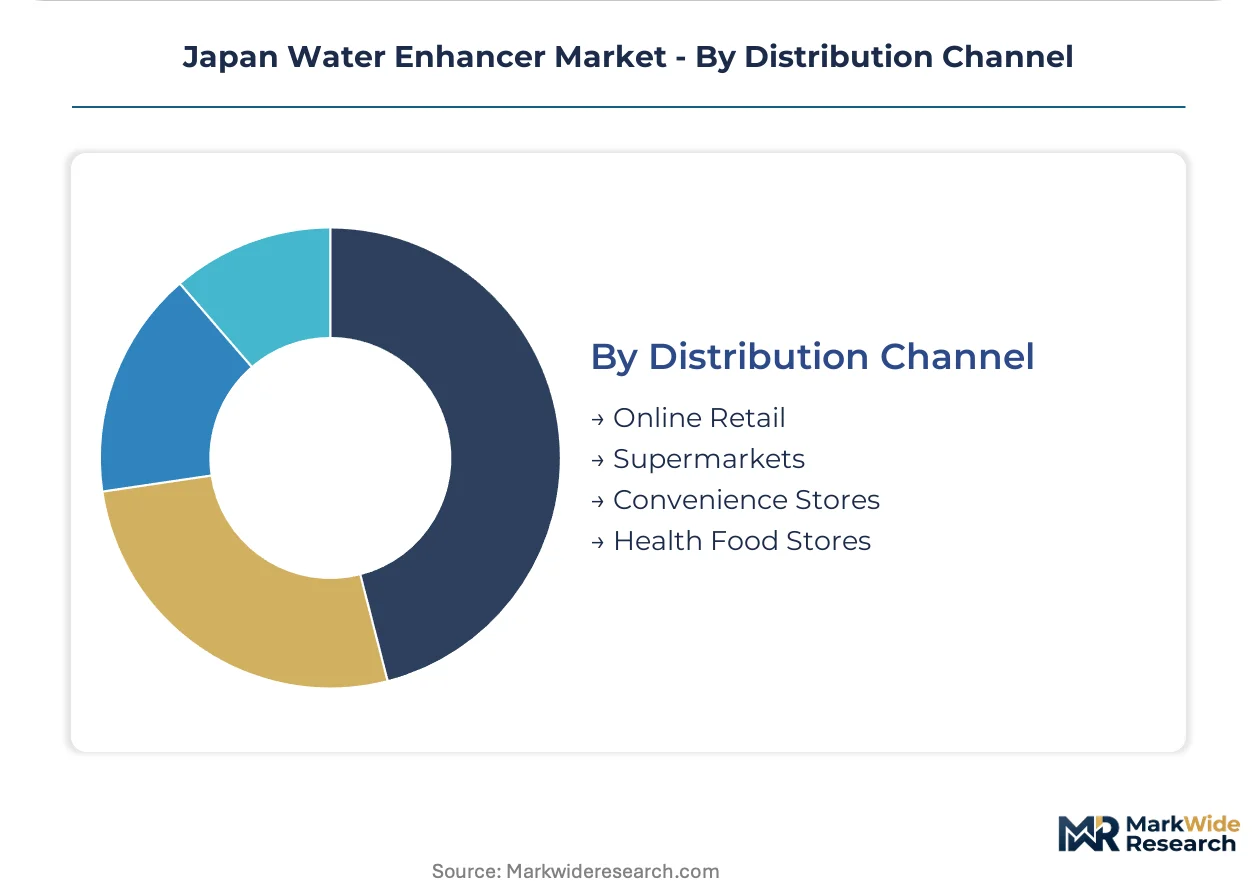
Distribution Channel:
Foot traffic patterns across Tokyo-Osaka metropolitan corridors concentrate purchase occasions in formats that reward immediate consumption over planned stocking.
- Convenience Stores:Lawson, FamilyMart, and 7-Eleven algorithms prioritize high-margin single-serve velocity. Office-worker corridors in Tokyo's Yamanote Line sustain multiple daily purchase occasions for pocket-sized formats.
- Online Retail:Subscription models and bulk purchasing attract price-sensitive households in peripheral prefectures.
- Supermarkets:Dilutable liquid concentrates retain residual shelf allocation for planned weekly shopping trips.
- Health Food Stores:Pharmacy-linked positioning enables functional hydration claims targeting aging demographics.
Purchase frequency favors convenience stores; basket size favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's water enhancer trade flows reflect a net import position in liquid concentrates balanced by domestic powder manufacturing strength. Metropolitan consumption clusters in Tokyo and Osaka absorb the majority of inbound volume. Regional production capacity concentrates in pharmaceutical-adjacent facilities with existing spray-drying infrastructure.
Kanto/Tokyo
Young urban professionals in the Yamanote Line corridor sustain premium single-serve velocity at Lawson and 7-Eleven outlets. METI's Plastic Resource Circulation Act enforcement pressures local packagers toward biodegradable substrate trials. Shinjuku and Shibuya districts host the densest convenience store placement of pocket-sized powder formats.
Kansai/Osaka
Office-worker foot traffic in Umeda district generates multiple daily purchase occasions for commuter-oriented hydration solutions. The Ministry of Health, Labour and Welfare's Food Sanitation Act revisions mandate granular additive disclosure that favors domestic formulators. Osaka's pharmaceutical manufacturing heritage supports local encapsulation technology development.
Chubu/Nagoya
Manufacturing supply chains in Aichi Prefecture connect spray-drying equipment vendors to water enhancer producers seeking powder line conversion. JIS food-contact material standards constrain substrate selection for regional packaging converters. Nagoya's logistics hub position enables efficient distribution to peripheral prefectures with lower convenience store density.
Kyushu
Citrus cultivation in Wakayama and Ehime prefectures supplies yuzu and sudachi extracts for clean-label flavor positioning. Regional agricultural cooperatives negotiate direct supply contracts with formulators seeking domestic sourcing advantages. Fukuoka's retail corridor tests pharmacy-linked wellness positioning for aging demographic segments.
Hokkaido
Lower convenience store penetration relative to metropolitan Japan sustains bulk jar demand for household pantry stocking. Cold-chain logistics constraints disadvantage liquid concentrate distribution in peripheral northern markets. Sapporo's retail landscape favors online subscription models for price-sensitive consumers.
Japan Water Enhancer Market Competitive Landscape
Concentration sits with multinational beverage conglomerates and domestic pharmaceutical-backed entrants in a bifurcated structure. PepsiCo Inc leverages global procurement infrastructure against Otsuka Pharmaceutical Co., Ltd's pharmacy-linked distribution networks. Two strategic archetypes dominate: global scale players with cost advantages and domestic wellness-positioned specialists with channel control. Competitive moves center on format conversion to powder lines and biodegradability compliance investments.
Within the multinational tier, PepsiCo Inc and The Coca-Cola Company exemplify scale-driven positioning through established liquid concentrate shelf presence. Otsuka Pharmaceutical Co., Ltd anchors the domestic pharmaceutical-backed archetype with distribution pathways competitors cannot easily replicate. Nestle S.A. and The Kraft Heinz Company occupy intermediate positions between global scale and regional specialization. These players collectively represent the competitive tension between procurement efficiency and channel-specific access control.
| Leading Market Players |
|---|
| PepsiCo Inc |
| The Coca-Cola Company |
| Nestle S.A. |
| The Kraft Heinz Company |
| Britvic Plc |
| Otsuka Pharmaceutical Co., Ltd |
| Dyla LLC |
| Kraft Foods |
| Jel Sert |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of finished-goods inventory in Tokyo metropolitan distribution centers signals how powder-format conversion timelines compress pricing power toward domestic formulators with captive spray-drying capacity. This lead-time band concentrates margin capture with Otsuka Pharmaceutical and PepsiCo's localized operations while elevating working-capital burdens for import-dependent liquid concentrate lines.
Pricing Analysis
Customization-premium spreads of clean-label formulations against standard artificial-sweetener alternatives command shelf-space premiums at Lawson and 7-Eleven outlets. Three-tier pricing structure across premium, standard, and economy levels stratifies by sweetener documentation depth under Food Sanitation Act mandates. Pricing pressure stems from stevia and monk fruit input volatility originating in Southeast Asian extraction facilities. Price-sensitive suburban households in Hokkaido and Kyushu favor bulk jar formats, while metropolitan commuters absorb single-serve premiums.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Japanese formulators to container-rate volatility for Southeast Asian natural sweetener shipments. Supply concentration rests on Thailand and Indonesia for stevia leaf processing, with domestic encapsulation technology concentrated in Aichi Prefecture pharmaceutical facilities. Raw material dependencies span acidulants from Chinese chemical processors, flavor extracts from Wakayama citrus cooperatives, and barrier films from South Korean substrate converters. Single-source vulnerability concentrates in natural high-intensity sweetener extraction. Distribution runs through convenience store algorithms at Lawson, FamilyMart, and 7-Eleven that prioritize turn velocity over margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's water enhancer sector reads as a service-attach opportunity where subscription-based flavor curation and personalized hydration coaching expand faster than hardware-equivalent powder sales. Recurring-revenue layers from direct-to-consumer replenishment programs outpace one-time sachet purchases in customer lifetime value metrics.
For Market Incumbents: Secure pharmacy-linked distribution networks against wellness-positioned entrants by deepening functional hydration claims targeting suburban aging demographics. Defend shelf position at Lawson and 7-Eleven through exclusive cooler placement agreements that block competitor access. Threat substitution from ready-to-drink functional waters demands accelerated clean-label reformulation investment. For New Entrants and Emerging Players: Anchor in Hokkaido's underpenetrated convenience store corridor where bulk jar demand sustains household pantry stocking and online subscription models reduce customer acquisition costs. Target Fukuoka's pharmacy-linked wellness positioning for aging demographic segments with matcha and mugwort functional variants. Go-to-market angle: direct-to-consumer sampling programs bypassing established retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across powder-format manufacturing as spray-drying equipment achieves modular scale. Long-term viability favors domestic formulators with JIS-compliant packaging capabilities and METI biodegradability pathway alignment. Acquisition target archetype: mid-tier encapsulation specialists with existing pharmaceutical infrastructure. Signal to watch: convenience store velocity data from Tokyo-Osaka corridors indicating format preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | Food Sanitation Act disclosure mandates reward domestic formulators with indigenous ingredient sourcing. |
| Biodegradable Packaging Transition | Plastic Resource Circulation Act deadlines force substrate innovation before alternatives achieve cost parity. |
| Pharmacy Channel Expansion | Otsuka Pharmaceutical's distribution template demonstrates viable functional hydration claim pathways. |
| Convenience Store Algorithm Optimization | Lawson and 7-Eleven velocity-based placement favors high-margin single-serve powder formats. |
| Direct-to-Consumer Subscription Launch | Recurring-revenue models bypass retail margin capture and build proprietary customer data assets. |
Research Methodology
Cross-validation between convenience store buyer interviews and METI packaging guideline filings anchors the qualitative findings on format preference shifts. Primary fieldwork with flavor chemists at domestic encapsulation facilities, category managers at Lawson and FamilyMart, and procurement leads at Aichi Prefecture pharmaceutical plants combined with secondary validation from JIS standards documentation, Food Sanitation Act revision drafts, and Plastic Resource Circulation Act implementation notices. Bottom-up powder production estimates and top-down retail velocity data triangulate market sizing.
Sensitivity analysis across sweetener input cost scenarios and biodegradability compliance timelines tests forecast robustness. The analytical framework segments by format type, flavor profile, packaging substrate, and distribution channel across the projection horizon. CAGRs derive from historical convenience store velocity trends extrapolated through format conversion curves and regulatory deadline impacts. Industry-specific inputs include spray-drying capacity utilization at pharmaceutical-adjacent facilities and convenience store cooler placement algorithm weights.
Underlying assumptions cover METI enforcement timelines for biodegradability mandates, with deviation risk concentrated in Southeast Asian climate volatility affecting natural sweetener harvests. Practitioners should keep alternative scenarios live as Food Sanitation Act disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Mexico Water Enhancer Market