
 Mustard Seeds Market | 2026-2036
Mustard Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Mustard Seeds Market Analysis
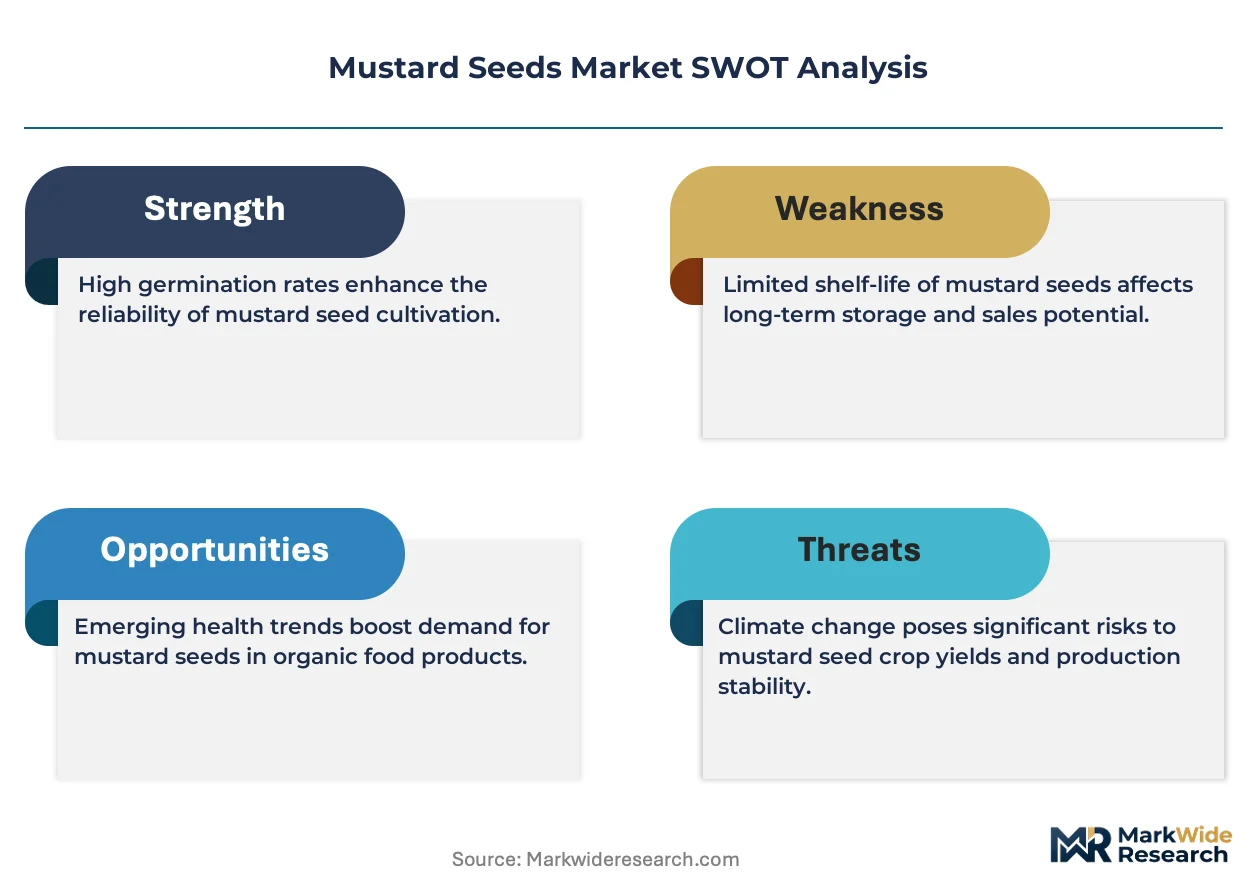
The EU Green Deal is expanding sustainable agriculture requirements for oilseed crops, tightening residue limits and pushing buyers toward certified supply chains. Cargill leverages its North American origination network to secure premium yellow mustard contracts. McCormick & Company anchors its flavor portfolio on consistent seed quality from long-term grower partnerships. Megha Corporation specializes in Indian brown mustard exports to Middle Eastern processors.
Mustard seeds are the dried, spherical fruits of Brassica juncea and related species, containing 25-40% fixed oil and characteristic glucosinolate compounds that hydrolyze into pungent isothiocyanates upon milling or moisture contact. The seeds undergo cleaning, drying, and either cold-pressing for oil extraction or grinding into powder for condiment production. Yellow mustard dominates commercial volume due to its milder flavor profile and broader food industry acceptance, while brown mustard commands premium positioning in Asian seasoning applications where higher allyl isothiocyanate content delivers sharper heat. Oil extraction represents the fastest-growing end use as biodiesel and renewable chemical feedstock demand redirects crush capacity from edible oils toward industrial oleochemistry.
The USDA enforces graded standards for mustard seed cleanliness and oil content that determine export eligibility from major US growing regions. India's FSSAI mandates pesticide residue testing and labeling transparency for domestic spice distribution, while the EU's REACH framework governs chemical inputs in processed mustard derivatives entering European markets. Stakeholders must monitor evolving biofuel blending mandates and food safety certification schemes to align crush capacity with the most profitable demand channels.
Market Dynamics
Processing clusters in Gujarat and Rajasthan are consolidating procurement power, forcing upstream suppliers to adopt FSSAI-mandated traceability systems or lose access to India's dominant crush capacity. This concentration is reshaping contract structures across the value chain.
Growth Catalysts
- Biodiesel blending mandates:Industrial oleochemistry demand is redirecting crush capacity toward non-edible oil extraction, creating new offtake channels for high-erucic acid mustard varieties.
- EU Green Deal residue limits:Tighter pesticide thresholds for oilseed imports are accelerating certified supply chain adoption among European food manufacturers seeking compliant yellow mustard sources.
- Specialty condiment procurement:Organic yellow mustard varieties are commanding premium contracts as clean-label positioning spreads through North American and European retail channels.
Market Restraints
- Input cost volatility:Fertilizer and irrigation energy costs swing with crude oil benchmarks, compressing margins for rainfed growers in Rajasthan's semi-arid zones.
- Supply concentration risk:Over half of global brown mustard processing capacity sits within a 200-kilometer radius of Gujarat's Kandla port, creating single-point vulnerability.
- Regulatory friction:India's FSSAI pesticide residue testing protocols add 15-20 days to import clearance timelines, freezing working capital for Middle Eastern traders.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya lack domestic mustard processing infrastructure, creating first-mover openings for packaged condiment exporters with halal certification.
- Regulatory tailwind:The EU's REACH framework for chemical inputs in processed derivatives favors suppliers with pre-registered substance dossiers, locking out informal competitors.
- Technology convergence:Near-infrared spectroscopy for oil content assessment is converging with blockchain lot tracking, enabling real-time quality verification for distant buyers.
Industry Challenges
- Skill gap in traceability systems:Smallholder cooperatives lack personnel trained in FSSAI-compliant documentation software, delaying market access upgrades.
- Capex intensity for cold-press retrofitting:Shifting from solvent extraction to mechanical pressing for premium oil grades requires stainless steel equipment investments that exhaust working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mustard Seeds Market |
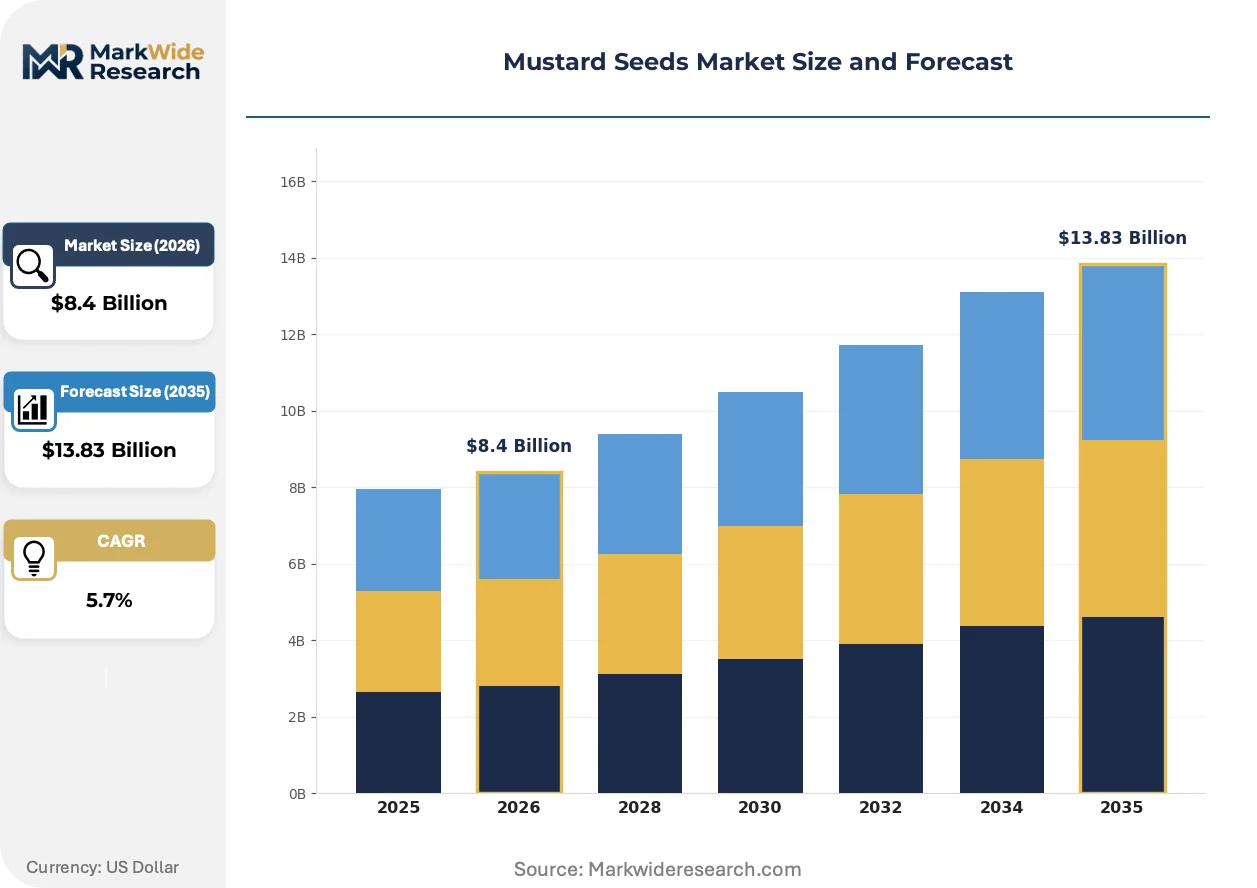
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Mustard, Yellow Mustard, Brown Mustard, Others End Use Industry: Food Industry, Oil Extraction, Animal Feed, Biopesticides Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales Application: Cooking, Seasoning, Food Preservation, Medicinal Use |
| Companies Covered | Archer Daniels Midland Company, Cargill, McCormick & Company, Megha Corporation, Sakai Spice, Kaveri Seeds, Sun Impex, ITC, Organic Products India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mustard Seeds Market Emerging Trajectories
Digital quality verification and sustainability certification are rewriting procurement criteria across mustard seed value chains. Buyers now prioritize transparent origin data over spot-price arbitrage.
Near-infrared spectroscopy for rapid oil content and glucosinolate assessment is converging with mobile-based farmer payment systems. Large processors in Saskatchewan and Alberta are deploying handheld devices at farmgate intake points, cutting laboratory turnaround from days to minutes. This compression is enabling dynamic pricing tied to actual compositional quality rather than visual grading alone.
REACH registration requirements for isothiocyanate derivatives are tightening documentation burdens on European importers. Processed mustard products entering EU markets now require full substance dossiers covering hydrolysis byproducts. Specialty chemical manufacturers are responding by segregating crush streams into food-grade and industrial-grade channels with separate chain-of-custody records.
Direct contracting between processors and grower cooperatives is displacing spot-market intermediation in North American origination territories. Large condiment manufacturers are offering three-year offtake guarantees in exchange for prescribed agronomic practices and exclusive variety planting. This shift is most visible across Montana and North Dakota, where identity-preserved yellow mustard contracts now cover a majority of planted acreage.
Mustard Seeds Market Segmentation
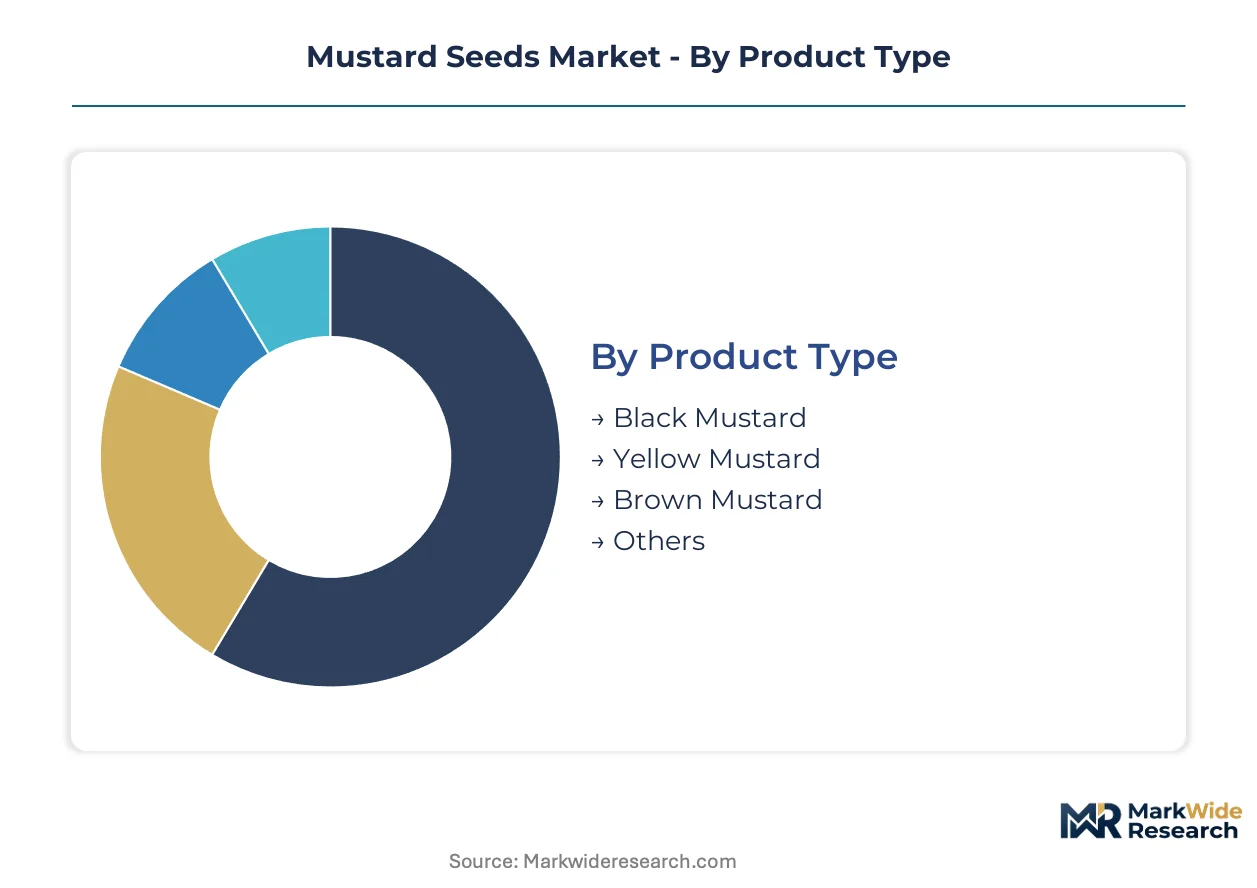
Mustard seed procurement patterns diverge sharply across buyer categories, with industrial crushers prioritizing oil content specifications while condiment manufacturers fixate on glucosinolate profiles and color consistency. Understanding these segment-specific purchasing criteria unlocks pricing power and contract security for suppliers navigating fragmented downstream channels.
Product Type:
Buyers differentiate seed varieties primarily by pungency intensity and oil yield, with industrial processors favoring high-erucic acid brown strains while retail condiment brands specify milder yellow grades for mass-market palatability.
- Yellow Mustard:Brassica hirta varieties contain lower allyl isothiocyanate concentrations, producing the mild, bright condiments dominating North American supermarket shelves. Saskatchewan processors contract identity-preserved acreage for consistent color and heat profiles demanded by CPG brand owners.
- Brown Mustard:Brassica juncea seeds deliver sharper pungency from higher sinigrin content, anchoring Asian seasoning applications and industrial oleochemistry feedstocks. Gujarat's Kandla corridor crush capacity concentrates procurement for Middle Eastern and European oil extraction demand.
- Black Mustard:Brassica nigra offers intermediate heat characteristics with historical dominance in traditional European medicine preparations.
- Others:Specialty heritage varieties and experimental crosses serve niche organic condiment producers seeking differentiation.
Yellow mustard leads volumes today; brown mustard is gaining share fastest.
End Use Industry:
Volume concentration varies dramatically by processing intensity, with food manufacturers requiring food-grade certification chains while biofuel blenders prioritize cost-efficient oil yields over organoleptic purity.
- Oil Extraction:Cold-press and solvent extraction routes produce edible oils, biodiesel feedstocks, and renewable chemical precursors. EU Green Deal blending mandates are redirecting crush capacity toward high-erucic acid varieties for industrial oleochemistry.
- Food Industry:Condiment manufacturing, spice blending, and prepared sauce production demand consistent glucosinolate stability and traceable origin documentation. FSSAI-mandated pesticide testing in India has elongated clearance timelines for food-grade imports.
- Animal Feed:Defatted meal byproducts from oil extraction provide protein supplements for ruminant nutrition.
- Biopesticides:Isothiocyanate derivatives function as natural soil fumigants and crop protection agents.
Oil extraction commands the steepest expansion trajectory; food industry maintains the largest absolute tonnage.
Distribution Channel:
Channel selection reflects buyer scale and certification burden, with multinational processors bypassing intermediaries for direct farmgate contracting while smaller regional players depend on wholesale liquidity.
- Direct Sales:Long-term offtake agreements between crushers and grower cooperatives eliminate spot-price exposure. Montana and North Dakota yellow mustard acreage now moves predominantly through three-year processor contracts with prescribed agronomic protocols.
- Wholesale:Aggregators in Rajasthan's Jaipur and Jodhpur mandis consolidate smallholder production for domestic mill consumption.
- Supermarkets:Packaged retail seeds and branded condiments reach household consumers through modern trade.
- Online Retail:Specialty organic and heirloom varieties find price-premium buyers through direct-to-consumer platforms.
Direct sales channels are climbing the fastest; wholesale retains dominant volume share.
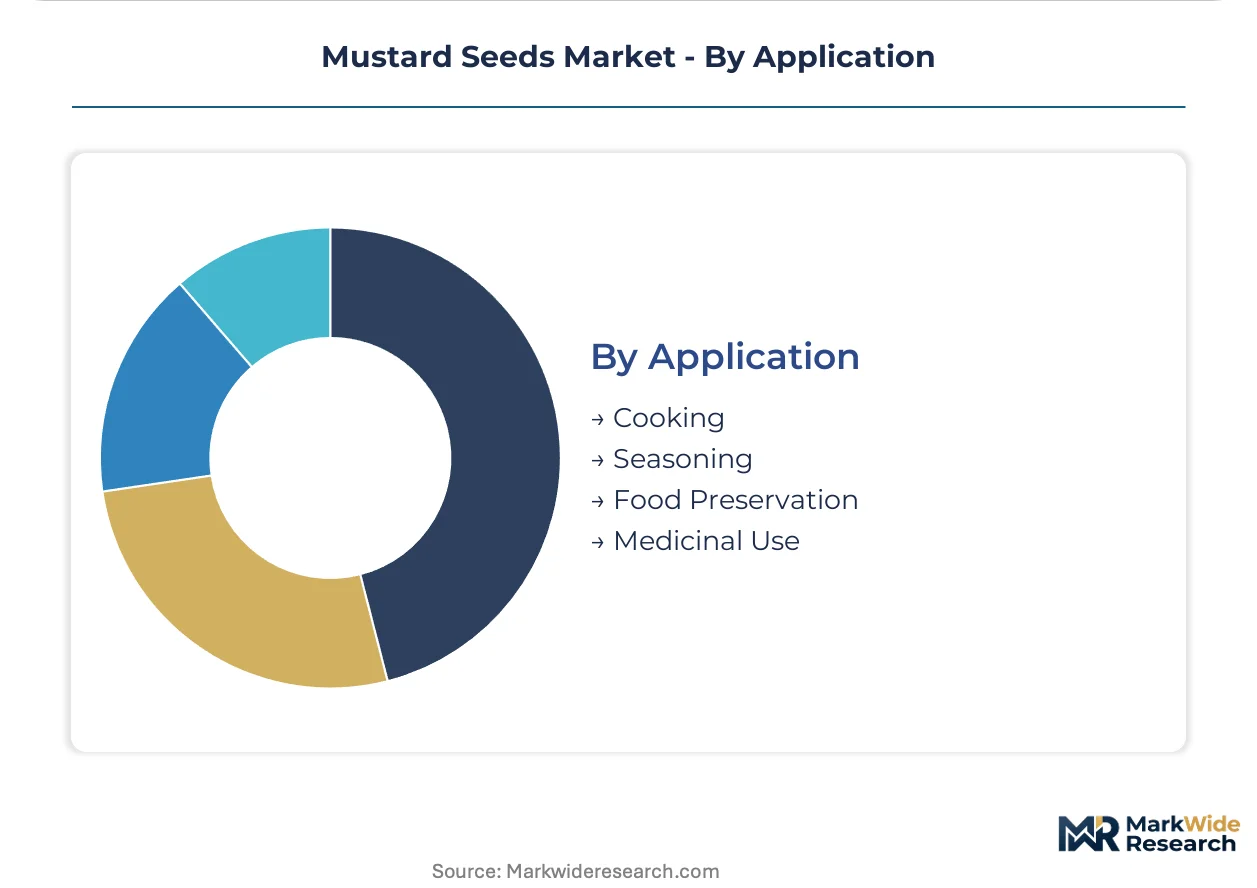
Application:
Functional requirements split procurement between thermal processing applications demanding heat-stable pungency and cold-use scenarios where fresh hydrolysis intensity determines product performance.
- Seasoning:Dry spice blends, prepared mustards, and table condiments require consistent particle size distribution and moisture-controlled storage. McCormick's quality specifications for yellow mustard powder mandate sub-5% moisture and specified mesh fineness.
- Cooking:Whole seed tempering and oil-based frying applications in South Asian cuisine consume substantial brown mustard volumes.
- Food Preservation:Antimicrobial isothiocyanate properties extend shelf life in pickled and fermented products.
- Medicinal Use:Traditional Ayurvedic and Unani preparations utilize processed mustard plasters and oil extracts.
Seasoning applications lead current consumption; cooking applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mustard seed cultivation traces its commercial origins to the Indo-Gangetic plains, where ancient trade routes established the crop as a staple oilseed and condiment source. European colonization later transplanted production to North American prairies, creating today's bifurcated supply geography between South Asian crush clusters and Canadian export origination.
Canada
Saskatchewan's identity-preserved yellow mustard contracts now cover the majority of North American planted acreage, with processors deploying near-infrared spectroscopy at farmgate intake points. The Canadian Grain Commission enforces graded standards for seed cleanliness and oil content that determine export eligibility. Alberta processors are consolidating procurement power through three-year offtake guarantees tied to prescribed agronomic protocols.
India
Gujarat and Rajasthan process over half of global brown mustard volumes within a 200-kilometer radius of Kandla port, creating concentrated crush capacity. FSSAI mandates pesticide residue testing and labeling transparency that add 15-20 days to import clearance timelines. Jaipur and Jodhpur mandis serve as aggregation hubs where smallholder production consolidates for domestic mill consumption.
United States
Montana and North Dakota yellow mustard acreage moves predominantly through direct processor contracts rather than spot-market intermediation. USDA graded standards govern export eligibility from these growing regions. Specialty condiment manufacturers in the Midwest are expanding procurement of organic yellow mustard varieties for clean-label retail positioning.
Germany
Industrial oleochemistry demand is redirecting crush capacity toward high-erucic acid mustard varieties for biodiesel and renewable chemical feedstocks. REACH registration requirements for isothiocyanate derivatives are tightening documentation burdens on importers of processed mustard products. Bavarian specialty chemical manufacturers are segregating crush streams into food-grade and industrial-grade channels with separate chain-of-custody records.
Japan
Traditional wasabi-mustard blending applications sustain premium brown mustard imports for discerning food service channels. METI standards govern chemical inputs in processed derivatives entering Japanese markets. Kansai-based processors maintain long-term grower partnerships across South Asian origination territories to secure consistent seed quality.
Mustard Seeds Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and traceability capabilities, with organic and identity-preserved supply chains commanding contract premiums over undifferentiated bulk origins. The vendor base stratifies into three tiers: multinational agribusiness houses with integrated origination networks, regional specialists dominating single-origin export corridors, and processor-grower cooperatives leveraging geographic concentration. Two dominant competitive moves are reshaping positioning: direct contracting between crushers and grower cooperatives displacing spot-market intermediation, and technology convergence between near-infrared quality assessment and blockchain lot tracking enabling real-time verification.
Within the multinational agribusiness tier, Cargill and Archer Daniels Midland Company exemplify scale-driven origination networks spanning North American prairie production. McCormick & Company occupies a position among branded condiment manufacturers anchoring flavor portfolios on consistent seed quality from long-term grower partnerships. Megha Corporation represents the regional specialist archetype, with its positioning in Indian brown mustard exports to Middle Eastern processors reflecting geographic concentration strategies.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| McCormick & Company |
| Megha Corporation |
| Sakai Spice |
| Kaveri Seeds |
| Sun Impex |
| ITC |
| Organic Products India |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal residue limits gate qualified supply access and premium-tier pricing power, as European food manufacturers redirect procurement toward certified yellow mustard origins that command contract premiums over undifferentiated bulk sources.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies mustard seed markets by certification grade and oil content specifications. FSSAI-compliant traceability documentation and organic certification drive premium-mid-economy pricing differentiation, with identity-preserved yellow mustard contracts from Saskatchewan commanding the highest tier. Cost compression in economy-grade bulk brown mustard is intensifying because Gujarat processing clusters consolidate procurement power. Small regional condiment manufacturers exhibit the greatest price sensitivity, while multinational CPG brands with clean-label mandates accept substantial premiums for consistent quality.
Supply Chain Analysis
Certification and qualification gating now determines downstream market access, with FSSAI-mandated pesticide residue testing and REACH registration requirements filtering informal competitors from European and Indian channels. Geographic supply concentrates in Canada, India, and the United States, with Saskatchewan yellow mustard and Gujarat brown mustard anchoring respective regional crush capacities. Raw material flows draw from Brassica juncea and Brassica hirta seed stocks, fertilizer inputs, and solvent or mechanical pressing equipment. Single-source vulnerability around Kandla port creates structural risk for global brown mustard availability. Distribution runs through direct processor-grower contracts displacing spot-market intermediation in North American origination territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with FSSAI clearance timelines adding working capital costs in India that disappear under USDA graded standards in North American export corridors.
For Market Incumbents: Deploy backward integration into identity-preserved seed multiplication programs to defend against emerging organic specialist entrants. Cargill and McCormick anchor positioning through long-term grower partnerships; incumbents should replicate this lever by offering three-year offtake guarantees with prescribed agronomic protocols. Capacity consolidation in Alberta and Saskatchewan processing plants will absorb margin pressure from input cost volatility. For New Entrants and Emerging Players: Halal-certified packaged condiment buyers in Nigeria and Kenya represent an underserved buyer archetype lacking domestic processing infrastructure. First-mover openings exist for exporters with pre-registered REACH substance dossiers seeking African market penetration. A direct-to-processor digital procurement platform bypassing Jaipur and Jodhpur mandi aggregators offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional brown mustard specialists with captive Kandla corridor access because crush capacity concentration within 200 kilometers of the port creates irreplaceable geographic moats. The optimal acquisition target archetype combines FSSAI-compliant traceability systems with established Middle Eastern oil extraction relationships. Watch for biodiesel blending mandate acceleration as the inflection indicator triggering industrial oleochemistry demand redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | Identity-preserved acreage contracts in Saskatchewan and Alberta secure consistent quality for CPG brand owners. |
| REACH Pre-Registration Investment | Full substance dossiers for isothiocyanate derivatives lock out informal competitors from European processed mustard channels. |
| Halal Certification Program | Religious compliance opens packaged condiment distribution in Nigeria and Kenya lacking domestic infrastructure. |
| Near-Infrared Spectroscopy Deployment | Real-time oil content assessment at Saskatchewan farmgate intake points compresses laboratory turnaround from days to minutes. |
| Three-Year Offtake Guarantee Structure | Prescribed agronomic protocols in Montana and North Dakota displace spot-market intermediation with direct processor contracting. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with mustard seed processors, condiment manufacturer procurement leads, FSSAI compliance officers, and agricultural cooperative managers with secondary validation. Trade data from the Canadian Grain Commission and USDA, FSSAI regulatory filings, EU REACH substance registrations, and customs records anchored bottom-up volume estimates. Top-down triangulation against oil extraction capacity announcements and biodiesel blending policy disclosures verified demand-side assumptions.
Segment-weighting approaches distributed value and volume across product type, end use industry, distribution channel, and application dimensions over the projection horizon. CAGRs were derived from modeled crush capacity expansion against consumption growth in food manufacturing and industrial oleochemistry channels. Forecast inputs incorporated FSSAI traceability compliance adoption curves, EU Green Deal residue limit phase-in schedules, and near-infrared spectroscopy deployment rates at North American farmgate intake points.
Inputs from processor interviews and regulatory filing databases were available through the study window; gaps in smallholder cooperative documentation practices introduce uncertainty bands around Indian origin volume estimates. Forecasts reflect documented assumptions regarding biodiesel mandate enforcement intensity and organic certification adoption rates. A model refresh is warranted upon material change in EU renewable fuel blending targets or FSSAI testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flaxseed (Linseed) Market
Seeds
Europe Cannabis Seeds Market
Seeds
India Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Flax Crop Market
Seeds
North America Quinoa Seeds Market
Seeds
Pigeon Pea Market
Seeds
Custom Selected Seed Market
Seeds
Canary Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
Dragon Fruit Seeds Market
Seeds
Philippines Seed Market
Seeds
Flower Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Watermelon Seeds Market