
 Cover Crop Seed Varieties Market | 2026-2036
Cover Crop Seed Varieties Market Size, Share, and Industry Trends Forecast 2026-2036
Cover Crop Seed Varieties Market Insights
The Conservation Reserve Program is expanding cost-share thresholds for diverse seed mixes, elevating compliance costs for new entrants while rewarding established breeders. Bayer Crop Science leverages its germplasm library to dominate cereal rye and winter wheat portfolios across North American distribution channels. Corteva Agriscience anchors its position through proprietary trait stacks in brassica lines. Syngenta Group competes via integrated seed-treatment formulations that extend germination windows in variable climates.
Cover crop seed varieties comprise botanically diverse species selected for specific agroecological functions including nitrogen fixation, soil carbon sequestration, and allelopathic weed suppression; typical formulations blend 3–7 species with certified germination rates exceeding 85% and purity standards governed by state seed laws. Legume-dominant blends command premium positioning due to biological nitrogen fixation capacity that reduces synthetic fertilizer dependency. Grasses and cereals sustain volume leadership through lower per-acre input costs and broader climate adaptability. Brassica segments attract margin-focused suppliers targeting organic producers and specialty vegetable rotations where biofumigation properties justify price premiums.
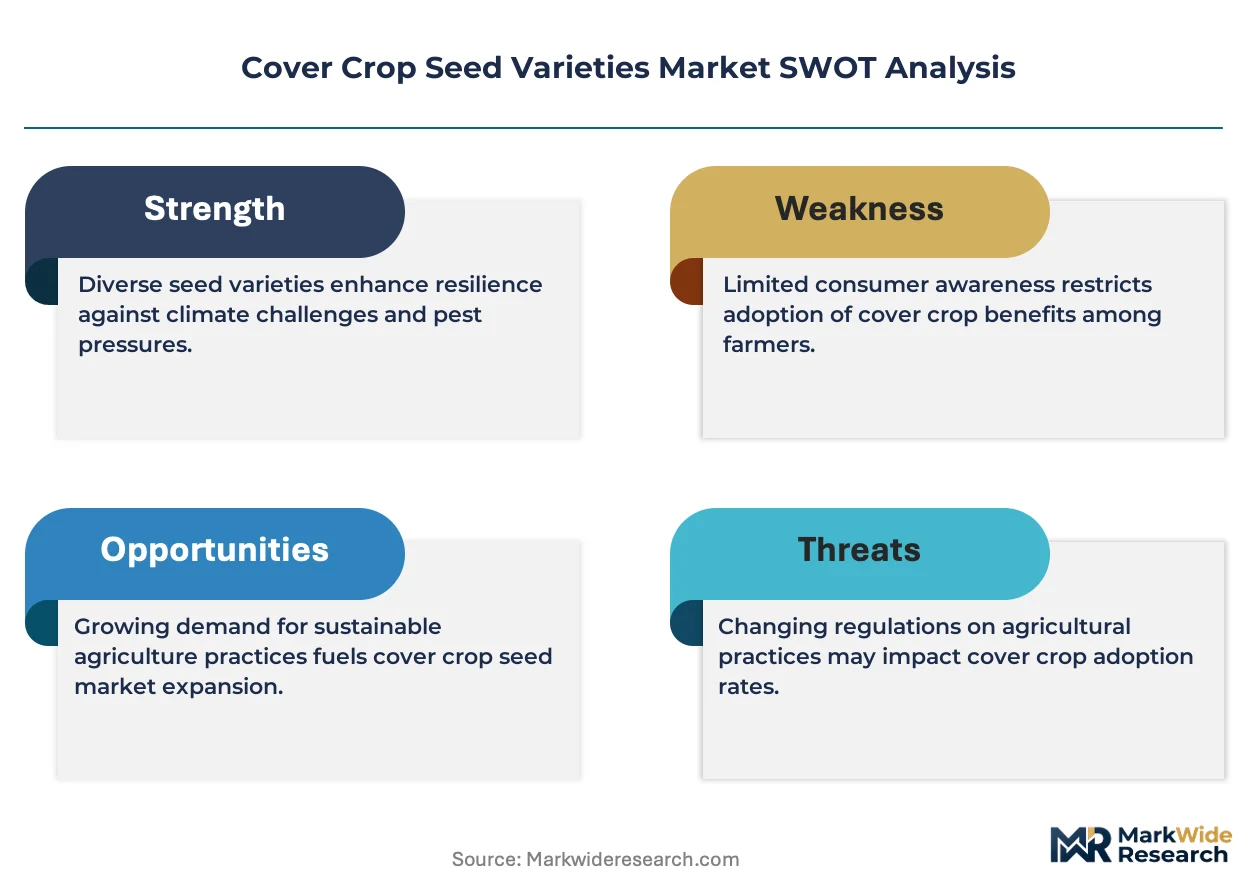
The USDA Natural Resources Conservation Service shapes demand through cost-share allocations, while state seed certification agencies enforce varietal purity and noxious weed thresholds that determine market access. The EU Green Deal and national sustainable farming incentives in France, Germany, and the Netherlands are accelerating import demand for certified organic seed lots. Stakeholders must monitor evolving carbon credit protocols and soil health measurement standards that will determine which seed mixtures qualify for emerging ecosystem service payments.
Market Dynamics
USDA Environmental Quality Incentives Program cost-share thresholds are concentrating procurement power among certified seed suppliers while fragmenting regional distribution networks across state seed law jurisdictions.
Growth Catalysts
- Soil Health Mandates:Midwest Corn Belt nutrient runoff regulations are compelling row crop farmers to adopt multi-species cover crop protocols. State-level phosphorus reduction targets in Iowa, Illinois, and Minnesota are accelerating certified seed demand.
- EU Green Deal Import Demand:National sustainable farming incentives in France, Germany, and the Netherlands are creating import pull for certified organic seed lots meeting varietal purity standards.
- Carbon Sequestration Protocols:Emerging soil health measurement frameworks are qualifying diverse seed mixtures for ecosystem service payments, expanding addressable acreage beyond traditional conservation compliance.
Market Restraints
- Input Cost Volatility:Brassica and legume seed production faces weather-sensitive yield variability, compressing margin buffers for specialty blend suppliers.
- Supply Concentration Risk:Cereal rye germplasm availability clusters in limited North American breeding corridors, creating single-source dependency for volume purchasers.
- Regulatory Friction:State seed certification agencies enforce divergent noxious weed thresholds, fragmenting interstate commerce and elevating compliance overhead for multi-state distributors.
Strategic Opportunities
- Underpenetrated Organic Vegetable Rotations:Specialty brassica lines with biofumigation properties remain underserved in California and Florida fresh produce systems.
- Technology Convergence:Drone-enabled variable-rate seeding is converging with precision soil mapping to enable site-specific multi-species prescriptions.
- Distribution Innovation:Direct-to-farm digital platforms are bypassing traditional elevator and co-op channels, capturing margin from legacy seed dealer networks.
Industry Challenges
- Certification Timeline Compression:State seed law germination and purity testing backlogs are extending time-to-market for new varietal introductions.
- Integration Complexity:Multi-species blend formulation requires cross-functional expertise spanning agronomy, seed pathology, and mechanical conditioning that remains scarce among regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cover Crop Seed Varieties Market |
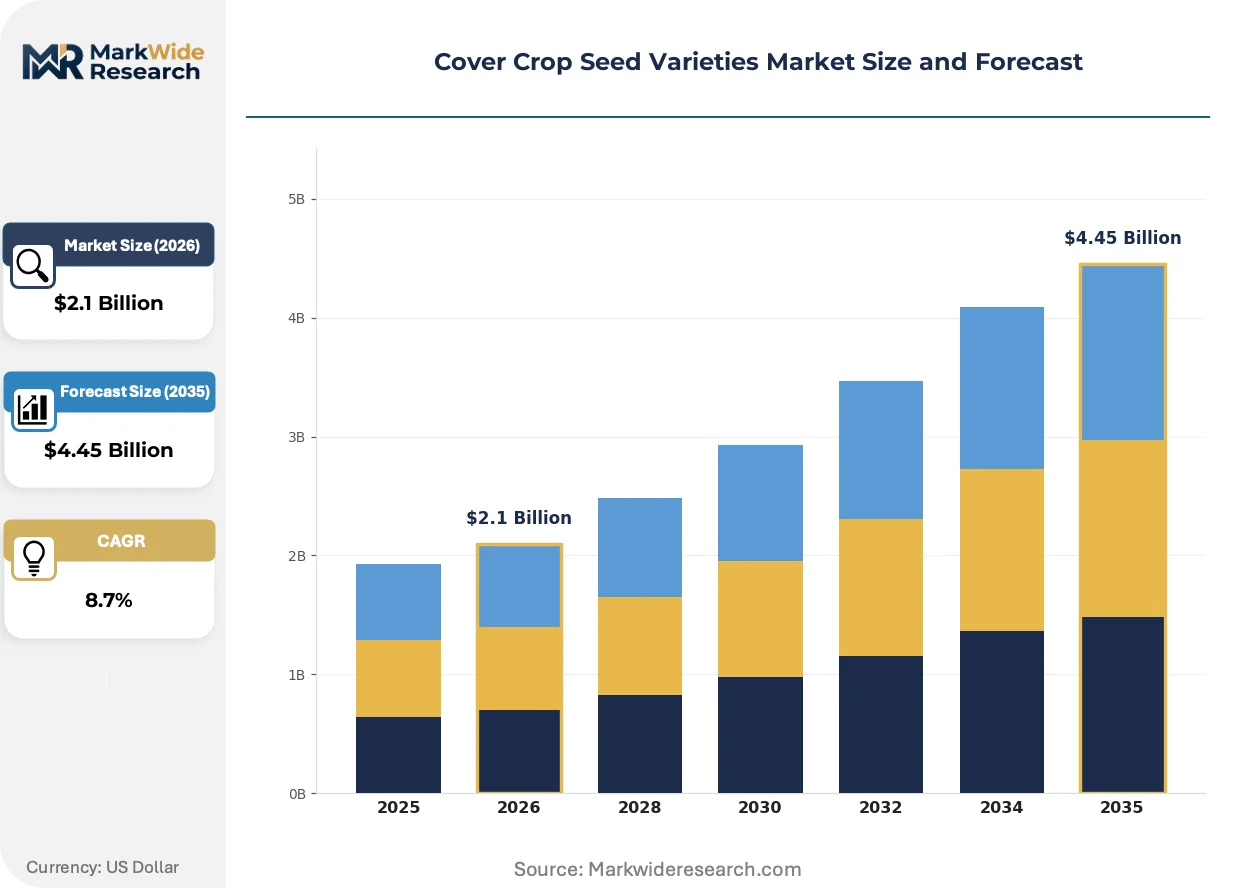
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Legumes, Grasses, Brassicas, Cereals, Broadleaves Application: Soil Erosion Control, Nutrient Management, Weed Suppression, Moisture Retention, Organic Matter Enhancement End User: Row Crop Farmers, Vegetable Growers, Organic Producers, Horticulturists, Turf Managers Packaging Type: Bags, Bulk Sacks, Pelleted Seeds, Coated Seeds, Vacuum Sealed Packs |
| Companies Covered | Bayer Crop Science, Corteva Agriscience, Syngenta Group, KWS Cereals, DLF Seeds A/S, Barenbrug Group, Limagrain, RAGT Semences, Advanta Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cover Crop Seed Varieties Market Trends and Innovations
Precision agriculture tools are compressing the seed-to-soil interface, enabling real-time adaptation of planting protocols to microclimatic conditions and soil biogeochemistry.
Hyperspectral seed quality assessment is automating germination prediction and purity verification. Large-scale certified seed handlers in Nebraska and Kansas are deploying this technology to reduce laboratory testing cycles. The compression of quality assurance timelines is automating inventory turnover and reducing working capital requirements for seasonal suppliers.
EU Green Deal Farm-to-Fork Strategy targets are tightening residue limits and mandating cover crop integration in nitrate-vulnerable zones. French and German national implementation frameworks are requiring documented seed origin and varietal traceability. Organic certification bodies are responding by accelerating third-party audit frequency for imported seed lots.
Buyer concentration among consolidated row crop operations is compressing procurement cycles and unbundling technical advisory services from seed transactions. Large Midwest grain producers are negotiating direct varietal development agreements with breeders, displacing traditional dealer relationships. This pattern is most visible in Iowa and Illinois where thousand-acre-plus operations dominate cover crop adoption metrics.
Cover Crop Seed Varieties Market Segmentation
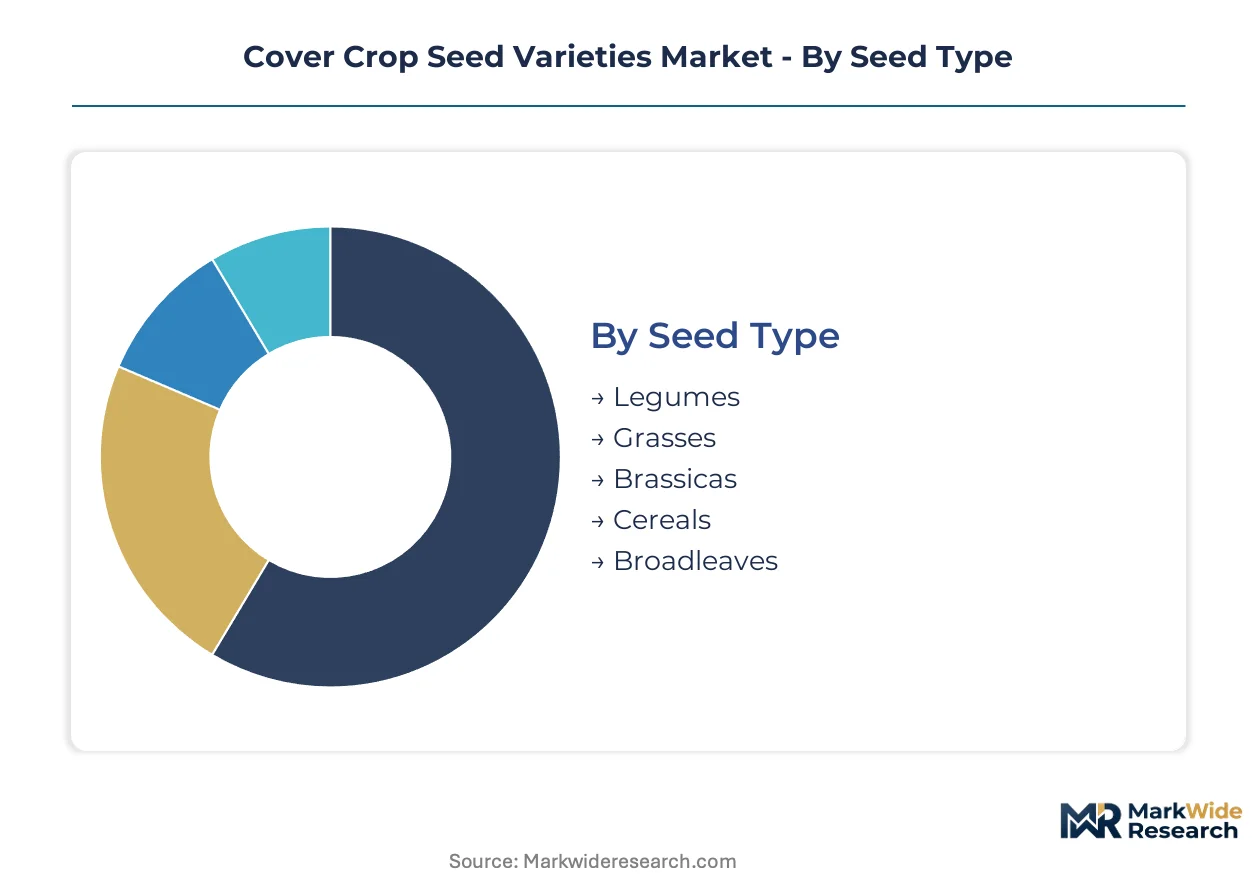
Cover crop seed varieties fragment across botanical function, agronomic purpose, and operational scale. Buyers select formulations based on soil health objectives, equipment compatibility, and certification requirements that vary by farming system.
Seed Type:
Cost tier separates commodity volume purchasers from premium blend buyers seeking specific agroecological outcomes.
- Legumes:Nitrogen-fixing species such as crimson clover and hairy vetch incorporate symbiotic rhizobia bacteria that convert atmospheric nitrogen into plant-available forms. Demand concentrates among Midwest Corn Belt row crop farmers facing state-level phosphorus reduction mandates that incentivize biological fertility inputs.
- Grasses:Fibrous-rooted species including annual ryegrass and sorghum-sudangrass establish rapid ground cover and scavenge residual soil nitrogen. Vegetable growers in California's Central Valley deploy these for pre-plant erosion control in intensive fresh produce rotations.
- Brassicas:Biofumigant species releasing isothiocyanate compounds during decomposition.
- Cereals:Winter-hardy grains such as cereal rye and winter wheat dominating volume procurement through lower per-acre input costs and broad climate adaptability.
- Broadleaves:Diverse non-grass, non-legume species including buckwheat and phacelia supporting pollinator habitat and rapid soil coverage.
Volume sits with Cereals; growth tilts toward Legumes.
Application:
Functional priority determines species selection and blend complexity across farming operations.
- Soil Erosion Control:Rapid-establishment species with dense fibrous root systems stabilize vulnerable fields during fallow periods. Row crop farmers in Iowa's loess hills prioritize these formulations where slope gradients exceed permissible soil loss tolerance limits.
- Nutrient Management:Scavenger and accumulator species capture residual nitrogen and phosphorus before off-site migration. Illinois watershed districts mandate these protocols where tile drainage concentrates nutrient loading into receiving waters.
- Weed Suppression:Allelopathic species and dense-canopy covers outcompete herbicide-resistant weed populations.
- Moisture Retention:Residue-heavy species improving soil water-holding capacity through organic matter accumulation.
- Organic Matter Enhancement:High-biomass species contributing carbon inputs for soil health measurement frameworks.
Adoption clusters on Nutrient Management; regulatory pressure is accelerating Weed Suppression fastest.
End User:
Operational scale and certification status fragment procurement behavior and technical service expectations.
- Row Crop Farmers:Thousand-acre-plus Midwest grain operations negotiating direct varietal development agreements with breeders. These buyers displace traditional dealer relationships through consolidated procurement cycles and unbundled advisory services.
- Vegetable Growers:Intensive fresh produce systems requiring precise rotation timing and biofumigation properties. California and Florida operations drive specialty brassica demand where residue limits restrict synthetic alternatives.
- Organic Producers:Certified operations requiring third-party audited seed origin and varietal traceability.
- Horticulturists:Nursery and ornamental systems seeking aesthetic ground covers with minimal maintenance inputs.
- Turf Managers:Golf course and athletic field operators prioritizing rapid establishment and traffic tolerance.
Procurement volume aggregates with Row Crop Farmers; certification premiums expand fastest among Organic Producers.
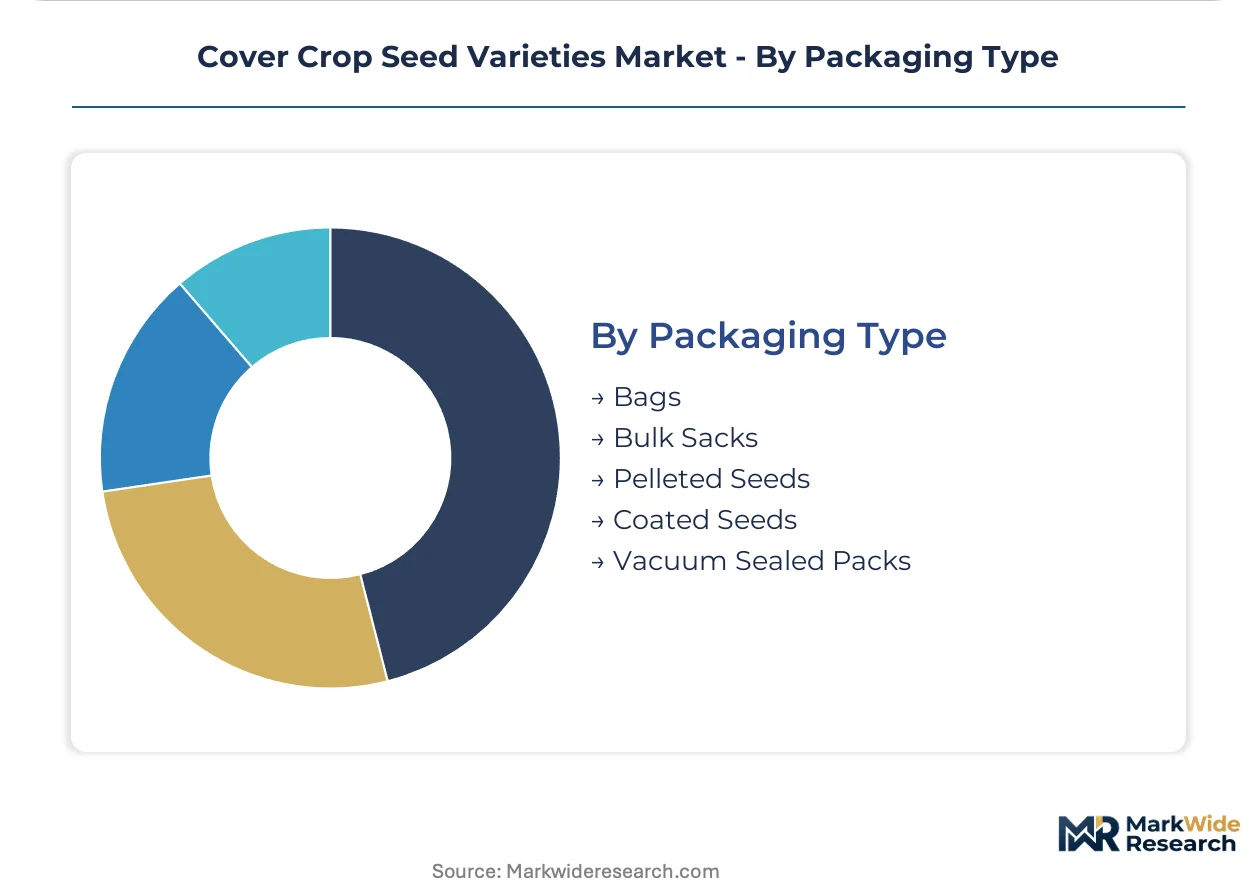
Packaging Type:
Equipment compatibility and storage duration separate mechanical planting systems from precision application methods.
- Bags:Standard 50-pound woven polypropylene units serving conventional drill and broadcast equipment. Regional elevator and co-op channels distribute these through legacy dealer networks across state seed law jurisdictions.
- Bulk Sacks:One-ton flexible intermediate bulk containers reducing per-unit handling costs for large-scale operations. Nebraska and Kansas certified seed handlers deploy these for seasonal inventory turnover compression.
- Pelleted Seeds:Clay-coated units enabling precision metering in vegetable transplanting equipment.
- Coated Seeds:Polymer and nutrient treatments extending germination windows in variable climates.
- Vacuum Sealed Packs:Extended-shelf-life packaging preserving viability for multi-year organic certification compliance documentation.
Shipment volume flows through Bulk Sacks; margin expansion concentrates in Coated Seeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest Corn Belt operations concentrate procurement volume through thousand-acre-plus grain producers negotiating direct varietal agreements. State-level nutrient runoff mandates in Iowa, Illinois, and Minnesota anchor North American demand. The EU Green Deal accelerates import pull from France, Germany, and the Netherlands.
United States
USDA Environmental Quality Incentives Program cost-share allocations drive certified seed procurement across Iowa's loess hills and Illinois watershed districts. The Natural Resources Conservation Service enforces germination and purity standards that determine market access for multi-species blends. Nebraska and Kansas certified seed handlers deploy hyperspectral quality assessment to compress laboratory testing cycles for seasonal inventory turnover.
Germany
National sustainable farming incentives under EU Green Deal implementation create import demand for certified organic seed lots with documented varietal traceability. The Federal Office of Consumer Protection and Food Safety enforces residue limits that mandate cover crop integration in nitrate-vulnerable zones. Bavarian breeding corridors cluster cereal rye germplasm development for volume purchasers across Central European distribution networks.
France
Farm-to-Fork Strategy targets tighten residue limits and accelerate brassica demand for biofumigation properties in intensive fresh produce rotations. ANSM and national agricultural regulators require third-party audit frequency acceleration for imported seed lots. The Île-de-France and Hauts-de-France regions anchor procurement consolidation among consolidated row crop operations unbundling technical advisory services from seed transactions.
Netherlands
National implementation frameworks for EU Green Deal sustainable farming incentives drive certified organic seed lot demand with strict varietal purity standards. The Dutch Food and Consumer Product Safety Authority enforces noxious weed thresholds that fragment interstate commerce for multi-state distributors. Wageningen University clusters drive precision agriculture tool convergence with drone-enabled variable-rate seeding for site-specific multi-species prescriptions.
Canada
Prairie Provinces row crop farmers expand cover crop adoption to meet soil health mandates in Manitoba and Saskatchewan grain belts. Health Canada and PMRA regulate seed treatment formulations that extend germination windows in variable continental climates. Alberta certified seed handlers concentrate bulk sack distribution through direct-to-farm digital platforms bypassing traditional elevator and co-op channels.
Cover Crop Seed Varieties Market Competitive Landscape
North American producers anchor one tier through germplasm libraries and proprietary trait stacks; European specialists hold position via certified organic seed lots and varietal traceability systems. The vendor base stratifies across integrated agrochemical-seed conglomerates, regional breeding cooperatives, and specialty brassica suppliers. Three archetypes dominate: germplasm-integrated multinationals, certification-focused European breeders, and precision-treatment formulators. Competitive moves concentrate on direct varietal development agreements with thousand-acre-plus operations and hyperspectral quality assessment deployment for testing cycle compression.
Within the germplasm-integrated tier, Bayer Crop Science, Corteva Agriscience, and Syngenta Group exemplify multinational positioning through North American distribution channel dominance and integrated seed-treatment capabilities. These entities represent the consolidation vector where proprietary trait stacks and germplasm libraries displace traditional dealer relationships through direct breeder-producer negotiations. Their archetype anchors volume procurement in Midwest Corn Belt nutrient management mandates while European counterparts occupy certification-premium positions in EU Green Deal import markets.
| Leading Market Players |
|---|
| Bayer Crop Science |
| Corteva Agriscience |
| Syngenta Group |
| KWS Cereals |
| DLF Seeds A/S |
| Barenbrug Group |
| Limagrain |
| RAGT Semences |
| Advanta Seeds |
| Others |
Pricing and Supply Chain Analysis
Captive germplasm development by Bayer Crop Science, Corteva Agriscience, and Syngenta Group anchors both supply security and pricing power across North American distribution channels. This upstream control over cereal rye and winter wheat genetics enables volume-tier pricing discipline while state seed law compliance costs fragment regional competitor margins.
Pricing Analysis
Volume procurement concentrates in commodity cereals while margin expansion tilts toward legume-dominant blends and certified organic seed lots. Three-tier pricing structure across premium, standard, and economy levels separates biological nitrogen fixation capacity from basic erosion control formulations. Cost compression in brassica and legume tiers is intensifying because weather-sensitive yield variability compresses margin buffers for specialty blend suppliers. Thousand-acre-plus row crop operations exhibit lowest price sensitivity through direct varietal development agreements, while regional elevator channels serving smaller farms face highest procurement cost pressure.
Supply Chain Analysis
Dual-sourcing requirements from consolidated Midwest grain producers mandate multi-supplier qualification across Nebraska, Kansas, and Iowa breeding corridors. Germplasm availability draws from limited North American cereal rye development clusters and EU Green Deal import channels for certified organic lots. Supply chain risk centers on single-source dependency for volume purchasers where Bavarian and Prairie Provinces germplasm corridors face climate volatility. Distribution runs through direct-to-farm digital platforms displacing traditional elevator and co-op networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-level phosphorus reduction mandates and EU Green Deal residue limits are consolidating procurement power among certified suppliers with compliance infrastructure, forcing margin compression on regional blenders lacking germplasm libraries or organic certification pathways.
For Market Incumbents: To counter hyperspectral quality assessment deployment by Nebraska and Kansas certified seed handlers, Bayer Crop Science and Corteva Agriscience should deepen backward integration into brassica breeding corridors and secure exclusive distribution through direct-to-farm digital platforms bypassing legacy dealer networks. For New Entrants and Emerging Players: EU Green Deal Farm-to-Fork Strategy implementation in France and Germany opens a window for specialty brassica suppliers with biofumigation properties targeting California and Florida fresh produce rotations. White-space concentration sits in organic vegetable systems requiring third-party audited seed origin documentation, with go-to-market traction through precision agriculture tool integration for drone-enabled variable-rate seeding prescriptions. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-treatment formulators with integrated seed-treatment capabilities and proprietary trait stacks. Long-term viability favors germplasm-integrated multinationals with direct varietal development agreements across thousand-acre-plus operations. The signal to monitor is carbon credit protocol finalization determining which seed mixtures qualify for ecosystem service payments.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Quality Assessment Deployment | Nebraska and Kansas handlers compress laboratory testing cycles for seasonal inventory turnover. |
| Direct Varietal Development Agreements | Midwest grain producers displace traditional dealer relationships through consolidated procurement cycles. |
| EU Organic Certification Pathway Investment | ANSM and Dutch Food and Consumer Product Safety Authority requirements accelerate third-party audit frequency. |
| Drone-Enabled Variable-Rate Seeding Integration | Wageningen University clusters converge precision agriculture tools with site-specific multi-species prescriptions. |
| Backward Integration into Brassica Breeding | Specialty biofumigation properties justify price premiums in California Central Valley vegetable rotations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving seed certification agency directors, USDA Natural Resources Conservation Service program officers, certified seed handlers in Nebraska and Kansas, and procurement leads at thousand-acre-plus Midwest grain operations. USDA Environmental Quality Incentives Program cost-share allocations, state seed law germination standards, and EU Green Deal implementation frameworks provided triangulation anchors. Bottom-up acreage adoption modeling and top-down value chain sizing were reconciled across validation passes.
Granularity-level modeling disaggregated volume and value across seed type, application function, end-user operational scale, and packaging format throughout the forecast period. CAGRs were derived from regression-adjusted adoption curves incorporating state-level nutrient runoff mandate enforcement intensity and carbon sequestration protocol development trajectories. Industry-specific inputs included hyperspectral quality assessment deployment rates and direct-to-farm digital platform penetration in Alberta and Prairie Provinces distribution networks.
The model assumes a particular technology adoption path; alternative pathways for drone-enabled variable-rate seeding convergence with precision soil mapping would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal residue limit enforcement timing and state seed law harmonization progress. A model refresh is warranted upon material change in carbon credit protocol finalization or USDA cost-share threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
India Vegetable Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Sri Lanka Seed Market
Seeds
Garden Seeds Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Custom Selected Seed Market
Seeds
Global Vegetable Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Dodder Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Mexico Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Okra Seed Market
Seeds
Organic Seed Market
Seeds
E. Angustifolium Market